
 Mixed Signal System-On-Chip (Mxsoc) Market | 2026-2036
Mixed Signal System-On-Chip (Mxsoc) Market Size, Share, and Industry Trends Forecast 2026-2036
Mixed Signal System-On-Chip (Mxsoc) Market Foresight
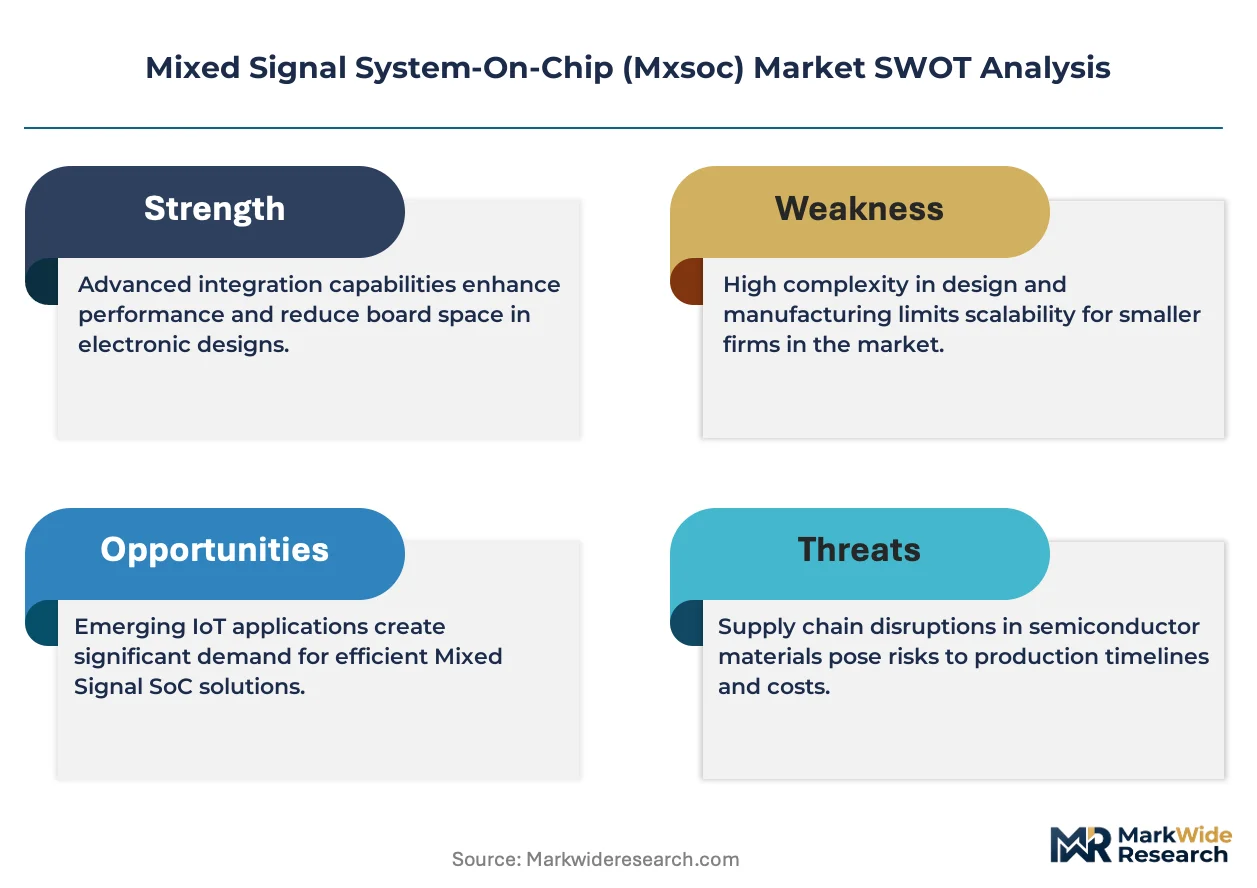
Gallium nitride is restructuring power-stage economics in mixed-signal SoCs by displacing silicon in high-frequency switching applications. Texas Instruments leverages captive GaN-on-Si fabrication to sustain cost advantages in industrial power conversion. Analog Devices anchors precision signal-chain portfolios through proprietary converter architectures. NXP Semiconductors dominates automotive-qualified MXSoC supply with AEC-Q100-certified BiCMOS platforms.
A mixed-signal system-on-chip integrates analog front-ends, digital processing cores, and RF transceivers onto a single die, typically manufactured on 40nm to 180nm CMOS or BiCMOS nodes with operating voltages spanning 1.8V to 5V for sensor interfacing and real-time control. Its primary purpose is eliminating discrete component counts while maintaining signal integrity across heterogeneous domains in space-constrained electronics. Consumer electronics applications lead volume shipment but generate thinner margins, whereas automotive systems command premium pricing due to functional-safety certification requirements and extended temperature-grade specifications. Medical devices represent the fastest-growing application segment, driven by portable diagnostic equipment and implantable monitoring systems requiring ultra-low-power mixed-signal integration.
FDA device-classification rules in the United States mandate design-control documentation for MXSoCs deployed in Class II and Class III medical equipment, elevating barrier-to-entry for non-specialist suppliers. EMA's Medical Device Regulation in Europe extends this compliance burden through post-market surveillance and unique device identification requirements. China's NMPA has aligned its technical review standards with international harmonization initiatives, streamlining approval pathways for imported mixed-signal components. Stakeholders must weigh regional certification timelines against foundry allocation priorities when committing to process-node roadmaps.
Market Dynamics
Automotive electrification is compressing design cycles for mixed-signal SoCs as battery management systems and sensor fusion architectures demand tighter analog-digital integration at automotive-grade reliability thresholds.
Growth Catalysts
- REACH and RoHS compliance in Europe:Environmental mandates are eliminating lead-based packaging substrates and accelerating migration to copper-pillar and gold-wire bonding alternatives across industrial and automotive supply chains.
- Domestic foundry expansion in China:State-backed capacity builds for 40nm to 90nm BCD and BiCMOS processes are reducing import dependency for mature-node mixed-signal manufacturing.
- Implantable medical monitoring:Ultra-low-power integration requirements for continuous glucose monitors and cardiac event recorders are pulling advanced mixed-signal architectures into Class II and Class III device pipelines.
Market Restraints
- 300mm silicon wafer spot price volatility:Input cost swings for starting material compress gross margins on high-volume consumer-grade MXSoCs where pricing is already compressed.
- Advanced packaging substrate concentration:ABF substrate and high-density organic laminate supply concentrates among Taiwanese and Japanese suppliers, creating allocation bottlenecks during demand surges.
- Silicon carbide displacement threat:SiC power devices are capturing traction in high-voltage industrial motor drives above 600V, narrowing the addressable window for GaN-integrated mixed-signal power stages.
Strategic Opportunities
- India's electronics manufacturing incentives:PLI scheme disbursements for semiconductor assembly and testing are attracting MXSoC packaging investments to Gujarat and Tamil Nadu clusters.
- AI inference at the sensor edge:Convergence of analog feature extraction with tinyML digital accelerators is opening new design slots in predictive maintenance and acoustic monitoring applications.
- Japan's METI semiconductor revitalization framework:Subsidies for legacy node capacity preservation are creating partnership opportunities for automotive-qualified mixed-signal process development.
Industry Challenges
- AEC-Q100 functional safety certification timelines:Automotive-grade qualification cycles spanning 18-24 months delay revenue recognition and strain working capital for fabless designers.
- Mixed-signal design automation talent scarcity:Experienced architects capable of optimizing signal-to-noise ratios across analog-digital boundaries command premium compensation and constrain team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mixed Signal System-On-Chip (Mxsoc) Market |
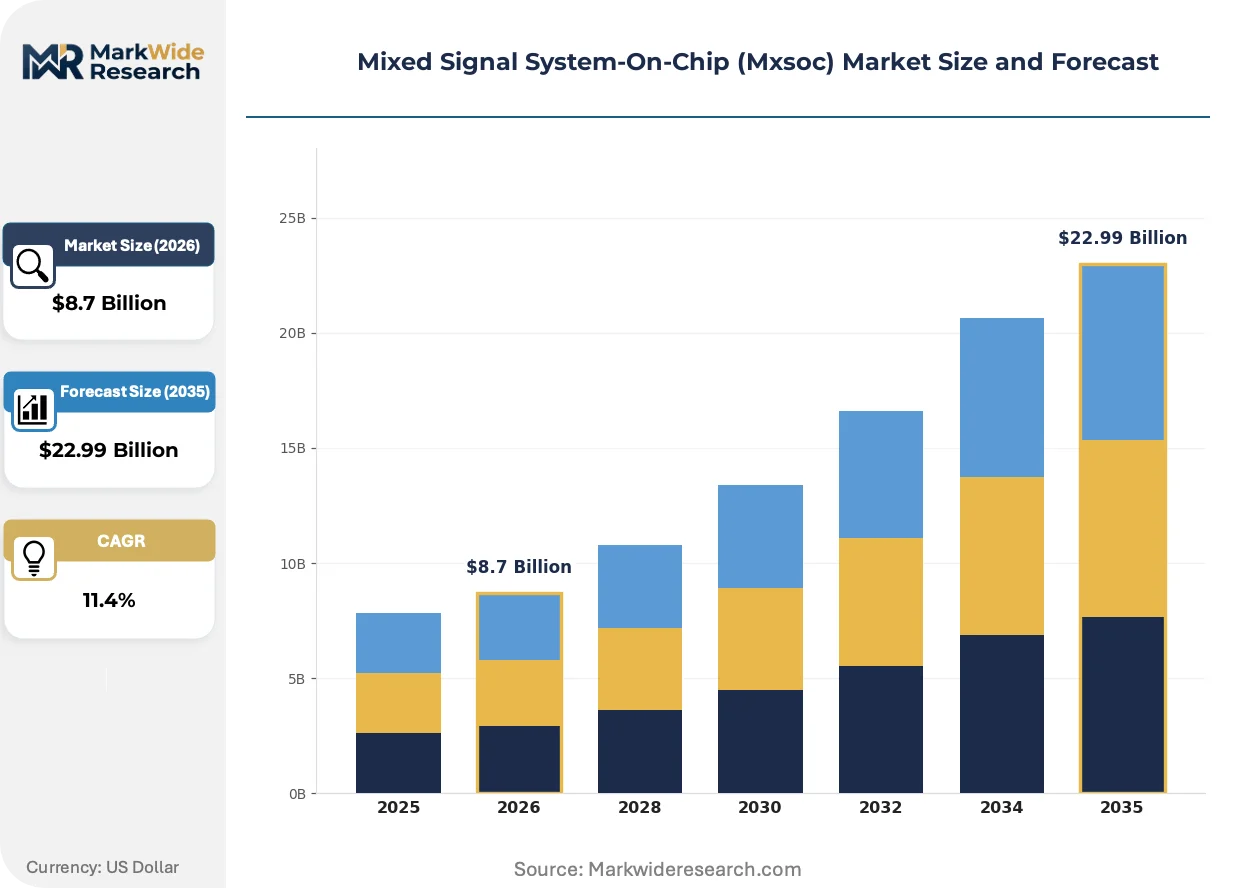
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog IC, Digital IC, Mixed-Signal IC, RF IC Technology: CMOS, BiCMOS, GaAs, SOI Application: Consumer Electronics, Automotive Systems, Medical Devices, Industrial Automation End User: OEMs, Tier-1 Suppliers, Component Manufacturers, System Integrators |
| Companies Covered | Texas Instruments Inc., Analog Devices Inc., NXP Semiconductors, STMicroelectronics, Infineon Technologies AG, Qualcomm Incorporated, Intel Corporation, MediaTek Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mixed Signal System-On-Chip (Mxsoc) Market Shifts & Advancements
Gallium nitride is restructuring power-stage economics by enabling higher switching frequencies at reduced thermal budgets, forcing incumbent silicon-based architectures into defensive repositioning across industrial and automotive segments.
GaN-on-silicon power integration is integrating high-electron-mobility transistors with gate drivers and protection logic onto monolithic dies. Industrial power supply manufacturers are adopting these platforms for 48V to 400V conversion stages. This integration is compressing magnetics size and system bill-of-materials counts in server power and solar inverter applications.
EMA's Medical Device Regulation in Europe is extending post-market surveillance obligations to component suppliers. Unique device identification requirements now flow downstream to MXSoC manufacturers serving diagnostic equipment OEMs. Class II implantable device producers are responding by locking in multi-year supply agreements with qualified mixed-signal foundries.
Buyer consolidation among tier-one automotive OEMs is compressing supplier negotiation cycles and demanding system-level warranties rather than component-level specifications. Direct contracting between vehicle manufacturers and semiconductor suppliers is displacing traditional tier-two module vendor relationships. This pattern is most visible in Germany and South Korea where battery electric vehicle platforms are scaling fastest.
Mixed Signal System-On-Chip (Mxsoc) Market Segmentation
Mixed-signal SoC segmentation reveals how integration complexity, process-node economics, and end-use certification requirements fragment procurement patterns across buyer categories. Each dimension carries distinct margin structures and qualification timelines that reshape supplier prioritization.
Product Type:
Buyers differentiate by the degree of analog-digital integration required and the corresponding die-size cost tradeoffs.
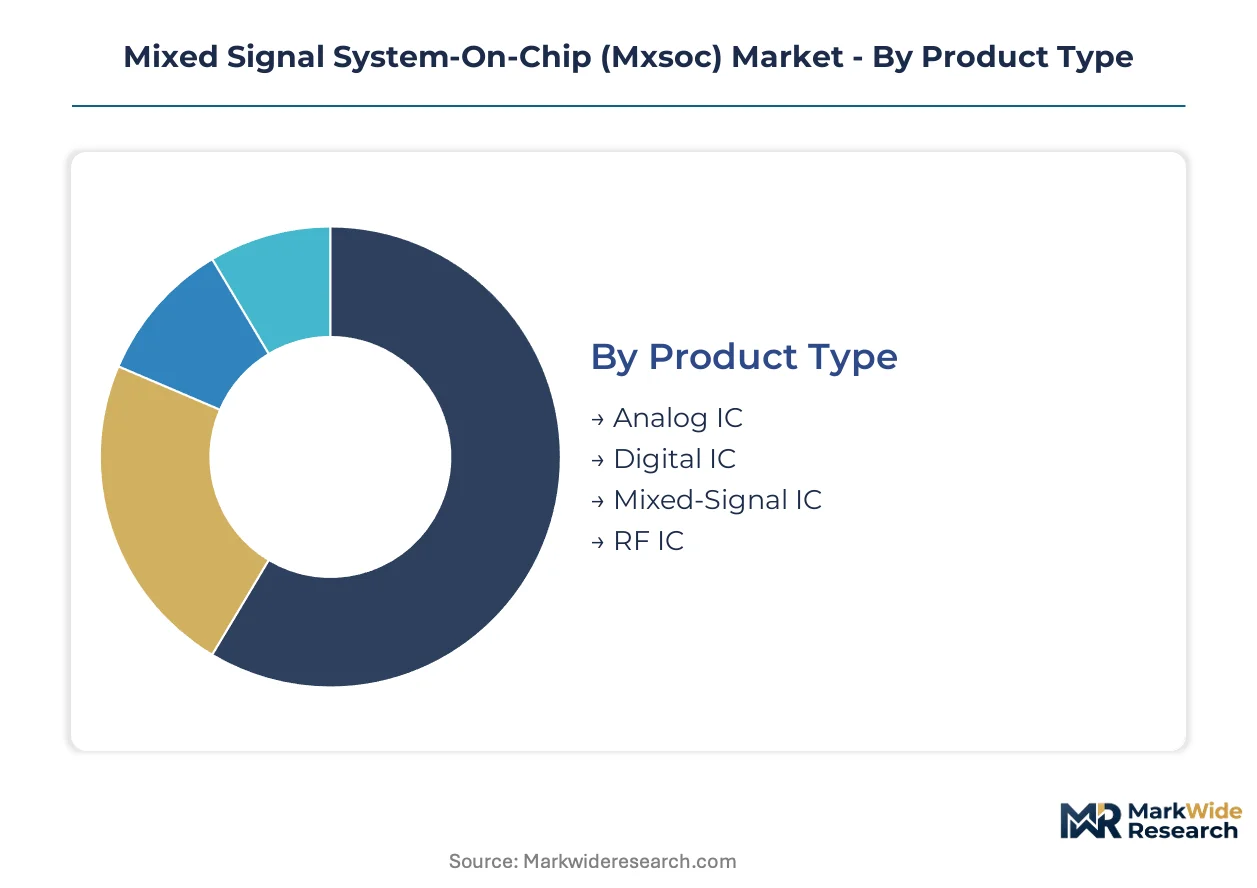
- Mixed-Signal IC:Combines analog front-ends, data converters, and digital processing cores on monolithic dies, typically fabricated on 40nm to 180nm nodes. Automotive battery management systems and sensor fusion architectures in Germany and South Korea are pulling the most advanced integration levels as OEMs eliminate discrete component counts.
- Analog IC:Specialized signal conditioning and power management functions without embedded digital logic. Industrial motor drive manufacturers in Japan favor discrete analog integration for noise isolation in high-voltage environments above 600V.
- Digital IC:Pure logic implementations for algorithmic processing, often paired with companion analog dies in multi-chip modules. Consumer wearable OEMs in Shenzhen prioritize digital ICs for AI inference at the sensor edge.
- RF IC:Transceiver and frequency synthesis functions for wireless connectivity. 5G small-cell deployments in India are accelerating RF IC procurement for sub-6GHz infrastructure.
Mixed-Signal IC leads volumes today; RF IC is gaining share fastest.
Technology:
Process selection hinges on voltage-handling requirements, frequency performance, and the availability of automotive-qualified foundry capacity.
- BiCMOS:Merged bipolar-CMOS architectures deliver high transconductance for precision analog alongside dense digital logic. NXP Semiconductors and automotive tier-1 suppliers in Germany rely on BiCMOS for AEC-Q100-certified battery monitoring and radar signal chains.
- CMOS:Dominant baseline process for cost-sensitive consumer applications, with mature nodes from 40nm to 90nm serving high-volume medical and industrial segments. China's domestic foundry expansion is concentrating CMOS capacity for BCD and power-management derivatives.
- GaAs:Gallium arsenide substrates enable millimeter-wave and high-frequency RF performance. Defense and satellite communication programs in the US sustain limited GaAs demand despite higher substrate costs.
- SOI:Silicon-on-insulator structures reduce parasitic capacitance for RF switching and low-power logic. IoT sensor node designers in Japan leverage SOI for sub-threshold operation in energy-harvesting applications.
CMOS leads volumes today; BiCMOS is expanding most quickly.
Application:
End-use certification requirements and temperature-grade specifications create tiered pricing bands that separate premium automotive and medical demand from consumer volume plays.
- Automotive Systems:Battery management, sensor fusion, and powertrain control functions requiring AEC-Q100 qualification and -40°C to 150°C operation. OEMs in South Korea and Germany are compressing supplier negotiation cycles through direct semiconductor contracting.
- Medical Devices:Portable diagnostic equipment and implantable monitors demanding ultra-low-power integration with FDA Class II/III or EMA MDR compliance. Continuous glucose monitor manufacturers are locking multi-year supply agreements with qualified foundries.
- Consumer Electronics:High-volume, thinner-margin applications including smartphones, wearables, and smart home devices. Design cycles here compress to 12-18 months versus 24-36 months for automotive.
- Industrial Automation:Predictive maintenance, motor drives, and process control systems requiring extended temperature grades and galvanic isolation. GaN-integrated power stages are restructuring magnetics size and bill-of-materials counts in server power and solar inverters.
Consumer Electronics leads volumes today; Medical Devices is climbing the fastest.
End User:
Procurement authority is shifting upstream as automotive OEMs displace traditional tier-two module vendors through direct semiconductor sourcing.
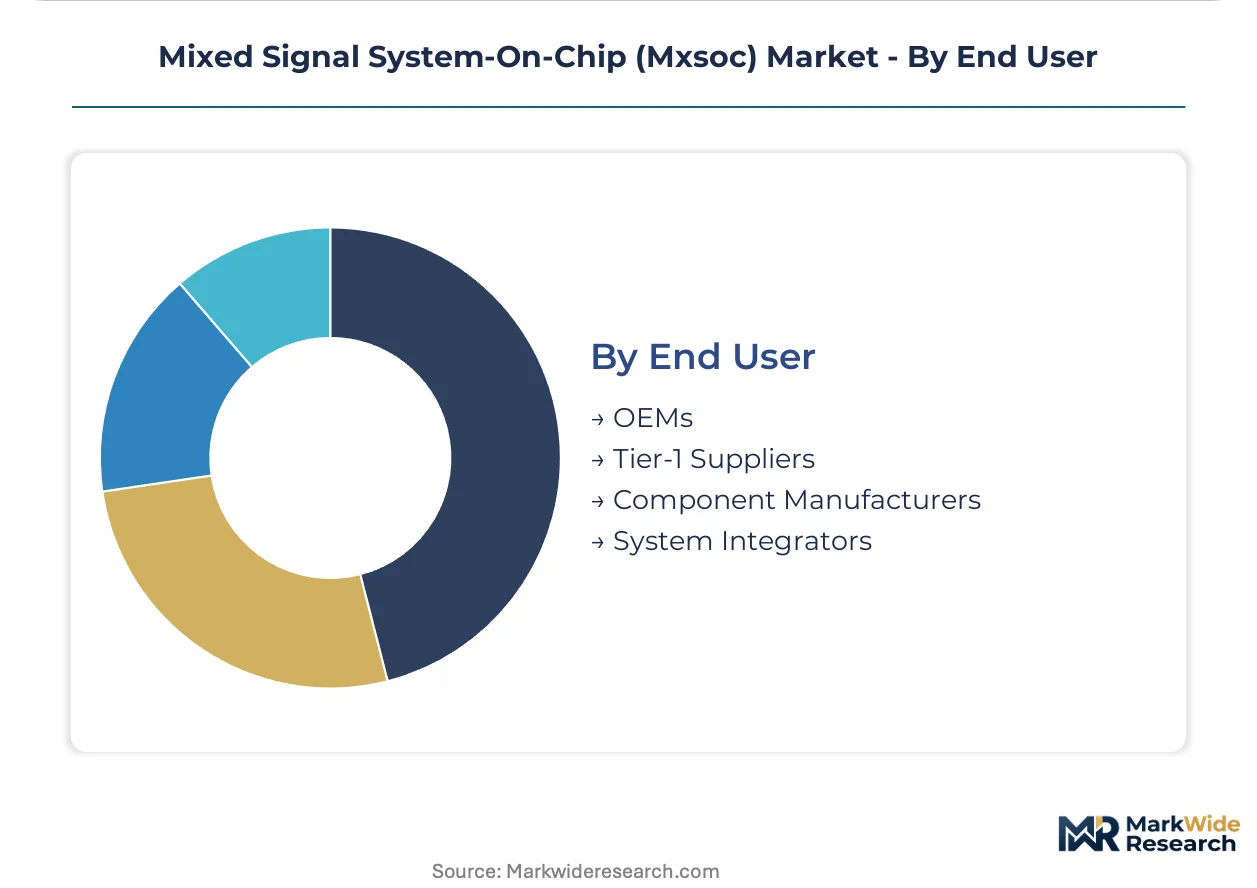
- OEMs:Original equipment manufacturers with in-house electronics design teams and direct foundry relationships. Battery electric vehicle platforms in Germany and South Korea exhibit the most aggressive vertical integration into mixed-signal component selection.
- Tier-1 Suppliers:Module and subsystem vendors serving as traditional intermediaries between semiconductor suppliers and vehicle manufacturers. Their negotiation leverage is compressing as OEMs consolidate supplier bases.
- Component Manufacturers:Discrete semiconductor and passive component suppliers integrating MXSoCs into larger bill-of-materials offerings. India's PLI scheme disbursements are attracting packaging investments from this tier.
- System Integrators:Engineering service providers and contract manufacturers assembling complete electronic systems. Medical device startups in the US increasingly rely on system integrators for FDA design-control documentation support.
Tier-1 Suppliers lead volumes today; OEMs is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the most concentrated electronics manufacturing ecosystem for mixed-signal SoC packaging and system integration. Foundry investments in mature-node BCD processes are accelerating across three continents. Regulatory divergence on medical device certification is fragmenting procurement timelines.
United States
FDA device-classification rules for Class II and Class III medical equipment mandate design-control documentation that elevates supplier qualification barriers. The IRA's domestic manufacturing incentives are pulling packaging investments toward Arizona and Texas. Boston's medical device cluster is locking multi-year supply agreements with qualified mixed-signal foundries for implantable monitoring systems.
Germany
Direct contracting between automotive OEMs and semiconductor suppliers is displacing traditional tier-two module relationships in battery electric vehicle platforms. KBA vehicle-type approval requirements cascade into component-level traceability obligations for functional-safety systems. Stuttgart's automotive electronics corridor is compressing supplier negotiation cycles through consolidated procurement authority.
China
NMPA alignment with international harmonization initiatives is streamlining approval pathways for imported mixed-signal components serving portable diagnostic equipment. State-backed capacity builds for 40nm to 90nm BCD processes are reducing import dependency for mature-node manufacturing. Yangtze River Delta foundry clusters are expanding domestic capacity for automotive-qualified BiCMOS platforms.
Japan
METI's semiconductor revitalization framework is subsidizing legacy node capacity preservation for automotive-qualified mixed-signal process development. JIS standards for industrial automation components impose extended temperature-grade specifications that filter supplier eligibility. Nagoya's automotive electronics belt is deepening backward integration into mixed-signal component selection for sensor fusion architectures.
South Korea
MFDS medical device regulations are converging with international standards for continuous glucose monitor and cardiac event recorder components. Battery electric vehicle platform scaling is driving direct OEM-semiconductor contracting for battery management systems. Seoul Capital Area electronics clusters are prioritizing AEC-Q100-certified foundry partnerships for powertrain control functions.
Mixed Signal System-On-Chip (Mxsoc) Market Competitive Landscape
Global majors compete with regional champions across automotive qualification and medical certification vectors. The vendor base stratifies into three tiers: captive foundry operators with process control, fabless specialists with architectural IP, and diversified conglomerates with system-level integration. Consolidation pressure concentrates among automotive-qualified suppliers where AEC-Q100 timelines stretch working capital. Dominant competitive moves include backward integration into GaN-on-silicon fabrication and strategic partnerships for AI-at-the-edge accelerator integration.
Among diversified semiconductor conglomerates, Texas Instruments, Analog Devices, and NXP Semiconductors occupy positions that exemplify three distinct archetypes. Texas Instruments represents captive foundry operators leveraging in-house GaN-on-silicon fabrication for cost advantages in industrial power conversion. Analog Devices sits within the precision signal-chain specialist tier, anchoring proprietary converter architectures for measurement-intensive applications. NXP Semiconductors exemplifies automotive-qualified platform dominance through AEC-Q100-certified BiCMOS supply relationships with tier-one OEMs in Germany and South Korea.
| Leading Market Players |
|---|
| Texas Instruments Inc. |
| Analog Devices Inc. |
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies AG |
| Qualcomm Incorporated |
| Intel Corporation |
| MediaTek Inc. |
| Renesas Electronics Corporation |
| Others |
Supply & Pricing Matrix
Automotive OEM direct contracting in Germany and South Korea is eliminating tier-two module vendor intermediaries, forcing foundries to absorb AEC-Q100 qualification costs while defending margins against consumer-grade price benchmarks.
Pricing Analysis
300mm silicon wafer spot price volatility passes through unevenly across product tiers. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates premium AEC-Q100-qualified supply from standard commercial temperature-range parts. Cost compression in high-volume consumer MXSoCs intensifies because foundry allocation prioritizes automotive backlog commitments. Tier-one automotive OEMs exhibit lowest price sensitivity; Shenzhen wearable OEMs face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese ABF substrate suppliers and Japanese high-density organic laminate manufacturers. Manufacturing concentrates in Taiwan, South Korea, and China for wafer fabrication, with back-end packaging anchored in Malaysia and Vietnam. Raw material dependencies include 300mm silicon wafers, gallium nitride epitaxial wafers, and gold-wire bonding materials. Tariff exposure on advanced packaging substrates creates allocation risk during demand surges. Distribution runs through authorized distributors serving tier-one automotive module vendors and direct foundry relationships for medical device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Battery electric vehicle platform scaling pulls procurement authority upstream toward OEMs demanding extended temperature grades and functional-safety certification.
For Market Incumbents: To counter silicon carbide displacement in industrial motor drives above 600V, deepen captive GaN-on-silicon fabrication capacity and lock multi-year substrate supply agreements. Accelerate AEC-Q100 certification pipeline investments to match 18-24 month automotive qualification timelines.
For New Entrants and Emerging Players: Launch via system integrator partnerships serving FDA Class II medical device startups requiring design-control documentation support. Target India's PLI scheme disbursements for semiconductor assembly and testing in Gujarat and Tamil Nadu clusters. White-space sits with AI inference at the sensor edge for predictive maintenance applications.
For Investors and Strategic Acquirers: Asymmetric upside sits with fabless specialists holding proprietary converter architectures or automotive-qualified BiCMOS platform IP. Five-to-ten year viability hinges on foundry access for mature-node mixed-signal processes. Watch NMPA approval pathway streamlining for imported components as inflection indicator for China market access.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Silicon Fab Capacity Expansion | Captive fabrication secures cost position against silicon carbide in 48V-400V power stages. |
| AEC-Q100 Certification Acceleration | Automotive qualification timelines stretch working capital; early pipeline commitment locks OEM allocation. |
| Medical Device Foundry Partnership | FDA Class II/III design-control documentation requirements elevate barriers for non-specialist suppliers. |
| India PLI Packaging Investment | Assembly and testing incentives in Gujarat and Tamil Nadu diversify geographic footprint. |
| AI-at-the-Edge Accelerator Integration | TinyML convergence with analog feature extraction opens predictive maintenance design slots. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured mixed-signal design architects, automotive tier-one procurement leads, medical device regulatory affairs specialists, and foundry capacity planning directors. Secondary validation drew from SEC semiconductor filings, FDA 510(k) device classifications, EMA MDR post-market surveillance databases, and NMPA technical review standards. Bottom-up die-size cost modeling and top-down foundry revenue allocation triangulated market sizing across product type, technology node, and end-use application.
Historical reference periods anchored the projection framework against capacity build cycles and automotive platform launch cadences. Segmentation modeling spanned product integration level, process technology, certification grade, and regional regulatory cluster. CAGR derivation weighted foundry utilization rates, AEC-Q100 qualification pipeline velocity, and medical device approval timelines. Industry-specific inputs included 300mm wafer spot price indices and GaN epitaxial wafer supply availability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt foundry allocation shifts or medical device regulatory harmonization reversals. Forecasts reflect documented assumptions on mature-node capacity expansion and automotive electrification penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Industrial Internet Chip Market