
 Chip Antenna Market | 2026-2036
Chip Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Chip Antenna Market Analysis
Automotive OEMs is bifurcating demand away from traditional consumer electronics buyers as vehicle connectivity requirements multiply. Murata Manufacturing Co., Ltd. anchors ceramic antenna supply through vertical integration into dielectric material production. Vishay Intertechnology, Inc. leverages broad passive component portfolios to cross-sell chip antenna solutions into industrial accounts. Johanson Technology, Inc. specializes in high-frequency miniaturization for defense and aerospace qualification paths.
A chip antenna is a compact surface-mount radiating element typically fabricated on ceramic or organic substrates, operating from sub-GHz to millimeter-wave frequencies with dimensions under 10 mm for IoT integration. Ceramic antennas dominate current volume owing to temperature stability and Q-factor performance in compact modules. PCB antennas capture margin pools in cost-optimized smart home and wearable technology applications where substrate integration eliminates discrete component handling. NFC technology trails Wi-Fi and Bluetooth in unit volume but commands premium positioning in secure payment and access control endpoints.
FCC Part 15 in the United States and CE marking under the EU Radio Equipment Directive constrain spurious emissions and spectrum efficiency, forcing redesign cycles that favor qualified suppliers. Japan's METI technical standards and China's MIIT radio type approval add further compliance layers for multi-region product launches. Stakeholders must monitor evolving spectrum reallocations and material restriction timelines to preserve market access across jurisdictions.
Market Dynamics
Automotive OEM procurement power is restructuring supplier relationships as connected vehicle mandates multiply design-in requirements and compress qualification timelines for ceramic antenna vendors.
Growth Catalysts
- Connected vehicle mandates:NHTSA telematics requirements and EU eCall regulations are mandating cellular connectivity in new vehicle platforms, expanding antenna count per vehicle from two to eight units.
- REACH material compliance:European ECHA restrictions on hazardous substances are accelerating substitution toward ceramic substrates that eliminate lead-based formulations in consumer electronics modules.
- Millimeter-wave spectrum allocation:FCC Part 15 rulemaking in the 60 GHz band is unlocking radar and high-speed data applications that demand compact antenna arrays for industrial sensing.
Market Restraints
- Raw material concentration:High-purity barium titanate and rare-earth dopants for ceramic antennas concentrate in Chinese mining and refining operations, exposing supply chains to export control volatility.
- Sub-6 GHz performance ceiling:Dielectric losses in compact ceramic packages degrade radiation efficiency below negative three decibels at frequencies under one gigahertz, limiting IoT range.
- MIIT type approval timelines:China's radio equipment certification process extends sixteen to twenty-four months for new antenna SKUs, delaying product launches for multi-region device makers.
Strategic Opportunities
- India PLI scheme leverage:The country's production-linked incentive program for telecom equipment is attracting module assembly investment that creates localized antenna sourcing demand for export manufacturing.
- Wi-Fi 7 beamforming convergence:Multi-input multi-output antenna arrays integrated with baseband processors are opening socket opportunities in enterprise access points and premium consumer routers.
- UWB regulatory tailwind:FCC Part 15 rule relaxations on ultra-wideband power limits are enabling precision ranging applications in automotive keyless entry and industrial asset tracking.
Industry Challenges
- Electromagnetic simulation talent scarcity:Finite element modeling expertise for antenna optimization commands premium compensation, constraining design throughput at mid-tier module houses.
- Automotive AEC-Q200 qualification:Temperature cycling and mechanical shock testing for ceramic antennas extends eighteen months, locking working capital in inventory before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chip Antenna Market |
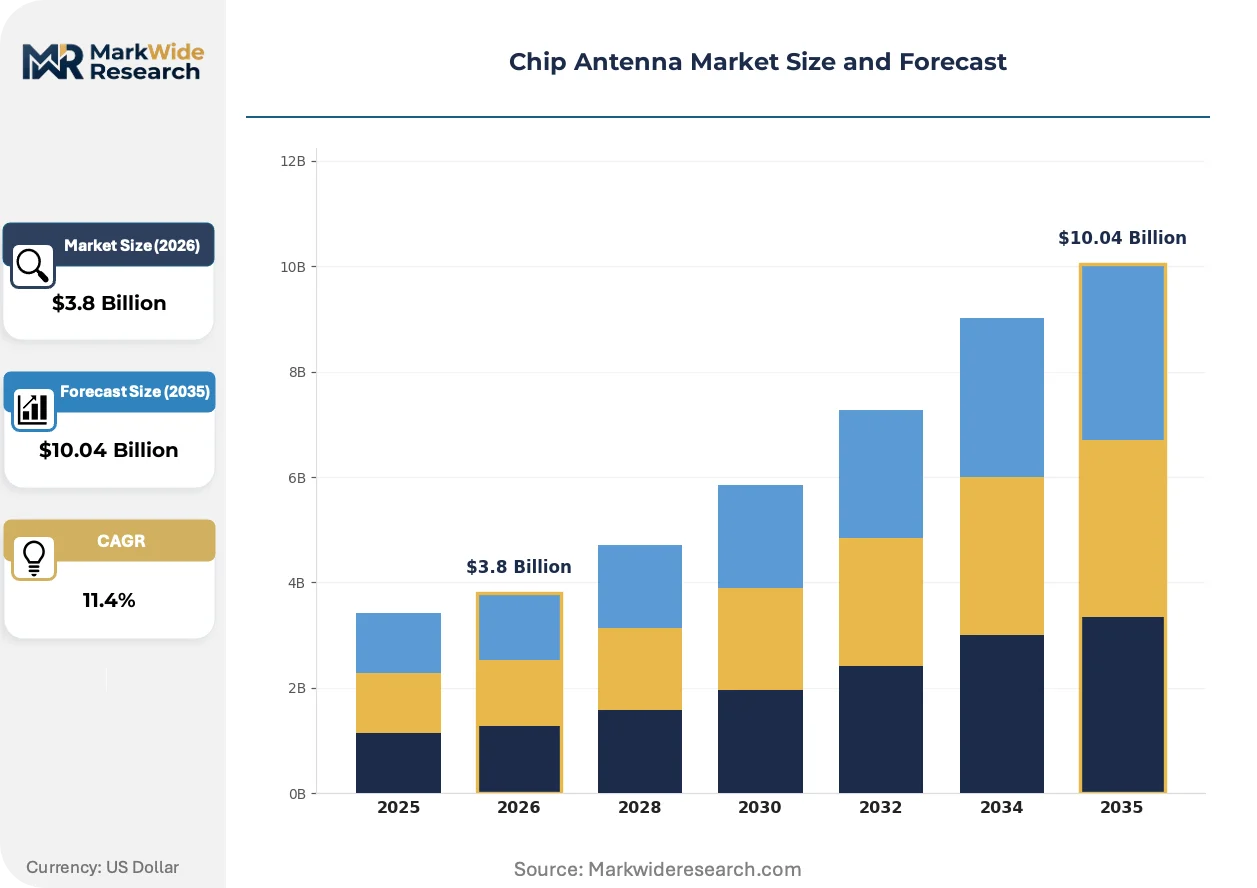
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printed Antennas, Ceramic Antennas, PCB Antennas, Patch Antennas End User: Telecommunications, Consumer Electronics, Automotive, Healthcare Technology: Wi-Fi, Bluetooth, Zigbee, NFC Application: IoT Devices, Wireless Communication, Smart Home, Wearable Technology |
| Companies Covered | Vishay Intertechnology, Inc., Yageo Corporation, Johanson Technology, Inc., Antenova Ltd., Taoglas, Mitsubishi Materials Corporation, Linx Technologies, Inc., Abracon, Murata Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chip Antenna Market Emerging Trajectories
Antenna-in-package integration is compressing module footprints while substrate material innovation and procurement model evolution are redrawing competitive boundaries across frequency bands.
Low-temperature co-fired ceramic technology is miniaturizing multilayer antenna structures into sub-two-millimeter thicknesses for wearable and hearable applications. Medical device OEMs and fitness tracker brands are adopting these substrates at accelerated pace to eliminate connector assemblies. The technology is miniaturizing board area requirements by sixty percent versus traditional PCB trace antennas, forcing laminate suppliers to defend position through cost reduction.
EU Radio Equipment Directive harmonization is converging electromagnetic compatibility testing across member states, reducing redundant certification costs for antenna vendors. The framework mandates unified spurious emission limits and spectrum efficiency metrics that previously varied by national regulator. Automotive telematics and industrial IoT modules face the steepest compliance burden, with manufacturers consolidating SKU portfolios to streamline documentation.
Contract manufacturers are consolidating antenna procurement under direct material programs that bypass traditional distribution channels. Foxconn and Jabil are negotiating multi-year dielectric supply agreements that lock in volume commitments and technical roadmaps. This concentration is most visible in China, where domestic module makers are securing captive ceramic antenna capacity to support 5G CPE and IoT gateway production.
Chip Antenna Market Segmentation
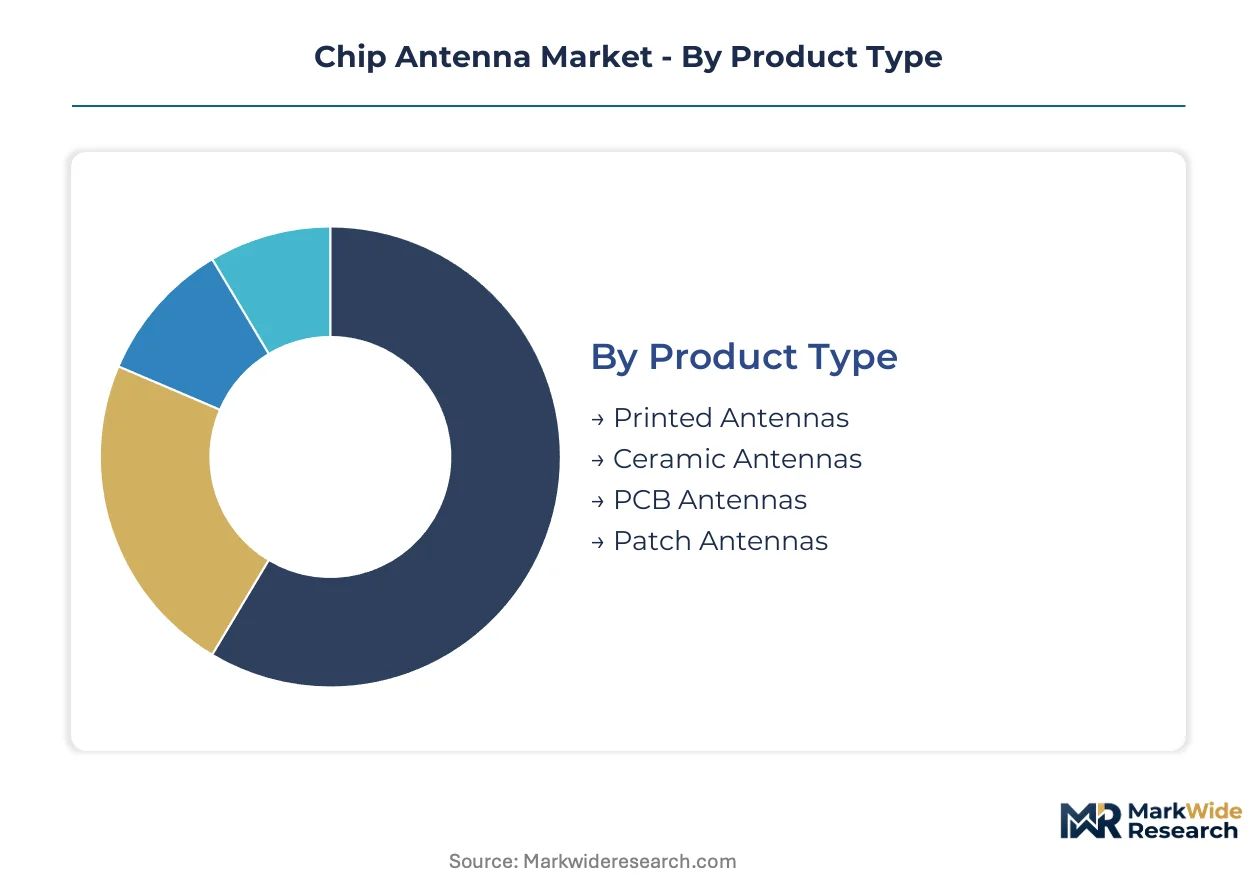
Antenna substrate selection and frequency band targeting determine module cost structures and regulatory compliance pathways across connected device ecosystems. Segmentation reveals where ceramic dielectrics defend position against organic laminate substitution and which wireless protocols command premium socket value.
Product Type:
Ceramic formulations face mounting pressure from cost-optimized PCB trace alternatives in consumer electronics volume tiers, while printed antenna architectures displace discrete components in smart home gateways.
- Ceramic Antennas:Multilayer low-temperature co-fired ceramic substrates deliver temperature-stable dielectric performance with Q-factors exceeding 200 for 5G sub-6 GHz modules. Automotive telematics suppliers in Germany and Japan specify these for AEC-Q200 qualification paths requiring negative 40 to positive 150 degree Celsius operation.
- PCB Antennas:Copper trace radiators integrated into FR-4 or high-frequency laminate substrates eliminate discrete component handling for cost-optimized IoT endpoints. Smart home device assemblers in Shenzhen and Dongguan favor these for sub-dollar bill-of-material targets in Wi-Fi motion sensors and smart plugs.
- Printed Antennas:Silver or carbon conductive inks deposited on flexible polymer films enable conformal integration into wearable form factors with sub-millimeter thickness constraints.
- Patch Antennas:Rectangular metallic radiators on grounded substrates provide directional gain for millimeter-wave radar and fixed wireless access CPE deployments.
Ceramic antennas anchor the volume base while PCB antennas gain share at the steepest rate in cost-driven consumer tiers.
End User:
Procurement scale and qualification intensity diverge sharply between automotive OEM direct material programs and electronics contract manufacturer spot buying.
- Automotive:Connected vehicle mandates from NHTSA and EU eCall regulations mandate cellular and V2X antenna counts rising from two to eight units per platform. Tier-1 module suppliers in Stuttgart, Munich, and Toyota City lock in multi-year ceramic antenna supply agreements with dielectric material roadmaps.
- Consumer Electronics:Smartphone and tablet OEMs drive absolute unit demand with Bluetooth and Wi-Fi coexistence architectures requiring three to five antennas per device. Foxconn and Pegatron consolidation in Zhengzhou and Chengdu concentrates procurement leverage.
- Telecommunications:5G small cell and CPE infrastructure demands beamforming antenna arrays with tight phase-matching specifications.
- Healthcare:FDA Class II device requirements and IEC 60601-1-2 electromagnetic immunity standards constrain antenna selection for patient monitoring wearables.
Consumer electronics anchors the volume base while automotive gains share at the steepest rate on connected vehicle penetration.
Technology:
Protocol selection governs frequency allocation, power consumption budgets, and intellectual property licensing cost structures across module designs.
- Wi-Fi:IEEE 802.11be Wi-Fi 7 specifications drive multi-input multi-output antenna array integration with 320 MHz channel bonding for enterprise access points. Qualcomm and Broadcom baseband reference designs specify two-by-two and four-by-four configurations in premium consumer routers.
- Bluetooth:Low-energy 5.3 specifications enable sub-milliwatt operation for hearable and wearable battery life extension. Nordic Semiconductor and Silicon Labs module reference designs dominate TWS earbud and fitness tracker sockets.
- NFC:13.56 MHz inductive coupling demands ferrite-backed antenna coils for secure payment and access control metal-environment operation.
- Zigbee:802.15.4 mesh networking at 2.4 GHz and sub-GHz bands targets smart home and industrial sensor networks with multi-year battery life requirements.
Bluetooth anchors the volume base while Wi-Fi gains share at the steepest rate on bandwidth escalation in premium tiers.
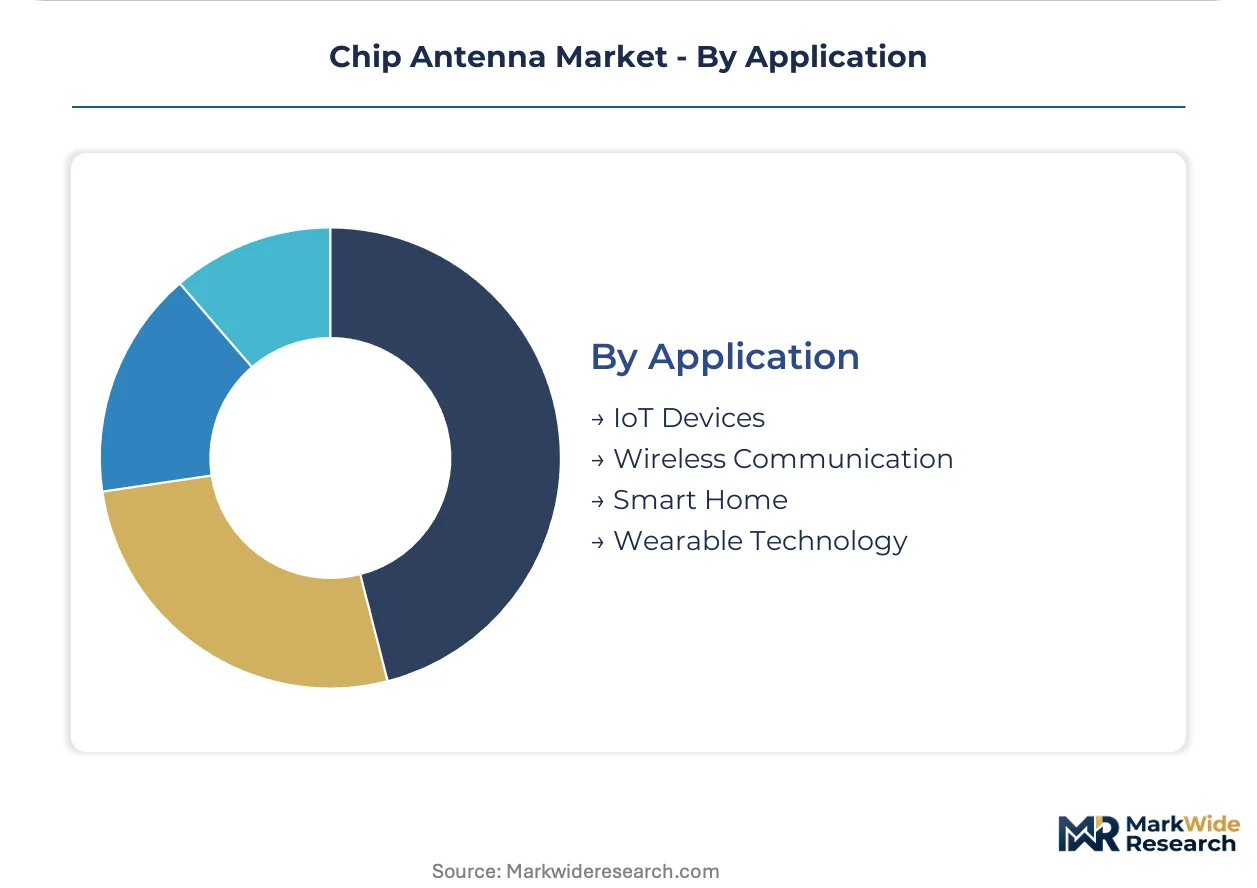
Application:
Integration depth and antenna count per device vary from single-radiator IoT endpoints to multi-band arrays in converged communication platforms.
- IoT Devices:Asset trackers, environmental sensors, and utility meters demand sub-GHz and 2.4 GHz dual-band ceramic antennas with negative 40 dBm sensitivity for extended range. Semtech LoRa and Telit cellular module ecosystems specify compact surface-mount formats for battery-constrained deployments.
- Wearable Technology:Smartwatches and fitness bands require sub-two-millimeter ceramic antennas with human-body loading compensation algorithms. Apple Watch and Samsung Galaxy Watch industrial designs drive miniaturization roadmaps at Murata and Johanson Technology.
- Smart Home:Voice assistants, security cameras, and climate controllers integrate PCB and ceramic hybrid architectures for Wi-Fi and Thread coexistence.
- Wireless Communication:Smartphones and tablets remain the antenna count leaders with cellular, Wi-Fi, Bluetooth, UWB, and NFC radiators sharing compact chassis volumes.
Wireless communication anchors the volume base while IoT devices gain share at the steepest rate on sensor network deployment scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement power concentrates most visibly in China, where domestic module makers scale 5G and IoT deployments, while European REACH compliance and evolving FCC Part 15 rules in the US tighten electromagnetic compatibility thresholds across supplier networks.
China
MIIT radio type approval timelines extend sixteen to twenty-four months for new antenna SKUs, delaying product launches for multi-region device makers. Domestic module makers in Shenzhen and Dongguan scale 5G CPE and IoT gateway production, securing captive ceramic antenna capacity through direct material programs that bypass traditional distribution channels.
United States
NHTSA telematics requirements mandate cellular connectivity in new vehicle platforms, expanding antenna count per vehicle from two to eight units. FCC Part 15 rulemaking in the 60 GHz band unlocks radar and high-speed data applications demanding compact antenna arrays for industrial sensing in Austin and Boston technology corridors.
Germany
EU eCall regulations mandate cellular and V2X antenna integration in automotive platforms. ECHA REACH restrictions on hazardous substances accelerate substitution toward ceramic substrates eliminating lead-based formulations. Stuttgart and Munich host Tier-1 module suppliers locking in multi-year ceramic antenna supply agreements with dielectric material roadmaps.
Japan
METI technical standards add compliance layers for multi-region product launches in automotive telematics. Temperature cycling and mechanical shock testing for ceramic antennas extends eighteen months for AEC-Q200 qualification. Toyota City anchors automotive supplier concentration requiring negative 40 to positive 150 degree Celsius operation specifications.
India
TRAI spectrum allocations support 5G infrastructure deployment creating module assembly demand. The production-linked incentive program for telecom equipment attracts investment that creates localized antenna sourcing demand for export manufacturing. Bengaluru and Hyderabad electronics manufacturing clusters expand contract manufacturer presence.
Chip Antenna Market Vendor Landscape
Player mix skews toward vertically integrated material specialists and broad-line passive component houses. Ceramic dielectric expertise concentrates among Japanese and Taiwanese suppliers with backward integration into barium titanate refining. Three archetypes dominate: substrate-integrated specialists commanding automotive qualification paths, portfolio-diversified conglomerates cross-selling through distribution, and frequency-focused boutiques serving aerospace and defense accounts. Competitive moves center on multi-year supply agreements locking volume commitments and technical roadmaps, alongside AEC-Q200 qualification investments extending eighteen-month testing cycles.
Within the substrate-specialist tier, Murata Manufacturing Co., Ltd. and Johanson Technology, Inc. exemplify divergent scale positioning. Murata anchors ceramic antenna supply through in-house production of dielectric materials. Johanson Technology occupies a boutique position specializing in high-frequency miniaturization. Among broad-line passive houses, Vishay Intertechnology, Inc. represents the cross-selling archetype leveraging component portfolios to access industrial accounts. Yageo Corporation sits within the Taiwanese manufacturing cluster serving cost-optimized consumer electronics tiers.
| Leading Market Players |
|---|
| Vishay Intertechnology, Inc. |
| Yageo Corporation |
| Johanson Technology, Inc. |
| Antenova Ltd. |
| Taoglas |
| Mitsubishi Materials Corporation |
| Linx Technologies, Inc. |
| Abracon |
| Murata Manufacturing Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Eighteen-month AEC-Q200 qualification cycles lock working capital in ceramic antenna inventory before revenue recognition, concentrating pricing power among Japanese and Taiwanese suppliers with backward integration into barium titanate refining while compressing margins for module houses without captive material supply.
Pricing Analysis
Wi-Fi 7 antenna arrays command premium positioning over legacy Bluetooth and sub-GHz ceramic units. Three-tier pricing structure across AEC-Q200 automotive, industrial-grade, and consumer electronics tiers separates qualification-intensive sockets from cost-optimized IoT endpoints. Cost compression in PCB trace alternatives is intensifying because Shenzhen contract manufacturers eliminate discrete component handling. Consumer electronics OEMs exhibit highest price sensitivity, while German automotive Tier-1s accept premium positioning for negative 40 to positive 150 degree Celsius operation specifications.
Supply Chain Analysis
Port congestion on the Shanghai-Ningbo corridor and container availability constraints on Asia-Europe trade lanes expose antenna module houses to inbound logistics volatility. High-purity barium titanate and rare-earth dopants draw from Chinese mining and refining operations, with Japanese ceramic specialists sourcing from domestic and Taiwanese material networks. Single-source vulnerability concentrates in Chinese dielectric powder refining, threatening supply continuity under export control scenarios. Distribution runs through direct material programs negotiated by Foxconn and Jabil that bypass traditional component distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chip antenna procurement is consolidating under platform-economics logic as automotive OEMs mandate cellular and V2X integration, forcing module suppliers to standardize around Qualcomm and Broadcom baseband reference designs that privilege qualified antenna vendors with dielectric material roadmaps.
For Market Incumbents: Secure multi-year supply agreements locking volume commitments and technical roadmaps with German and Japanese automotive Tier-1s before AEC-Q200 qualification windows close. Deepen backward integration into barium titanate refining to defend margin position against Chinese ceramic substrate cost erosion. Prioritize LTCC capacity expansion for wearable and hearable miniaturization demands from Apple and Samsung industrial design teams. For New Entrants and Emerging Players: Lead with India PLI scheme leverage to capture localized antenna sourcing demand from Bengaluru and Hyderabad contract manufacturing clusters expanding 5G CPE export production. Target industrial IoT asset tracking as the most penetrable segment, where UWB regulatory tailwinds from FCC Part 15 relaxations enable precision ranging applications with less entrenched incumbent supply relationships. Pursue white-label module partnerships with domestic Indian telecom equipment assemblers. For Investors and Strategic Acquirers: Long-term, this sits as a automotive-semiconductor convergence play because connected vehicle mandates multiply antenna count per platform from two to eight units, embedding ceramic antenna suppliers into cellular telematics value chains with decade-long design-in cycles. Acquisition targets should emphasize boutique frequency specialists with aerospace qualification paths and in-house electromagnetic simulation talent. Watch MIIT type approval timeline compression as the signal indicating Chinese regulatory alignment with global automotive launch schedules.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Qualification Investment | Eighteen-month testing cycles lock automotive OEM design-in preference for temperature-stable ceramic substrates. |
| LTCC Capacity Expansion | Sub-two-millimeter ceramic miniaturization captures wearable sockets from PCB trace alternatives in smartwatch and fitness tracker designs. |
| Backward Integration into Barium Titanate | In-house dielectric material production insulates margin structures from Chinese rare-earth export control volatility. |
| Direct Material Program Negotiation | Multi-year agreements with Foxconn and Jabil bypass distribution channels and secure volume visibility for capacity planning. |
| Wi-Fi 7 Beamforming Array Development | Multi-input multi-output antenna integration with Qualcomm and Broadcom reference designs captures enterprise access point sockets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive Tier-1 procurement directors, RF module design engineers, ceramic dielectric material specialists, and contract manufacturing sourcing leads. Secondary validation drew from FCC Part 15 rulemaking dockets, MIIT radio type approval databases, EU ECHA REACH restriction timelines, and SEC filings from passive component manufacturers. Bottom-up antenna unit demand estimates triangulated against top-down connected vehicle production forecasts and IoT device shipment projections.
Across the analysis window, volume and value outputs reflect segmented modeling across ceramic, PCB, printed, and patch antenna product types; automotive, consumer electronics, telecommunications, and healthcare end users; and Wi-Fi, Bluetooth, NFC, and Zigbee technology protocols. CAGRs were derived from regression analysis of historical qualification cycle data and forward projection of regulatory mandate implementation schedules. Industry-specific inputs included AEC-Q200 test duration benchmarks, MIIT approval timeline distributions, and LTCC substrate thickness miniaturization curves.
The analysis sits within stated boundaries; outcomes outside FCC Part 15 spectrum reallocation decisions, ECHA material restriction timelines, or MIIT certification process reforms would require recalibration. Forecasts reflect documented assumptions regarding connected vehicle mandate adherence rates and ceramic substrate substitution elasticity under REACH compliance pressure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
802.15.4 Chipset Market