
 Wireless Connectivity Chipset Market | 2026-2036
Wireless Connectivity Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Connectivity Chipset Market Analytics
Wi-Fi 7 certification is redrawing competitive boundaries for high-throughput wireless platforms. Qualcomm Incorporated leverages its integrated modem-RF systems to sustain design wins across premium smartphone tiers. Broadcom Inc. anchors enterprise access point supply with specialized baseband architectures. MediaTek Inc. competes aggressively in mid-market IoT modules where cost-optimized Bluetooth-Wi-Fi combos dominate bill-of-materials decisions.
Wireless connectivity chipsets are integrated circuits that modulate, demodulate, encode, and decode radio frequency signals across licensed and unlicensed spectrum bands, typically fabricated on 12-inch CMOS wafers with integrated power amplifiers and switch matrices to enable device-to-device and device-to-network communication. Their primary purpose is to provide protocol-compliant wireless interfaces for data transmission in consumer, industrial, and automotive systems. Wi-Fi chipsets capture the largest value pool as enterprise and residential access point upgrades accelerate, while Bluetooth modules in wearable devices represent the fastest-expanding volume segment driven by health-monitoring form factors. Automotive electronics applications are concentrating margin pools where ASIL-compliant variants command premium positioning against standard consumer-grade alternatives.
The Federal Communications Commission in the United States governs unlicensed spectrum allocation and device authorization, while the European Telecommunications Standards Institute coordinates harmonized frequency access across EU member states, and China's Ministry of Industry and Information Technology administers type approval for radio transmission equipment. These frameworks shape chipset development roadmaps by mandating coexistence protocols, power limits, and security requirements that determine market access eligibility. Stakeholders must monitor spectrum reallocation proceedings and regional cybersecurity mandates to align certification timelines with product release cycles.
Market Dynamics
Wi-Fi 7 certification timelines and EU Radio Equipment Directive compliance thresholds are compressing product development cycles while concentrating procurement authority among automotive OEMs and cloud infrastructure operators with dedicated certification resources.
Growth Catalysts
- Connected Vehicle Mandates:Automotive electronics manufacturers are expanding chipset procurement for ADAS and infotainment platforms as vehicle architectures centralize compute around zonal controllers.
- REACH and RoHS Evolution:European material compliance requirements are accelerating replacement of legacy substrate materials with halogen-free laminates in high-volume consumer modules.
- 6 GHz Spectrum Liberation:FCC Part 15 rulemaking across the United States, South Korea, and Brazil is unlocking contiguous bandwidth for multi-gigabit residential and enterprise deployments.
Market Restraints
- Advanced CMOS Wafer Allocation:Foundry capacity for 12-inch RF-CMOS processes remains concentrated among three Taiwan-based suppliers, creating input bottlenecks during demand surges.
- ASIL Certification Overhead:Automotive-grade variants require fault-tolerant architectures that carry 40-60% die area penalties versus consumer equivalents, compressing margin pools at volume.
- Power Amplifier Integration Limits:Linearization requirements at Wi-Fi 7 modulation densities are forcing discrete PA architectures in flagship smartphones, reversing prior integration trends.
Strategic Opportunities
- Industrial Private 5G Convergence:Manufacturing facilities in Germany and Japan are deploying blended Wi-Fi 6E/5G campus networks requiring unified baseband silicon.
- Wearable Health Form Factors:Bluetooth Low Energy Audio and ultra-wideband ranging are converging in continuous glucose monitors and fall-detection pendants.
- India PLI Incentives:Production-linked incentive schemes for telecom equipment are attracting module assembly investments serving domestic handset and automotive demand.
Industry Challenges
- RF-Analog Design Talent Scarcity:Millimeter-wave circuit expertise resides with a shrinking cohort of specialists trained on legacy GaAs processes, constraining team scaling.
- Coexistence Certification Complexity:Wi-Fi and Bluetooth simultaneous operation testing under FCC and ETSI frameworks extends validation timelines by 8-14 weeks.
- Legacy Fleet Support Burden:Long-tail maintenance obligations for Wi-Fi 4/5 automotive modules divert engineering resources from next-generation development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Connectivity Chipset Market |
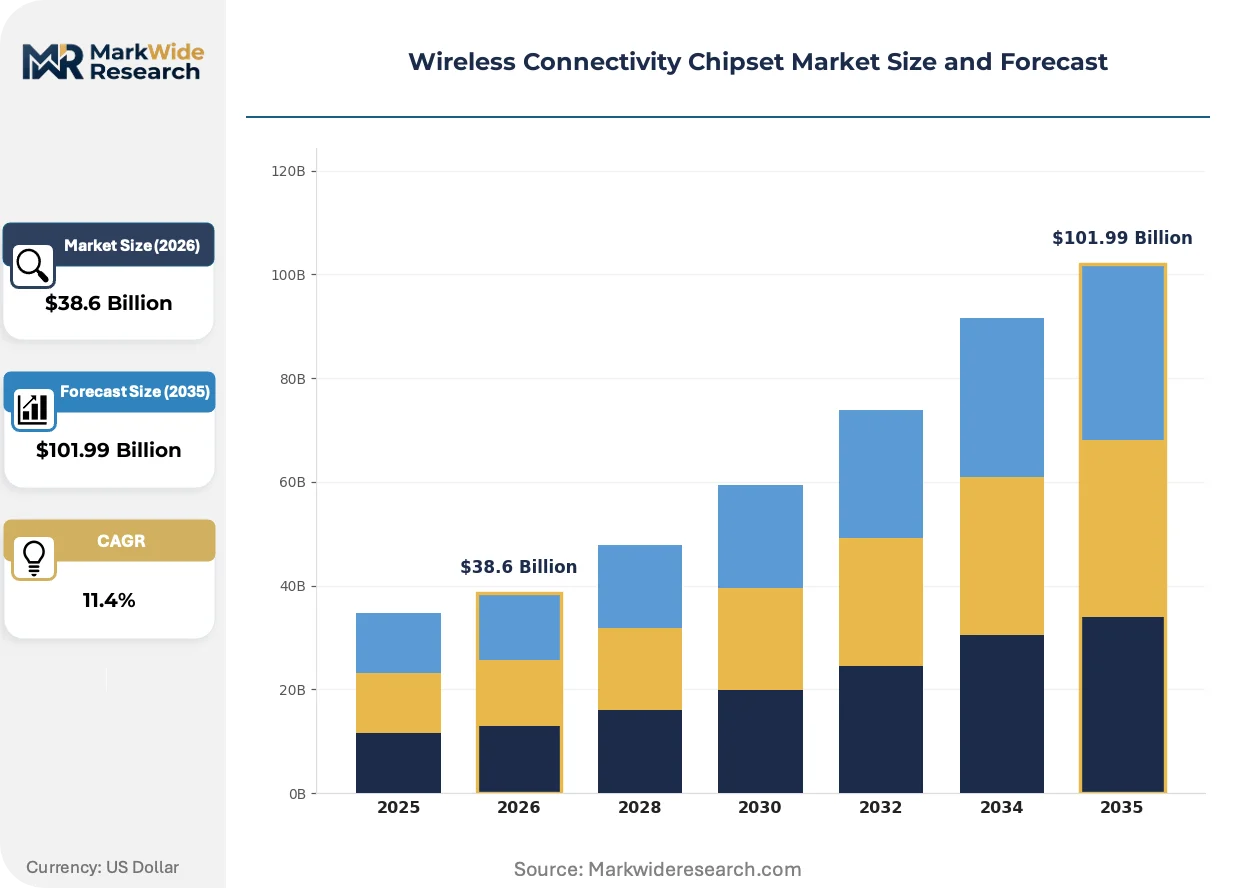
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Bluetooth, Wi-Fi, Zigbee, NFC Application: Smart Home, Automotive Electronics, Wearable Devices, Industrial Automation End User: Consumer Electronics, Healthcare Devices, Telecommunications, Automotive Form Factor: Module, Chip-on-Board, System-on-Chip, Integrated |
| Companies Covered | Broadcom Inc., Qualcomm Incorporated, MediaTek Inc., Intel Corporation, Texas Instruments Incorporated, STMicroelectronics NV, NXP Semiconductors NV, Infineon Technologies AG, Skyworks Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Connectivity Chipset Market Evolving Landscape
Silicon integration architectures and spectrum policy frameworks are reshaping how connectivity functions are partitioned between host processors, discrete basebands, and front-end modules across device categories.
System-in-package designs incorporating antenna-in-package substrates are miniaturizing RF front-end footprints for true wireless earbuds and smartwatch form factors. Wearable OEMs in China and Vietnam are adopting these configurations to preserve battery volume. The compression of board area is enabling multi-sensor fusion without expanding device dimensions.
ETSI harmonized standards for 6 GHz power spectral density are mandating automated frequency coordination in enterprise access points sold across EU member states. Infrastructure vendors must embed environmental sensing capabilities that dynamically throttle transmit power. Germany and France are enforcing the strictest implementation timelines, forcing firmware architecture redesigns.
Enterprise IT departments are consolidating wireless access point procurement through hyperscale cloud marketplaces rather than traditional value-added distributors. Amazon Web Services and Microsoft Azure marketplaces now list pre-certified hardware bundles with management software subscriptions. This channel migration is most pronounced in North American mid-market deployments where internal RF engineering expertise is limited.
Wireless Connectivity Chipset Market Segmentation
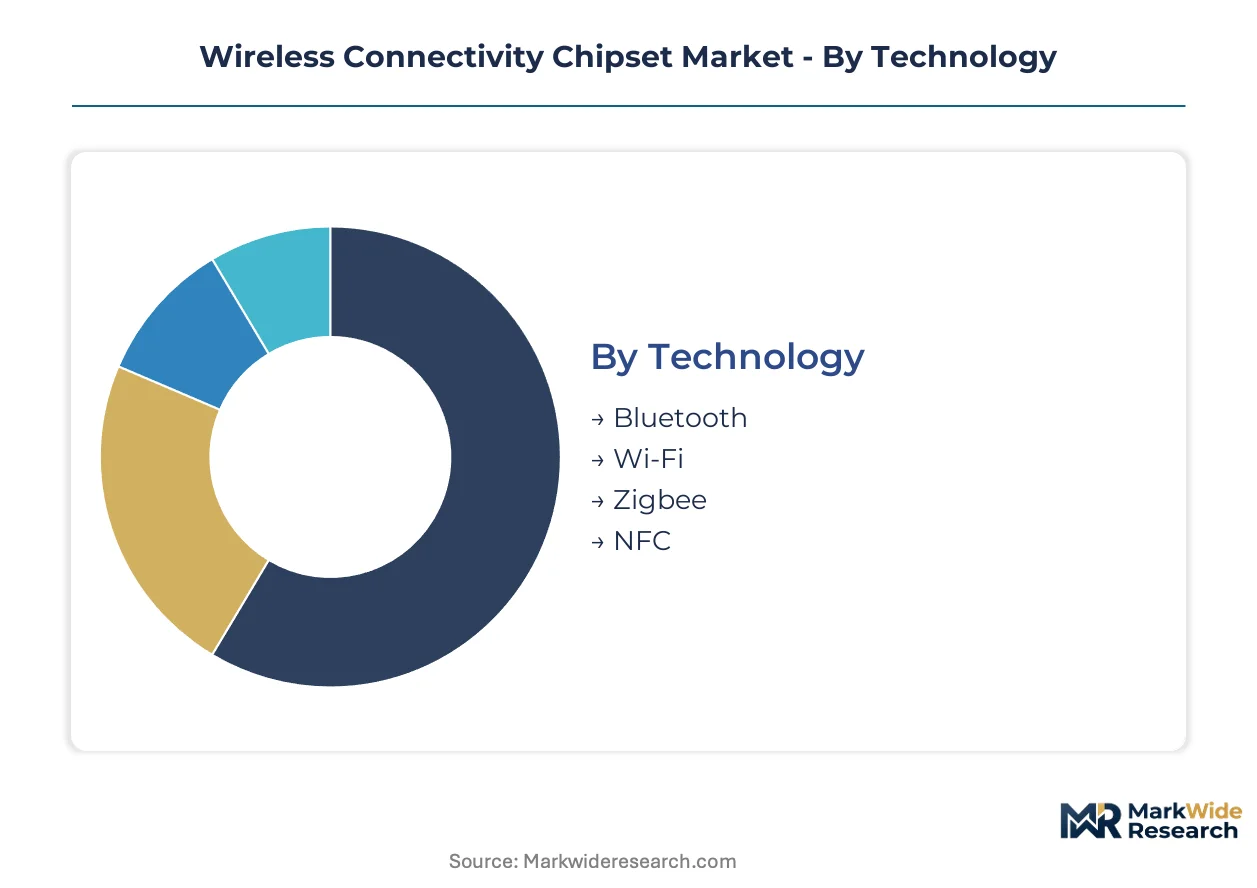
Connectivity chipset procurement patterns diverge sharply across technology standards and device architectures, with automotive qualification requirements and wearable miniaturization pressures fragmenting sourcing strategies. Understanding segment boundaries helps vendors align R&D roadmaps with certification timelines and foundry capacity allocation.
Technology:
Substitution pressure from converged multi-protocol silicon is reshaping standalone baseband demand, with integrated solutions displacing discrete Bluetooth and Zigbee variants in cost-sensitive consumer modules.
- Wi-Fi:Baseband architectures supporting 320 MHz channel bonding and 4K-QAM modulation dominate enterprise access point and premium smartphone bill-of-materials. Demand concentrates in South Korea and the United States where 6 GHz spectrum allocation has accelerated infrastructure refresh cycles.
- Bluetooth:Low Energy Audio and Auracast broadcast capabilities are driving socket wins in true wireless earbuds and hearing aid form factors. Procurement from Chinese wearable OEMs in Shenzhen and Dongguan clusters is climbing fastest as health-monitoring features proliferate.
- Zigbee:Mesh networking stacks optimized for sub-GHz operation retain positioning in smart lighting and utility meter deployments where interoperability with legacy Thread networks matters.
- NFC:Secure element integration for contactless payment authentication limits supplier pool to vendors with Common Criteria certification.
Wi-Fi retains volume leadership among discrete baseband categories; Bluetooth holds the steepest expansion curve as audio and ranging applications multiply.
Application:
Cost tier stratification separates ASIL-compliant automotive variants from consumer-grade alternatives, with qualification overhead creating 3-4x pricing spreads between functionally similar silicon.
- Automotive Electronics:Zonal gateway architectures and V2X communication modules require fault-tolerant designs with extended temperature ranges. Procurement from German and Japanese OEMs is tightening as UNECE WP.29 cybersecurity mandates take effect.
- Wearable Devices:Continuous glucose monitors and fall-detection pendants are converging Bluetooth Low Energy with ultra-wideband ranging in single-die solutions. Chinese and Vietnamese contract manufacturers are driving module miniaturization through system-in-package adoption.
- Smart Home:Matter protocol certification is consolidating previously fragmented Zigbee, Thread, and Wi-Fi ecosystems behind unified application layers.
- Industrial Automation:Private 5G and Wi-Fi 6E convergence in German and Japanese manufacturing facilities is creating demand for unified baseband silicon with deterministic latency guarantees.
Automotive Electronics commands the highest average selling prices; Wearable Devices is expanding most quickly on health-monitoring unit volume.
End User:
Customer type determines certification burden and support lifecycle, with automotive and healthcare procurement teams imposing traceability requirements that consumer electronics vendors rarely match.
- Consumer Electronics:Smartphone, tablet, and PC OEMs prioritize modem-RF integration to preserve board area and simplify thermal management. Annual design cycles compress supplier qualification windows.
- Healthcare Devices:FDA and EMA regulatory pathways for connected diagnostic equipment mandate ISO 13485 quality management and post-market surveillance capabilities.
- Telecommunications:Carrier-grade infrastructure deployments require NEBS Level 3 environmental compliance and decades-long firmware support commitments.
- Automotive:Tier-1 module suppliers must demonstrate PPAP submission capabilities and zero-defect traceability across multi-year platform lifecycles.
Consumer Electronics dominates unit shipment volume; Healthcare Devices shows the steepest margin expansion as continuous monitoring reimbursement codes proliferate.
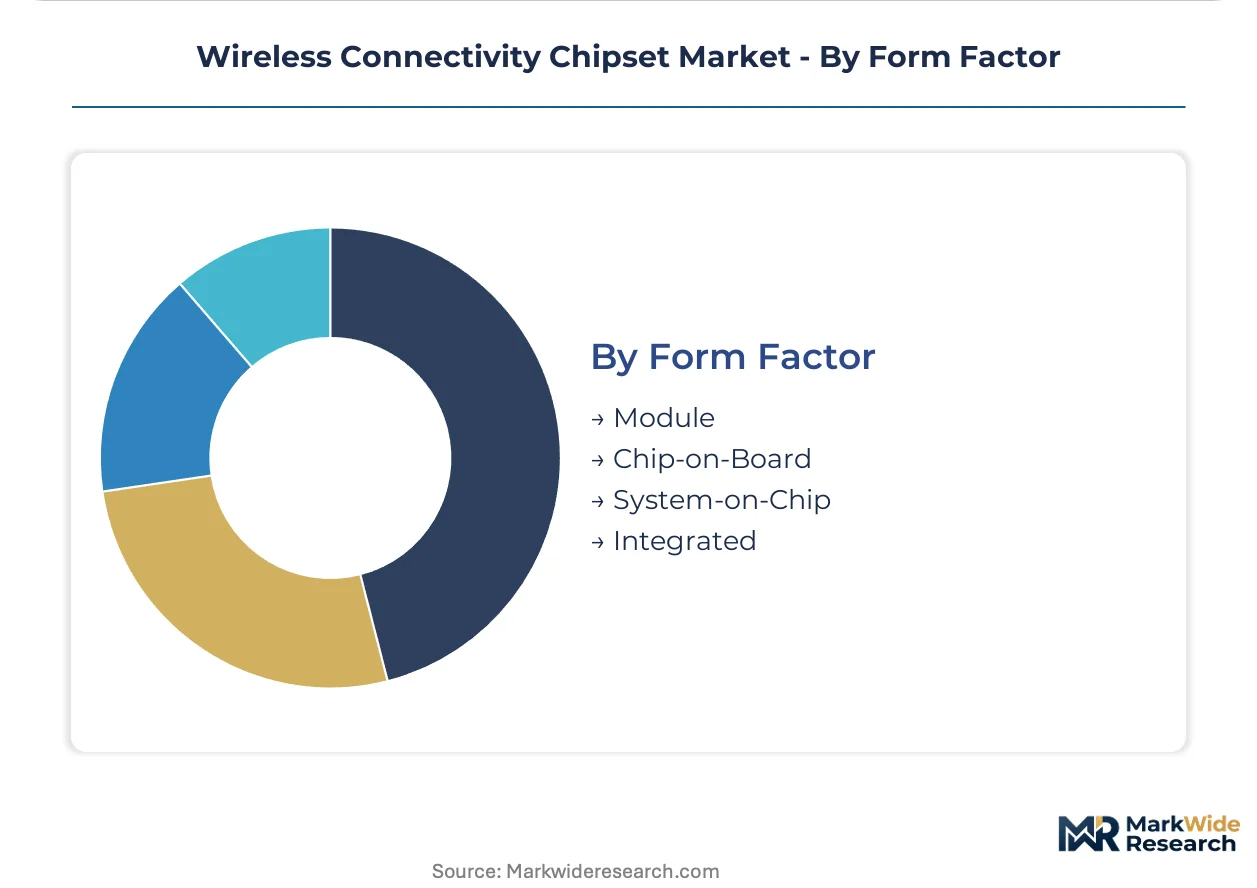
Form Factor:
Supply concentration in Taiwan-based substrate and assembly houses shapes availability timelines for miniaturized packaging variants, with antenna-in-package capacity particularly constrained.
- System-on-Chip:Application processor integration of connectivity basebands is advancing in flagship smartphones, though thermal constraints and process node mismatch limit migration to mid-tier devices.
- Module:Pre-certified radio units with integrated crystals and matching networks accelerate time-to-market for IoT device manufacturers lacking RF engineering expertise. Assembly in India under PLI incentives is rising for domestic handset demand.
- Chip-on-Board:Direct die attach with wire bonding persists in cost-optimized consumer applications where board area constraints are relaxed.
- Integrated:Single-die solutions combining MCU, radio, and power management dominate battery-powered sensor nodes in smart agriculture and asset tracking.
Module form factors retain the broadest customer base; System-on-Chip integration is climbing fastest at the premium tier as semiconductor process economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany and Japan dominate premium chipset procurement, while contract manufacturers in Vietnam and India absorb module assembly migration from coastal China.
United States
Cloud infrastructure operators and enterprise IT departments drive Wi-Fi 7 access point demand through hyperscale marketplace procurement. FCC Part 15 rulemaking governs 6 GHz spectrum allocation for multi-gigabit deployments. Design activity concentrates in San Diego and Austin, where modem-RF integration teams anchor premium smartphone platform development.
China
MIIT type approval requirements shape certification timelines for radio transmission equipment entering domestic channels. Shenzhen and Dongguan clusters host wearable OEMs adopting system-in-package configurations for health-monitoring form factors. Domestic foundry capacity for RF-CMOS processes remains concentrated among Taiwan-based suppliers serving cross-strait assembly networks.
Germany
Automotive electronics manufacturers impose ASIL-compliant qualification requirements for zonal gateway architectures. ETSI harmonized standards for 6 GHz power spectral density mandate automated frequency coordination in enterprise access points. Manufacturing facilities in Bavaria and Baden-Württemberg deploy blended Wi-Fi 6E/5G campus networks requiring unified baseband silicon.
South Korea
Smartphone OEMs sustain design wins for integrated modem-RF systems across premium tiers. National spectrum policy aligns with FCC frameworks on 6 GHz liberation for residential and enterprise infrastructure. Seoul-based semiconductor fabrication anchors supply for memory-integrated connectivity solutions serving domestic handset demand.
India
PLI schemes for telecom equipment attract module assembly investments serving domestic handset and automotive demand. TRAI frameworks govern spectrum allocation for private 5G deployments in manufacturing corridors. Tamil Nadu and Karnataka states host emerging electronics manufacturing clusters absorbing supply chain diversification from East Asian hubs.
Wireless Connectivity Chipset Market Competitive Landscape
Player mix skews toward integrated platform vendors with captive modem-RF expertise and specialized baseband architects serving enterprise infrastructure. Market structure concentrates procurement authority among automotive OEMs and cloud operators with dedicated certification resources. Two strategic archetypes dominate: vertically integrated semiconductor conglomerates controlling foundry relationships, and fabless specialists licensing IP cores to module manufacturers. Competitive moves center on spectrum policy alignment and ASIL qualification acceleration for automotive sockets.
Within the integrated platform tier, Qualcomm Incorporated and Broadcom Inc. occupy positions defined by modem-RF system completeness and enterprise access point specialization respectively. MediaTek Inc. sits within the cost-optimized volume tier, representing the archetype of fabless suppliers capturing mid-market IoT module sockets through Bluetooth-Wi-Fi combo integration.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Qualcomm Incorporated |
| MediaTek Inc. |
| Intel Corporation |
| Texas Instruments Incorporated |
| STMicroelectronics NV |
| NXP Semiconductors NV |
| Infineon Technologies AG |
| Skyworks Solutions Inc. |
| Others |
Value Network & Pricing Analysis
ASIL certification requirements gate both supplier qualification and price differentiation simultaneously, compressing margin pools for automotive-grade variants while concentrating procurement authority among Tier-1 module suppliers with dedicated compliance resources. Three-tier pricing structure across premium, standard, and economy levels reflects die area penalties, certification overhead, and volume scale rather than raw performance metrics alone.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate procurement between foundries and fabless designers, transferring commodity input volatility directly into module pricing. Price differentiation hinges on ASIL-D certification tier and 12-inch wafer allocation priority, with automotive OEMs showing lowest price sensitivity due to platform lifecycle commitments. Cost compression in consumer-grade Bluetooth-Wi-Fi combos is intensifying because Chinese wearable OEMs are consolidating socket decisions around integrated solutions.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for RF-CMOS processes, while Vietnam and India absorb module assembly migration from coastal China. Supply draws from 12-inch silicon substrates, halogen-free laminates, and antenna-in-package substrates. Single-source vulnerability concentrates in Taiwan-based foundry capacity. Distribution runs through hyperscale cloud marketplaces and traditional value-added distributors serving enterprise IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens across automotive zonal gateway architectures as OEMs diversify chipset sourcing beyond incumbent modem-RF suppliers. Health-monitoring wearable form factors create additional niche entry points for specialized baseband architects.
For Market Incumbents: Secure captive foundry allocation through long-term offtake agreements with Taiwan-based suppliers, insulating against capacity crunches during demand surges. Deepen backward integration into antenna-in-package substrate production to defend margin position against system-in-package miniaturization trends. Accelerate ASIL-D qualification pipelines to preempt emerging entrants from automotive socket wins. For New Entrants and Emerging Players: Firmware customization for automated frequency coordination in EU enterprise access points represents a service-layer gap where incumbents under-serve mid-market deployments lacking internal RF engineering expertise. Target Indian module assembly under PLI incentives as the most penetrable geography, leveraging domestic handset and automotive demand growth. Pursue certification-as-a-service partnerships with established test houses to compress validation timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor conglomerates with under-monetized connectivity IP cores stranded outside core business units. Long-term viability centers on spectrum policy alignment capabilities and automotive qualification acceleration rather than pure R&D scale. Watch FCC Part 15 rulemaking proceedings on additional unlicensed spectrum as the inflection indicator for next-generation infrastructure refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Unlocks automotive zonal gateway sockets requiring fault-tolerant architectures under UNECE WP.29 mandates. |
| System-in-Package Miniaturization | Preserves battery volume for Chinese wearable OEMs adopting health-monitoring form factors. |
| 6 GHz Spectrum Policy Alignment | Secures enterprise access point positioning as ETSI harmonized standards enforce automated frequency coordination. |
| Foundry Capacity Pre-commitment | Guarantees 12-inch RF-CMOS wafer allocation during demand surges from connected vehicle mandates. |
| Hyperscale Marketplace Listing | Captures North American mid-market procurement migrating from traditional value-added distributors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with RF design engineers, automotive Tier-1 procurement managers, wearable OEM supply chain directors, and hyperscale cloud marketplace operators; and secondary validation against FCC equipment authorization databases, ETSI harmonized standards filings, MIIT type approval records, SEC 10-K disclosures from listed semiconductor firms, and foundry capacity utilization reports. Bottom-up unit demand modeling triangulated against top-down value pool estimates across technology standards and application segments.
Across the analysis window, the analytical framework modeled volume and value trajectories by connectivity protocol, device architecture, certification tier, and regional regulatory cluster. CAGRs derived from segment-level growth rate blending weighted by value pool contribution. Forecast inputs incorporated spectrum allocation timelines, automotive platform lifecycle commitments, and foundry capacity expansion announcements.
Underlying assumptions cover sustained 6 GHz spectrum liberation, stable foundry pricing for RF-CMOS processes, and ASIL certification timeline compression, with deviation risk concentrated in geopolitical trade restrictions affecting cross-strait supply flows. Recalibration cycles align with material shifts in FCC and ETSI rulemaking proceedings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
5G CPE Chip Market