
 Global Narrowband IoT (NB IoT) Chipset Market | 2026-2036
Global Narrowband IoT (NB IoT) Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Global Narrowband IoT (NB IoT) Chipset Market Intelligence
Taiwanese and South Korean fabless design capacity is decoupling from reliance on a single foundry for sub-28nm process nodes, creating new supply chain dynamics. Qualcomm Technologies leverages its extensive intellectual property in cellular standards to command the high-performance segment. MediaTek Inc. competes on integrated System-on-Chip solutions for high-volume consumer electronics. In contrast, u-blox AG differentiates with robust modules for demanding automotive and industrial environments.
A Narrowband IoT (NB-IoT) chipset is a specialized integrated circuit designed for low-power wide-area network (LPWAN) communication. It operates on licensed spectrum and provides enhanced indoor coverage, often exceeding 20dB improvement over legacy GPRS, for battery-powered devices. The smart cities segment, particularly for utility metering, constitutes the largest end-user base. System-on-Chip (SoC) solutions are gaining share over module-based designs due to their smaller footprint and lower bill-of-materials cost.
Regulatory frameworks are critical for market access and interoperability. In Europe, compliance with the Radio Equipment Directive (RED) and CE marking is mandatory, while in the United States, the FCC sets spectrum rules under Part 15. China's MIIT enforces stringent network access license requirements for all cellular IoT devices. Device manufacturers must now decide on long-term chipset strategies as network operators finalize their 2G and 3G sunset timelines.
Market Dynamics
The global sunset of 2G and 3G cellular networks is the central force shaping the NB-IoT chipset market. This planned obsolescence compels device manufacturers in utility, logistics, and industrial sectors to migrate to modern LPWAN technologies for long-term deployments.
Growth Catalysts
- State-Led Deployments:China's Ministry of Industry and Information Technology (MIIT) continues to promote massive-scale NB-IoT adoption through national policies, particularly for smart water and gas metering, creating unparalleled volume demand for chipsets.
- Smart City Infrastructure:Investment in smart city projects, especially in Europe and North America, provides a significant catalyst. Applications like smart street lighting, waste management, and parking sensors depend on the low-power, deep-coverage capabilities of NB-IoT.
- 2G/3G Network Shutdown:The phased decommissioning of legacy cellular networks by mobile operators worldwide is a direct technological driver. This forces an upgrade cycle for millions of existing M2M devices, with NB-IoT positioned as a primary replacement technology.
Market Restraints
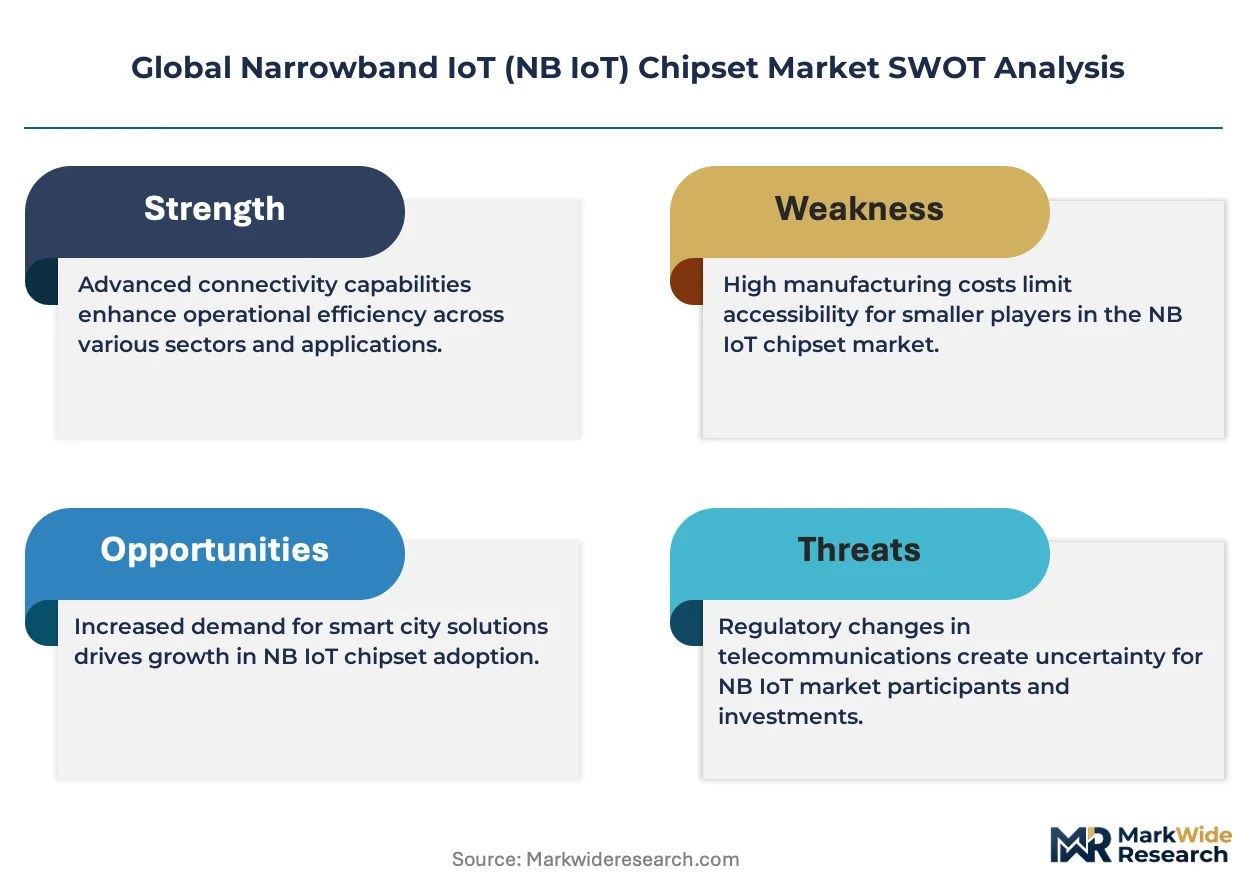
- LPWAN Technology Competition:NB-IoT faces competition from unlicensed spectrum technologies like LoRaWAN, which can offer lower total cost of ownership in private network deployments, posing a substitution threat in specific verticals like agriculture and campus environments.
- Mobility Limitations:The technology's design prioritizes stationary, low-power devices, resulting in limited support for seamless cell handover. This inherent technical constraint makes it unsuitable for high-mobility asset tracking and telematics applications that require continuous connectivity.
- Spectrum Fragmentation:Deployment is complicated by varying frequency band allocations across different countries and regions. This lack of global harmonization requires chipset and module vendors to produce multiple hardware variants, increasing inventory complexity and design costs.
Strategic Opportunities
- Emerging Agricultural IoT:The agricultural sector represents an underpenetrated market for NB-IoT. Applications in soil monitoring, livestock tracking, and smart irrigation in large-scale farms in the Americas and Australia offer substantial growth potential.
- Satellite-Terrestrial Integration:Combining NB-IoT with non-terrestrial satellite networks presents an opportunity to provide ubiquitous connectivity for logistics and environmental monitoring. This hybrid approach solves coverage gaps in remote or maritime locations where cellular infrastructure is unavailable.
- Smart Health and Wearables:There is a nascent opportunity in low-power personal health monitoring devices and wearables. Chipsets designed for remote patient monitoring or personal emergency response systems can leverage NB-IoT for reliable, low-bandwidth data transmission.
Industry Challenges
- Legacy System Integration:A significant operational hurdle is the complexity of integrating new NB-IoT-enabled sensors and devices with existing enterprise IT and operational technology (OT) platforms, which often rely on older, proprietary protocols.
- Cellular IP Licensing:Navigating the licensing landscape for standard-essential patents (SEPs) related to 3GPP cellular standards is a major challenge. The associated royalty costs and legal complexities can be a barrier for smaller device manufacturers.
- Carrier Certification Bottlenecks:Before market launch, every NB-IoT device must pass lengthy and costly certification processes not only for regulatory compliance like FCC or CE but also for each target mobile network operator, creating significant delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Narrowband IoT (NB IoT) Chipset Market |
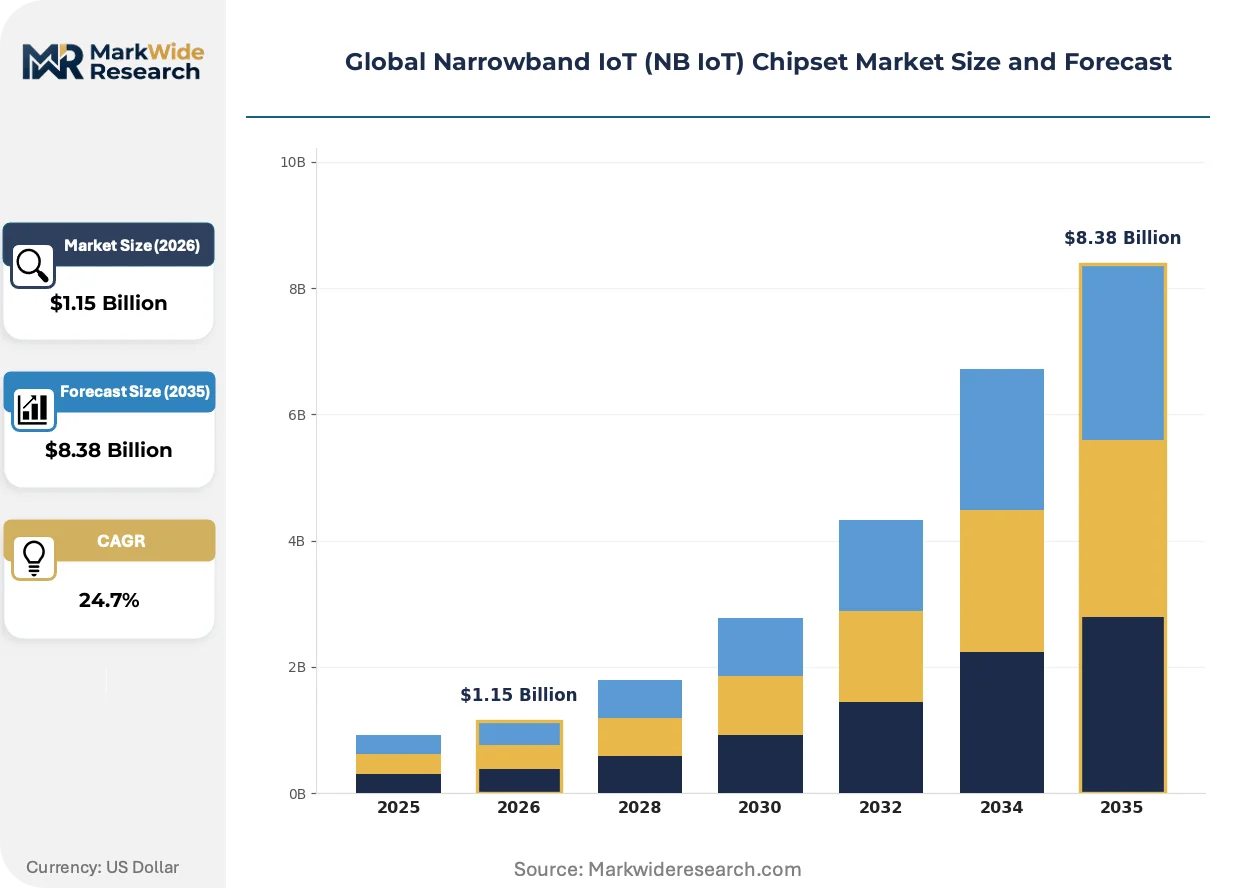
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $8.38 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Chipsets, Module-Based Chipsets, Standalone Chipsets, System-on-Chip Solutions End User: Agriculture, Smart Cities, Healthcare, Automotive Deployment Model: Private Network, Public Network, Hybrid Network, Managed Service Connectivity Technology: LTE-M, NB-IoT, Sigfox, LoRaWAN |
| Companies Covered | Intel Corporation, Samsung Electronics, Huawei Technologies Co. Ltd., Quectel Wireless Solutions, u-blox AG, Qualcomm Technologies, MediaTek Inc., Altair Semiconductor, Nordic Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Narrowband IoT (NB IoT) Chipset Market Strategic Shifts & Innovations
The market is evolving toward solutions that reduce complexity and total cost of ownership for device makers. This drives innovation in silicon integration, pre-certified modules, and simplified development platforms that abstract away the underlying cellular complexity, accelerating mass-market IoT adoption.
System-on-Chip (SoC) designs integrate the baseband processor, RF transceiver, power management, and memory into a single piece of silicon. High-volume manufacturers in smart metering and consumer electronics are adopting these SoCs to reduce their bill of materials and device footprint. This trend toward integrated silicon is modularizing the supply chain, enabling OEMs to focus on software and service differentiation rather than complex RF hardware engineering.
Europe's Radio Equipment Directive (RED) establishes a mandatory regulatory framework for products sold within the EU, ensuring safety and interoperability. The directive forces chipset and module designers to incorporate stringent security and electromagnetic compatibility features from the initial design phase. This particularly affects suppliers targeting European industrial IoT and critical infrastructure markets, where compliance is non-negotiable and serves as a mark of quality.
A clear behavioral shift is underway from sourcing discrete components to procuring pre-certified modules, often bundled with data plans from mobile virtual network operators. This model disrupts the traditional approach where OEMs managed chipset selection, hardware integration, and carrier negotiations as separate, complex workstreams. This trend is most prominent among new entrants and SMEs in North America who prioritize speed-to-market over deep hardware customization.
Global Narrowband IoT (NB IoT) Chipset Market Segmentation
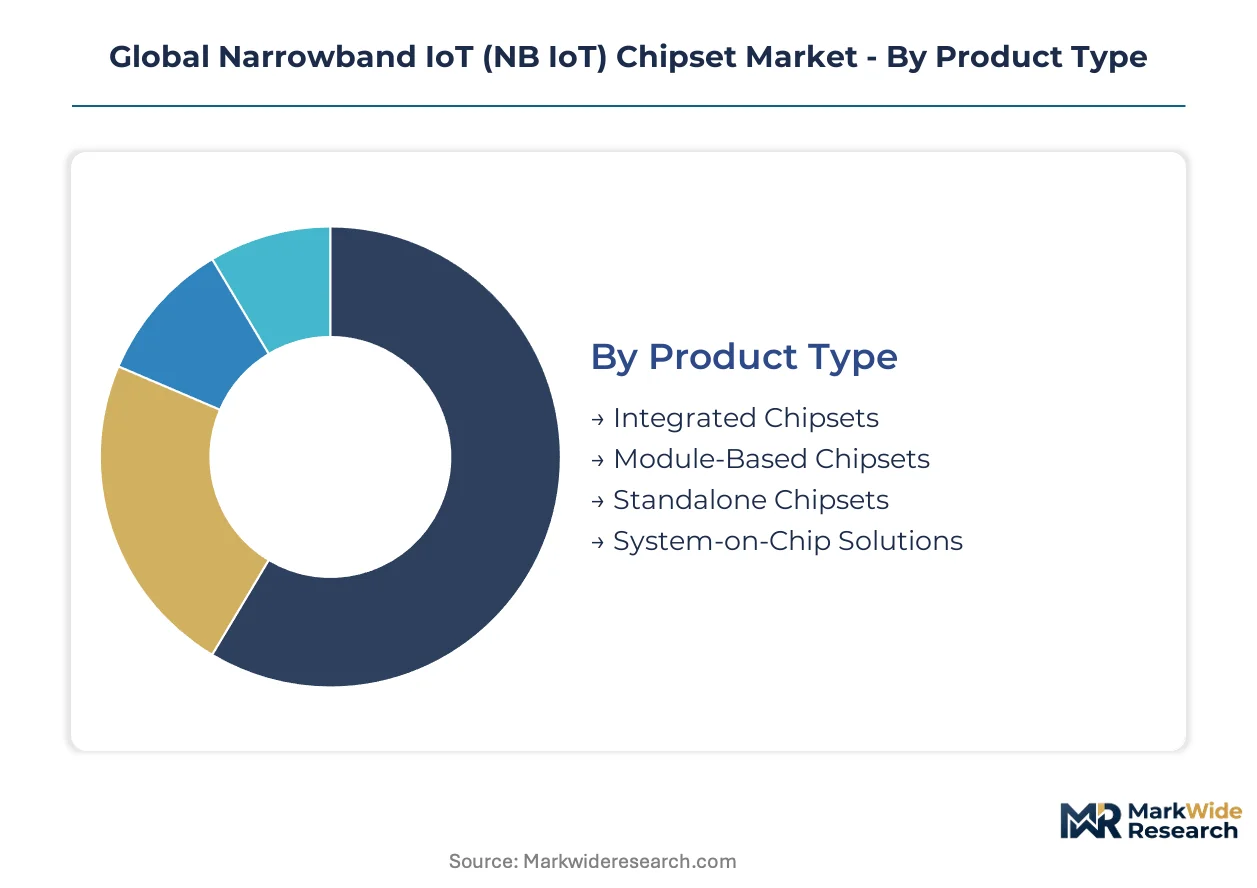
The Global Narrowband IoT (NB IoT) Chipset Market is analyzed through distinct segments, reflecting diverse technological requirements and application landscapes. Understanding these divisions helps stakeholders identify specific demand drivers and strategic opportunities. This granular view clarifies how different product types and end-user needs shape market evolution.
Product Type:
Buyers in the NB-IoT chipset market differentiate based on their design complexity tolerance and total cost of ownership objectives.
- System-on-Chip Solutions:Integrates baseband, RF, power management, and memory onto a single silicon die for compact designs. Demand concentrates in smart metering and consumer electronics, driven by the need for smaller footprints and lower bill-of-materials costs.
- Module-Based Chipsets:Pre-certified, self-contained units that simplify integration and accelerate time-to-market for device manufacturers. Significant demand comes from new entrants and SMEs in North America, prioritizing rapid deployment over deep hardware customization.
- Integrated Chipsets:Combine multiple functionalities onto a single die, streamlining design for various IoT applications.
- Standalone Chipsets:Provide core NB-IoT communication functionality, requiring external components for a complete solution.
Volume sits with Module-Based Chipsets; growth tilts toward System-on-Chip Solutions.
End User:
End-user segments define specific application requirements and deployment scales for NB-IoT chipsets.
- Smart Cities:Encompasses applications like utility metering, smart street lighting, and waste management, leveraging NB-IoT for low-power, deep-coverage capabilities. Demand is particularly strong in China due to state-led initiatives for massive-scale deployments in water and gas metering.
- Agriculture:Includes solutions for soil monitoring, livestock tracking, and smart irrigation across large-scale farms, requiring robust, low-power connectivity in remote areas. The Americas and Australia represent significant growth potential for these NB-IoT applications.
- Healthcare:Focuses on low-power personal health monitoring devices and remote patient monitoring systems.
- Automotive:Involves specific use cases for vehicle tracking and telematics where mobility limitations are less critical or addressed by hybrid solutions.
Application diversity drives Smart Cities deployments; emerging needs propel Agriculture sector expansion.
Deployment Model:
Operational control and service provision differentiate various deployment models for NB-IoT chipsets.
- Public Network:Utilizes existing mobile network operator infrastructure, offering broad coverage and simplified connectivity for mass-market IoT devices. This model is prevalent in Europe and North America, supporting diverse smart city and utility applications.
- Managed Service:Involves third-party providers handling network operations, device management, and data integration, offering a comprehensive solution for enterprises. This approach is gaining traction among SMEs seeking to reduce operational complexity and accelerate IoT adoption.
- Private Network:Deployed by organizations for dedicated, secure IoT connectivity within specific campuses or industrial sites.
- Hybrid Network:Combines elements of both private and public networks, optimizing for specific coverage, security, and cost requirements.
Scalability underpins Public Network deployments; simplified adoption drives Managed Service growth.
Connectivity Technology:
Technical specifications and spectrum usage distinguish different connectivity technologies within the LPWAN ecosystem.
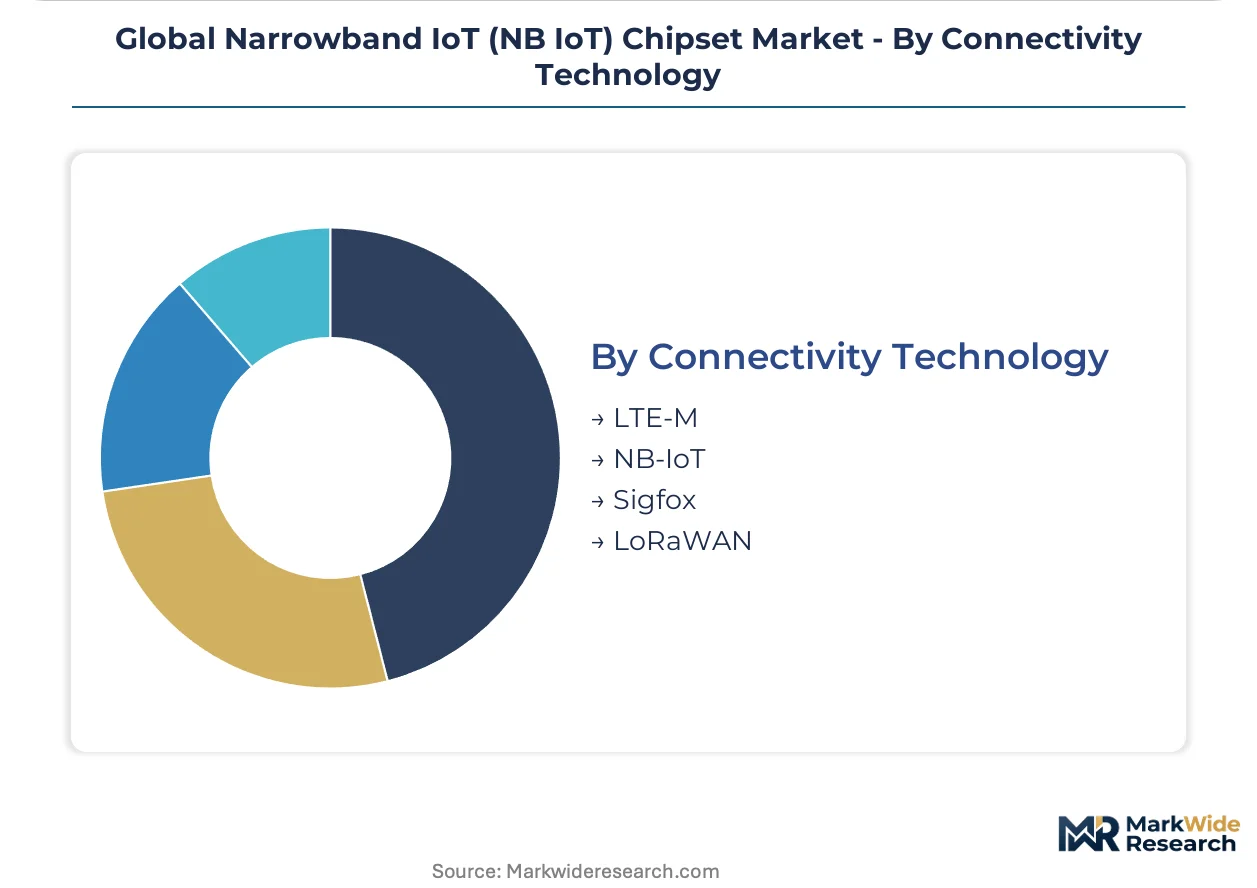
- NB-IoT:Operates on licensed spectrum, providing enhanced indoor coverage and ultra-low power consumption for stationary, battery-powered devices. Its deployment is heavily concentrated in China, driven by state-led initiatives for utility metering and infrastructure monitoring.
- LoRaWAN:Utilizes unlicensed spectrum, offering flexibility for private network deployments and potentially lower total cost of ownership in specific verticals. This technology poses a substitution threat in agriculture and campus environments, competing with licensed spectrum solutions.
- LTE-M:Provides higher bandwidth and supports mobility, catering to applications requiring more data throughput or asset tracking capabilities than NB-IoT.
- Sigfox:Offers ultra-narrowband communication for extremely low-power, low-data-rate applications, often used for simple sensor readings and asset tracking.
Market penetration centers on NB-IoT; niche applications expand through LoRaWAN.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, with its vast manufacturing base and state-led initiatives, anchors the global demand for Narrowband IoT (NB-IoT) chipsets. This concentration drives significant volume for chipset manufacturers worldwide. The country's strategic focus on smart city infrastructure sets a global benchmark for large-scale deployments.
China
China's Ministry of Industry and Information Technology (MIIT) actively promotes massive-scale NB-IoT adoption for smart water and gas metering. This state-led initiative creates unparalleled volume demand for chipsets. The Yangtze River Delta region, a major industrial hub, experiences extensive NB-IoT infrastructure deployment for smart utility applications.
Germany
Germany's industrial sector and smart city initiatives drive demand for robust NB-IoT modules for demanding automotive and industrial environments. Compliance with the Radio Equipment Directive (RED) and CE marking is mandatory for market access. Cities such as Hamburg actively deploy NB-IoT solutions for smart street lighting and waste management, showcasing practical applications.
United States
United States investment in smart city projects and emerging agricultural IoT applications fuels NB-IoT chipset demand. The FCC sets spectrum rules under Part 15, influencing device design and deployment. Silicon Valley companies are increasingly targeting agricultural IoT in California's Central Valley, leveraging NB-IoT for soil monitoring and smart irrigation.
Australia
Australia represents significant growth potential for NB-IoT, particularly in large-scale agricultural IoT and environmental monitoring. The Australian Communications and Media Authority (ACMA) regulates spectrum allocation and device compliance. Remote farming regions in Western Australia are rapidly adopting NB-IoT for livestock tracking and smart irrigation, addressing coverage gaps.
Global Narrowband IoT (NB IoT) Chipset Market Key Industry Players
Global majors compete with regional champions across cellular standards and intellectual property development in the NB-IoT chipset market. The market structure exhibits a tiered consolidation, with a few large players dominating the high-performance segment. Strategic archetypes include high-performance specialists, integrated System-on-Chip (SoC) providers, and robust module suppliers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and solution offerings.
Within the high-performance segment, Qualcomm Technologies, Inc. exemplifies leadership through its extensive intellectual property in cellular standards, commanding premium pricing. MediaTek Inc. occupies a position as a provider of integrated System-on-Chip solutions, targeting high-volume consumer electronics with cost-effective offerings. Switzerland-based u-blox AG represents the robust module supplier archetype, differentiating with solutions for demanding automotive and industrial environments requiring reliability. These companies anchor different value propositions within the broader NB-IoT ecosystem, catering to distinct customer requirements.
| Leading Market Players |
|---|
| Intel Corporation |
| Samsung Electronics |
| Huawei Technologies Co. Ltd. |
| Quectel Wireless Solutions |
| u-blox AG |
| Qualcomm Technologies |
| MediaTek Inc. |
| Altair Semiconductor |
| Nordic Semiconductor |
| Others |
Cost & Logistics Intelligence
Sovereign-backed initiatives in China profoundly influence NB-IoT chipset supply behavior, driving massive volume demand that impacts global pricing discipline. This state-led push for smart city deployments creates unique dynamics across the value chain.
Pricing Analysis
After-sales support and bundled software capabilities often differentiate pricing for NB-IoT chipsets and modules. The dominant pricing structure remains per-unit transactional, though licensing fees apply for standard-essential patents. Price differentiation stems from certification levels, such as CE marking compliance, and the volume scale of orders. Pricing pressure is intensifying due to competition from unlicensed LPWAN technologies like LoRaWAN. Smart city deployments in China, driven by state mandates, are highly price-sensitive, while industrial and automotive applications prioritize reliability and are less sensitive.
Supply Chain Analysis
Silicon wafer supply and advanced packaging capabilities heavily influence NB-IoT chipset production. Geographic supply concentrates in Taiwan, South Korea, and China, where major foundries and fabless design houses operate. Key dependencies include baseband processors, RF transceivers, and specialized memory components. Geopolitical tensions and trade restrictions represent a significant structural supply chain risk for this market. Downstream distribution runs primarily through direct sales to large OEMs and specialized distributors serving smaller device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NB-IoT chipset market operates as a cost-of-compliance story, with Europe's Radio Equipment Directive (RED) establishing a significant barrier-to-entry moat for non-compliant players.
For Market Incumbents:Hedge against rising intellectual property licensing costs by investing in proprietary cellular standards research and development. Diversify product portfolios to include 5G NR-Light solutions, mitigating the threat from evolving cellular standards. Deepen relationships with mobile network operators, ensuring preferential access to certification processes. Consolidate market share through strategic acquisitions of smaller, specialized module providers in Europe.
For New Entrants and Emerging Players:Module distributors represent a crucial channel for market entry, offering pre-certified solutions bundled with data plans. Target emerging agricultural IoT in regions like Australia, where coverage gaps create white-space opportunities. Focus on niche applications requiring robust, low-power connectivity, such as environmental monitoring sensors. A go-to-market angle emphasizing simplified integration and rapid deployment appeals to small and medium-sized enterprises.
For Investors and Strategic Acquirers:The global 2G and 3G network shutdown is the leading indicator that validates the long-term viability of NB-IoT as a replacement technology. The market shows potential for sustained growth over the next 5-10 years, driven by massive IoT deployments. Acquisition targets should include specialized SoC providers with strong IP portfolios or module manufacturers with established carrier certifications. New regulatory mandates expanding NB-IoT applications warrant ongoing watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into 5G NR-Light | Extends chipset relevance beyond NB-IoT, capturing future low-power cellular demand. |
| Investment in Carrier Certification Labs | Accelerates time-to-market for new devices, reducing bottlenecks for OEMs and operators. |
| Strategic Partnerships with Cloud Providers | Integrates device data with scalable analytics platforms, enhancing end-to-end IoT solutions. |
| Targeted Acquisition of Module Specialists | Consolidates market share and expands geographic reach, particularly in Europe and North America. |
| R&D in Satellite-Terrestrial Integration | Addresses coverage limitations in remote areas, enabling ubiquitous connectivity for logistics and agriculture. |
Research Approach
Document review covered publicly available financial statements, regulatory filings from the FCC and MIIT, and technical specifications from 3GPP, complemented by interviews with chipset engineers, IoT solution architects, and smart city planners. This approach incorporated both bottom-up market sizing and top-down validation. Secondary data sources included industry association reports and academic research on LPWAN technologies.
Volume and value outputs were generated through a robust analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, end-user industry, deployment model, connectivity technology, and geographic region. Compound annual growth rates were derived from historical data and projected market drivers, with 2G/3G sunset timelines and smart city investment trends serving as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical trade restrictions and rapid shifts in competing LPWAN technology adoption. Forecasts reflect assumptions documented through primary and secondary research, acknowledging inherent market uncertainties. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Optical Communications Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market