
 Nano GPS Chipset Market | 2026-2036
Nano GPS Chipset Market Size, Share, and Industry Trends Forecast 2026-2036
Nano GPS Chipset Market Outlook
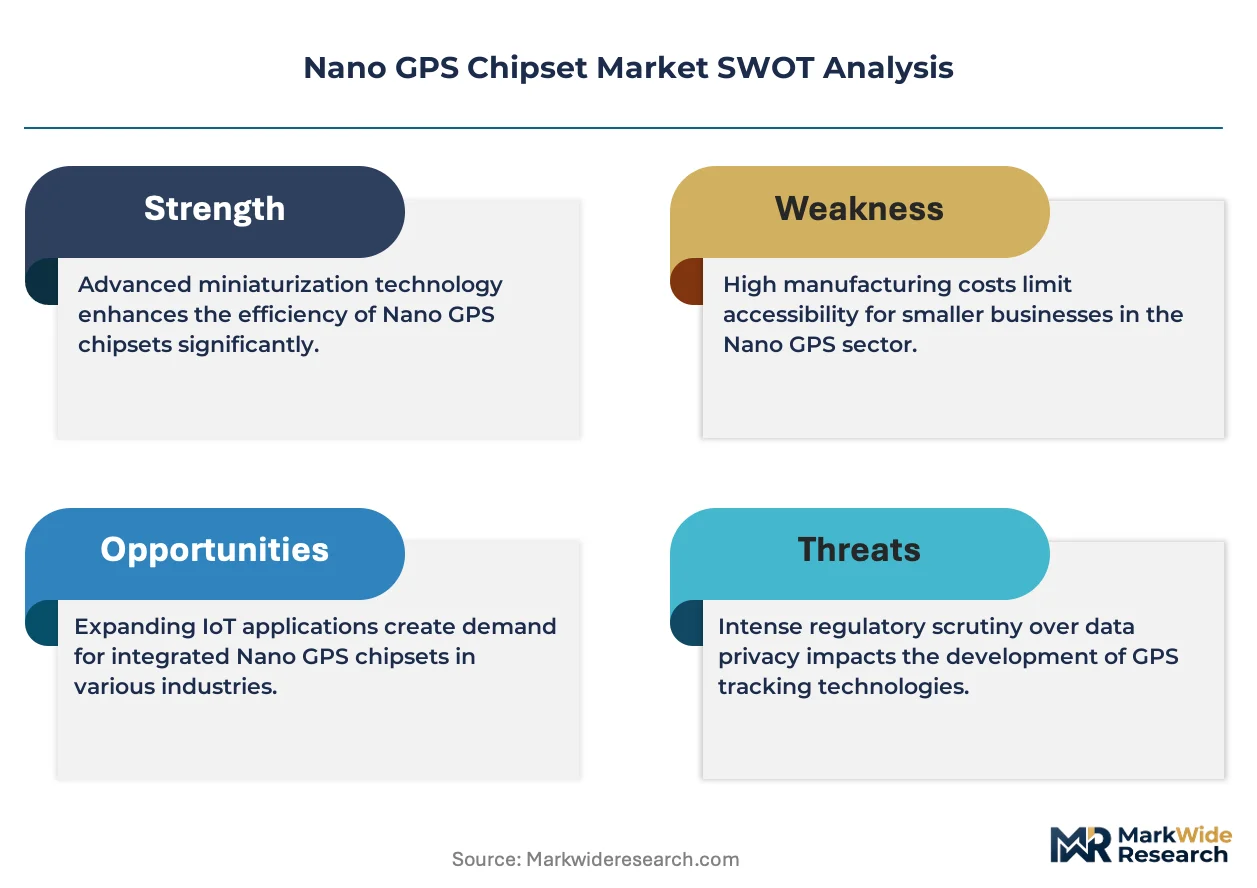
Multi-sourced fabless design partnerships is expanding across the nano GPS chipset supply base as foundry capacity constraints ease. Qualcomm leverages its Snapdragon platform integration to dominate premium smartphone sockets. STMicroelectronics sustains European automotive certification leadership through its ASIL-compliant manufacturing lines. u-blox anchors industrial IoT positioning with specialized dead-reckoning firmware stacks.
A nano GPS chipset integrates radio frequency front-end, baseband processor, and memory into a sub-5mm² die footprint, typically fabricated on 40nm or 22nm CMOS processes with sensitivity thresholds below -160 dBm for indoor signal acquisition. The component enables meter-to-decimeter positioning accuracy for battery-constrained mobile and vehicular platforms. Embedded chip configurations command the deepest margin pools as automotive tier-ones demand system-in-package integration with microcontrollers and power management units. Consumer electronics applications for personal tracking and wearables represent the fastest-growing volume segment, though unit economics remain compressed by handset OEM procurement leverage.
FCC Part 15 emissions rules in the United States, ETSI EN 303 413 for Galileo receiver performance in Europe, and Japan's MIC radio equipment regulations collectively shape chipset certification timelines and frequency band support requirements. REACH substance restrictions on lead-free solder interfaces add material compliance costs for European-bound shipments. Stakeholders must monitor evolving multi-constellation mandates from regulators and prioritize software-defined radio architectures that accommodate future satellite signals without silicon respins.
Market Dynamics
Automotive OEM procurement leverage is compressing chipset margins while mandating ASIL-D functional safety integration, forcing fabless suppliers to absorb certification costs or cede socket access to vertically integrated semiconductor houses with captive foundry relationships.
Growth Catalysts
- EU Radio Equipment Directive:Galileo compatibility mandates for devices sold in member states are accelerating multi-constellation chipset refreshes across consumer electronics and automotive verticals.
- Lane-level positioning accuracy:Advanced driver-assistance systems in premium vehicles require decimeter-precision dead-reckoning capabilities that legacy GPS architectures cannot deliver.
- Munich-Stuttgart corridor:Germany's automotive semiconductor cluster concentrates tier-one telematics control unit demand, creating localized pull for system-in-package integration expertise.
Market Restraints
- 22nm CMOS foundry allocation:Leading-edge RF process nodes face capacity rationing from smartphone AP and 5G modem demand, extending lead times for GPS-specific tape-outs.
- REACH substance compliance:Lead-free solder interface requirements add material validation costs for European-bound shipments, disproportionately burdening smaller fabless players.
- Indoor signal acquisition physics:Sensitivity thresholds below -160 dBm demand exotic RF front-end architectures that trade power consumption for performance in battery-constrained wearables.
Strategic Opportunities
- Software-defined radio architectures:Field-programmable RF paths enable satellite signal protocol updates without silicon respins, extending chipset commercial lifecycles.
- Industrial IoT asset tracking:Unmonitored freight containers and agricultural equipment represent underpenetrated volume pools with less stringent certification burdens than automotive.
- Japan MIC radio equipment regulations:QZSS augmentation mandates create regional product differentiation opportunities for suppliers with L-band signal processing capabilities.
Industry Challenges
- RF-baseband co-design talent scarcity:The intersection of millimeter-wave analog expertise and digital signal processing algorithm development commands premium compensation in Munich, San Diego, and Hsinchu hiring markets.
- Multi-constellation certification matrix:Simultaneous GPS, GLONASS, Galileo, and BeiDou validation protocols extend time-to-revenue by 8-14 months for new chipset introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano GPS Chipset Market |
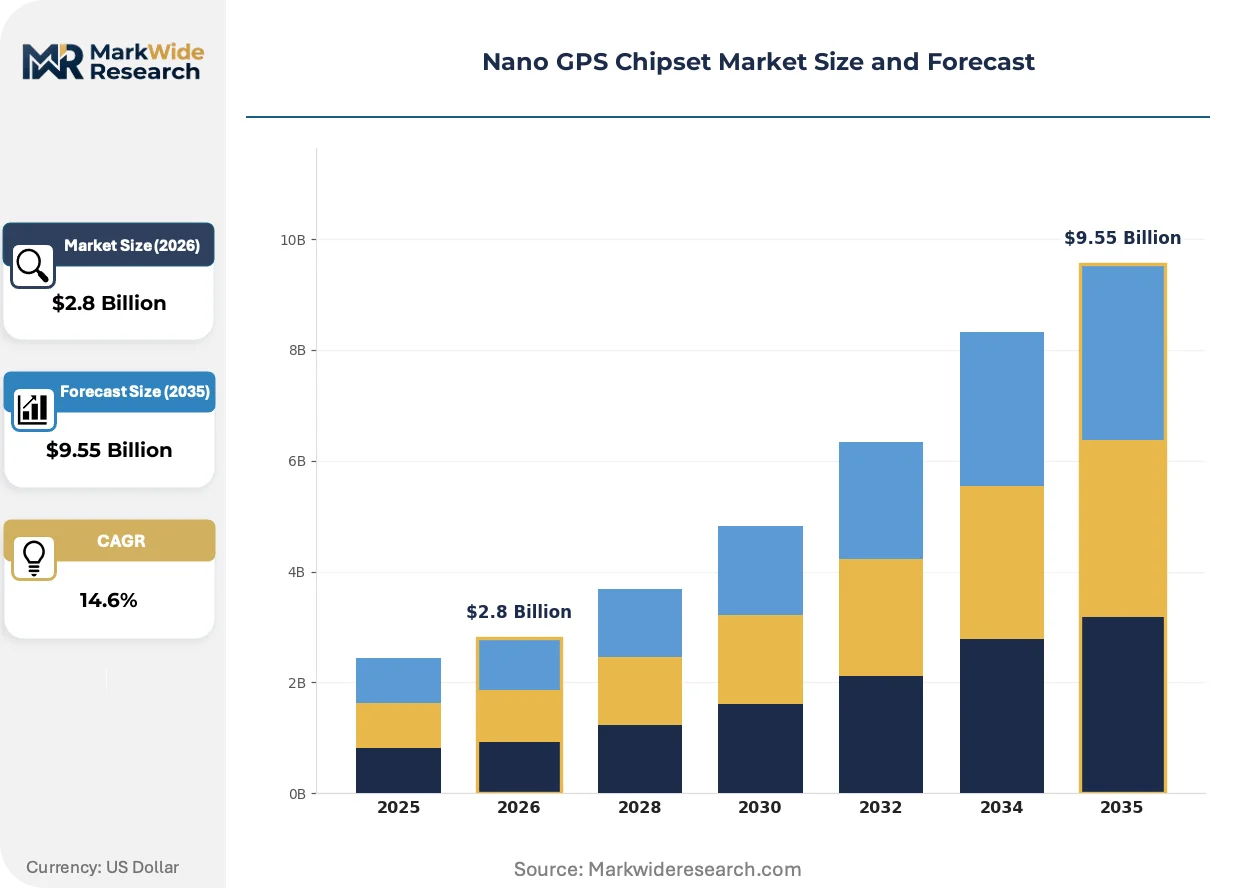
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Chip, Embedded Chip, Module, Receiver End User: Consumer Electronics, Automotive, Aerospace, Healthcare Technology: Assisted GPS, Differential GPS, Global Navigation Satellite System, Control Techniques Application: Asset Tracking, Fleet Management, Navigation, Personal Tracking |
| Companies Covered | Qualcomm, Broadcom, STMicroelectronics, MediaTek, u-blox, Skyworks Solutions, OriginGPS, Analog Devices, Fujitsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano GPS Chipset Market Strategic Shifts
Silicon integration density and regulatory multi-constellation mandates are jointly redefining competitive position in nano GPS chipset supply, favoring architectural approaches that decouple hardware from protocol evolution.
Dual-frequency L1/L5 reception is overtaking single-band architectures in automotive and precision agriculture segments. Tier-one telematics suppliers in Germany and Japan have standardized on ionospheric-error-corrected positioning for lane-keeping systems. This technology compression is marginalizing chipset vendors without L5 signal chain IP.
ETSI EN 303 413 Galileo receiver performance standards in Europe are tightening adjacent-band rejection specifications. The regulation forces RF front-end redesigns that trade die area for selectivity, particularly impacting cost-optimized consumer electronics sockets. Automotive OEMs in Stuttgart and Wolfsburg are responding by consolidating procurement around suppliers with pre-certified reference designs.
Specification-driven procurement now dominates automotive tier-one sourcing, displacing component-centric vendor selection. Buyers issue system-level positioning performance guarantees that push integration risk onto chipset suppliers. This behavioral shift is most pronounced in Germany's automotive corridor, where OEMs demand end-to-end liability coverage for functional safety failures.
Nano GPS Chipset Market Segmentation
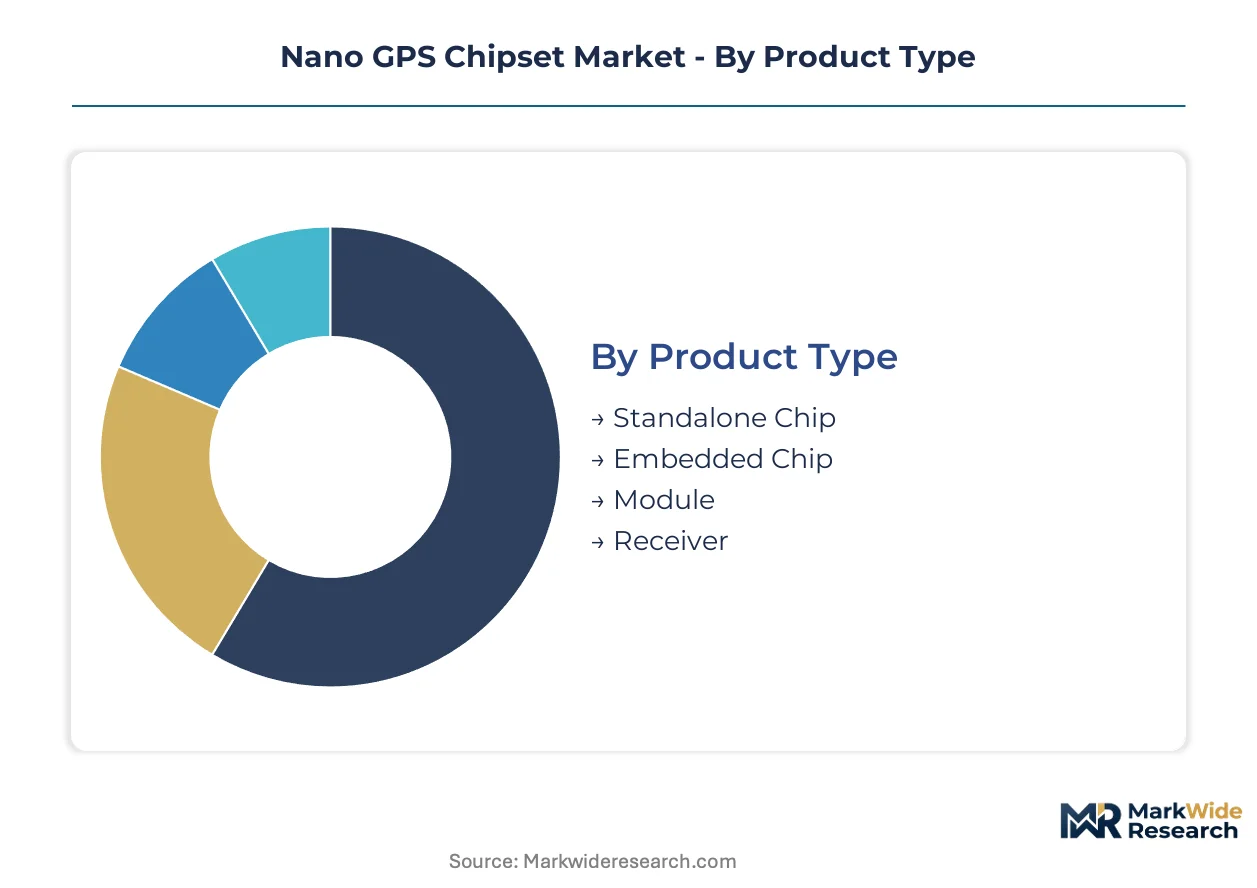
Nano GPS chipset segmentation reveals how technical architecture, buyer procurement power, and regulatory certification burdens fragment commercial opportunity across discrete pockets of value. Understanding these divides exposes where margin pools concentrate versus where volume scales.
Product Type:
Embedded configurations dominate automotive procurement, while standalone devices serve cost-optimized consumer applications with minimal integration requirements.
- Standalone Chip:Discrete RF-baseband die requiring external memory and power management. Consumer wearables manufacturers in Shenzhen and Taipei source these for rapid product cycles unconstrained by automotive qualification timelines.
- Embedded Chip:System-in-package integration with microcontrollers and PMICs. Tier-one telematics suppliers around Stuttgart and Wolfsburg mandate this architecture for ASIL-D functional safety compliance in lane-keeping systems.
- Module:Pre-certified RF subsystem with antenna matching networks. Industrial IoT deployers favor these for shortened time-to-market in freight container tracking.
- Receiver:Complete positioning subsystem including firmware stacks. Precision agriculture OEMs specify these for ionospheric-error-corrected L1/L5 reception.
Embedded chip configurations lead volumes today; standalone chips are gaining share fastest in wearables.
End User:
Certification intensity and procurement scale separate buyers, with automotive demanding liability coverage that consumer electronics will not fund.
- Consumer Electronics:Smartphone, wearable, and personal tracker OEMs drive the steepest volume expansion. Handset procurement leverage compresses unit economics to sub-dollar levels at million-unit scale.
- Automotive:OEMs and tier-one telematics suppliers concentrate demand in Germany, Japan, and the US. FCC Part 15, ETSI EN 303 413, and Japan MIC regulations mandate multi-constellation compatibility with 8-14 month validation cycles.
- Aerospace:Unmanned aerial systems and commercial aviation applications require DO-160G environmental qualification. Dual-frequency architectures penetrate this segment for ionospheric correction at altitude.
- Healthcare:Remote patient monitoring and emergency response wearables demand sub-milliwatt power budgets. FDA device classification adds regulatory overhead distinct from FCC emissions rules.
Automotive leads volumes today; consumer electronics is expanding most quickly.
Technology:
Signal processing sophistication determines where accuracy premiums command viable pricing versus commoditized positioning.
- Assisted GPS:Network-supplied ephemeris and almanac data accelerate time-to-first-fix. Cellular-connected automotive telematics and smartphone platforms deploy this ubiquitously.
- Differential GPS:Real-time kinematic correction enables centimeter-level accuracy for precision agriculture and surveying. Base station infrastructure requirements limit deployment to developed agricultural economies.
- Global Navigation Satellite System:Multi-constellation reception across GPS, GLONASS, Galileo, and BeiDou. EU Radio Equipment Directive mandates now require this capability for European market access.
- Control Techniques:Adaptive signal processing for multipath rejection and interference mitigation. Urban canyon navigation in dense metropolitan environments drives adoption.
Assisted GPS leads volumes today; differential GPS is climbing the fastest in precision agriculture.
Application:
Use case durability and tracking continuity requirements separate pricing power between intermittent consumer location and mission-critical fleet operations.
- Asset Tracking:Unmonitored freight containers and agricultural equipment represent underpenetrated volume pools. Battery life measured in years outweighs positioning accuracy for this buyer set.
- Fleet Management:Commercial vehicle operators in North America and Europe mandate ELD compliance with real-time location reporting. Telematics service providers bundle hardware with subscription revenue models.
- Navigation:In-dash and smartphone mapping applications demand lane-level accuracy for highway guidance. Dual-frequency L1/L5 reception is displacing legacy single-band architectures.
- Personal Tracking:Child safety devices, elderly fall detection, and pet locators drive consumer volume. Sub-5mm² die footprints enable integration into jewelry-form-factor hardware.
Navigation leads volumes today; asset tracking is gaining share fastest in industrial IoT.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping nano GPS chipset procurement as automotive OEMs migrate system-in-package integration toward jurisdictions with streamlined multi-constellation certification pathways. Cost-of-compliance gaps between Europe's ETSI EN 303 413 validation cycles and Asia-Pacific foundry ecosystems are accelerating design center relocation.
United States
FCC Part 15 emissions rules govern RF front-end architectures for smartphone and automotive telematics platforms. The NHTSA mandates ELD compliance for commercial vehicle operators, driving dual-frequency L1/L5 chipset penetration. San Diego anchors premium mobile socket design activity through fabless RF-baseband specialists with Snapdragon platform integration expertise.
Germany
The KBA enforces ASIL-D functional safety standards for lane-keeping systems in premium vehicles. EU Radio Equipment Directive Galileo compatibility mandates extend validation timelines by 8-14 months for non-compliant suppliers. Stuttgart and Wolfsburg concentrate tier-one telematics control unit demand, where OEMs consolidate procurement around pre-certified reference designs.
Japan
METI oversees MIC radio equipment regulations mandating QZSS augmentation for domestic market access. These L-band signal processing requirements create regional product differentiation opportunities. Nagoya and Tokyo host precision agriculture OEMs specifying ionospheric-error-corrected positioning for automated cultivation equipment.
China
MIIT coordinates GB standards for BeiDou constellation compatibility in consumer electronics and automotive platforms. Domestic foundry capacity on 22nm CMOS nodes supports rapid tape-out cycles for wearables manufacturers. Shenzhen and Shanghai concentrate handset OEM procurement leverage compressing unit economics to sub-dollar levels at million-unit scale.
South Korea
The MFDS regulates medical device classifications for remote patient monitoring wearables with distinct RF emissions requirements from FCC rules. Seoul Capital Area hosts semiconductor houses with captive foundry relationships absorbing ASIL certification costs. Busan-Ulsan corridor supports industrial IoT asset tracking deployments for unmonitored freight containers.
Nano GPS Chipset Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined radio architectures that decouple hardware from protocol evolution. The vendor base stratifies across three tiers: vertically integrated semiconductor houses with captive foundry relationships, fabless specialists with ASIL-compliant manufacturing partnerships, and module-level integrators serving shortened time-to-market requirements. Strategic archetypes include platform-integrated RF specialists, automotive certification leaders, and industrial IoT positioning anchors. Dominant competitive moves center on multi-constellation certification pre-qualification and system-in-package integration expertise acquisition.
Within the platform-integrated tier, Qualcomm and MediaTek represent fabless design houses leveraging smartphone application processor dominance to secure premium mobile sockets. STMicroelectronics anchors European automotive certification leadership through ASIL-compliant manufacturing lines. u-blox exemplifies the industrial IoT positioning specialist archetype with dedicated dead-reckoning firmware capabilities.
| Leading Market Players |
|---|
| Qualcomm |
| Broadcom |
| STMicroelectronics |
| MediaTek |
| u-blox |
| Skyworks Solutions |
| OriginGPS |
| Analog Devices |
| Fujitsu |
| Others |
Value Chain & Pricing Dynamics
ASIL-D certification tiers bifurcate the nano GPS chipset landscape into premium automotive sockets and commoditized consumer electronics, with Stuttgart-based tier-one suppliers commanding system-in-package integration at margins threefold above Shenzhen wearables manufacturers sourcing standalone dies. This tier divergence manifests in procurement leverage: automotive OEMs demand end-to-end liability coverage that forces fabless vendors to absorb 8-14 month validation costs, while handset OEMs compress unit economics through million-scale direct sourcing that eliminates distributor layers entirely.
Pricing Analysis
Distributor margins of 12-18% separate module-level integrators from direct-to-OEM automotive contracts that trade volume commitments for 22-30% price discounts. Three-tier pricing structure across ASIL-D automotive, industrial IoT, and consumer wearables segments reflects certification grade and volume scale as primary differentiation drivers. Cost compression in consumer sockets intensifies because 22nm CMOS foundry allocation faces rationing from smartphone AP demand. Handset OEMs exhibit extreme price sensitivity; automotive telematics suppliers prioritize functional safety over unit cost.
Supply Chain Analysis
RF-baseband co-design talent scarcity in Munich, San Diego, and Hsinchu constrains fabless vendor expansion even as Taiwan, South Korea, and China concentrate 22nm CMOS foundry capacity. Raw material dependencies span gallium arsenide substrates, high-purity silicon wafers, and lead-free solder interfaces mandated by REACH. Single-source vulnerability concentrates in TSMC's leading-edge RF process nodes. Distribution runs through tier-one telematics suppliers in Germany and module integrators serving industrial IoT deployers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nano GPS chipset market represents a late-cycle quality story where lane-level positioning accuracy mandates are shifting procurement toward dual-frequency L1/L5 architectures that command sustained margin premiums over legacy single-band alternatives.
For Market Incumbents: Extend ASIL-D certification leadership by acquiring specialized dead-reckoning firmware stacks from industrial IoT specialists before emerging entrants replicate u-blox's positioning. Consolidate system-in-package integration expertise through backward integration into microcontroller partnerships that captive foundry relationships enable. Defend against Qualcomm's Snapdragon platform dominance by embedding Galileo pre-certification into reference designs before EU Radio Equipment Directive enforcement tightens.
For New Entrants and Emerging Players: Industrial IoT module integrators represent the most penetrable channel partner type for circumventing automotive certification barriers that exclude fabless startups. Target unmonitored freight container tracking and precision agriculture equipment where battery-life specifications outweigh functional safety requirements. Pursue white-label module supply agreements with telematics service providers bundling hardware with subscription revenue models.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-constellation certification matrices extend time-to-revenue beyond 14 months for capital-constrained fabless vendors. Long-term viability favors vertically integrated semiconductor houses with captive foundry relationships absorbing compliance costs. Acquisition target archetype: industrial IoT positioning specialists with L-band signal processing IP and established Japan MIC regulatory relationships. Watch QZSS augmentation mandate enforcement as inflection indicator for regional product differentiation value.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Certification Pre-Qualification | ETSI EN 303 413 compliance secures EU market access before competitor tape-outs complete. |
| System-in-Package Integration Acquisition | ASIL-D manufacturing partnerships in Stuttgart corridor anchor automotive socket retention. |
| Software-Defined Radio Architecture Development | Field-programmable RF paths extend commercial lifecycles without silicon respin costs. |
| Industrial IoT Channel Partnership | Freight container tracking modules bypass automotive validation timeline constraints. |
| Dual-Frequency L1/L5 Signal Chain Investment | Ionospheric-error-corrected positioning satisfies tier-one telematics supplier specifications. |
Study Parameters
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each market's automotive tier-one procurement officers, fabless RF-baseband engineering directors, industrial IoT telematics service providers, and semiconductor foundry account managers. Secondary validation draws from FCC Part 15 filings, ETSI EN 303 413 certification databases, Japan MIC radio equipment registrations, MIIT GB standards publications, and SEC 10-K semiconductor segment disclosures. Bottom-up vendor shipment aggregation triangulates against top-down automotive telematics control unit production estimates.
Granularity-level modeling disaggregates volumes across embedded chip, standalone chip, module, and receiver product types; consumer electronics, automotive, aerospace, and healthcare end users; and Assisted GPS, Differential GPS, GNSS, and Control Techniques technology tiers. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs include foundry capacity allocation disclosures, OEM platform production schedules, and regulatory mandate implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to 22nm CMOS foundry capacity rationing, EU Radio Equipment Directive enforcement timing, and QZSS augmentation mandate adoption. Forecasts reflect documented assumptions regarding multi-constellation certification cycle durations and automotive OEM procurement consolidation behavior. Material deviation in foundry allocation priorities or regulatory implementation schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Nano GPS Chip Market