
 Global Application Specific Communications Analog IC Market | 2026-2036
Global Application Specific Communications Analog IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Specific Communications Analog IC Market Foresight
Gallium nitride is hardening cost-performance tradeoffs in RF power amplifiers, displacing legacy LDMOS in base station transmitters. Texas Instruments leverages its 300-millimeter analog fab network to sustain cost leadership in precision voltage regulators for 5G massive MIMO arrays. Analog Devices anchors its position through in-house production of high-linearity mixers and modulators for military radios. Infineon Technologies AG dominates silicon germanium BiCMOS processes for millimeter-wave automotive radar crossovers into communications infrastructure.
Application specific communications analog ICs are mixed-signal integrated circuits engineered for targeted RF and baseband processing functions, typically fabricated in CMOS, BiCMOS, or compound semiconductor processes with operating frequencies spanning sub-gigahertz to millimeter-wave bands. These devices integrate amplifiers, filters, and voltage regulators with specialized linearity and noise specifications to enable signal conditioning in wireless transmission chains. Amplifiers and modulators capture the largest margin pools as 5G massive MIMO deployments scale, while filters and oscillators face accelerating competition from digital synthesis in IoT networks. CMOS and SiGe technologies lead volume production, though GaAs and LDMOS retain defensive positions in high-power satellite uplink and military radar applications where thermal performance dictates material selection.
The FCC in the United States enforces emission masks and spectrum allocation rules that directly shape amplifier linearity requirements and filter rolloff specifications for domestic infrastructure. ETSI and the EU AI Act collectively impose cybersecurity and supply chain transparency mandates on network equipment deployed across European member states, compelling chip vendors to document provenance through REACH-aligned material declarations. China's MIIT and GB standards govern domestic 5G base station certification, creating parallel compliance pathways that fragment qualification costs for multinational suppliers. Stakeholders must monitor how divergent spectrum auction timelines between the FCC, Ofcom, and Japan's MIC reshape regional demand cycles for RF front-end components.
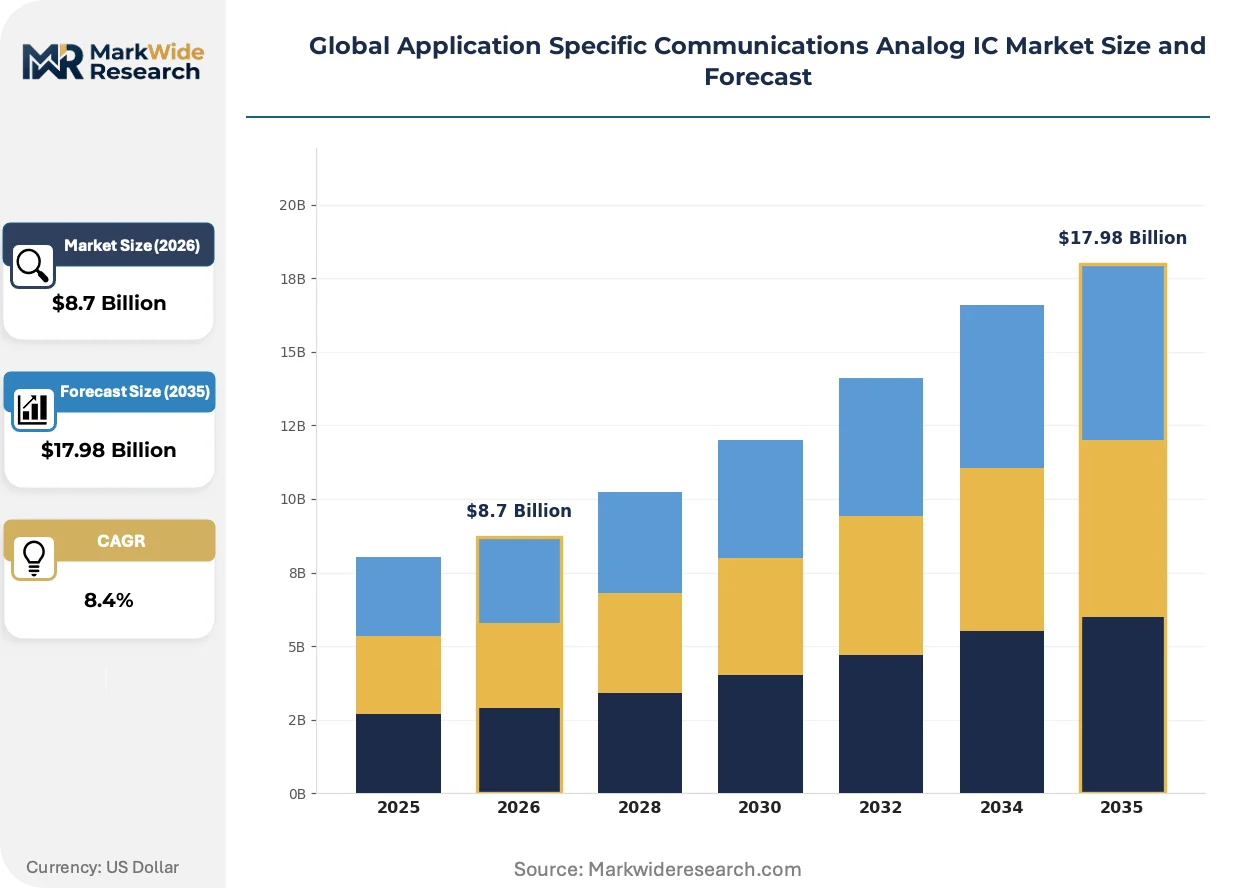
Market Dynamics
GaN-on-SiC substrates are compressing cost-performance curves in RF power amplifiers, forcing legacy LDMOS foundries to retool or exit base station transmitter markets entirely. This material transition concentrates bargaining power among three compound semiconductor substrate suppliers.
Growth Catalysts
- EU AI Act cybersecurity mandates:Network equipment vendors must document chip-level provenance, creating captive demand for traceable RF front-end modules across German and French telecom infrastructure.
- Low-earth orbit ground station buildouts:Satellite operators in Japan and Germany are procuring specialized millimeter-wave chipsets for gateway terminals, pulling GaAs and GaN components through qualified supply chains.
- Silicon germanium BiCMOS scaling:Automotive radar process crossovers into 5G infrastructure are reducing non-recurring engineering costs for millimeter-wave transceiver designs.
Market Restraints
- Substrate supply concentration:GaN-on-SiC epitaxial wafer production clusters in U.S. and Japanese facilities, exposing buyers to single-source risk during capacity constraints.
- REACH material compliance:ECHA restrictions on gallium and indium compounds force costly redesigns of high-frequency amplifiers, extending qualification timelines by 8-14 months.
- Digital synthesis substitution:Software-defined radio architectures in IoT endpoints are displacing discrete filter and oscillator ICs below 6 GHz.
Strategic Opportunities
- South Korean defense-foundry partnerships:Local IDMs are qualifying RF components for military radios under offset agreements, creating captive demand insulated from commercial pricing cycles.
- India PLI scheme localization:Telecom infrastructure incentives are attracting analog IC packaging and test investments for 5G base station supply chains.
- GaN-SiC thermal convergence:Combining wide-bandgap power devices with advanced substrate cooling is enabling integrated transmit-receive modules for phased array antennas.
Industry Challenges
- Compound semiconductor talent scarcity:GaN HEMT process engineering expertise concentrates in legacy defense contractors and IDMs, constraining foundry expansion.
- Multi-standard certification complexity:Parallel FCC, ETSI, and MIIT qualification pathways for 5G massive MIMO amplifiers fragment engineering resources and delay revenue recognition.
- Legacy LDMOS inventory stranding:Base station OEMs face write-downs on qualified but obsolete amplifier stock as GaN penetration accelerates in macro cell deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Specific Communications Analog IC Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amplifiers, Modulators, Filters, Comparators, Voltage Regulators, Oscillators Technology: CMOS, Bipolar, BiCMOS, GaAs, SiGe, LDMOS Application: Mobile Infrastructure, Satellite Communication, Military Radios, IoT Networks, Wireless Sensor Networks, Emergency Communications End User: Telecom Operators, Defense Contractors, Network Equipment Providers, IoT Solution Developers, Wireless System Integrators, Broadcast Service Providers |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Inc., Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Renesas Electronics Corporation, Microchip Technology Inc., Skyworks Solutions Inc., Onsemi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Specific Communications Analog IC Market Shifts & Advancements
RF front-end integration is compressing discrete component counts while widening the performance gap between integrated and modular architectures. Three forces are actively restructuring competitive positioning in analog communications ICs.
Monolithic microwave integrated circuits fabricated in silicon germanium BiCMOS are unifying LNA, mixer, and VGA functions for millimeter-wave 5G receivers. Base station OEMs in South Korea and Taiwan are qualifying these designs for massive MIMO arrays, displacing multi-chip GaAs modules. This integration is compressing bill-of-materials costs while tightening linearity specifications that only IDMs with captive BiCMOS capacity can meet.
ETSI cybersecurity certification under the EU AI Act is mandating hardware-level secure boot and side-channel resistance in network equipment RF subsystems. European telecom operators now require documented silicon provenance through REACH-aligned material declarations, disqualifying second-source suppliers without qualified foundry partnerships. German and French infrastructure tenders are most affected, with vendors absorbing 12-18 month requalification cycles.
Defense contractors are consolidating RF component procurement through single-source IDM relationships rather than distributor channels. This disintermediation concentrates volume with vendors offering in-house GaN HEMT and SiGe BiCMOS fabrication, squeezing fabless competitors out of military radio and radar programs. The shift is most visible in Taiwan and South Korea, where foundry partnerships with domestic defense primes are accelerating.
Global Application Specific Communications Analog IC Market Segmentation
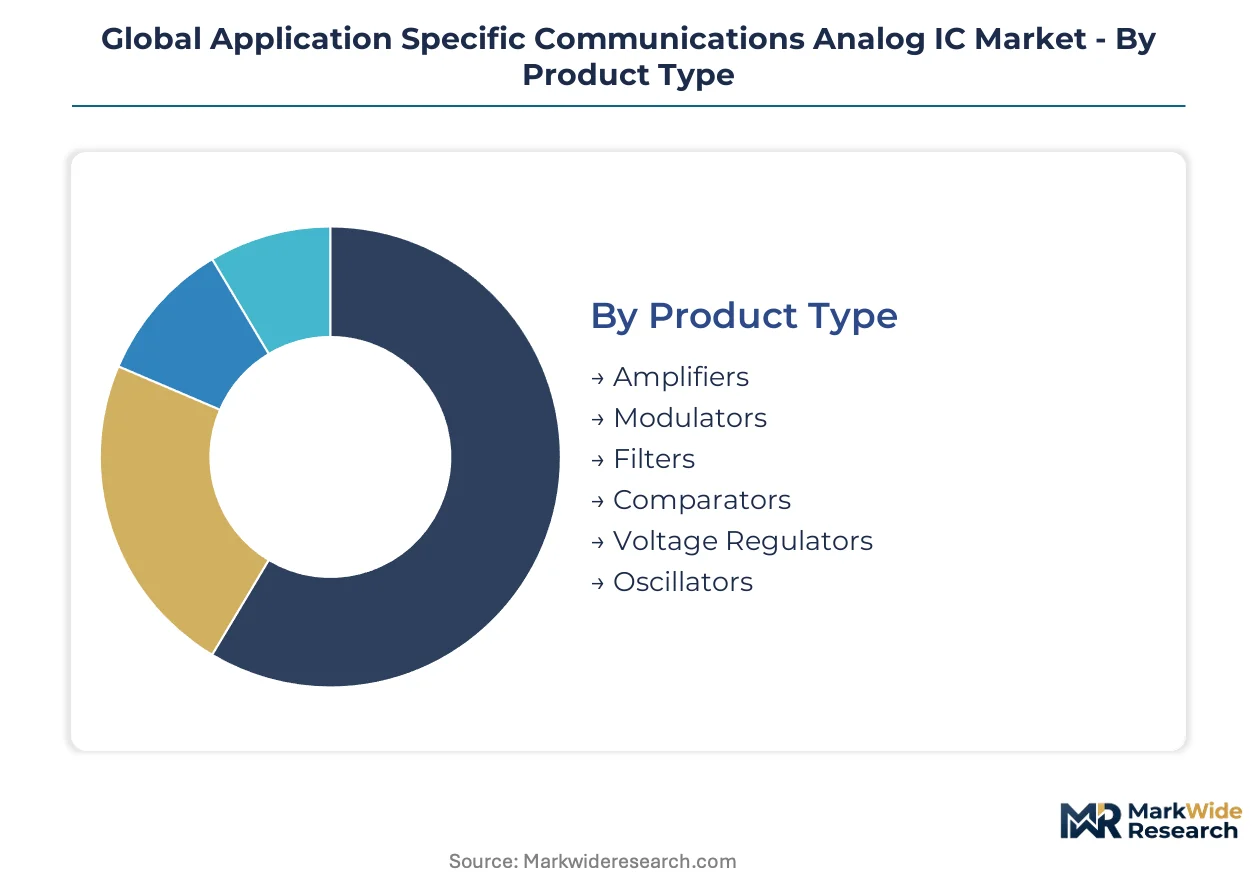
Application specific communications analog ICs fragment across four structural dimensions that shape procurement patterns and margin capture. Product type and technology selections determine foundry partnerships and qualification pathways, while application and end-user specifications dictate compliance regimes and volume scaling trajectories.
Product Type:
Customization intensity varies from catalog-standard voltage regulators to fully specified amplifiers with proprietary linearity curves.
- Amplifiers:RF power amplifiers and low-noise amplifiers dominate bill-of-materials in 5G massive MIMO arrays. South Korean base station OEMs are qualifying GaN-on-SiC variants for macro cell transmitters, though REACH gallium restrictions are extending qualification timelines.
- Modulators:Quadrature modulators and direct-conversion mixers integrate with digital predistortion engines in software-defined radios. Taiwan's network equipment providers are consolidating procurement through single-source IDM relationships for millimeter-wave variants.
- Filters:Surface acoustic wave and bulk acoustic wave devices face displacement below 6 GHz from digital synthesis in narrowband IoT endpoints.
- Comparators:High-speed voltage comparators enable clock recovery in optical communication front-ends with sub-nanosecond propagation delays.
- Voltage Regulators:Low-dropout and switching regulators for RF subsystems emphasize noise spectral density specifications below 10 µVrms.
- Oscillators:Voltage-controlled oscillators and temperature-compensated crystal oscillators face margin compression from silicon MEMS timing alternatives in consumer IoT.
Most installed capacity flows through Amplifiers. Expansion is steepest in Modulators.
Technology:
Process selection maps directly to frequency-power tradeoffs and thermal management requirements.
- CMOS:Bulk and SOI CMOS processes dominate sub-6 GHz transceivers with integrated digital calibration. Foundry capacity in Taiwan supports cost-optimized production for IoT network endpoints.
- Bipolar:Complementary bipolar processes retain defensive positions in precision analog functions where noise figure outweighs integration density.
- BiCMOS:Silicon germanium BiCMOS unifies RF and analog functions at millimeter-wave frequencies. Infineon's in-house 130-nanometer SiGe capacity anchors European supply for automotive radar crossovers into communications infrastructure.
- GaAs:Gallium arsenide pHEMT and HBT processes defend high-frequency, medium-power applications in satellite uplink amplifiers.
- SiGe:Pure silicon germanium processes without bipolar CMOS integration target specialized low-noise amplifier applications.
- LDMOS:Laterally diffused metal-oxide-semiconductor processes face accelerating displacement by GaN in base station transmitters above 3.5 GHz.
Volume concentrates in CMOS. Technology transitions are most active in BiCMOS.
Application:
Deployment environments span controlled terrestrial infrastructure to orbital and contested electromagnetic spectrum operations.
- Mobile Infrastructure:5G massive MIMO and small cell deployments consume precision voltage regulators and high-linearity amplifiers. German and Japanese telecom operators are expanding procurement for sub-6 GHz and millimeter-wave arrays.
- Satellite Communication:Low-earth orbit ground stations in Japan and Germany are pulling specialized millimeter-wave chipsets through qualified supply chains with extended temperature ranges.
- Military Radios:Software-defined radio platforms mandate secure boot capabilities and documented silicon provenance under EU AI Act cybersecurity mandates.
- IoT Networks:Narrowband-IoT and LoRa endpoints prioritize cost-optimized CMOS integration with relaxed linearity specifications.
- Wireless Sensor Networks:Ultra-low-power requirements favor sub-threshold CMOS designs with aggressive duty cycling.
- Emergency Communications:Public safety networks require hardened specifications with interoperability certification across FCC and ETSI bands.
Revenue scales through Mobile Infrastructure. Application expansion is most rapid in Satellite Communication.
End User:
Procurement sophistication ranges from commodity distributor purchases to multi-year sole-source development agreements.
- Telecom Operators:Deutsche Telekom and NTT are mandating REACH-aligned material declarations and hardware-level secure boot in RF subsystem tenders.
- Defense Contractors:Single-source IDM relationships are displacing distributor channels for military radio and radar programs in Taiwan and South Korea.
- Network Equipment Providers:Samsung and Ericsson are qualifying integrated transceiver designs that compress discrete component counts.
- IoT Solution Developers:Module vendors prioritize catalog availability and second-source compatibility over performance optimization.
- Wireless System Integrators:Custom specification requirements drive captive design services from analog IC vendors.
- Broadcast Service Providers:Terrestrial and satellite broadcast infrastructure maintains demand for high-power amplifiers with strict emission mask compliance.
Contract value concentrates with Telecom Operators. Procurement growth is strongest among Defense Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's foundry ecosystem concentrates captive BiCMOS capacity for millimeter-wave transceiver integration. German telecom operators mandate REACH-aligned material declarations for RF subsystem tenders. Japanese satellite operators procure specialized GaAs and GaN chipsets for low-earth orbit ground stations.
United States
FCC emission masks and spectrum allocation rules directly shape amplifier linearity requirements for domestic 5G infrastructure. The IRA's domestic manufacturing incentives are pulling analog IC packaging investments toward Texas and Arizona. Defense contractors in the Washington-Baltimore corridor are consolidating RF procurement through single-source IDM relationships.
Germany
Deutsche Telekom's hardware-level secure boot mandates are extending qualification timelines for RF front-end modules. ECHA restrictions on gallium compounds force costly redesigns of high-frequency amplifiers. Munich-based network equipment vendors are absorbing 12-18 month requalification cycles under EU AI Act cybersecurity mandates.
Japan
NTT and KDDI are expanding procurement of millimeter-wave chipsets for satellite gateway terminals. METI's semiconductor subsidy programs are attracting GaN-on-SiC epitaxial wafer capacity investments. Yokohama's defense-industrial complex is qualifying RF components for military radios under offset agreements with domestic foundries.
South Korea
Samsung's massive MIMO array deployments consume precision voltage regulators and high-linearity GaN amplifiers. The national defense offset program is creating captive demand for RF components insulated from commercial pricing cycles. Seoul's foundry partnerships with defense primes are accelerating qualification of secure-boot-capable transceiver designs.
China
MIIT's GB standards govern domestic 5G base station certification, creating parallel compliance pathways for multinational suppliers. Yangtze River Delta foundries are scaling CMOS production for cost-optimized IoT network endpoints. Shenzhen's network equipment providers are qualifying integrated transceiver designs that compress discrete component counts.
Global Application Specific Communications Analog IC Market Competitive Landscape
Capacity expansion dominates the current landscape as compound semiconductor substrate suppliers consolidate bargaining power. The vendor base structures around three tiers: integrated device manufacturers with captive fabrication, specialized compound semiconductor foundries, and fabless design houses dependent on external qualification. Strategic archetypes include GaN HEMT process specialists, SiGe BiCMOS integrators, and precision analog catalog suppliers. M&A activity and strategic foundry partnerships represent the dominant competitive moves as vendors secure qualified supply chains.
Among US-based integrated device manufacturers, Texas Instruments Incorporated and Analog Devices, Inc. exemplify the scale-driven archetype with captive analog fabrication networks. Infineon Technologies AG anchors the European tier through in-house compound semiconductor processes. These three companies represent the consolidation vector as defense contractors and telecom operators disintermediate distributor channels for RF component procurement.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Renesas Electronics Corporation |
| Microchip Technology Inc. |
| Skyworks Solutions Inc. |
| Onsemi |
| Others |
Supply & Pricing Matrix
Sovereign-backed compound semiconductor producers in Japan and the United States anchor substrate supply for GaN-on-SiC power amplifiers, creating asymmetric pricing power that favors IDMs with captive epitaxial wafer partnerships over fabless competitors exposed to spot-market volatility.
Pricing Analysis
Input-cost pass-through from gallium and silicon carbide substrate prices shapes contract negotiations for RF power amplifiers, with three-tier pricing structure across premium, standard, and economy levels separating military-grade qualified parts from commercial base station components. Certification tier under ETSI cybersecurity mandates and REACH material declarations commands 15-25 point premiums over catalog-standard voltage regulators. Pricing pressure stems from GaN HEMT foundry expansion in Taiwan compressing margins on legacy LDMOS amplifiers. Telecom operators in Germany and Japan exhibit lowest price sensitivity due to sole-source qualification requirements, while IoT module vendors in China drive aggressive cost-down targets.
Supply Chain Analysis
Freight costs for temperature-controlled transport of GaN-on-SiC epitaxial wafers from Japanese and U.S. facilities to Taiwanese foundries add 8-12% to landed substrate costs, amplifying geographic concentration risks. Supply concentrates in Taiwan for CMOS and BiCMOS fabrication, the United States for GaN HEMT epitaxy, and Japan for SiC substrates. Raw material dependencies span high-purity gallium, silicon carbide boules, and specialized ceramic packaging compounds. Single-source vulnerability in GaN-on-SiC epitaxial wafer production exposes buyers to 6-9 month allocation delays during capacity constraints. Distribution runs through authorized distributors for commercial volumes and direct IDM relationships for defense and telecom infrastructure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU AI Act compliance costs in Germany and France versus India's PLI scheme localization incentives, creating divergent landed cost structures for equivalent RF front-end modules.
For Market Incumbents: To counter GaN HEMT foundry expansion in Taiwan eroding pricing power on legacy amplifier portfolios, Texas Instruments and Analog Devices should deepen backward integration into 300-millimeter analog fab capacity for precision voltage regulators while accelerating REACH-aligned material declaration documentation to capture Deutsche Telekom and NTT secure-boot mandates. For New Entrants and Emerging Players: Direct-to-defense-procurement channels offer the most penetrable entry vector, specifically targeting South Korean offset agreements and Indian PLI scheme packaging investments where qualification barriers favor new suppliers with clean compliance histories over incumbents burdened by legacy LDMOS inventory. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless design houses with qualified foundry partnerships but no captive fabrication, presenting acquisition targets that gain immediate margin expansion through integration with IDM substrate supply. The signal to watch is GaN-on-SiC substrate allocation announcements from Japanese producers, which would indicate inflection toward sustained supply expansion and pricing stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| GaN HEMT Process Capacity Expansion | Captures base station transmitter market share as LDMOS obsolescence accelerates across German and Japanese deployments. |
| REACH-Aligned Material Traceability Investment | Qualifies RF front-end modules for EU AI Act tenders from Deutsche Telekom and French telecom operators. |
| Defense-Foundry Partnership Formation | Creates captive demand insulated from commercial pricing cycles through South Korean and Taiwanese offset agreements. |
| SiGe BiCMOS Millimeter-Wave Integration | Compresses bill-of-materials costs for 5G massive MIMO arrays while tightening linearity specifications competitors cannot meet. |
| India PLI Scheme Localization | Establishes packaging and test footprint for cost-optimized supply to emerging 5G infrastructure markets. |
Research Methodology
Direct dialogue with RF component procurement managers at telecom operators, defense contractor supply chain directors, foundry process engineers, and semiconductor distributor account managers grounded qualitative insights, cross-referenced against FCC equipment authorization databases, ETSI cybersecurity certification registries, METI subsidy disclosure filings, and customs trade data for gallium compound imports. Bottom-up and top-down triangulation validated volume estimates across product type and technology segments.
Segment-level projections across amplifiers, modulators, filters, and voltage regulators by CMOS, BiCMOS, GaAs, and GaN process technologies fed into analytical framework spanning mobile infrastructure, satellite communication, and military radio applications. CAGRs derived from weighted average of historical capacity expansion rates and announced foundry investment timelines, incorporating GaN HEMT yield improvement curves and SiGe BiCMOS node migration patterns as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for GaN-on-Silicon substrates achieving cost parity with GaN-on-SiC would alter the outlook by fragmenting substrate supply concentration. Forecasts reflect assumptions about regulatory compliance timeline adherence and defense procurement continuity. A model refresh is warranted upon material change in FCC spectrum auction schedules or ECHA gallium compound restriction enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market