
 Bluetooth Low Energy Market | 2026-2036
Bluetooth Low Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Low Energy Market Analysis
Buyer concentration across the Bluetooth Low Energy ecosystem is broadening beyond smartphone OEMs to encompass industrial automation vendors, healthcare device manufacturers, and smart home platform operators. Nordic Semiconductor leverages its integrated protocol stack and developer tooling to sustain design-win momentum across wearable and medical segments. Texas Instruments Incorporated anchors its position through low-power RF process expertise and extensive analog integration that reduces bill-of-material complexity for IoT endpoints.
Bluetooth Low Energy denotes a wireless personal area network technology operating in the 2.4 GHz ISM band with data rates up to 2 Mbps and sub-microamp sleep currents, engineered for intermittent data transmission across battery-constrained devices. Its primary commercial purpose centers on enabling proximity-based connectivity, sensor telemetry, and control signaling without the power penalty of classic Bluetooth. Wearable Devices and Healthcare Equipment represent the most margin-attractive product categories, with the former capturing consumer volume and the latter commanding premium pricing through FDA and CE regulatory validation requirements. Mesh Networking and Location Services within the technology dimension are expanding fastest, as enterprise buyers deploy asset-tracking and indoor positioning infrastructure across manufacturing floors and logistics warehouses.
The FCC governs radio frequency emissions and equipment authorization for BLE devices marketed in the United States, while ETSI harmonizes spectrum access and electromagnetic compatibility standards across European member states. REACH and RoHS directives from the European Union constrain material composition in BLE chip packaging and module substrates, elevating compliance costs for semiconductor suppliers. Stakeholders must monitor evolving spectrum allocation debates and energy-efficiency mandates that could redefine chipset architecture priorities and certification pathways.
Market Dynamics
Healthcare providers are expanding remote patient monitoring deployments using BLE-enabled wearables, while industrial automation vendors integrate mesh networking for asset tracking across manufacturing floors. This demand diversification is compressing chipset development cycles and forcing protocol stack vendors to support concurrent medical certification and industrial reliability requirements.
Growth Catalysts
- Remote Patient Monitoring Mandates:Healthcare systems in the United States and Germany now reimburse connected diagnostic devices, accelerating FDA and CE validation pathways for BLE-enabled wearables with clinical-grade telemetry.
- ETSI Spectrum Harmonization:The European Telecommunications Standards Institute's unified electromagnetic compatibility framework reduces country-by-country certification costs for module suppliers targeting EU member states.
- Smart Manufacturing Clusters:Factory automation buyers in China, Japan, and South Korea are deploying BLE mesh infrastructure for indoor positioning and predictive maintenance on production lines.
Market Restraints
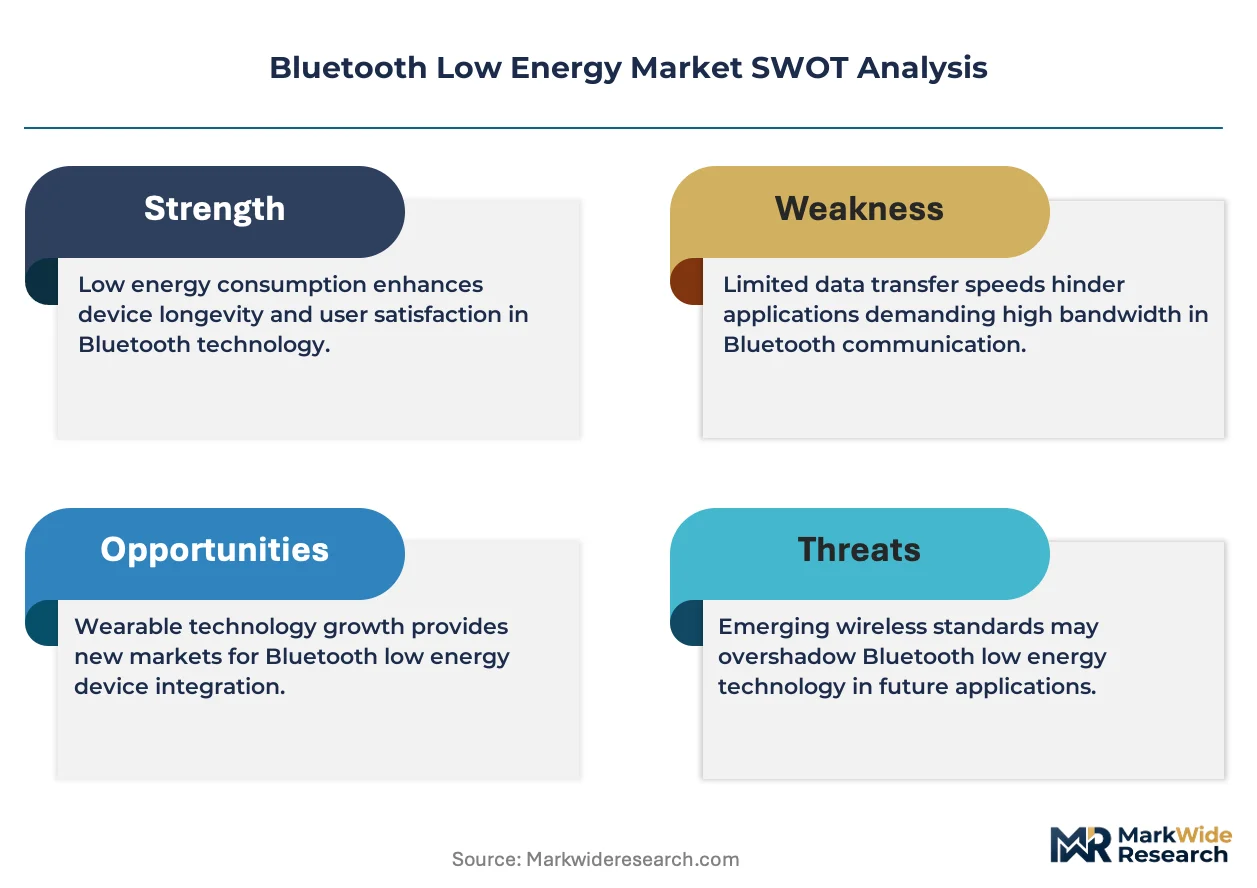
- Silicon Supply Concentration:Advanced RF process nodes for ultra-low-power BLE SoCs depend on a concentrated foundry base in Taiwan, exposing procurement timelines to geopolitical disruption.
- Input Cost Volatility:Rare earth elements in ceramic antenna substrates and lithium in coin-cell batteries face price swings that compress module margins at the low end.
- Wi-Fi HaLow Substitution:The IEEE 802.11ah standard offers comparable range with higher throughput for industrial sensor backhaul, threatening BLE's position in warehouse automation.
Strategic Opportunities
- Ambient IoT Convergence:BLE is absorbing energy-harvesting photovoltaic and piezoelectric power sources, enabling battery-free sensors for smart building and retail inventory applications.
- India PLI Incentive:India's production-linked incentive scheme for electronics manufacturing is attracting module assembly investments to serve domestic smart meter and automotive telematics demand.
- Channel Innovation via Distributors:Arrow Electronics and Avnet are building BLE developer kits with pre-certified stacks, shortening time-to-market for mid-sized OEMs without in-house RF expertise.
Industry Challenges
- RF Engineering Talent Scarcity:BLE product teams struggle to hire antenna design and protocol stack optimization specialists, particularly in markets outside established semiconductor hubs.
- Certification Timeline Compression:FCC Part 15 and ETSI EN 300 328 testing queues have lengthened, delaying product launches even for designs with proven reference implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Low Energy Market |
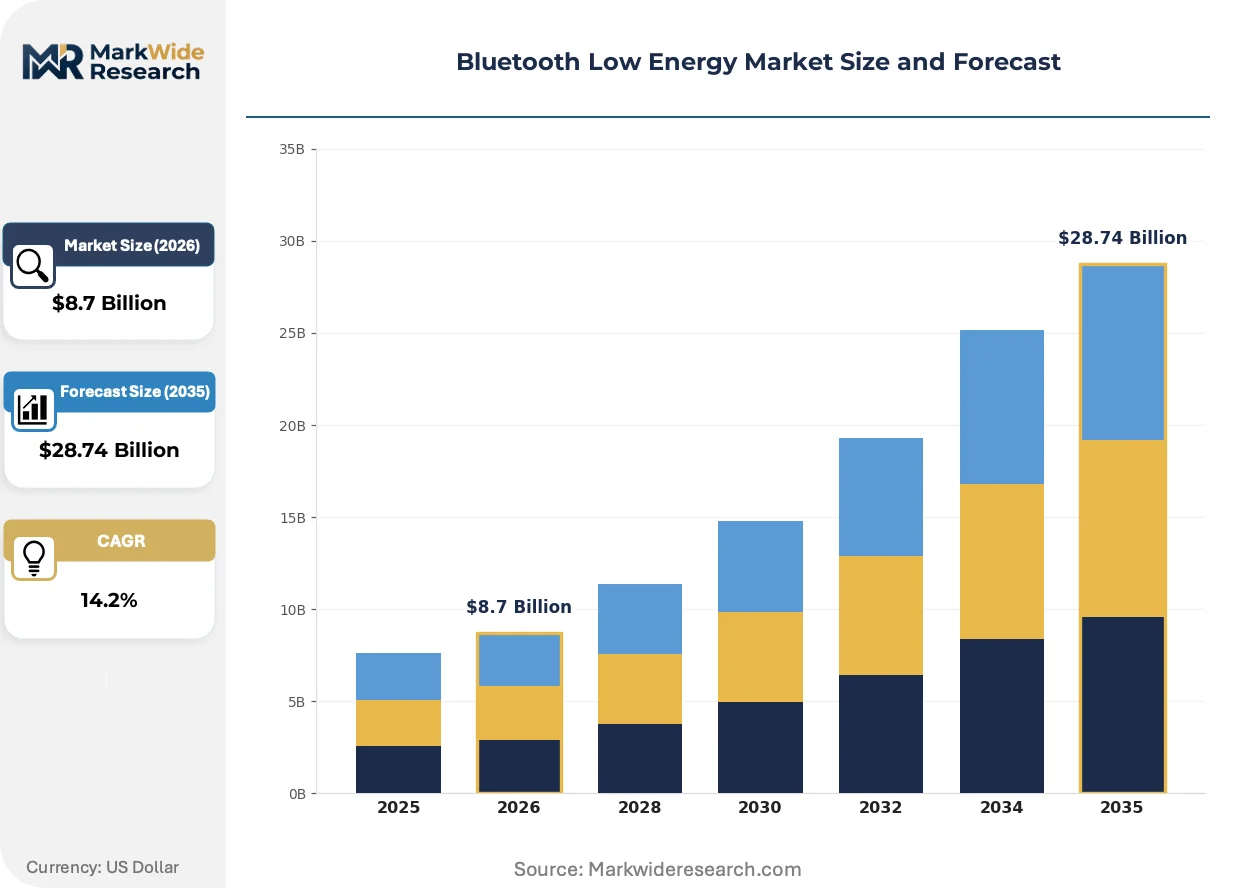
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Home Devices, Healthcare Equipment, Industrial Sensors Application: Fitness Tracking, Home Automation, Asset Management, Remote Monitoring End User: Retail, Healthcare, Manufacturing, Logistics Technology: Mesh Networking, Beacon Technology, Location Services, Wireless Charging |
| Companies Covered | Nordic Semiconductor, Texas Instruments Incorporated, Intel Corporation, STMicroelectronics, Silicon Laboratories, NXP Semiconductors, Qualcomm Incorporated, Infineon Technologies AG, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Low Energy Market Emerging Trajectories
BLE chipset architecture is converging with edge AI accelerators and energy-harvesting interfaces, transforming the technology from a simple radio into an autonomous sensor node platform. This evolution is redrawing competitive boundaries between connectivity specialists and system-level solution providers.
Bluetooth 5.4 with Periodic Advertising with Responses (PAwR) is absorbing electronic shelf label and warehouse tag applications previously served by proprietary sub-GHz protocols. Retailers in France and Germany are piloting thousand-node PAwR deployments for dynamic pricing and inventory accuracy. The structural consequence is compressing addressable market space for single-purpose RF alternatives in commercial IoT.
The EU's Radio Equipment Directive (RED) cybersecurity requirements taking effect in 2025 mandate vulnerability disclosure and secure boot capabilities for all wireless devices sold in member states. BLE module vendors must redesign firmware architectures to satisfy notified body assessments, adding engineering overhead but creating differentiation for suppliers with pre-certified security stacks. Medical and payment terminal segments are responding earliest, baking RED compliance into procurement specifications ahead of enforcement.
Industrial buyers are consolidating vendor relationships around suppliers offering combined BLE connectivity and cloud telemetry platforms, displacing component-only procurement. Automotive Tier 1s and agricultural equipment OEMs now demand turnkey sensor-to-dashboard solutions rather than discrete chipsets. This pattern is most visible in Germany and Japan, where factory automation and precision farming equipment makers prioritize integration speed over radio hardware cost.
Bluetooth Low Energy Market Segmentation
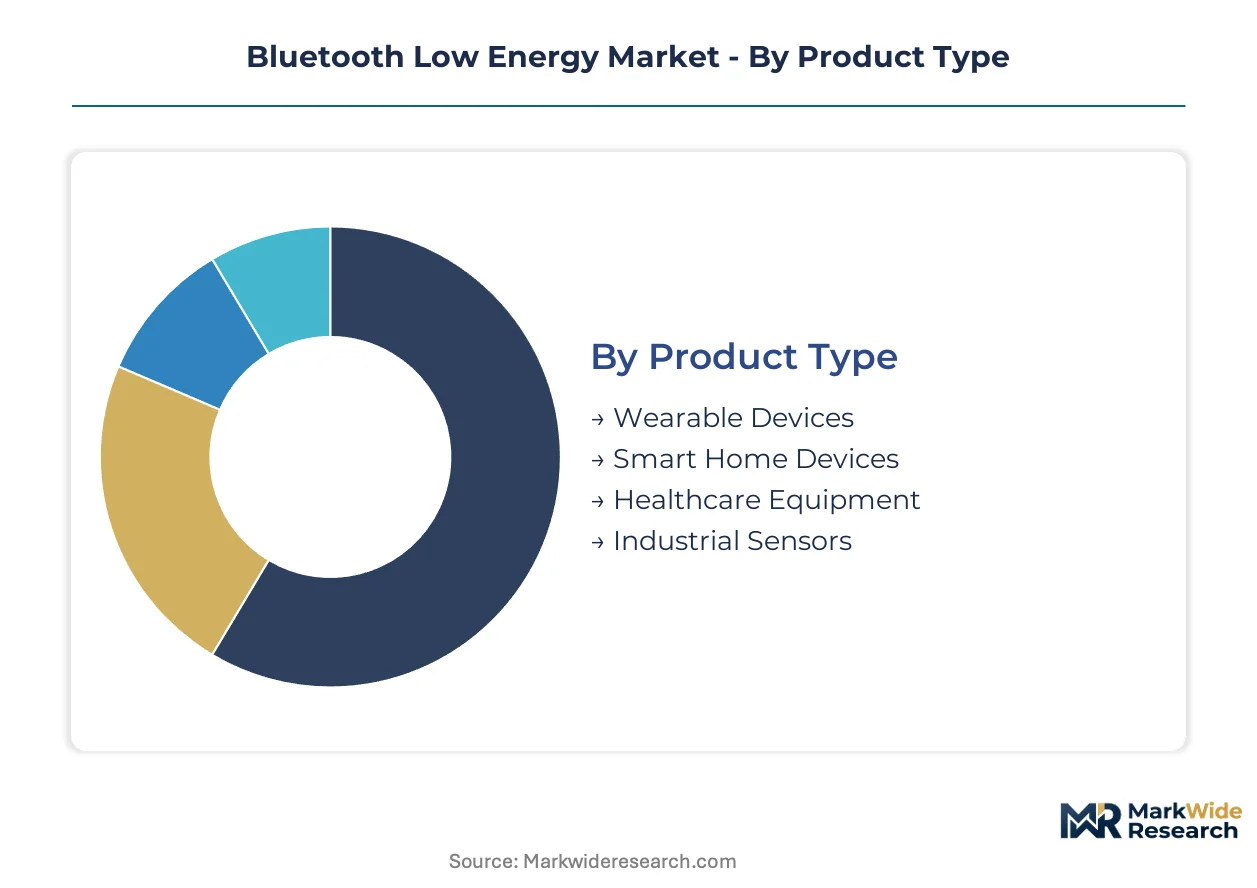
BLE market segmentation reveals distinct certification pathways and margin profiles across product categories. Regulatory requirements from FDA, FCC, and ETSI create tiered entry barriers that reshape competitive dynamics within each segment cluster.
Product Type:
FDA 510(k) clearance and FCC Part 15 certification impose divergent engineering burdens across hardware categories, with clinical-grade devices demanding multi-year validation cycles.
- Wearable Devices:Consumer wristbands and smartwatches integrate multi-protocol radios with sub-100µA sleep currents. Demand concentrates in Shenzhen and Cupertino design centers, where smartphone OEMs specify custom antenna matching for brand differentiation.
- Healthcare Equipment:Continuous glucose monitors and pulse oximeters require ISO 14155 clinical validation plus FDA 510(k) or CE MDR clearance. German hospitals and US accountable care organizations now mandate encrypted telemetry as a procurement prerequisite.
- Smart Home Devices:Thermostats and lighting controllers prioritize Matter protocol interoperability over raw RF performance.
- Industrial Sensors:Vibration and temperature nodes for predictive maintenance operate on 10-year battery targets.
Leading the category by volume: Wearable Devices. Growing fastest: Healthcare Equipment.
Application:
Application segments diverge sharply in data throughput requirements and cloud integration depth, with enterprise use cases commanding premium pricing over consumer fitness tracking.
- Asset Management:Warehouse pallet tracking and tool-crib inventory systems deploy BLE mesh with sub-meter location accuracy. DHL and Amazon fulfillment centers in Germany and Poland are consolidating vendor relationships around integrated hardware-software platforms.
- Remote Monitoring:Post-acute patient surveillance and elderly fall detection bridge clinical and consumer domains. Japan's Ministry of Health has approved reimbursement codes for BLE-enabled home monitoring, accelerating PMDA registration timelines.
- Fitness Tracking:Step counting and sleep scoring algorithms run on-device to preserve smartphone battery.
- Home Automation:Voice assistant integration drives chipset selection toward multiprotocol silicon.
Asset Management claims the highest average selling prices. Remote Monitoring is expanding most quickly.
End User:
End-user procurement patterns range from centralized healthcare system tenders to fragmented retail pilot programs, with manufacturing buyers emphasizing supply continuity over unit cost.
- Manufacturing:Automotive Tier 1s and electronics contract manufacturers specify AEC-Q100 qualified chipsets for production line tracking. BMW's Leipzig and Spartanburg plants require 99.99% uptime guarantees in vendor contracts.
- Logistics:Third-party logistics providers deploy disposable shipping labels with printed BLE antennas. Maersk and DSV are trialing battery-free sensor tags for refrigerated container monitoring.
- Healthcare:Hospital procurement committees evaluate total cost of ownership across 7-year device lifecycles.
- Retail:Grocery and apparel chains pilot electronic shelf labels with dynamic pricing capabilities.
Manufacturing leads in module ASP. Logistics is climbing the fastest.
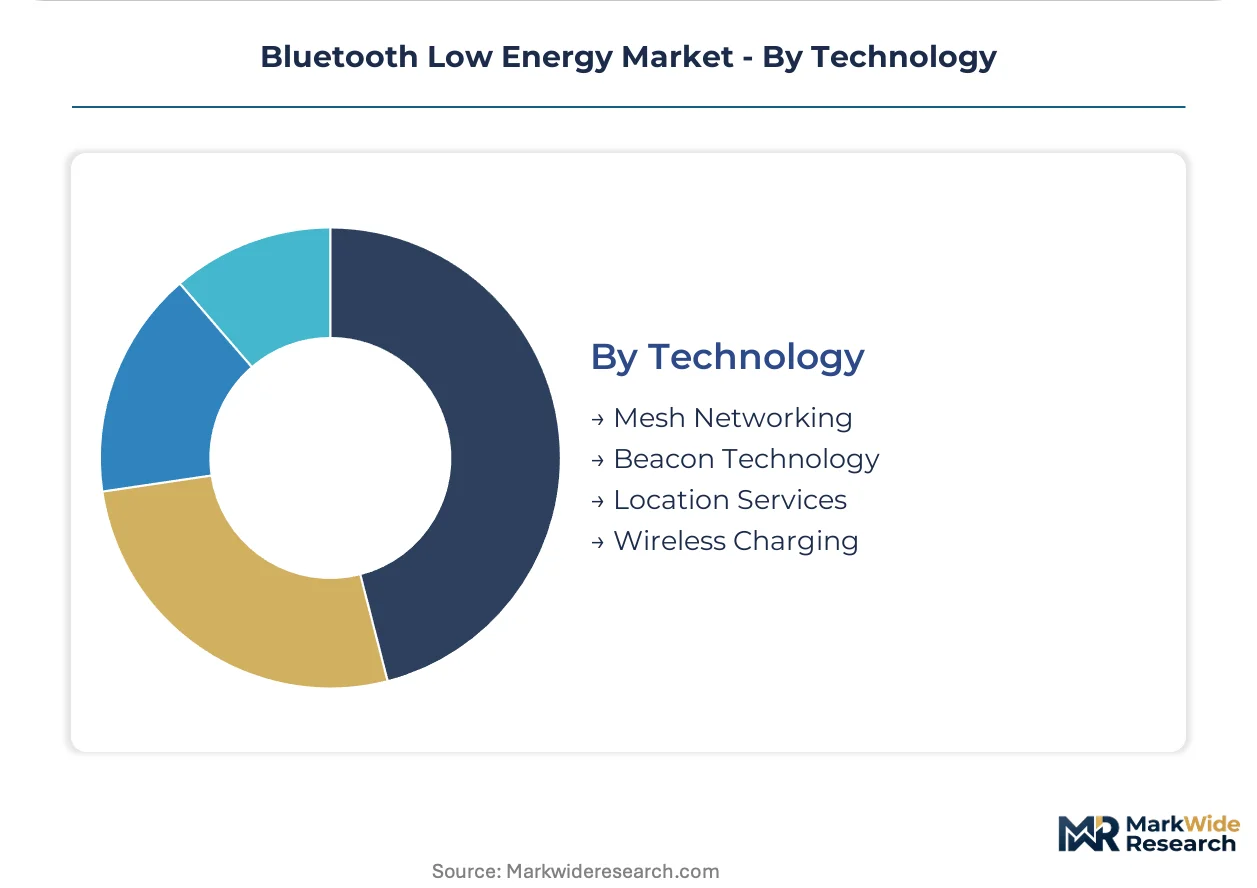
Technology:
Technology segments reflect architectural trade-offs between network scale, positioning precision, and power autonomy, with mesh networking requiring the most complex protocol stack investment.
- Mesh Networking:Self-healing multi-hop topologies support thousand-node factory deployments with sub-50ms latency. Siemens and Bosch are standardizing on BLE mesh for Industry 4.0 brownfield retrofits in Stuttgart and Munich manufacturing facilities.
- Location Services:Angle-of-arrival and received-signal-strength algorithms enable indoor positioning without dedicated infrastructure. Apple and Google ecosystem mandates are driving UWB-BLE fusion into smartphone reference designs.
- Beacon Technology:Fixed-position transmitters for proximity marketing face margin pressure from smartphone-based alternatives.
- Wireless Charging:Qi-compatible BLE tags eliminate battery replacement cycles in sealed industrial enclosures.
Mesh Networking dominates installed node count. Location Services shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capabilities in Inner Mongolia and Jiangxi province anchor China's dominance in ceramic antenna substrates and magnet materials essential for BLE module manufacturing.
United States
FCC Part 15 certification queues and FDA 510(k) pathways for clinical-grade wearables drive procurement timelines for healthcare OEMs. The Inflation Reduction Act allocates manufacturing tax credits for domestic semiconductor packaging. Austin and Boston design centers concentrate RF engineering talent for next-generation protocol stacks.
Germany
ETSI EN 300 328 harmonization reduces cross-border certification costs for module suppliers serving EU member states. The EU Radio Equipment Directive cybersecurity mandates taking effect in 2025 force firmware architecture redesigns. Stuttgart and Munich manufacturing clusters deploy BLE mesh for Industry 4.0 brownfield retrofits at Siemens and Bosch facilities.
China
MIIT spectrum allocation debates and dual carbon goals reshape chipset architecture priorities toward energy efficiency. Smart manufacturing clusters in Shenzhen and Dongguan drive chipset procurement at scale for consumer electronics OEMs. The Yangtze River Delta concentrates foundry capacity for advanced RF process nodes.
Japan
METI production-linked incentives for IoT component manufacturing accelerate PMDA registration timelines for home monitoring devices. JIS standards for electromagnetic compatibility constrain module design specifications. The Kanto region around Tokyo hosts precision farming equipment makers demanding turnkey sensor-to-dashboard solutions.
India
The PLI scheme for electronics manufacturing attracts module assembly investments to serve domestic smart meter and automotive telematics demand. BIS certification requirements for radio equipment create entry barriers for unqualified suppliers. Karnataka and Tamil Nadu industrial corridors concentrate contract manufacturing capacity for export-oriented BLE tags.
Bluetooth Low Energy Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue ambient IoT convergence and energy-harvesting integration. The vendor base stratifies across three tiers: integrated protocol stack specialists, low-power RF process experts, and multiprotocol platform providers. Strategic archetypes include design-win aggregators sustaining momentum through developer tooling, analog integrators reducing bill-of-material complexity, and edge-AI convergers transforming radio hardware into autonomous sensor nodes. Capacity expansion and pre-certified security stack differentiation dominate competitive moves as EU cybersecurity mandates approach enforcement.
Among Nordic-based connectivity specialists, Nordic Semiconductor exemplifies the design-win aggregation archetype through sustained momentum across wearable and medical segments. Texas Instruments Incorporated anchors the low-power RF integration tier, occupying a position where analog expertise reduces endpoint complexity. Within the multiprotocol platform category, Qualcomm Incorporated represents the scale-driven convergence of connectivity silicon with smartphone ecosystem mandates.
| Leading Market Players |
|---|
| Nordic Semiconductor |
| Texas Instruments Incorporated |
| Intel Corporation |
| STMicroelectronics |
| Silicon Laboratories |
| NXP Semiconductors |
| Qualcomm Incorporated |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| Others |
Supply Flow & Price Mechanics
Smartphone OEM procurement committees in Shenzhen and Cupertino anchor volume pricing for BLE chipsets, while FDA-validated healthcare device manufacturers absorb premium markups for certified modules. This buyer bifurcation enforces a certification-driven pricing architecture that rewards pre-qualified suppliers with pricing power over commodity radio vendors.
Pricing Analysis
Volume concentrates in consumer wearables at thin margins, while healthcare equipment commands substantial premiums through FDA 510(k) and CE MDR validation tiers. Three-tier pricing structure across clinical-grade, industrial-qualified, and consumer-economy levels separates modules by electromagnetic compatibility testing depth and protocol stack maturity. Cost compression in the consumer tier intensifies because Shenzhen-based OEMs negotiate consolidated annual volumes exceeding million-unit thresholds. Hospital procurement committees exhibit the lowest price sensitivity, prioritizing seven-year total cost of ownership and liability coverage over per-unit acquisition cost.
Supply Chain Analysis
Ocean freight rates from Taiwanese foundries to Dongguan module assembly plants directly shape landed cost structures for BLE SoCs. Advanced RF process nodes concentrate in Taiwan, while ceramic antenna substrate processing anchors in China's Jiangxi province and magnet materials refine in Inner Mongolia. Rare earth element price volatility in lithium and neodymium presents single-source vulnerability for battery and antenna component feeds. Distribution runs through Arrow Electronics and Avnet for developer kit pre-certification, with direct OEM contracts dominating healthcare and automotive verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Radio Equipment Directive cybersecurity mandates effective 2025 erect a compliance moat that favors incumbent module vendors with pre-certified firmware architectures and notified body relationships. This regulation transforms security stack investment from optional differentiation into mandatory market access requirement.
For Market Incumbents: Acquire RF engineering talent pools in Austin and Boston design centers to defend against Wi-Fi HaLow substitution threats in warehouse automation. Fortify backward integration into energy-harvesting photovoltaic interfaces for ambient IoT convergence, while expanding AEC-Q100 qualified foundry capacity to capture automotive telematics procurement.
For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for module assembly investments serving domestic smart meter demand with BIS certification as entry barrier. Target Karnataka and Tamil Nadu industrial corridors for contract manufacturing partnerships, with pre-certified reference designs as the go-to-market angle to bypass in-house RF expertise requirements.
For Investors and Strategic Acquirers: The window for entry favors edge-AI convergers with integrated protocol stacks and developer tooling ecosystems. Long-term viability hinges on differentiation beyond commodity radio hardware toward autonomous sensor node platforms. Watch for FDA 510(k) clearance velocity as inflection indicator for healthcare segment margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified Security Stack Development | EU RED compliance transforms firmware architecture into mandatory procurement filter for hospital systems. |
| Energy-Harvesting Interface Integration | Photovoltaic and piezoelectric power absorption enables battery-free retail inventory tags. |
| Turnkey Sensor-to-Dashboard Platform | German automotive Tier 1s now demand combined BLE connectivity with cloud telemetry solutions. |
| India PLI Scheme Manufacturing Footprint | Domestic module assembly serves smart meter and telematics demand with BIS certification pathway. |
| Angle-of-Arrival Positioning Fusion | UWB-BLE integration responds to Apple and Google ecosystem mandates for indoor navigation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Bluetooth Low Energy market assessment. Primary interviews with RF engineering directors, hospital procurement managers, semiconductor foundry planners, and industrial automation system integrators validated demand assumptions. FCC Part 15 equipment authorization databases, ETSI harmonized standards publications, and MIIT spectrum allocation notices supplemented volume estimation. Bottom-up triangulation across chipset shipment data and top-down reconciliation against end-use equipment production statistics ensured cross-verification.
Data-stream reconciliation across foundry capacity reports, OEM design-win announcements, and certification timeline disclosures informed the analytical framework. Segmentation dimensions modeled include product type certification tier, application throughput requirement, end-user procurement pattern, and technology architecture complexity. CAGRs derived from installed base growth rates and replacement cycle analysis across healthcare, industrial, and consumer verticals. Energy-harvesting adoption curves and mesh networking node deployment trajectories provided industry-specific forecast inputs across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for Wi-Fi HaLow or proprietary sub-GHz protocols would alter the outlook for BLE's warehouse automation positioning. Forecasts reflect assumptions regarding ETSI harmonization continuity, foundry capacity expansion timing, and cybersecurity mandate enforcement rigor. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Ethernet PHY Chip Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Satellite Communication Components Market