
 Nano GPS Chip Market | 2026-2036
Nano GPS Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Nano GPS Chip Market Intelligence
Buyer concentration in the wearable electronics segment is recalibrating procurement dynamics across the nano GPS chip value chain. Qualcomm Incorporated leverages its baseband-GPS integration expertise to dominate premium smartphone and smartwatch sockets. STMicroelectronics N.V. sustains European automotive and industrial design wins through specialized multi-constellation architectures. Quectel Wireless Solutions Co., Ltd. anchors Asia-Pacific module supply by controlling cost-optimized miniature module distribution channels.
A nano GPS chip is a sub-millimeter-scale radio-frequency integrated circuit that receives and processes signals from satellite navigation constellations such as GPS, GLONASS, Galileo, or BeiDou, typically fabricated on CMOS or GaAs processes with power consumption below 10 milliwatts to enable continuous positioning in battery-constrained devices. Dual-Frequency Chips are gaining structural importance because atmospheric error correction and urban multipath rejection justify premium pricing in precision agriculture and surveying applications. Multi-Constellation Chips occupy the broadest volume tier as logistics providers and consumer electronics manufacturers prioritize fix reliability over single-system dependency. Miniature Modules concentrate margin pools where defense contractors and medical device makers pay for pre-certified, shielded assemblies that compress time-to-market.
The FCC governs spurious emissions and spectrum allocation for GPS receivers marketed in the United States, while the EU Radio Equipment Directive mandates CE marking and interoperability testing for devices sold across member states. Japan's MIC establishes terrestrial radio law compliance that shapes product architectures for Asia-bound shipments. Stakeholders must monitor evolving Galileo Public Regulated Service mandates and BeiDou-3 global completion signals to determine constellation support roadmaps before committing to fixed silicon designs.
Market Dynamics
Wearable device manufacturers are compressing procurement cycles as fitness trackers and smartwatches demand tighter positioning capabilities, forcing chip vendors to accelerate miniaturization roadmaps and pre-certify modules for faster integration.
Growth Catalysts
- EU Radio Equipment Directive:CE marking mandates for electromagnetic compatibility are driving module suppliers toward pre-certified, shielded assemblies that reduce time-to-market for IoT integrators.
- Dual-Frequency Architecture:Atmospheric error correction capabilities in precision agriculture and surveying equipment justify premium positioning for chips with L1/L5 reception.
- Shenzhen Electronics Ecosystem:Concentrated manufacturing and testing infrastructure in southern China accelerates cost-down cycles and prototype iteration for module vendors.
Market Restraints
- GaAs Wafer Supply Concentration:Limited foundry capacity for gallium arsenide processes creates input bottlenecks for high-performance RF front-ends.
- FCC Part 15 Spurious Emissions:Tightening electromagnetic thresholds for miniature RF devices extend certification timelines and increase compliance engineering overhead.
- Multi-Constellation Silicon Complexity:Supporting GPS, GLONASS, Galileo, and BeiDou simultaneously inflates die area and power budgets beyond single-system alternatives.
Strategic Opportunities
- Medical Device Integration:Miniature modules for patient monitoring and asset tracking command premium pricing from device makers seeking pre-certified, shielded assemblies.
- Galileo Public Regulated Service:Emerging encrypted signal mandates for government and defense applications create differentiation for vendors with early PRS-capable designs.
- India BIS Certification Pathway:Local testing infrastructure expansion enables faster market entry for cost-optimized modules targeting logistics and fleet management.
Industry Challenges
- RF Front-End Integration Expertise:Scarce talent pools for sub-millimeter antenna matching and interference mitigation constrain design team scaling.
- Multi-Constellation Certification Matrices:Simultaneous validation across GPS, GLONASS, Galileo, and BeiDou signal environments multiplies test cycle duration and capital equipment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano GPS Chip Market |
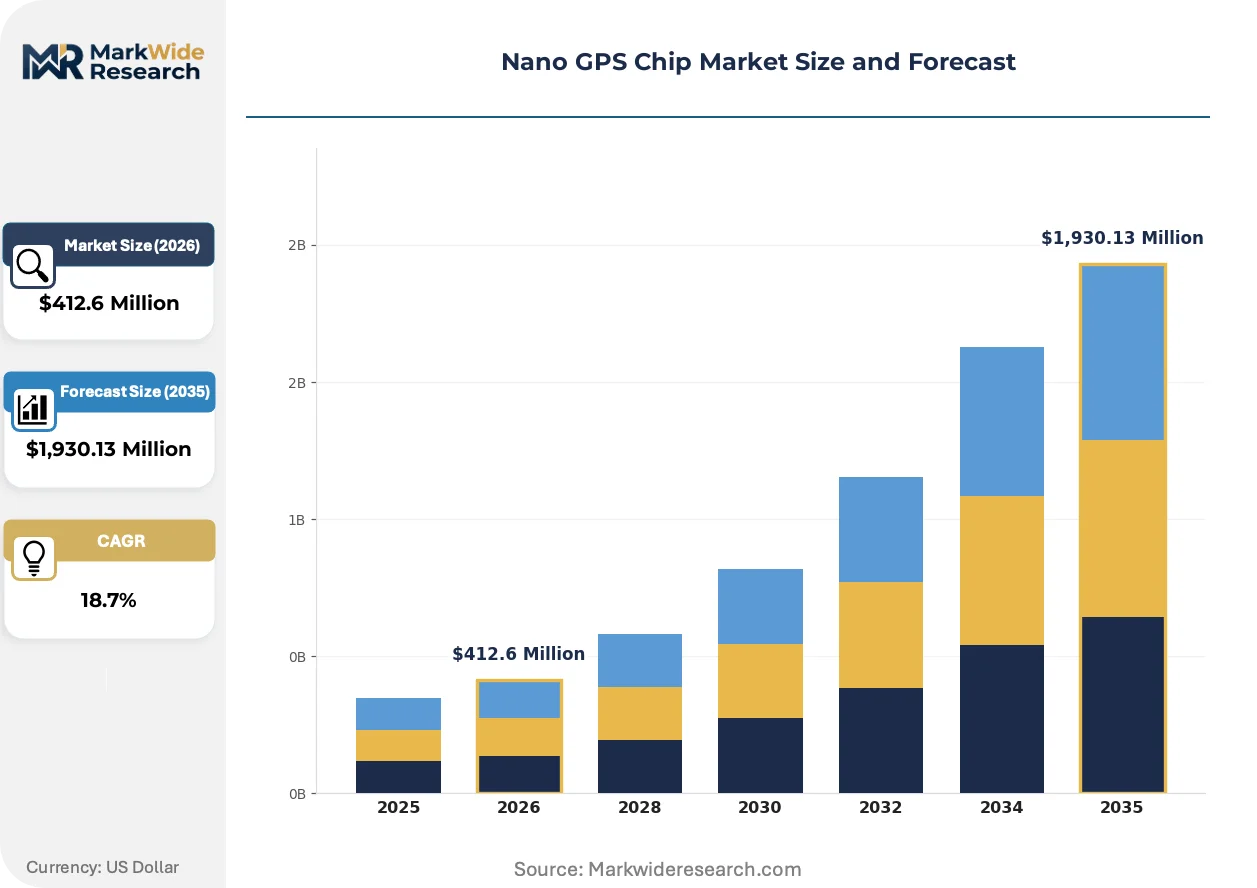
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Frequency Chips, Dual-Frequency Chips, Multi-Constellation Chips, Miniature Modules Technology: Complementary Metal-Oxide Semiconductor, Microelectromechanical Systems, Thin-Film Transistor, Gallium Arsenide Application: Wearable Devices, Asset Tracking, Unmanned Aerial Vehicles, Precision Agriculture, Logistics Management End User: Consumer Electronics Manufacturers, Defense Contractors, Logistics Providers, Agricultural Equipment Makers |
| Companies Covered | u-blox Holding AG, OriginGPS Ltd., Qualcomm Incorporated, Quectel Wireless Solutions Co., Ltd., Skyworks Solutions, Inc., Broadcom Corporation, STMicroelectronics N.V., Analog Devices Inc., MediaTek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano GPS Chip Market Strategic Shifts & Innovations
Baseband-GPS integration is collapsing discrete component counts as vendors merge positioning engines with connectivity silicon, compressing bill-of-materials costs and board area requirements simultaneously.
Dual-frequency reception architectures are unifying atmospheric correction and multipath rejection in single-die solutions. Precision agriculture OEMs and surveying equipment manufacturers are adopting these designs fastest, replacing discrete L1-only modules. This unification is compressing the addressable market for standalone correction services and premium-grade single-frequency alternatives.
Japan's MIC terrestrial radio law compliance requirements are reshaping product architectures for Asia-bound shipments, with specific spurious emission limits below FCC thresholds. Module vendors are redesigning shielding and filtering stages to satisfy the stricter Japanese regime. Medical device and automotive telematics segments targeting Japanese end-users face the longest recertification cycles.
Buyer concentration among wearable electronics brands is shortening supplier qualification timelines and demanding outcome-based module performance guarantees rather than component specifications. Tier-one fitness tracker manufacturers now require fix-accuracy warranties and field-failure liability terms. This contractual evolution is most visible in Shenzhen procurement offices where smartwatch OEMs negotiate directly with module integrators.
Nano GPS Chip Market Segmentation
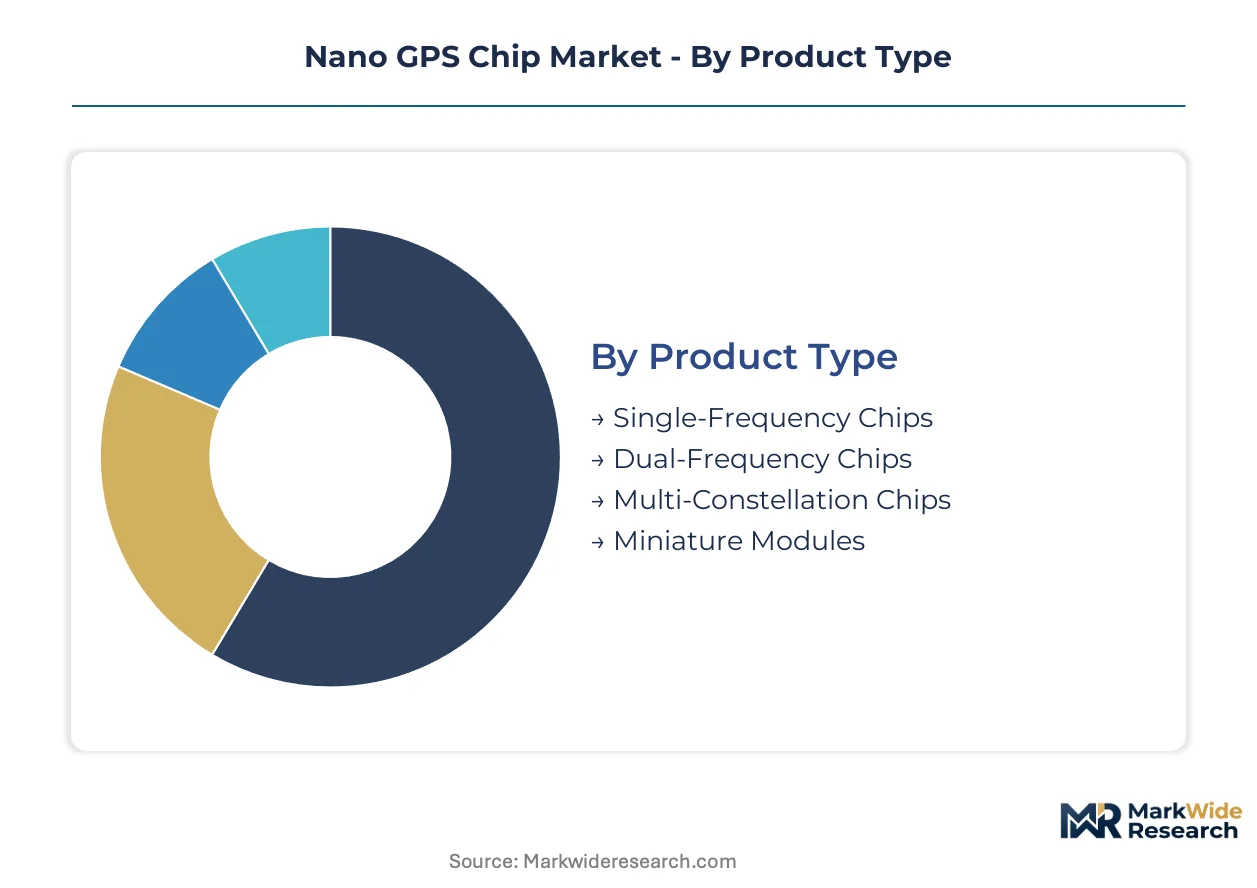
Chip architecture choices determine capital deployment intensity across foundry partnerships, certification matrices, and module integration workflows. Understanding how product specifications, fabrication processes, and end-use requirements fragment the addressable market clarifies where margin pools concentrate and which segments justify premium positioning.
Product Type:
Dual-Frequency Chips and Miniature Modules demand the heaviest upfront investment due to specialized RF front-end design, multi-layer shielding requirements, and extended regulatory certification cycles across FCC, EU Radio Equipment Directive, and Japan MIC jurisdictions.
- Dual-Frequency Chips:These architectures integrate L1/L5 band reception for atmospheric error correction and urban multipath rejection. Precision agriculture OEMs in the United States and surveying equipment manufacturers in Germany absorb the bulk of current shipments, driven by centimeter-grade accuracy mandates that justify die-area expansion and premium module pricing.
- Miniature Modules:Pre-certified, shielded assemblies compress time-to-market for medical device makers and defense contractors seeking turnkey positioning solutions. Manufacturing concentrates in Shenzhen's electronics ecosystem, where module integrators control distribution channels through backward integration into RF testing and electromagnetic compatibility validation.
- Single-Frequency Chips:Basic L1-only receivers serve cost-constrained logistics tags and entry-level fitness trackers with minimal silicon complexity.
- Multi-Constellation Chips:GPS-GLONASS-Galileo-BeiDou fusion enables fix reliability in urban canyons and dense foliage environments for fleet management applications.
Multi-Constellation Chips absorb the bulk of installed capacity; Dual-Frequency Chips are expanding most quickly as precision agriculture and surveying equipment manufacturers upgrade from single-frequency alternatives.
Technology:
Process node selection fragments the supply base between mature CMOS foundries with depreciated capital equipment and specialty compound semiconductor facilities requiring ongoing gallium arsenide wafer supply commitments.
- Gallium Arsenide:III-V compound semiconductors deliver superior electron mobility for high-performance RF front-ends in defense and aerospace applications. Limited foundry capacity in the United States and Japan creates input bottlenecks, forcing module vendors into long-term supply agreements with substrate manufacturers.
- Complementary Metal-Oxide Semiconductor:CMOS dominates volume production through mature 40nm and 28nm nodes, enabling baseband-GPS integration that collapses discrete component counts. Taiwan and South Korea foundries anchor supply for consumer electronics manufacturers seeking cost-optimized, low-power positioning engines.
- Microelectromechanical Systems:MEMS processes enable co-integration of accelerometers and gyroscopes with GPS receivers for dead-reckoning augmentation in tunnel and indoor environments.
- Thin-Film Transistor:TFT backplanes support flexible and transparent form factors for emerging wearable display applications requiring conformal antenna integration.
CMOS fabrication commands the greatest cumulative installed capacity; Gallium Arsenide is gaining share fastest among defense contractors prioritizing interference immunity over unit economics.
Application:
End-use concentration determines procurement leverage, with wearable electronics brands extracting outcome-based performance guarantees while agricultural and defense segments accept longer qualification cycles for specialized reliability metrics.
- Wearable Devices:Fitness trackers and smartwatches demand sub-10 milliwatt power budgets and fix-accuracy warranties from module suppliers. Shenzhen-based OEMs negotiate directly with integrators, compressing supplier qualification timelines and shifting contractual risk toward field-failure liability terms.
- Precision Agriculture:Autonomous tractors and variable-rate applicators require dual-frequency reception with RTK correction integration. Equipment manufacturers in the United States and Germany specify multi-constellation support to maintain signal lock under tree canopy and near grain elevator interference sources.
- Asset Tracking:Low-power, wide-area tags for shipping containers and rental equipment prioritize fix reliability over update frequency, favoring multi-constellation silicon with aggressive duty cycling.
- Unmanned Aerial Vehicles:Commercial drones and last-mile delivery aircraft mandate failsafe positioning with redundant constellation backup for beyond-visual-line-of-sight operations.
- Logistics Management:Fleet telematics providers integrate GPS with cellular connectivity for real-time route optimization and geofencing enforcement across interstate corridors.
Wearable Devices command the largest addressable volume; Precision Agriculture is climbing the fastest as equipment OEMs retrofit existing fleets with centimeter-grade guidance systems.
End User:
Customer type dictates pricing architecture and support intensity, with defense and medical segments absorbing premium positioning for pre-certified modules while consumer electronics manufacturers drive cost-down roadmaps through consolidated procurement.
- Defense Contractors:Encrypted signal reception, anti-jamming architectures, and extended temperature specifications define procurement criteria. Galileo Public Regulated Service mandates and classified BeiDou waveform support require specialized design teams with security clearance and ITAR compliance infrastructure.
- Consumer Electronics Manufacturers:Smartwatch and fitness tracker brands leverage Shenzhen's concentrated electronics ecosystem to compress module costs through direct integrator relationships and volume commitments. These buyers demand fix-accuracy warranties and accelerated failure analysis turnaround that shift operational risk upstream.
- Logistics Providers:Fleet operators and shipping lines prioritize multi-constellation reliability for cross-border asset visibility, accepting standardized modules with regional certification bundles.
- Agricultural Equipment Makers:Tractor and implement manufacturers specify dual-frequency reception with ISOBUS integration for precision planting and spraying automation.
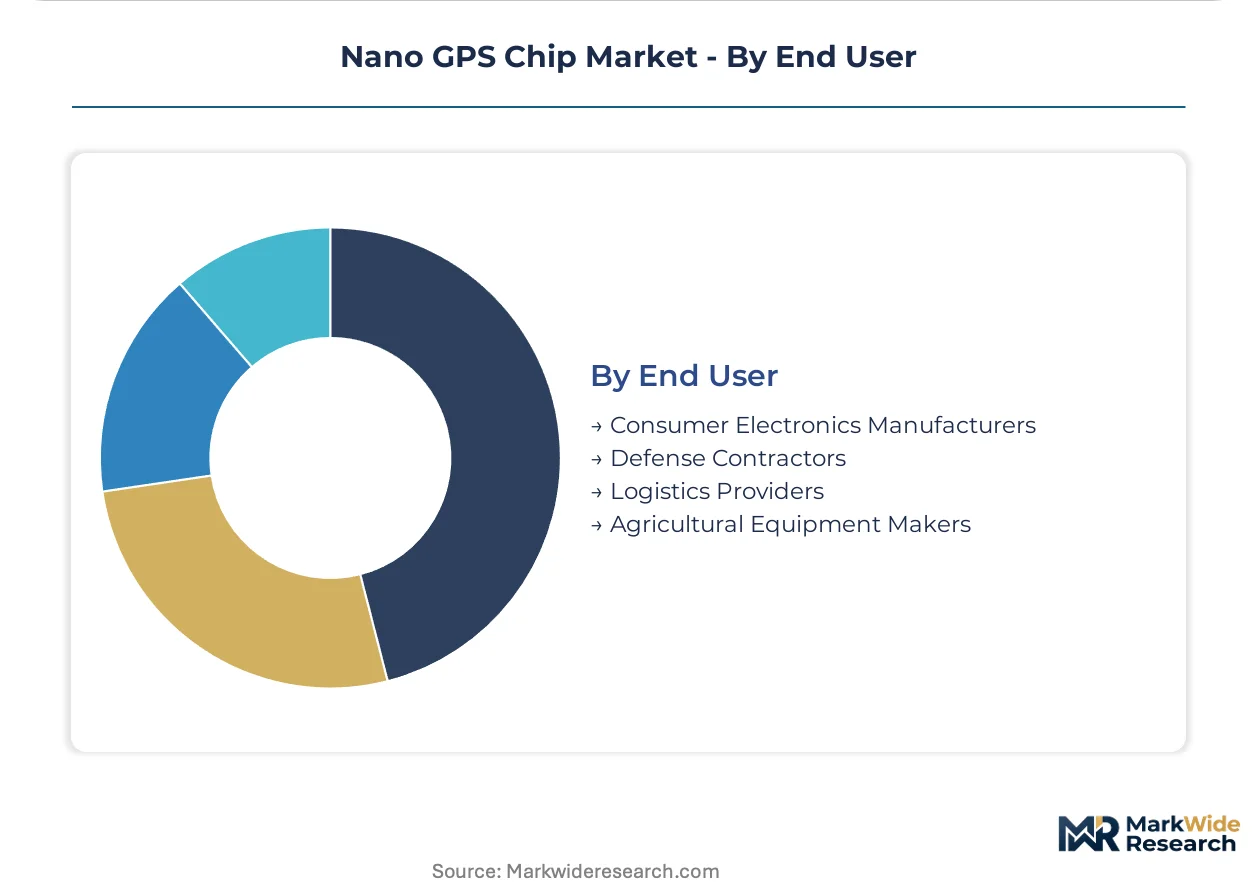
Consumer Electronics Manufacturers absorb the bulk of unit volume; Defense Contractors are expanding most quickly as NATO members accelerate Galileo PRS deployment and Indo-Pacific allies diversify constellation dependencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement leverage for nano GPS chip modules, with Shenzhen's electronics ecosystem compressing cost-down cycles for wearable OEMs. Germany and the United States anchor precision agriculture demand through dual-frequency adoption. Japan enforces the strictest electromagnetic compatibility thresholds, reshaping shielding architectures for Asia-bound shipments.
United States
Precision agriculture OEMs in Iowa and Illinois retrofit tractor fleets with centimeter-grade guidance systems. FCC Part 15 rules govern spurious emissions for miniature RF devices, extending certification timelines for module vendors. Austin's semiconductor corridor hosts RF front-end design teams specializing in interference mitigation for autonomous equipment.
Germany
Surveying equipment manufacturers in Bavaria absorb premium dual-frequency chips for construction and geodesy applications. The EU Radio Equipment Directive mandates CE marking and interoperability testing for devices sold across member states. Stuttgart's automotive cluster integrates multi-constellation receivers into telematics and advanced driver-assistance platforms.
China
Shenzhen-based smartwatch OEMs negotiate directly with module integrators, demanding fix-accuracy warranties and accelerated failure analysis. MIIT establishes type-approval requirements for BeiDou-3 compatibility in domestic consumer electronics. The Pearl River Delta's concentrated testing infrastructure enables prototype iteration cycles measured in weeks rather than months.
Japan
METI's terrestrial radio law compliance requirements impose spurious emission limits below FCC thresholds, forcing shielding redesigns for medical device shipments. Osaka's precision manufacturers source miniature modules for patient monitoring and asset tracking applications. Kansai-based RF specialists develop filtering stages for the stricter Japanese regulatory regime.
India
Logistics providers in Maharashtra and Gujarat prioritize multi-constellation reliability for cross-border fleet visibility. BIS certification pathway expansion accelerates market entry for cost-optimized modules targeting container tracking. Bangalore's electronics manufacturing cluster attracts module integrators seeking regional assembly partnerships.
Nano GPS Chip Market Key Industry Players
United States and European producers anchor one tier; Asia-Pacific specialists hold cost-optimized module supply. The vendor base splits between baseband-GPS integration leaders and RF front-end compound semiconductor fabricators. Three archetypes dominate: premium smartphone socket holders, automotive-grade multi-constellation suppliers, and Shenzhen-anchored miniature module integrators. Competitive moves concentrate on backward integration into RF testing infrastructure and strategic partnerships with wearable OEMs for pre-certified designs.
Among Switzerland-based positioning specialists, u-blox Holding AG exemplifies premium-tier module architecture. Qualcomm Incorporated and STMicroelectronics N.V. occupy distinct positions in baseband integration and automotive-grade multi-constellation supply respectively. Quectel Wireless Solutions Co., Ltd. anchors Asia-Pacific distribution through cost-optimized miniature module channels.
| Leading Market Players |
|---|
| u-blox Holding AG |
| OriginGPS Ltd. |
| Qualcomm Incorporated |
| Quectel Wireless Solutions Co., Ltd. |
| Skyworks Solutions, Inc. |
| Broadcom Corporation |
| STMicroelectronics N.V. |
| Analog Devices Inc. |
| MediaTek Inc. |
| Others |
Cost & Logistics Intelligence
EU Radio Equipment Directive compliance gates qualified supply and premium-tier pricing access, with CE marking mandates forcing module vendors toward pre-certified shielded assemblies that command price premiums from medical device makers and defense contractors seeking compressed time-to-market.
Pricing Analysis
Volume concentrates in single-frequency and multi-constellation chips while margins pool in dual-frequency architectures and miniature modules. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade pre-certified modules from consumer electronics bare chips and entry-level L1 receivers. Cost compression in the economy tier is intensifying because Shenzhen-based wearable OEMs negotiate directly with integrators, extracting fix-accuracy warranties and field-failure liability terms. Consumer electronics manufacturers exhibit highest price sensitivity; defense contractors and medical device makers absorb premium positioning for turnkey assemblies.
Supply Chain Analysis
RF front-end engineering talent scarcity in Taiwan, South Korea, and southern China constrains design team scaling for sub-millimeter antenna matching. Gallium arsenide wafer supply draws from limited United States and Japan foundry capacity, while CMOS fabrication rests on depreciated 40nm and 28nm nodes in Taiwan and South Korea. Single-source vulnerability concentrates in GaAs substrate manufacturers, with long-term supply agreements locking module vendors into fixed volume commitments. Distribution runs through Shenzhen's module integrators controlling backward integration into RF testing and electromagnetic compatibility validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
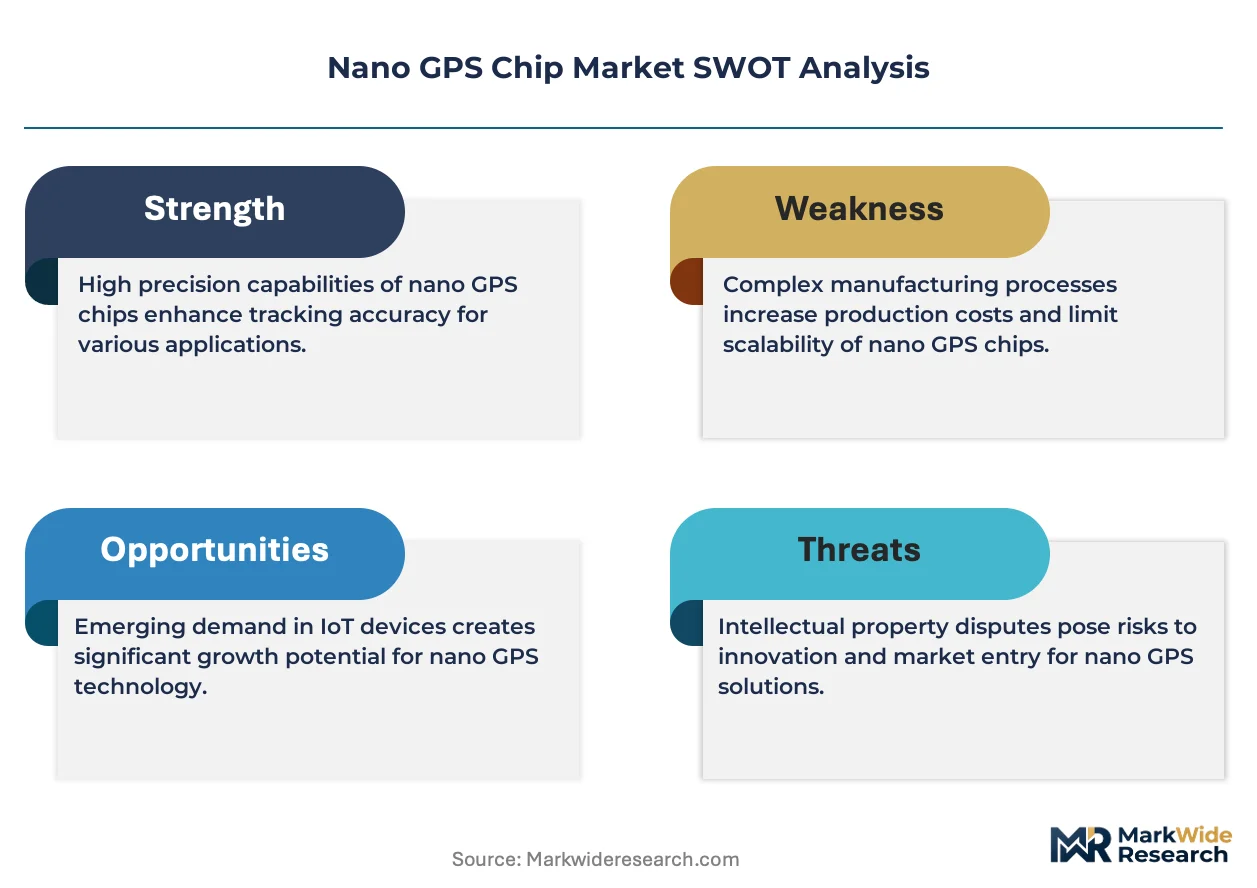
FCC Part 15 spurious emissions thresholds erect a cost-of-compliance barrier that favors incumbents with established certification infrastructure and dedicated compliance engineering teams.
For Market Incumbents: To counter margin erosion from Shenzhen-based cost-optimized module integrators, Qualcomm and STMicroelectronics should deepen backward integration into RF testing infrastructure and secure exclusive pre-certification partnerships with tier-one wearable OEMs. Captive supply of multi-constellation baseband-GPS silicon compresses bill-of-materials exposure while accelerating failure analysis turnaround. For New Entrants and Emerging Players: A price-point gap between premium dual-frequency modules and economy single-frequency chips opens entry paths for mid-tier multi-constellation suppliers targeting India's logistics sector. BIS certification pathway expansion enables faster market entry than FCC or EU Radio Equipment Directive timelines. Go-to-market should anchor on cost-optimized modules for fleet telematics providers prioritizing fix reliability over centimeter-grade accuracy. For Investors and Strategic Acquirers: Galileo Public Regulated Service mandate announcements from NATO procurement offices are the leading indicator that encrypted signal reception capabilities will command valuation premiums. Over a multi-year horizon, defense contractors and automotive-grade multi-constellation suppliers represent viable acquisition targets. Watch for BeiDou-3 waveform classification shifts in Indo-Pacific ally defense budgets as the signal triggering consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Certification Investment | CE marking and FCC Part 15 pre-certification compresses time-to-market for European and North American IoT integrators. |
| Backward Integration into RF Testing | Shenzhen-based module vendors controlling electromagnetic compatibility validation capture margin pools from shielded assembly premiums. |
| Dual-Frequency Architecture Development | L1/L5 reception capabilities unlock precision agriculture and surveying equipment manufacturers in Germany and the United States. |
| Galileo PRS Capability Roadmap | Encrypted signal support differentiates vendors for NATO defense procurement and government application mandates. |
| Baseband-GPS Silicon Integration | Qualcomm and MediaTek collapsing discrete component counts reduce board area and power budgets for wearable device manufacturers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with RF front-end design directors, module procurement managers at wearable OEMs, semiconductor foundry planning officers, and electromagnetic compliance engineering leads. FCC equipment authorization databases, EU Radio Equipment Directive notified body submissions, Japan MIC type-approval records, and Shenzhen customs export declarations supplied quantitative anchors. Bottom-up bill-of-materials modeling and top-down addressable market sizing were triangulated against foundry capacity disclosures and module shipment tracking.
Granularity-level modeling disaggregated volume and value across chip architecture, fabrication process, end-use application, and customer type dimensions throughout the forecast period. CAGRs were derived from installed base growth curves, replacement cycle analysis, and technology substitution elasticities. BeiDou-3 constellation completion signals, Galileo Public Regulated Service deployment timelines, and India BIS certification pathway maturation shaped regional trajectory assumptions.
Inputs from foundry utilization reports and module integrator shipment data were available through the study window; gaps in defense contractor procurement forecasts and classified waveform specification timelines introduce uncertainty bands around Galileo PRS and BeiDou encrypted signal adoption curves. Material deviation in NATO ally constellation diversification commitments or FCC spurious emissions threshold revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
I2C Bus Market