
 Bluetooth Low Energy (BLE) Module Market | 2026-2036
Bluetooth Low Energy (BLE) Module Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Low Energy (BLE) Module Market Outlook
Software-defined firmware update subscriptions is pivoting how BLE module vendors monetize hardware deployments. Nordic Semiconductor leverages its integrated development ecosystem to sustain design-win loyalty across wearable OEMs. Texas Instruments anchors its position through proprietary RF process technology that dominates industrial temperature ranges.
A Bluetooth Low Energy module is a compact radio transceiver subsystem operating in the 2.4 GHz ISM band with typical receive sensitivity of -95 dBm and transmit power configurable between -20 dBm and +8 dBm, purpose-built for intermittent data exchange at sub-milliwatt standby currents in battery-operated devices. Integrated modules combining BLE with application processors command premium positioning as OEMs seek to reduce BOM complexity and board area in space-constrained designs. Ultra-low power variants represent the fastest-expanding technology tier, driven by energy harvesting and disposable medical sensor applications where battery replacement is impractical.
The FCC Part 15 rules governing unintentional radiators and the EU Radio Equipment Directive with its CE marking requirements shape module certification pathways and determine whether end products need supplemental testing. FDA wireless medical device guidance and ETSI EN 300 328 broadband transmission standards add compliance layers for healthcare and European deployments respectively. Stakeholders must weigh module-level pre-certification against end-product testing obligations when selecting suppliers for multi-region rollouts.
Market Dynamics
Module-level pre-certification is fragmenting supplier selection criteria as OEMs weigh FCC Part 15 pre-approval against end-product testing obligations for multi-region medical device rollouts. This structural tension between compliance efficiency and regulatory coverage is redrawing procurement hierarchies across wearable and industrial automation verticals.
Growth Catalysts
- FDA Wireless Medical Device Cybersecurity Guidance:Tightened radio module design requirements are accelerating qualification of BLE-enabled remote patient monitoring systems by medical device manufacturers seeking streamlined 510(k) pathways.
- Germany's Industrial Automation Corridor:Factory digitization programs across Baden-Württemberg and Bavaria are concentrating demand for low-power wireless connectivity in predictive maintenance and asset tracking deployments.
- Energy Harvesting Integration:Sub-milliwatt standby current specifications are enabling disposable medical sensor applications where battery replacement is impractical, expanding addressable device categories.
Market Restraints
- RF Process Technology Concentration:Proprietary foundry capabilities for industrial temperature range performance remain concentrated among a limited supplier base, creating single-source vulnerability for -40°C to +85°C qualified modules.
- ETSI EN 300 328 Compliance Burden:European broadband transmission testing requirements add certification layers that extend time-to-market for healthcare deployments targeting CE marking.
- Integrated Module Cost Premium:Application processor consolidation commands 15-40% BOM cost elevation versus discrete BLE transceiver implementations, constraining adoption in price-sensitive consumer segments.
Strategic Opportunities
- Software-Defined Firmware Subscriptions:Recurring revenue models for over-the-air update capabilities are creating post-deployment monetization streams that decouple vendor economics from unit shipment volumes.
- Ultra-Low Power Tier Expansion:Disposable diagnostic and continuous glucose monitoring patches represent underpenetrated volume pools where energy harvesting compatibility opens new design-win categories.
- EU Medical Device Regulation (MDR) Transition:Stricter post-market surveillance requirements for wireless connectivity are favoring module suppliers with established notified body relationships and technical documentation depth.
Industry Challenges
- Multi-Region Certification Orchestration:Simultaneous FCC, CE, and FDA pathway management requires dedicated regulatory affairs bandwidth that strains mid-tier OEM resource allocation.
- Legacy System Integration Friction:Industrial automation retrofit projects demand protocol translation gateways that add latency and complexity to pure BLE architectures, complicating value proposition articulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Low Energy (BLE) Module Market |
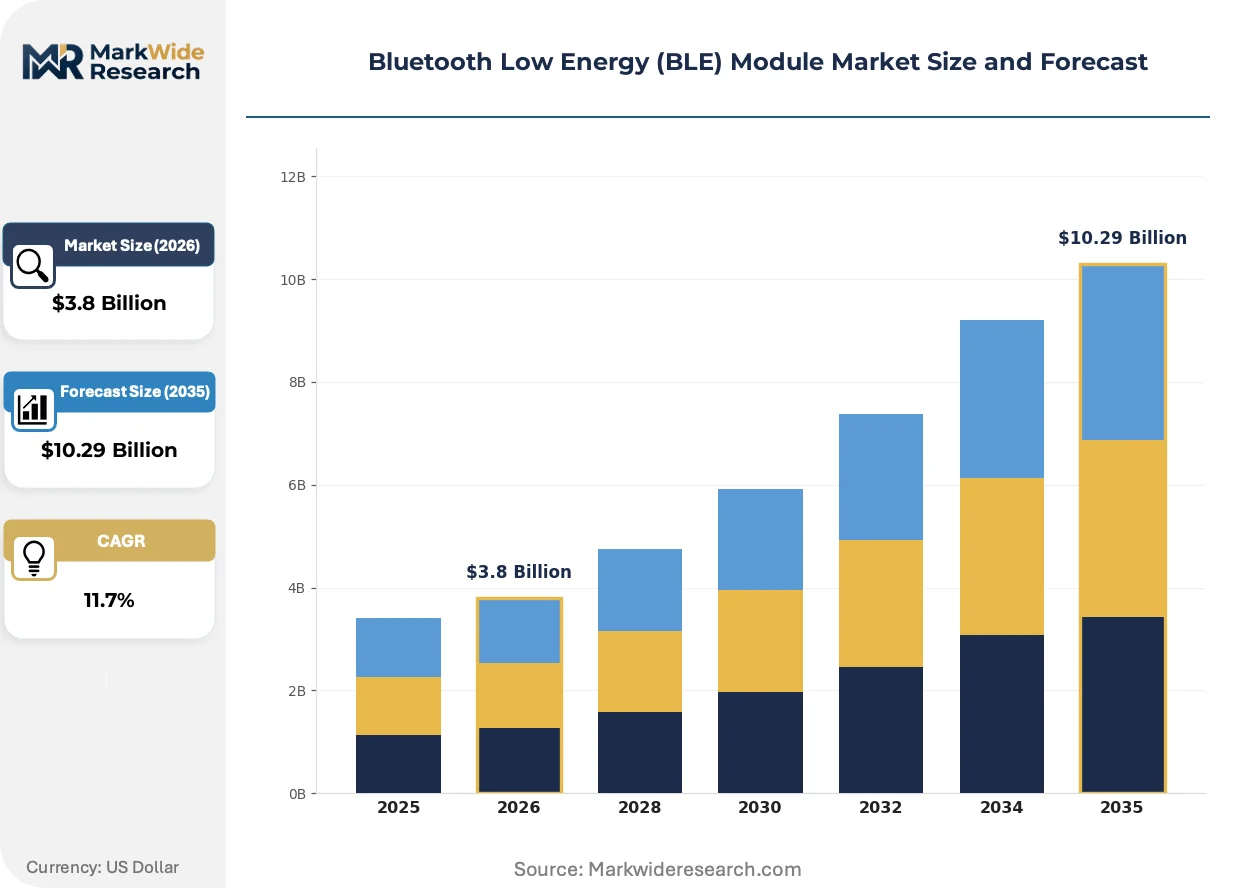
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Module Type: Standalone, Integrated, Multi-Protocol, Secure, Ultra-Low Power Technology: Bluetooth 4.0, Bluetooth 4.2, Bluetooth 5.0, Bluetooth 5.1, Bluetooth 5.2 Application Area: Wearable Electronics, Smart Home Devices, Industrial Automation, Asset Tracking, Smart Metering End User Type: Consumer Electronics Manufacturers, Industrial Equipment Suppliers, Healthcare Device Makers, Logistics Firms, Energy Providers |
| Companies Covered | Nordic Semiconductor, Texas Instruments, STMicroelectronics, Silicon Laboratories, NXP Semiconductors, Infineon Technologies, Renesas Electronics, Toshiba Corporation, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Low Energy (BLE) Module Market Strategic Shifts
Convergence between radio transceiver subsystems and edge processing capability is compressing board area requirements while elevating firmware complexity. This integration trajectory is redefining vendor competitive moats around development ecosystem depth rather than discrete RF performance metrics alone.
System-in-package architectures combining BLE transceivers with ARM Cortex-M33 application cores is absorbing functions previously executed on separate host processors. Wearable OEMs in fitness tracking and hearables are adopting these consolidated modules at accelerated pace to reduce BOM line items. This absorption of processing capability into the radio subsystem is compressing margin pools for standalone microcontroller suppliers while elevating firmware subscription attach rates for module vendors.
The EU Radio Equipment Directive's 2024 cybersecurity baseline requirements are mandating secure boot and firmware signing capabilities for all radio modules seeking CE marking. Industrial gateway manufacturers must now validate supply chain integrity documentation across tier-two semiconductor vendors. German automotive suppliers and French medical device OEMs are responding by pre-qualifying module vendors with established Common Criteria evaluation facilities, narrowing the approved supplier list ahead of enforcement deadlines.
Hospital procurement departments are consolidating wireless connectivity specifications into enterprise-wide master service agreements that span multiple device categories. This buyer concentration is displacing fragmented purchasing by individual clinical engineering departments across IDN networks. The shift is most visible in US health systems exceeding 500 beds, where standardization committees now mandate pre-certified BLE modules with documented FDA Q-Sub correspondence to reduce validation overhead for connected physiologic monitors and infusion pumps.
Bluetooth Low Energy (BLE) Module Market Segmentation
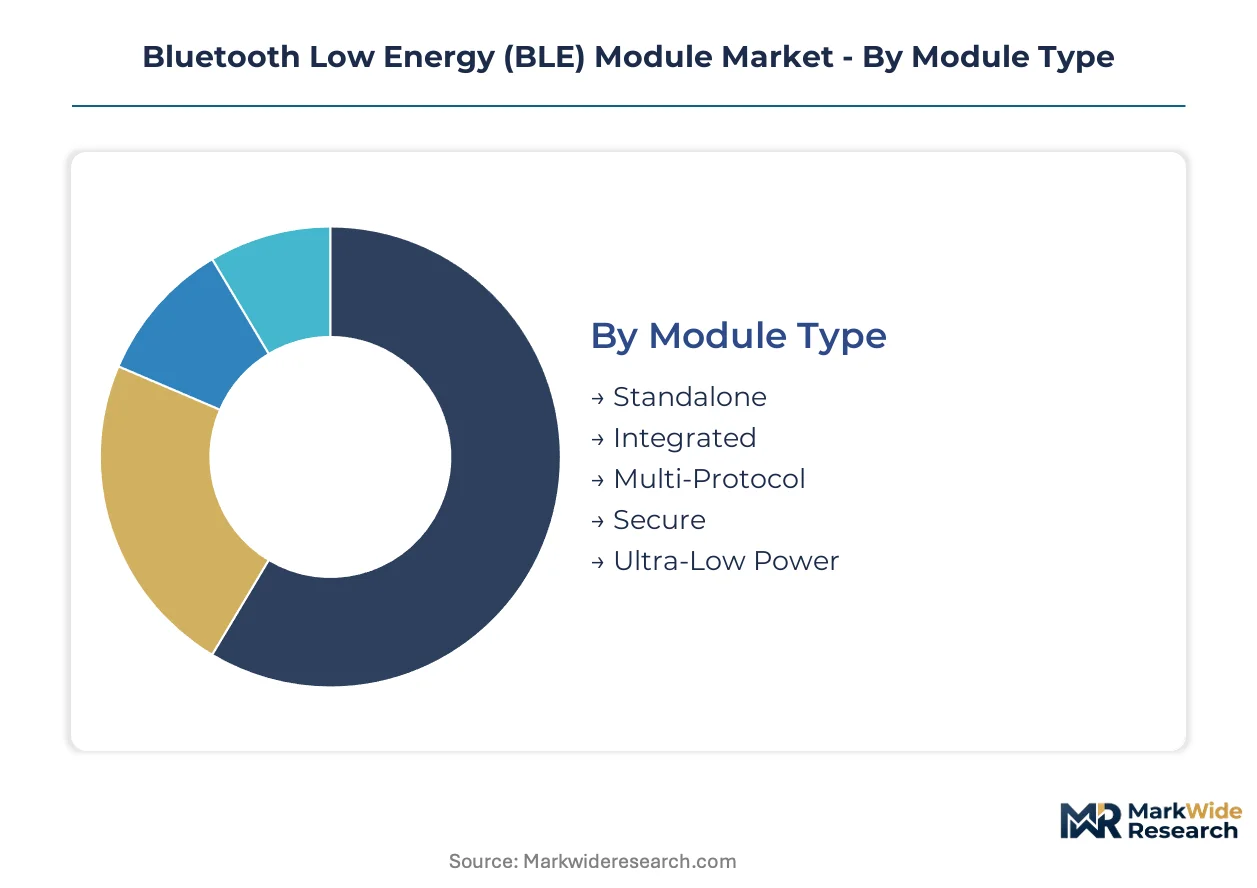
BLE module segmentation reflects a fundamental split between standalone transceivers for legacy retrofit applications and deeply integrated subsystems that compress board area in next-generation designs. Procurement teams weigh BOM complexity reduction against certification pathway simplicity when navigating these categories.
Module Type:
Standalone modules preserve host processor independence for industrial retrofit scenarios, while integrated variants absorb application-layer functions to serve space-constrained medical and wearable deployments.
- Standalone:Discrete radio transceivers operating with external host microcontrollers, preferred in Germany's factory automation corridor where legacy PLC integration demands protocol flexibility. Demand concentrates among industrial equipment suppliers retrofitting predictive maintenance sensors onto existing machinery without redesigning control architectures.
- Integrated:System-in-package architectures combining BLE transceivers with ARM Cortex-M33 cores, dominating wearable electronics where hearable OEMs eliminate separate application processors. Energy harvesting compatibility in disposable medical patches is accelerating qualification timelines for this tier.
- Multi-Protocol:Concurrent BLE, Zigbee, and Thread support enabling smart home hub consolidation.
- Secure:Hardware cryptographic engines with secure boot mandated by EU Radio Equipment Directive cybersecurity baselines.
- Ultra-Low Power:Sub-microamp sleep currents targeting battery-free energy harvesting applications in continuous glucose monitoring.
Standalone modules lead volumes today; integrated variants are gaining share fastest.
Technology:
Protocol generation selection determines range, throughput, and positioning capability, with newer specifications commanding premium positioning in asset tracking and indoor navigation applications.
- Bluetooth 5.0:Doubled range and quadrupled throughput over 4.2, establishing the baseline for industrial automation deployments across Bavaria's automotive supplier parks. Smart metering infrastructure in France leverages its extended range to reduce gateway density in rural deployments.
- Bluetooth 5.1:Direction-finding with angle-of-arrival/departure enabling sub-meter indoor positioning, critical for hospital asset tracking where US health systems mandate real-time infusion pump location. FDA-cleared surgical instrument tracking systems are consolidating procurement specifications around this generation.
- Bluetooth 4.0:Legacy interoperability tier for cost-constrained consumer peripherals.
- Bluetooth 4.2:Intermediate specification with improved security over 4.0, retained in established smart home device lines.
- Bluetooth 5.2:Latest specification with LE Audio and isochronous channels, penetrating premium hearables.
Bluetooth 5.0 dominates current procurement; Bluetooth 5.1 shows steepest expansion trajectory.
Application Area:
End-use verticals impose divergent power, range, and certification requirements that reshape module selection criteria across consumer, industrial, and regulated healthcare environments.
- Wearable Electronics:Fitness bands, smartwatches, and hearables demanding sub-milliwatt standby currents, with Nordic Semiconductor's development ecosystem capturing design wins among leading OEMs. Ultra-low power module variants are penetrating disposable diagnostic patches where battery replacement is impractical.
- Industrial Automation:Predictive maintenance sensors and wireless I/O modules operating across -40°C to +85°C ranges, concentrated in Germany's Baden-Württemberg manufacturing belt. Texas Instruments' proprietary RF process technology anchors qualification programs for automotive tier-one suppliers.
- Smart Home Devices:Lighting controls, security sensors, and HVAC thermostats prioritizing interoperability.
- Asset Tracking:Real-time location systems in logistics and healthcare, with Bluetooth 5.1 direction-finding displacing RFID in high-value equipment monitoring.
- Smart Metering:Utility infrastructure deployments favoring multi-protocol modules for grid interoperability.
Wearable electronics lead volumes today; industrial automation is climbing the fastest.
End User Type:
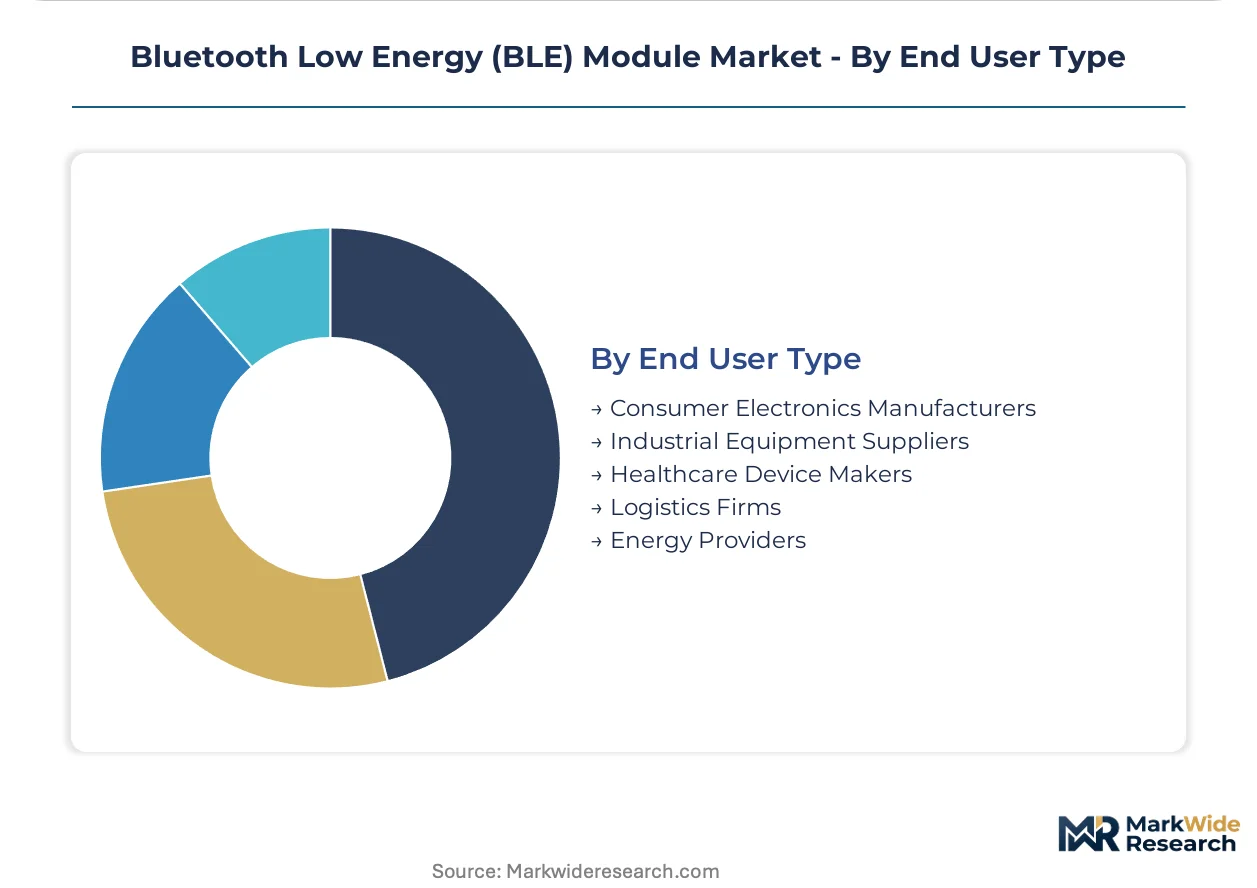
Buyer sophistication and regulatory exposure vary dramatically, from consumer electronics manufacturers optimizing unit economics to healthcare device makers navigating FDA wireless cybersecurity guidance.
- Consumer Electronics Manufacturers:High-volume, price-sensitive procurement with compressed development cycles, dominating integrated module uptake in fitness tracker and hearable production. BOM cost elevation tolerance of 15-40% constrains adoption of premium system-in-package offerings.
- Healthcare Device Makers:FDA-regulated manufacturers requiring documented Q-Sub correspondence and pre-certified modules for 510(k) streamlining, consolidating purchasing through enterprise master service agreements at US health systems exceeding 500 beds. Post-market surveillance obligations under EU MDR favor suppliers with established notified body relationships.
- Industrial Equipment Suppliers:Long qualification horizons with temperature range and reliability prioritization.
- Logistics Firms:Asset tracking deployments emphasizing multi-region certification coverage.
- Energy Providers:Smart grid infrastructure with utility-grade reliability specifications.
Consumer electronics manufacturers lead volumes today; healthcare device makers are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing BLE module procurement patterns as manufacturers migrate toward jurisdictions with streamlined pre-certification frameworks. The cost-of-compliance gap between FCC Part 15 pre-approval and end-product testing obligations in multi-region deployments is concentrating supplier selection decisions in specific national markets.
United States
Hospital procurement consolidation across IDN networks exceeding 500 beds is standardizing BLE module specifications for connected physiologic monitors. FDA wireless medical device cybersecurity guidance is tightening design requirements for radio modules seeking streamlined 510(k) pathways. Greater Boston and the Pacific Northwest host dense clusters of medical device OEMs qualifying pre-certified modules with documented Q-Sub correspondence.
Germany
Factory digitization programs across Baden-Württemberg and Bavaria are concentrating demand for industrial-temperature-range modules in predictive maintenance sensors. The EU Radio Equipment Directive's 2024 cybersecurity baseline is mandating secure boot capabilities for CE marking eligibility. Stuttgart's automotive supplier parks anchor qualification programs for -40°C to +85°C qualified modules serving tier-one manufacturers.
China
Domestic wearable OEMs in Shenzhen and Dongguan are absorbing integrated system-in-package modules to compress BOM line items in fitness tracker production. MIIT radio type approval requirements are adding certification layers for modules targeting the domestic consumer electronics market. The Pearl River Delta's electronics manufacturing corridor is consolidating procurement for hearable and disposable diagnostic patch applications.
Japan
Industrial automation retrofits in the Chubu region around Nagoya are demanding standalone modules with legacy PLC protocol flexibility. METI's energy efficiency standards are elevating sub-milliwatt standby current specifications for battery-operated sensor deployments. Osaka-based medical device manufacturers are pre-qualifying vendors with established PMDA consultation documentation for wireless connectivity components.
South Korea
Seoul Capital Area electronics conglomerates are driving Bluetooth 5.2 LE Audio module adoption in premium hearable product lines. MFDS medical device regulations are adding post-market surveillance obligations for wireless connectivity in continuous glucose monitoring patches. Suwon and Pangyo technology corridors host design centers specifying ultra-low power variants for energy harvesting applications.
Bluetooth Low Energy (BLE) Module Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated module vendors capturing premium positioning in space-constrained designs while discrete transceiver suppliers defend industrial retrofit volumes. The vendor base concentrates around semiconductor firms with proprietary RF process technology and development ecosystem depth. Three archetypes dominate: integrated system-in-package specialists, industrial-temperature-range foundry operators, and multi-protocol platform aggregators. Competitive moves center on firmware subscription monetization and notified body relationship deepening for EU MDR compliance.
Among Nordic-origin semiconductor specialists, Nordic Semiconductor occupies a position exemplifying the integrated ecosystem archetype through its developer tool penetration. Texas Instruments represents the industrial-temperature-range foundry tier with proprietary RF process technology. STMicroelectronics sits within the multi-protocol platform category, anchoring European supplier qualification programs with established CE marking documentation depth.
| Leading Market Players |
|---|
| Nordic Semiconductor |
| Texas Instruments |
| STMicroelectronics |
| Silicon Laboratories |
| NXP Semiconductors |
| Infineon Technologies |
| Renesas Electronics |
| Toshiba Corporation |
| Intel Corporation |
| Others |
Value Chain & Pricing Dynamics
System-in-package integration is compressing board area requirements while simultaneously concentrating procurement leverage among a handful of foundry operators with proprietary RF process technology. This consolidation of manufacturing capability is elevating cost premiums for industrial-temperature-range modules while eroding margin pools for discrete transceiver suppliers serving legacy retrofit applications.
Pricing Analysis
Distributor margins on BLE modules compress as direct-to-OEM volume commitments unlock tiered discount structures. Pricing stratifies across certification-grade tiers, with FDA pre-certified modules commanding substantial premiums over baseline FCC Part 15 variants. Cost pressure stems from integrated application processor consolidation, which elevates BOM outlays 15-40% versus standalone implementations. Consumer electronics manufacturers exhibit acute price sensitivity, while healthcare device makers absorbing enterprise master service agreements prioritize validation documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Taiwan, and the United States anchor hub-and-spoke fulfillment patterns for multi-region medical device rollouts. Semiconductor wafer fabrication draws from South Korean and Taiwanese foundry capacity, with packaging and test operations concentrated in Malaysia and Vietnam. Single-source vulnerability persists for -40°C to +85°C qualified modules where proprietary RF process technology remains captive to limited suppliers. Distribution runs through authorized distributor networks serving industrial automation corridors, with direct fulfillment gaining share among high-volume wearable OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The BLE module market functions as a regulatory compounder where EU MDR transition deadlines and FDA cybersecurity guidance are accelerating procurement consolidation among pre-qualified vendors.
For Market Incumbents: Acquire firmware subscription capabilities and notified body relationships to deepen post-deployment revenue streams. Defensive positioning demands backward integration into secure boot IP and Common Criteria evaluation facilities as the EU Radio Equipment Directive's cybersecurity baselines narrow approved supplier lists. Capacity expansion in Germany's industrial automation corridor anchors qualification programs for automotive tier-one suppliers. For New Entrants and Emerging Players: Ultra-low power energy harvesting compatibility offers a technology-first wedge into disposable diagnostic patches where battery replacement is impractical. White-space concentration sits in continuous glucose monitoring applications and industrial retrofit sensors requiring legacy PLC protocol flexibility. A development ecosystem partnership strategy with Shenzhen-based wearable OEMs accelerates design-win velocity without front-loaded certification investment. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone transceiver specialists facing margin compression from system-in-package consolidation. Long-term viability over a 5-10 year window favors vendors with established FDA Q-Sub correspondence and EU notified body relationships. The signal to watch is hospital procurement consolidation across US health systems exceeding 500 beds, where enterprise master service agreements are displacing fragmented clinical engineering purchasing.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Monetization | Recurring revenue from over-the-air updates decouples vendor economics from unit shipment volumes. |
| EU MDR Notified Body Deepening | Technical documentation depth accelerates CE marking pathways for wireless medical device deployments. |
| Secure Boot IP Acquisition | Hardware cryptographic engines satisfy EU Radio Equipment Directive cybersecurity baseline mandates. |
| Industrial Temperature Range Qualification | -40°C to +85°C certification opens procurement at Stuttgart's automotive supplier parks. |
| Energy Harvesting Compatibility Development | Sub-microamp sleep currents enable battery-free disposable sensor applications in continuous glucose monitoring. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with BLE module procurement managers, biomedical engineers at US health systems, regulatory affairs leads at medical device OEMs, and RF design engineers at wearable manufacturers with secondary validation against FCC equipment authorization databases, FDA 510(k) filings, EU MDR technical documentation, and semiconductor customs trade records. Bottom-up segment sizing and top-down market triangulation cross-checked volume assumptions.
Segment-weighting approaches distributed value across module type, protocol generation, application area, and end user type dimensions. CAGRs derived from fitted growth curves incorporating adoption trajectories for Bluetooth 5.1 direction-finding in hospital asset tracking and energy harvesting integration in disposable diagnostics. Forecast inputs included factory digitization program commitments across Baden-Württemberg and hospital procurement consolidation timelines at IDN networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement timing and FDA wireless cybersecurity guidance evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Zigbee Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Middle East and Africa Marine Communication Systems Market