
 High Reliability Oscillators Market | 2026-2036
High Reliability Oscillators Market Size, Share, and Industry Trends Forecast 2026-2036
High Reliability Oscillators Market Insights
Defense contractors is reorganizing procurement priorities around radiation-hardened and space-qualified timing components, pulling volume away from legacy industrial automation buyers. Seiko Epson Corporation leverages its vertical integration in quartz crystal growing to sustain supply security for aerospace programs. Murata Manufacturing anchors its position through ceramic packaging expertise that meets hermetic sealing standards for satellite payloads. SiTime Corporation differentiates via MEMS-based architectures that tolerate shock and vibration beyond quartz limits.
High reliability oscillators are precision frequency control devices engineered to maintain stability across temperature extremes, radiation exposure, and mechanical stress, typically achieving phase noise below -150 dBc per Hz and aging rates under 1 part per billion annually. These devices synchronize data transmission, navigation signals, and radar systems where timing jitter causes system failure. OCXO variants command the richest margin pools due to oven-controlled thermal compensation and weeks-long burn-in protocols. MEMS oscillators represent the fastest-expanding technology segment as factory automation firms adopt silicon-based alternatives for vibration-intense environments. Quartz technology retains dominance in telecom infrastructure where holdover stability requirements exceed 24 hours.
FAA certification standards for avionics timing and the U.S. Department of Defense MIL-PRF-55310 specification constrain market entry through multi-year qualification cycles and traceability mandates. ISO 9001 and AS9100 quality frameworks further segment suppliers by audit depth and counterfeit mitigation protocols. Stakeholders must monitor how export control expansions affect crystal raw material sourcing from restricted mining jurisdictions.
Market Dynamics
Defense procurement reorganization around radiation-hardened timing components is pulling volume away from legacy industrial automation buyers, while satellite constellation deployment schedules compress qualification timelines for oscillator suppliers.
Growth Catalysts
- LEO constellation expansion:Satellite manufacturers are scaling procurement of space-qualified oscillators for low-Earth orbit networks, creating sustained demand for hermetic packaging and radiation tolerance.
- MIL-PRF-55310 threshold tightening:The U.S. Department of Defense is raising performance requirements for military-grade oscillators, forcing supplier upgrades that filter into adjacent high-reliability segments.
- MEMS architecture maturation:Silicon-based resonators now tolerate shock and vibration beyond quartz limits, opening factory automation and aerospace applications previously closed to non-crystal technologies.
Market Restraints
- Raw material concentration:High-purity quartz crystal supply concentrates in limited mining jurisdictions, exposing the supply chain to export control disruptions and geopolitical friction.
- Qualification timeline drag:FAA avionics certification and MIL-PRF-55310 traceability mandates impose multi-year validation cycles that delay revenue recognition for new entrants.
- OCXO cost structure:Oven-controlled crystal oscillators require weeks-long burn-in protocols and precision thermal compensation, locking in premium pricing that limits addressable market expansion.
Strategic Opportunities
- India defense electronics:The country's PLI scheme for semiconductor manufacturing creates localized oscillator demand for indigenous radar and navigation programs.
- Automotive lidar timing:Autonomous vehicle sensor arrays require jitter performance below 100 femtoseconds, opening a new specification tier between industrial and aerospace grades.
- Quantum computing clock distribution:Cryogenic oscillator architectures capable of operating at millikelvin temperatures represent an emerging application with limited incumbent competition.
Industry Challenges
- Counterfeit mitigation protocols:AS9100 and ISO 9001 frameworks now mandate component traceability to the crystal growing batch, requiring expensive ERP upgrades for smaller suppliers.
- Legacy system integration friction:Telecom infrastructure holdover requirements exceeding 24 hours lock in quartz-dominated architectures, complicating MEMS substitution efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Reliability Oscillators Market |
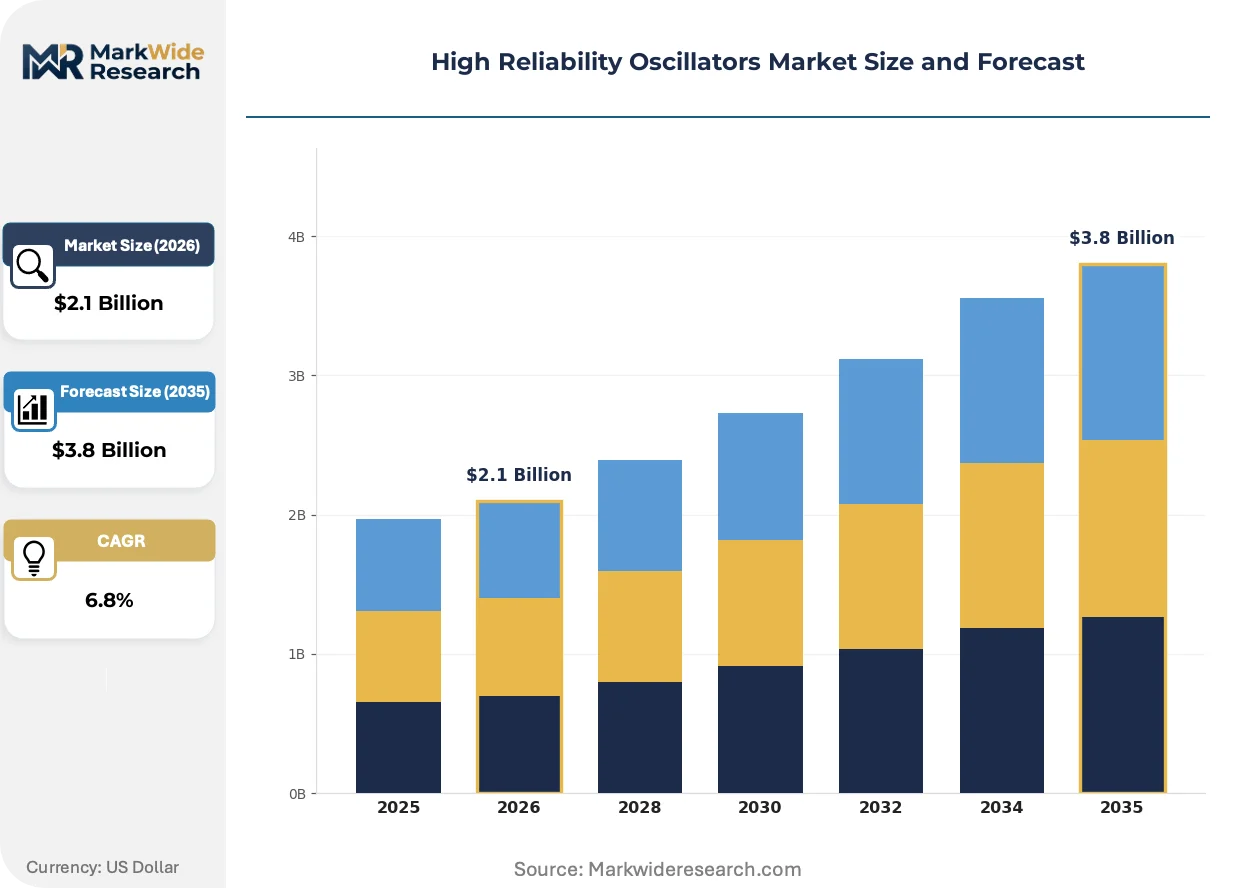
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TCXO, OCXO, VCXO, SCXO, MEMS Oscillators Technology: Quartz, MEMS, SAW, Silicon Oscillators Application: Aerospace & Satellite, Telecom Infrastructure, Defense Electronics, Industrial Automation, Scientific Instruments End User: Satellite Manufacturers, Network Equipment Providers, Defense Contractors, Factory Automation Firms |
| Companies Covered | Seiko Epson Corporation, Murata Manufacturing, Kyocera Corporation, Nihon Dempa Kogyo, TXC Corporation, Daishinku Corp., SiTime Corporation, Microchip Technology, Rakon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Reliability Oscillators Market Trends and Innovations
Precision timing architectures are diverging across temperature compensation methods, with thermal management innovations competing against silicon-based alternatives for dominance in vibration-intense environments.
MEMS resonator technology is fragmenting the traditional quartz monopoly in aerospace applications. Silicon-based oscillators now achieve phase noise performance approaching -140 dBc per Hz at 10 kHz offset. Factory automation firms in Germany and Japan are adopting these devices for robotic assembly lines where mechanical shock exceeds 50,000 g. The structural consequence is compressing margin pools for mid-grade crystal suppliers unable to match MEMS shock tolerance or OCXO stability.
REACH substance restrictions in Europe are forcing ceramic packaging reformulations for hermetic seals. The ECHA candidate list now scrutinizes lead-based glass frits used in traditional oscillator enclosures. Satellite payload integrators in France and Germany are accelerating qualification of alternative sealing materials ahead of anticipated SVHC designation. This regulatory pressure is compressing the supplier base to those with materials science capabilities spanning quartz growing, ceramic metallization, and polymer seal development.
Prime contractors are consolidating oscillator procurement through direct supplier relationships rather than distribution channels. Lockheed Martin and Northrop Grumman now require lot-specific radiation test data and burn-in records for every timing device. This disintermediation is displacing traditional electronics distributors in California's aerospace corridor. The shift is most visible in Los Angeles and Bay Area defense clusters, where vendor-managed inventory programs now dominate oscillator logistics.
High Reliability Oscillators Market Segmentation
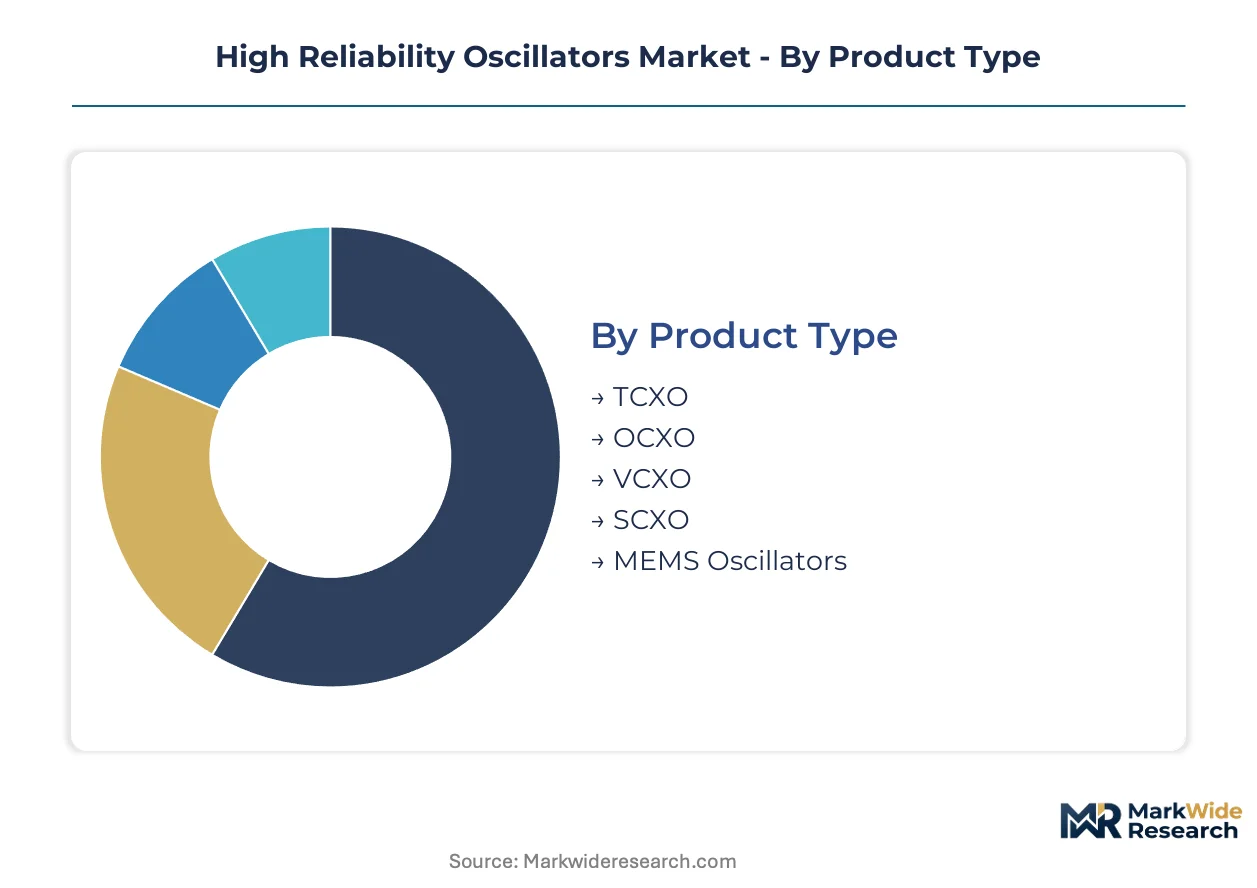
High reliability oscillators segment across multiple dimensions that determine qualification pathways, margin structures, and channel access. Product type and technology choices lock in performance ceilings and supply chain dependencies, while application and end-user categories dictate certification requirements and procurement timelines.
Product Type:
Channel distribution varies sharply by product type, with OCXO and MEMS oscillators flowing through direct prime contractor relationships while TCXO and VCXO variants retain broader distribution coverage.
- OCXO:Oven-controlled crystal oscillators achieve sub-ppb stability through precision thermal compensation and weeks-long burn-in protocols. Defense electronics programs in the United States absorb the majority of volume, driven by MIL-PRF-55310 threshold tightening that filters performance requirements upward.
- MEMS Oscillators:Silicon-based resonators tolerate mechanical shock exceeding 50,000 g, opening factory automation applications previously closed to crystal technologies. German and Japanese robotic assembly lines are converting procurement specifications to MEMS architectures for vibration-intense environments.
- TCXO:Temperature-compensated crystal oscillators balance cost and stability for telecom infrastructure holdover requirements.
- VCXO:Voltage-controlled variants serve phase-locked loop applications in network synchronization equipment.
- SCXO:Simple packaged crystal oscillators address cost-sensitive industrial timing needs with reduced environmental tolerance.
By volume, TCXO leads through telecom infrastructure scale. By growth pace, MEMS oscillators are climbing the fastest as aerospace qualification timelines compress.
Technology:
Cost tier stratification separates mature quartz architectures from emerging silicon alternatives, with SAW devices occupying a narrow premium niche for specialized frequency control.
- Quartz:Mature crystal growing and cutting processes deliver phase noise below -150 dBc per Hz for satellite payload timing. California's aerospace corridor concentrates demand, where prime contractors cluster near Los Angeles and the Bay Area for hermetic packaging integration.
- MEMS:Semiconductor fabrication enables batch processing and shock tolerance beyond quartz mechanical limits. Factory automation firms are adopting these devices for robotic environments where vibration previously mandated crystal architectures.
- SAW:Surface acoustic wave technology serves surface-mount frequency control with moderate stability requirements.
- Silicon Oscillators:CMOS-compatible timing devices integrate directly with digital systems for cost-sensitive consumer-grade applications.
By revenue concentration, quartz dominates through aerospace and defense procurement. By technology transition momentum, MEMS is gaining share fastest in industrial segments.
Application:
Application mix determines margin tier, with aerospace and satellite programs commanding premium pricing through radiation-hardening requirements while industrial automation operates at standard reliability grades.
- Aerospace & Satellite:Low-Earth orbit constellations demand hermetic packaging and radiation tolerance for timing synchronization across distributed satellite networks. Seiko Epson Corporation and Murata Manufacturing anchor supply positions through vertical integration in quartz crystal growing and ceramic packaging respectively.
- Defense Electronics:MIL-PRF-55310 qualification mandates traceability to crystal growing batch and multi-year validation cycles. The U.S. Department of Defense's tightening performance thresholds are forcing supplier upgrades that propagate into adjacent high-reliability segments.
- Telecom Infrastructure:Holdover stability requirements exceeding 24 hours lock in quartz-dominated architectures for network synchronization.
- Industrial Automation:Vibration-intense environments are converting to MEMS alternatives as shock tolerance specifications rise.
- Scientific Instruments:Precision measurement applications require aging rates under 1 part per billion annually for long-term calibration stability.
By program value, aerospace and satellite leads. By specification velocity, defense electronics is expanding most quickly through procurement reorganization.
End User:
Customer type shapes procurement modality, with satellite manufacturers and defense contractors consolidating direct supplier relationships while network equipment providers retain distribution channel access.
- Satellite Manufacturers:Low-Earth orbit constellation deployment compresses qualification timelines and demands lot-specific radiation test data. Lockheed Martin and Northrop Grumman now require burn-in records for every timing device, displacing traditional electronics distributors in California's aerospace corridor.
- Defense Contractors:Procurement reorganization around radiation-hardened timing components is pulling volume away from legacy industrial automation buyers. SiTime Corporation differentiates through MEMS-based architectures that meet emerging shock and vibration specifications.
- Network Equipment Providers:Telecom infrastructure buyers prioritize holdover stability and supply security for base station synchronization.
- Factory Automation Firms:German and Japanese manufacturers are adopting MEMS oscillators for robotic assembly lines where mechanical stress exceeds traditional crystal limits.
By contract scale, defense contractors lead. By procurement modality shift, satellite manufacturers are restructuring supplier relationships fastest through direct vendor-managed inventory programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision timing components to aerospace clusters in California and satellite integrators across France and Germany, establishing the dominant trade corridor for radiation-hardened oscillators serving low-Earth orbit constellations.
United States
The U.S. Department of Defense's MIL-PRF-55310 threshold tightening is forcing supplier upgrades across defense electronics programs. FAA certification standards for avionics timing constrain market entry through multi-year validation cycles. Prime contractors in Los Angeles and the Bay Area now require lot-specific radiation test data and burn-in records for every timing device, displacing traditional electronics distributors.
Japan
Domestic satellite manufacturers and factory automation firms are scaling procurement of space-qualified and vibration-tolerant timing devices. METI industrial standards and JIS certification frameworks govern precision component quality. Tokyo and Osaka anchor production clusters where quartz crystal growing and ceramic packaging expertise concentrate for aerospace supply security.
Germany
REACH substance restrictions are forcing ceramic packaging reformulations for hermetic seals used in satellite payloads. ECHA scrutiny of lead-based glass frits is accelerating qualification of alternative sealing materials. Satellite payload integrators in Munich and Stuttgart are compressing supplier bases to those with materials science capabilities spanning metallization and polymer seal development.
France
Space agency procurement for low-Earth orbit networks is driving demand for radiation-tolerant timing synchronization across distributed satellite architectures. ANSM and CNIL data protection frameworks intersect with aerospace traceability mandates for component batch tracking. Toulouse and Paris host prime contractor clusters where direct vendor-managed inventory programs now dominate oscillator logistics.
India
The PLI scheme for semiconductor manufacturing is creating localized oscillator demand for indigenous radar and navigation programs. BIS quality standards and DGFT export control administration shape component sourcing protocols. Bengaluru and Hyderabad defense electronics clusters are reorganizing procurement priorities around radiation-hardened timing components for domestic military programs.
High Reliability Oscillators Market Competitive Landscape
Listed leaders compete with private specialists across qualification depth and supply chain control, producing a tiered structure where public companies dominate volume and private entities capture premium niches. The vendor base stratifies into three archetypes: vertically integrated quartz growers, MEMS architecture specialists, and ceramic packaging integrators. Competitive moves concentrate on backward integration into crystal raw material sourcing and strategic partnerships for radiation-hardening certification.
Within the vertical integration tier, Seiko Epson Corporation and Murata Manufacturing exemplify supply security strategies through captive quartz crystal growing and ceramic packaging expertise respectively. SiTime Corporation occupies a position as the MEMS architecture anchor, representing silicon-based alternatives that tolerate mechanical stress beyond traditional crystal limits. These three entities collectively span the technology spectrum from precision thermal compensation to semiconductor fabrication, anchoring competitive positioning across aerospace, defense, and industrial automation segments.
| Leading Market Players |
|---|
| Seiko Epson Corporation |
| Murata Manufacturing |
| Kyocera Corporation |
| Nihon Dempa Kogyo |
| TXC Corporation |
| Daishinku Corp. |
| SiTime Corporation |
| Microchip Technology |
| Rakon |
| Others |
Pricing and Supply Chain Analysis
MIL-PRF-55310 qualification requirements simultaneously gate supply entry and stratify price tiers, with traceability mandates to crystal growing batch imposing ERP upgrade costs that filter into premium pricing for defense-grade oscillators while compressing margins for suppliers unable to absorb multi-year validation cycles.
Pricing Analysis
OCXO-to-MEMS-to-TCXO generational pricing spreads reflect performance ceiling differentials, with oven-controlled variants commanding premium positioning through weeks-long burn-in protocols while silicon-based alternatives capture mid-tier value through semiconductor batch processing economies. Three-tier pricing structure across aerospace-certified, industrial-grade, and commercial-temperature segments separates buyers by qualification depth and radiation-hardening requirements. Cost compression in MEMS architectures is intensifying because factory automation procurement is shifting volume toward shock-tolerant silicon alternatives. Satellite manufacturers exhibit lowest price sensitivity due to mission-critical timing requirements, while network equipment providers negotiate aggressively on TCXO volume contracts.
Supply Chain Analysis
Vendor-managed inventory programs now dominate oscillator logistics in California's aerospace corridor, compressing lead times for qualified suppliers while extending validation queues for new entrants. High-purity quartz crystal supply concentrates in limited mining jurisdictions, with ceramic packaging feedstock anchored in Japan and hermetic sealing expertise clustering in Germany. Raw material dependencies span synthetic quartz boules, lead-free glass frits under ECHA scrutiny, and radiation-hardened semiconductor substrates. Single-source vulnerability concentrates in crystal growing batch traceability systems mandated by AS9100 frameworks. Distribution runs through direct prime contractor relationships for OCXO and MEMS variants, with TCXO and VCXO retaining broader authorized distributor coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision timing is shifting toward platform-standardized architectures where MEMS interoperability with digital systems creates ecosystem lock-in effects previously reserved for quartz-dominated telecom infrastructure.
For Market Incumbents: Secure backward integration into synthetic quartz boule production to defend against MEMS substitution in aerospace applications, while accelerating radiation-hardening certification for silicon-based architectures to capture emerging LEO constellation volume. Lockheed Martin and Northrop Grumman procurement consolidation threatens distributor-dependent suppliers. Channel control through vendor-managed inventory programs in Los Angeles and Bay Area defense clusters represents the critical defensive lever. For New Entrants and Emerging Players: FAA certification fast-track programs for avionics timing offer accelerated market entry pathways for MEMS specialists targeting automotive lidar segments where jitter specifications below 100 femtoseconds create specification gaps between industrial and aerospace grades. Factory automation in Germany and Japan presents the most penetrable white-space for shock-tolerant silicon alternatives. Direct engagement with robotic assembly line procurement teams bypasses entrenched quartz distributor relationships. For Investors and Strategic Acquirers: ECHA SVHC designation timelines for lead-based glass frits reshape the acquisition landscape toward materials science capabilities spanning ceramic metallization and polymer seal development. Long-term viability over the next decade hinges on positioning for post-REACH hermetic packaging reformulations rather than legacy quartz cutting expertise. Acquisition targets should demonstrate captive crystal growing or MEMS fabrication assets with existing aerospace qualification records. The signal to monitor is compression of approved supplier lists at prime contractors as lot-specific radiation test data requirements tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardening Certification Investment | MIL-PRF-55310 qualification unlocks defense electronics procurement previously closed to industrial-grade suppliers. |
| MEMS Architecture Scale-Up | Semiconductor fabrication expansion captures factory automation volume converting from quartz shock limitations. |
| Ceramic Packaging Reformulation | Lead-free hermetic seal qualification ahead of ECHA SVHC designation secures satellite payload integrator relationships. |
| Direct Prime Contractor Engagement | Vendor-managed inventory programs in California displace traditional electronics distributors for OCXO procurement. |
| Synthetic Quartz Boule Integration | Captive crystal growing secures supply continuity against export control disruptions in restricted mining jurisdictions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across oscillator procurement, fabrication, and integration roles. Primary interviews engaged satellite payload engineers, defense electronics procurement officers, MEMS fabrication specialists, ceramic packaging metallurgists, and factory automation system integrators. Secondary validation drew from FAA certification databases, MIL-PRF-55310 specification revisions, ECHA candidate list updates, and customs trade records for quartz crystal imports. Bottom-up segment sizing triangulated against top-down aerospace and defense budget allocations.
Across the analysis window, forecasts model technology transition momentum from quartz to MEMS architectures, product type evolution across OCXO and TCXO segments, application penetration in aerospace versus industrial automation, and end-user procurement modality shifts toward direct supplier relationships. CAGRs derive from segment-level volume projections calibrated to satellite constellation deployment schedules and defense electronics modernization timelines. Industry-specific inputs include radiation-hardening qualification cycle durations and REACH substance restriction implementation trajectories.
Underlying assumptions cover sustained LEO constellation deployment, stable export control regimes for crystal raw materials, and MEMS phase noise performance convergence toward quartz benchmarks, with deviation risk concentrated in qualification timeline extensions and ceramic packaging material substitution delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RFID Tags Market
RF Components
Flat Panel Antenna Market
RF Components
Gaas RF Switch Market
RF Components
RF Power Dividers Market
RF Components
UHF RFID Inlays Market
RF Components
Digital Radio Frequency Memory Market
RF Components
RF Transceiver Chip Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
Phase Shifters Market
RF Components
Radio Frequency Components Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
FBAR Devices Market
RF Components
Digital Phase Shifter Market
RF Components
Power Amplifier Market
RF Components
RF Duplexer Market
RF Components
Silicon Tuners Market