
 Ethernet PHY Chip Market | 2026-2036
Ethernet PHY Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet PHY Chip Market Intelligence
The EU's Restriction of Hazardous Substances (RoHS) directive is expanding the compliance burden for semiconductor manufacturers, altering the cost calculus for market entry. Broadcom Inc. leverages its extensive IP portfolio in high-speed networking to address complex data center requirements. Marvell Technology Group Ltd. specializes in automotive and enterprise networking solutions, navigating specific end-market standards. These firms compete on performance metrics and power efficiency to secure design wins with original equipment manufacturers.
An Ethernet PHY chip is a physical layer transceiver that implements the physical signaling for data transmission over copper or fiber cables. These components manage analog-to-digital conversion and signal integrity for specific speeds, such as 10 Gigabit PHY. Within applications, data centers and enterprise networking constitute the largest demand segments due to bandwidth escalation. The 10 Gigabit PHY product type is becoming mainstream, while 25 Gigabit PHYs represent the fastest-growing category, driven by cloud and AI infrastructure.
Compliance with electromagnetic interference standards, such as the FCC Part 15 rules in the United States and CE marking requirements in Europe, is mandatory for market access. Additionally, ISO/IEC standards define interoperability and performance criteria for network components, influencing design and testing protocols. Stakeholders must now decide how to balance investments between mature Gigabit Ethernet technologies and emerging Multi-Gig Ethernet solutions to capture future growth.
Market Dynamics
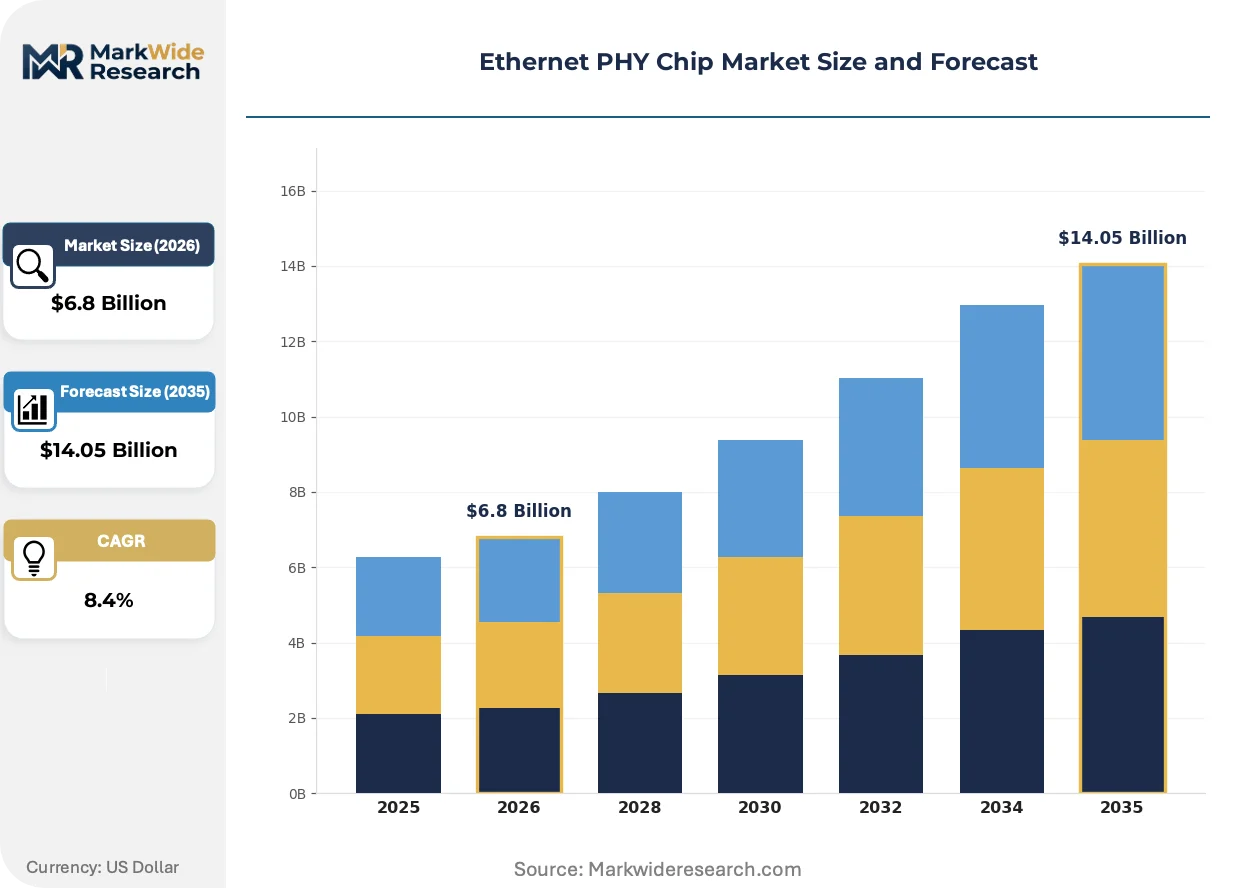
The Ethernet PHY chip market is defined by the strategic tension between servicing the massive installed base of Gigabit Ethernet and allocating R&D capital toward next-generation Multi-Gigabit standards. This dynamic forces vendors to balance investments, addressing current volume demand while positioning for future growth in high-bandwidth applications like AI infrastructure and industrial automation.
Growth Catalysts
- Industrial Automation:The deployment of smart factories and industrial IoT in manufacturing hubs, particularly in China, requires reliable, high-speed Ethernet for real-time data processing and machine-to-machine communication.
- Multi-Gigabit Standards:The shift to 2.5G, 5G, and 10G Ethernet in enterprise and campus networks is driven by the need to support bandwidth-intensive Wi-Fi 6/7 access points and eliminate network bottlenecks.
- Automotive Connectivity:Advanced Driver-Assistance Systems (ADAS) and in-vehicle infotainment (IVI) systems are fueling demand for automotive-grade Ethernet PHYs capable of handling high data volumes within the vehicle network architecture.
Market Restraints
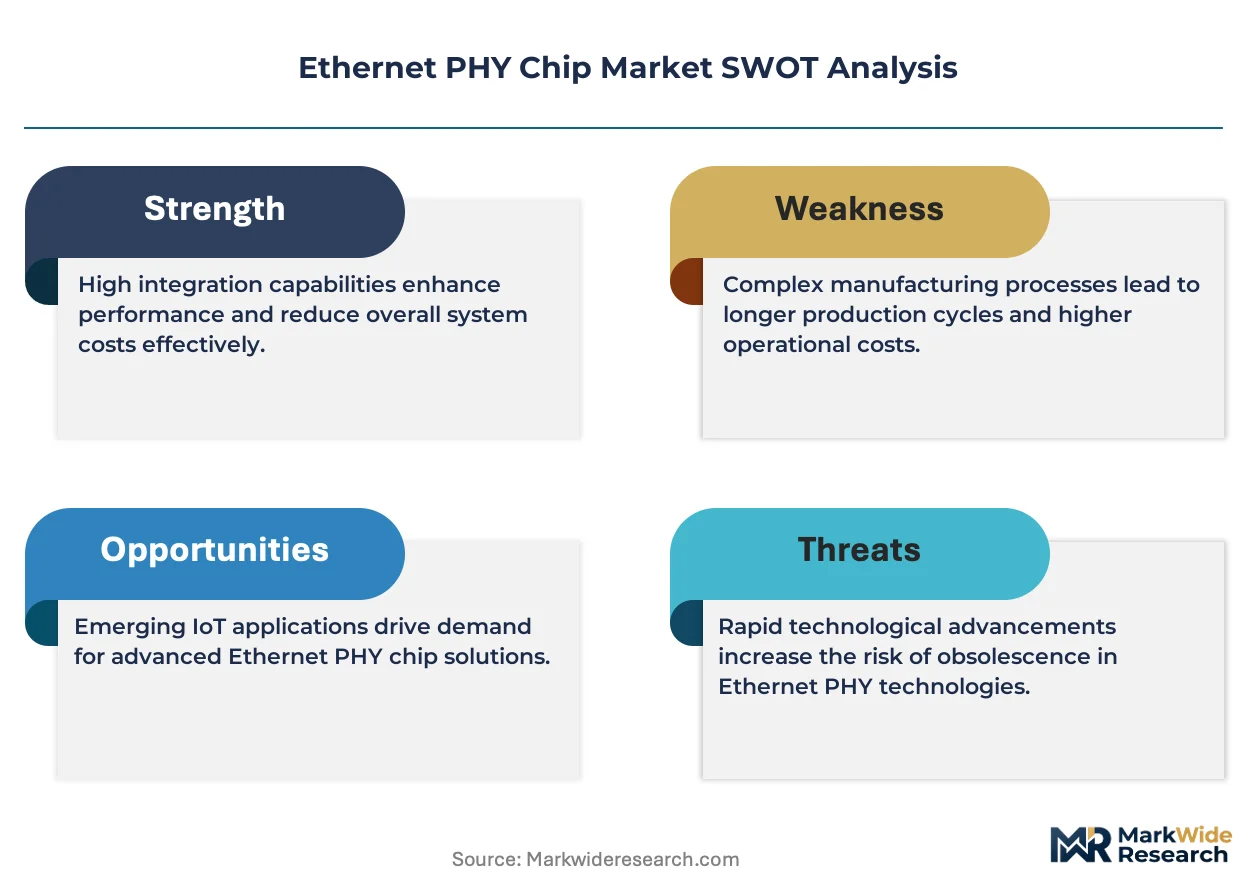
- Compliance Burden:Expanding environmental regulations, such as the EU's RoHS directive, increase the cost and complexity of semiconductor manufacturing, altering the financial calculus for new market entrants.
- Technical Trade-Offs:Achieving higher data rates in 25G and faster PHYs presents significant signal integrity and power consumption challenges, complicating chip design and increasing system-level thermal management requirements.
- Supply Chain Concentration:The reliance on a limited number of advanced semiconductor foundries, primarily located in East Asia, creates potential bottlenecks and supply chain risks for PHY chip production.
Strategic Opportunities
- Single-Pair Ethernet (SPE):The emergence of SPE standards like 10BASE-T1L creates a significant opportunity to extend Ethernet connectivity to field-level industrial devices, sensors, and actuators over simplified, long-reach cabling.
- Time-Sensitive Networking (TSN):Integrating TSN capabilities directly into PHY chips offers a pathway to capture demand in markets requiring deterministic, low-latency communication, including industrial robotics, professional audio/video, and automotive control systems.
- Emerging Data Center Hubs:Rapid cloud adoption and digital infrastructure build-outs in geographies like India and Southeast Asia present new growth frontiers for vendors of high-speed data center PHYs.
Industry Challenges
- Interoperability and Compliance:Ensuring PHYs from different vendors are fully interoperable and compliant with both performance standards like ISO/IEC and electromagnetic compatibility rules like FCC Part 15 is a persistent and resource-intensive challenge.
- Legacy System Integration:Integrating new Multi-Gigabit PHYs with existing network infrastructure often presents technical hurdles, potentially slowing down adoption cycles in brownfield enterprise environments.
- Specialized Talent Scarcity:A shortage of experienced analog and mixed-signal design engineers capable of developing power-efficient, high-speed PHY transceivers acts as a constraint on innovation and product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet PHY Chip Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 10/100Mbps PHY, Gigabit PHY, 10 Gigabit PHY, 25 Gigabit PHY, 40 Gigabit PHY Technology: Copper Ethernet, Fiber Ethernet, Multi-Gig Ethernet, Automotive Ethernet, Industrial Ethernet Application: Data Centers, Enterprise Networking, Consumer Electronics, Industrial Automation, Telecom Infrastructure Customer Type: Original Equipment Manufacturers, Network Service Providers, System Integrators, Value-Added Resellers, Semiconductor Companies |
| Companies Covered | NXP Semiconductors N.V., Realtek Semiconductor Corp., Broadcom Inc., Analog Devices, Inc., Intel Corporation, Marvell Technology Group Ltd., Microchip Technology Inc., Qualcomm Incorporated, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet PHY Chip Market Strategic Shifts & Innovations
Power efficiency and thermal performance are becoming central design vectors, influencing technology choices beyond raw data rates. This shift reflects the integration of high-speed Ethernet into increasingly dense and power-constrained environments, from automotive applications to edge computing hardware.
Multi-Gigabit Ethernet technology enables data rates of 2.5 Gbps, 5 Gbps, and 10 Gbps over existing Cat5e and Cat6 copper cabling. Enterprise network administrators are adopting these solutions to upgrade campus backbones and support new Wi-Fi 6 and Wi-Fi 7 access points without costly cable replacement. As a result, native Multi-Gigabit support is overtaking legacy 1-Gigabit-only functionality in the design of new enterprise switches and routers.
The European Union's Restriction of Hazardous Substances (RoHS) directive is a key regulatory driver impacting component design. This rule mandates strict limits on materials like lead and mercury in electronics, compelling chipmakers to adopt compliant materials and manufacturing processes. The automotive segment is particularly affected, as PHYs must meet both RoHS and stringent AEC-Q100 reliability qualifications, adding significant testing and validation overhead.
A distinct behavioral shift is occurring where original equipment manufacturers (OEMs) prioritize a PHY's power-per-gigabit metric as a primary selection criterion. This moves vendor evaluation beyond simple component cost to a more holistic assessment of total system power consumption and cooling requirements. This emphasis on efficiency is most pronounced in the hyper-scale data center and fanless industrial computing sectors, where energy costs and thermal limits are critical operational constraints.
Ethernet PHY Chip Market Segmentation
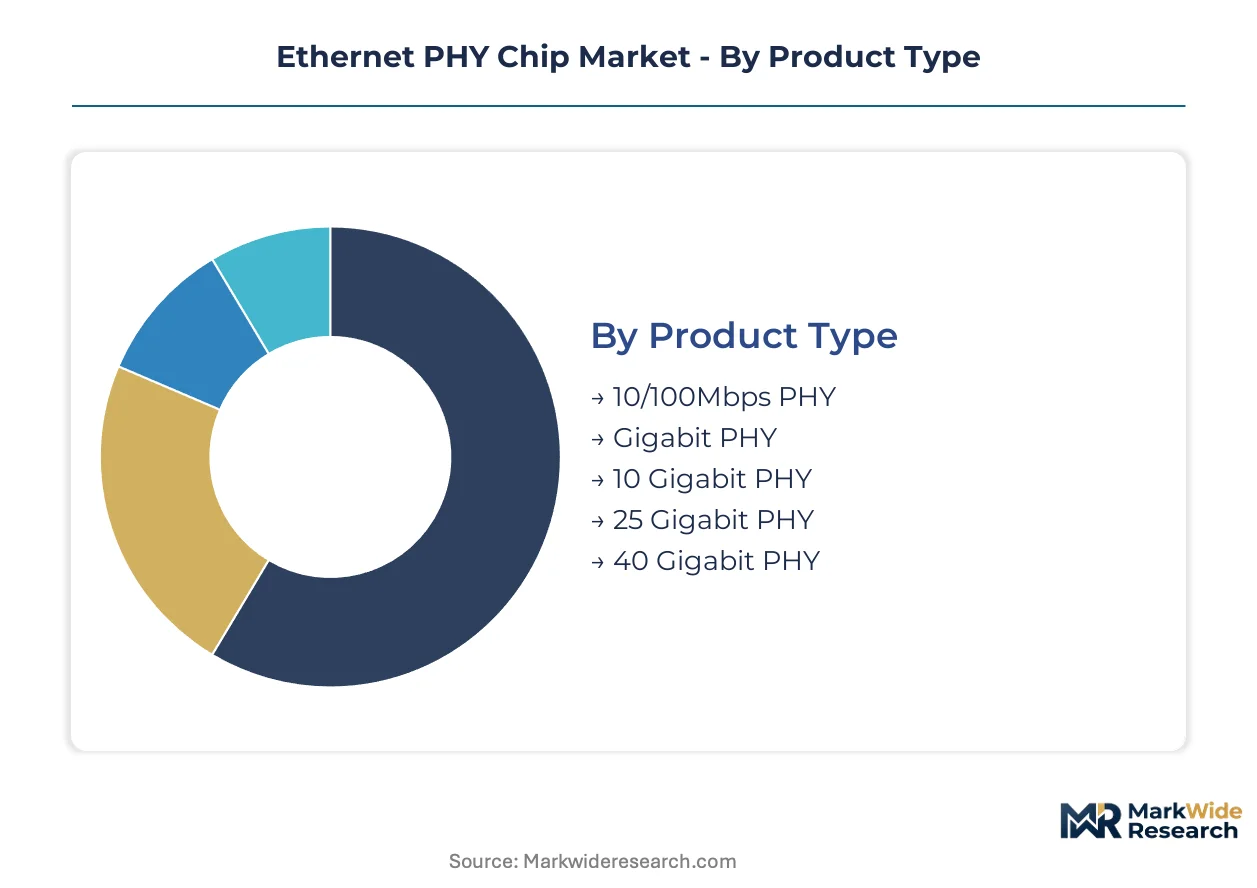
The Ethernet PHY chip market segments across various dimensions, reflecting diverse technical requirements and end-user applications. Understanding these segments helps stakeholders allocate research and development capital effectively and target specific growth opportunities within the evolving connectivity landscape.
Product Type:
Segments requiring significant upfront capital investment in design and fabrication shape the product type landscape.
- 10 Gigabit PHY:These transceivers support 10 Gbps data rates, operating over both copper and fiber optic cables. Demand for 10 Gigabit PHYs is becoming mainstream within enterprise networking and smaller data center deployments due to increasing bandwidth needs.
- 25 Gigabit PHY:This product type implements 25 Gbps physical layer signaling, primarily for cloud infrastructure and AI computing environments. The 25 Gigabit PHY represents the fastest-growing category, driven by hyperscale data center expansion and high-performance computing requirements.
- Gigabit PHY:These chips provide 1 Gbps connectivity, forming the backbone of many legacy enterprise networks and industrial control systems.
- 10/100Mbps PHY:This segment includes lower-speed transceivers, often used in embedded systems, basic industrial controls, and cost-sensitive consumer electronics.
- 40 Gigabit PHY:These high-speed components facilitate 40 Gbps data transmission, typically deployed in core data center interconnects and high-capacity backbone networks.
Most installed capacity flows through Gigabit PHY. Expansion is steepest in 25 Gigabit PHY.
Technology:
Technology choices often depend on the specific application environment and required performance characteristics.
- Multi-Gig Ethernet:This technology category encompasses 2.5 Gbps, 5 Gbps, and 10 Gbps solutions, designed to leverage existing Cat5e/Cat6 cabling infrastructure. Multi-Gig Ethernet enables upgrades for bandwidth-intensive Wi-Fi 6/7 access points in campus networks.
- Industrial Ethernet:These robust PHYs are engineered for harsh industrial environments, offering extended temperature ranges and enhanced electromagnetic compatibility. Industrial Ethernet is critical for reliable communication in smart factories and industrial IoT deployments across China and Germany.
- Copper Ethernet:This segment utilizes traditional twisted-pair copper cabling for data transmission, offering cost-effectiveness and widespread infrastructure compatibility for short-to-medium distances.
- Fiber Ethernet:Fiber optic PHYs enable high-speed data transfer over longer distances with superior signal integrity and immunity to electromagnetic interference.
- Automotive Ethernet:Specialized PHYs designed for in-vehicle networks, supporting Advanced Driver-Assistance Systems (ADAS) and infotainment systems with stringent reliability and low-latency requirements.
Multi-Gig Ethernet is gaining significant traction in enterprise upgrades. Automotive Ethernet adoption is accelerating due to ADAS requirements.
Application:
Volume demand for Ethernet PHY chips varies significantly across different application areas.
- Data Centers:Data centers represent the largest demand segment, requiring high-density, power-efficient PHYs to manage massive bandwidth escalation. Hyperscale cloud providers in the United States and Ireland drive significant procurement volumes.
- Enterprise Networking:This segment covers campus networks, office environments, and corporate infrastructure, where Multi-Gigabit upgrades are supporting Wi-Fi 6/7 deployments. Enterprise networking solutions demand interoperability and robust security features.
- Industrial Automation:PHYs in industrial automation connect sensors, actuators, and control systems in manufacturing plants, requiring deterministic communication and environmental resilience.
- Telecom Infrastructure:This application includes base stations, aggregation points, and core network equipment, necessitating high-speed and long-reach Ethernet solutions.
- Consumer Electronics:Ethernet PHYs are integrated into devices like smart TVs, gaming consoles, and home routers, emphasizing cost-effectiveness and low power consumption.
Data centers currently drive the largest volume demand. Industrial automation applications show robust future growth potential.
Customer Type:
Profitability margins for Ethernet PHY vendors often correlate with the technical complexity and customization required by different customer types.
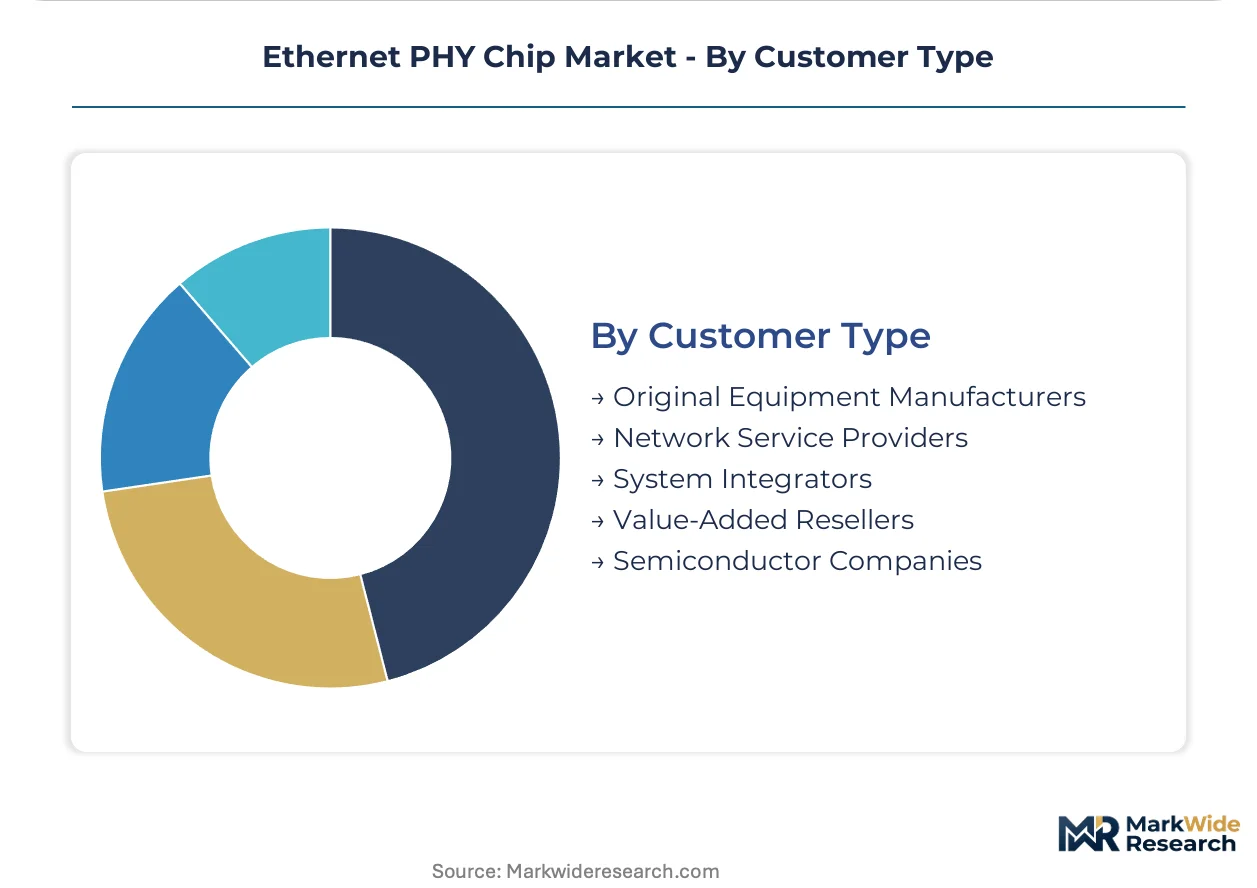
- Original Equipment Manufacturers:OEMs integrate PHY chips into their networking equipment, servers, and industrial control systems, requiring extensive technical support and validation. Design wins with major OEMs like Cisco and HPE are critical for market share.
- Network Service Providers:These customers deploy PHY-enabled equipment in their vast telecommunications and internet infrastructure, demanding high reliability and scalability. Large providers in Germany and Japan often influence component roadmaps.
- System Integrators:SIs combine various hardware and software components to deliver complete network solutions for end-users, focusing on interoperability and ease of deployment.
- Value-Added Resellers:VARs distribute PHY-based products, often bundling them with additional services or software, targeting specific niche markets.
- Semiconductor Companies:These entities sometimes procure PHY intellectual property or specialized PHY components for integration into their own larger system-on-chip designs.
Original Equipment Manufacturers dictate primary design specifications. Network Service Providers influence large-scale deployment standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ethernet PHY chip market originated and scaled significantly within early computing and networking hubs. These essential components now underpin global digital infrastructure, with demand concentrating in regions driving advanced manufacturing and hyperscale cloud services. Key geographic areas demonstrate distinct growth catalysts and regulatory environments.
China
Demand for Ethernet PHY chips in China is propelled by extensive industrial automation deployments and cloud infrastructure build-outs. The country's GB standards ensure compliance for network components across manufacturing and data centers. Cities like Shenzhen and Shanghai are centers for smart factory initiatives and hyperscale data center expansion.
United States
The United States drives significant Ethernet PHY demand through its vast data center expansion and enterprise network upgrades. FCC Part 15 rules govern electromagnetic interference for electronic devices, impacting PHY chip design. Silicon Valley and Northern Virginia remain critical hubs for cloud computing and AI infrastructure development.
Germany
Germany's industrial automation sector and automotive industry fuel substantial demand for robust Ethernet PHY solutions. CE marking requirements mandate rigorous safety and environmental compliance for electronic components sold within Europe. The automotive clusters around Munich and Stuttgart are central to advanced in-vehicle networking development.
Japan
Japan exhibits strong demand for Ethernet PHYs in its advanced automotive systems and precision industrial equipment. JIS standards define critical performance and quality criteria for electronic components used in diverse applications. The Tokyo metropolitan area leads in consumer electronics and telecom infrastructure deployments.
India
Rapid cloud adoption and digital infrastructure build-outs in India present new growth frontiers for high-speed data center PHYs. The country's BIS standards ensure product quality and safety for electronic goods entering the market. Bengaluru and Hyderabad are emerging as significant data center hubs, attracting substantial investment.
Ethernet PHY Chip Market Key Industry Players
The competitive structure tilts toward established semiconductor giants with extensive intellectual property portfolios in high-speed networking. The market exhibits a tiered structure, with a few large players dominating the high-performance segments and numerous smaller firms specializing in niche applications. These firms primarily engage in strategic partnerships for technology co-development and continuous portfolio diversification to address evolving standards. Geographic expansion into emerging data center hubs also represents a significant competitive move.
Within the premium-tier segment, Broadcom Inc. and Marvell Technology Group Ltd. exemplify companies leveraging extensive R&D investments to address complex data center and enterprise requirements. These US-based corporations occupy a position that prioritizes performance metrics and power efficiency in their Ethernet PHY offerings, securing design wins with major original equipment manufacturers. NXP Semiconductors N.V., a Netherlands-based entity, represents another archetype focused on automotive and industrial applications, navigating stringent reliability and environmental standards for specialized end-markets.
| Leading Market Players |
|---|
| NXP Semiconductors N.V. |
| Realtek Semiconductor Corp. |
| Broadcom Inc. |
| Analog Devices, Inc. |
| Intel Corporation |
| Marvell Technology Group Ltd. |
| Microchip Technology Inc. |
| Qualcomm Incorporated |
| Texas Instruments Incorporated |
| Others |
Cost & Logistics Intelligence
Capital-intensive semiconductor firms, driven by shareholder demands, prioritize R&D investments that influence both product roadmaps and a tiered pricing structure. This strategic approach shapes how advanced PHYs are supplied and priced globally.
Pricing Analysis
A value-based pricing model governs the Ethernet PHY chip market. The pricing model for Ethernet PHYs often stratifies across premium, standard, and economy tiers. Price differentiation stems from performance metrics like power efficiency and signal integrity, alongside the level of technical support required by OEMs. Pricing softness impacts legacy Gigabit PHYs due to commoditization and high volume demand. Data centers, requiring cutting-edge performance, exhibit lower price sensitivity compared to consumer electronics manufacturers.
Supply Chain Analysis
Specialized workforce availability in East Asian manufacturing hubs defines the Ethernet PHY chip supply chain. Production concentrates heavily in Taiwan, South Korea, and China, drawing from advanced silicon wafers and rare earth elements. A structural risk involves single-source vulnerability for advanced foundry services, creating potential bottlenecks. Distribution runs through a direct sales model to Original Equipment Manufacturers and a network of specialized distributors serving system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ethernet PHY chip market functions as a stable compounder, driven by the continuous expansion of digital infrastructure and the persistent need for higher bandwidth across all sectors. This sustained demand ensures consistent long-term growth.
For Market Incumbents: Anticipate increasing regulatory compliance burdens, such as the EU's RoHS directive, by investing in sustainable material sourcing. Consolidate market share in high-growth segments like 25 Gigabit PHYs through targeted R&D. Leverage extensive IP portfolios to secure design wins against emerging competitors, mitigating commoditization in mature Gigabit Ethernet. For New Entrants and Emerging Players: Industrial IoT device manufacturers represent an underserved buyer archetype seeking specialized, robust Ethernet PHYs. Target the Single-Pair Ethernet (SPE) segment, particularly industrial automation applications, focusing on simplified cabling. Penetrate emerging data center hubs in India with cost-effective Multi-Gigabit solutions. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirers, seeking to internalize critical networking IP for long-term strategic advantage. The market offers viable long-term investment across the next decade due to foundational demand for connectivity. Target mid-sized specialists with patented innovations in 25 Gigabit PHYs or Time-Sensitive Networking.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Gigabit PHY Portfolio Expansion | Supports enterprise network upgrades for Wi-Fi 6/7 access points, enabling higher bandwidth in campus networks. |
| Automotive Ethernet Certification Investment | Secures design wins with ADAS system providers by meeting AEC-Q100 reliability for in-vehicle networks. |
| Single-Pair Ethernet (SPE) R&D Focus | Extends Ethernet to industrial devices, leveraging simplified cabling for industrial automation. |
| Advanced Foundry Capacity Agreements | Mitigates supply risks and ensures production volumes for 25 Gigabit PHYs, crucial for cloud infrastructure. |
| Power-per-Gigabit Optimization Programs | Addresses operational constraints in hyperscale data centers by reducing energy costs and thermal limits. |
Research Approach
Direct dialogue with product managers, R&D directors, and procurement leads across leading semiconductor firms and OEMs formed the primary data foundation. This primary research was validated through secondary sources including FCC Part 15 filings, ISO/IEC standards, and financial reports from public companies. The analysis employed both bottom-up market sizing and top-down validation, triangulating data points for accuracy.
The quantitative model produced detailed volume and value forecasts across the analysis window. Segmentation dimensions modeled included product type, technology, application, and customer type, alongside geographic deployment patterns. Compound Annual Growth Rates were derived from historical trends and projected future demand for high-speed connectivity. Key forecast inputs included Multi-Gig Ethernet adoption rates and industrial automation investment levels.
Underlying measurement precision varies by segment; data centers and enterprise networking carry tighter precision than others. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Material deviation in global trade policies or semiconductor supply chain stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
5G Chip Market
Communication Chips & Hardware
4D Radar Chip Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
Mixed Signal System-On-Chip (Mxsoc) Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
IoT Chip Market
Communication Chips & Hardware
Optical Communications Market