
 Satellite Communication Components Market | 2026-2036
Satellite Communication Components Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communication Components Market Analytics
Aftermarket service revenue for legacy geostationary amplifiers and waveguide assemblies is reshaping margin distribution across the value chain. L3Harris Technologies leverages its sustainment footprint on military SATCOM terminals to capture recurring overhaul contracts. Thales Group anchors European defense programs through sovereign payload integration capabilities. RTX Corporation competes on gallium nitride power amplifier reliability for next-generation phased arrays.
Satellite communication components comprise radio frequency subsystems, antenna assemblies, and baseband processors engineered for vacuum operation, thermal cycling tolerance, and radiation hardness per MIL-STD-1540. These elements enable bidirectional data links between orbital platforms and terrestrial gateways for broadcasting, navigation, and broadband services. Amplifiers and antennas command the dominant share of component value, with Ku-band and Ka-band units benefiting from direct-to-home television and maritime connectivity expansion. Q/V-band technology represents the fastest-growing segment as operators pursue higher throughput for low Earth orbit constellations, though C-band retains residual demand from legacy government networks.
FCC spectrum auctions and ITU coordination procedures govern orbital slot assignments and interference management for U.S.-licensed operators. ESA procurement rules and EU Space Programme funding criteria require European component sourcing for classified Galileo and GovSatCom payloads. Stakeholders must monitor frequency reallocation timelines and radiation tolerance certification pathways to align R&D spending with qualifying standards.
Market Dynamics
Ka-band and Q/V-band frequency reallocations by the FCC and ITU are compressing transponder development cycles while forcing amplifier manufacturers to redesign thermal management architectures for higher power densities.
Growth Catalysts
- LEO Constellation Deployment:Commercial broadband initiatives from SpaceX, Amazon, and OneWeb are generating sustained demand for phased array antennas and radiation-hardened baseband processors.
- NATO SATCOM Modernization:Defense procurement programs across member states are mandating interoperability standards that favor suppliers with sovereign payload integration capabilities.
- FCC Spectrum Auctions:C-band clearing proceeds are funding replacement satellite builds, creating aftermarket demand for Ku-band and Ka-band waveguide assemblies.
Market Restraints
- Gallium Nitride Supply Concentration:Substrate fabrication for high-power amplifiers concentrates among Japanese and U.S. wafer suppliers, exposing lead time volatility.
- Radiation Hardness Qualification Costs:MIL-STD-1540 testing protocols extend development timelines by 18-24 months for new component designs.
- Optical Interconnect Substitution:Free-space laser terminals for inter-satellite links threaten RF component demand in certain orbital regimes.
Strategic Opportunities
- India Space Ecosystem:ISRO's commercial arm NSIL is opening launch and manufacturing partnerships for foreign component suppliers meeting BIS certification.
- Software-Defined Payload Convergence:Digital beamforming algorithms and reconfigurable FPGAs are collapsing hardware refresh cycles.
- EU GovSatCom Mandate:European Space Programme funding criteria require European-sourced components for classified payloads, creating protected demand pools.
Industry Challenges
- Radiation Effects Modeling Talent:Single-event upset simulation and total ionizing dose prediction require specialized expertise concentrated at national laboratories and legacy defense contractors.
- Multi-Band Integration Complexity:Terminals must simultaneously manage C-band legacy government links, Ku-band commercial traffic, and Ka-band broadband without interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Communication Components Market |
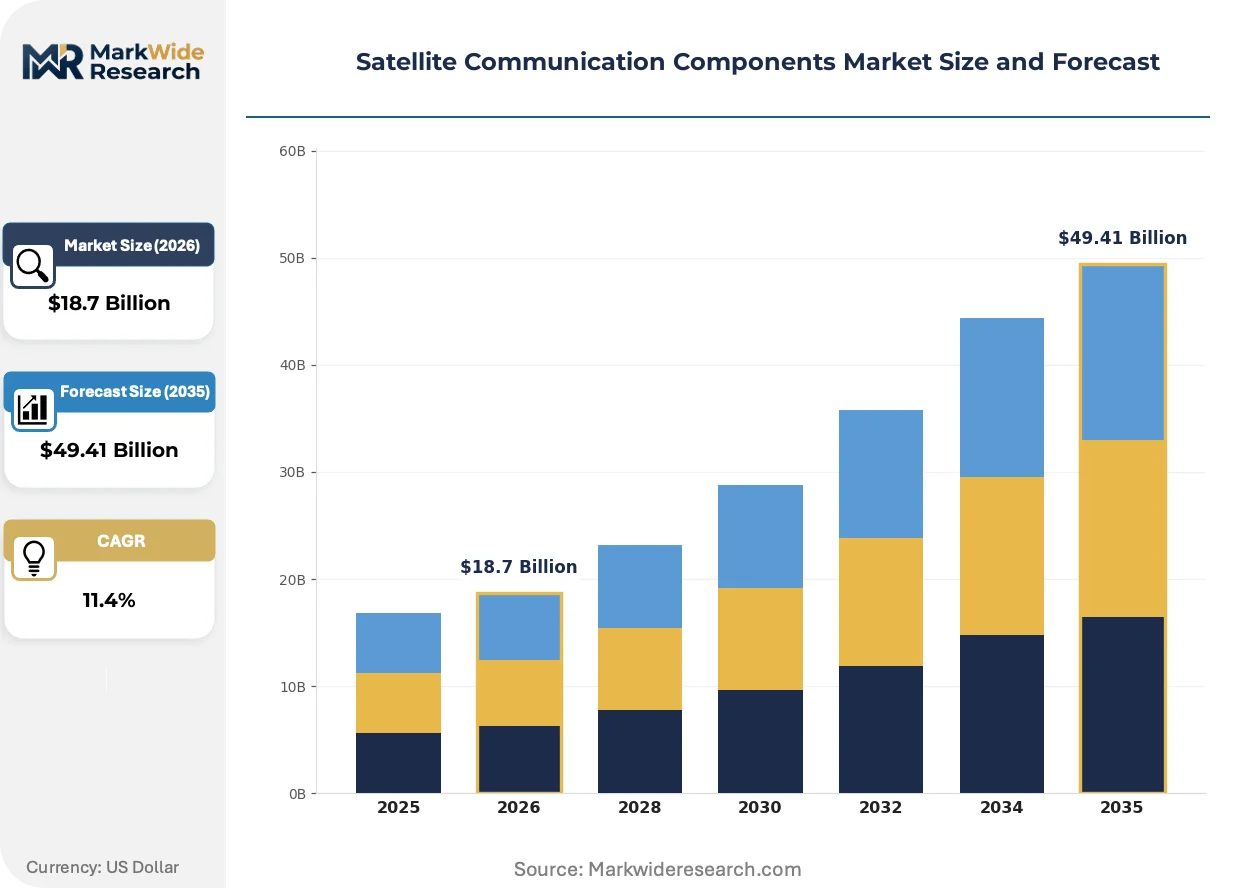
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Amplifiers, Modulators, Antennas, Transmitters Technology: SES, Q/V Band, C Band, Ku Band End User: Aerospace, Defense, Maritime, Telecommunications Application: Broadcasting, Internet Access, Remote Sensing, Disaster Management |
| Companies Covered | L3Harris Technologies Inc., RTX Corporation, Thales Group, Lockheed Martin Corporation, Northrop Grumman Corporation, Honeywell International Inc., General Dynamics Corporation, Airbus Defence and Space, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communication Components Market Evolving Landscape
Digital payload architectures are displacing analog RF chains across geostationary and low Earth orbit platforms, compressing hardware margins while expanding software-defined service revenue streams.
Software-defined radio implementations for satellite transponders are virtualizing functions previously executed in discrete analog hardware. Major operators including SES and Intelsat are migrating beam management to cloud-native orchestration layers. This virtualization is collapsing the traditional boundary between payload and ground segment suppliers.
ITU-R coordination procedures for Q/V-band filings are tightening orbital slot registration requirements and interference protection criteria. Satellite operators must now demonstrate advanced coding and modulation schemes before receiving international frequency assignments. European and U.S. applicants face the most stringent documentation burdens as spectrum congestion intensifies at 40-50 GHz.
Service unbundling is fragmenting traditional equipment-plus-support contracts into separate procurement streams for hardware, software licenses, and mission assurance. Defense integrators now source amplifiers, antennas, and modems through distinct vendor pools rather than single-source terminal packages. This shift is most pronounced in U.S. Space Force constellation deployments, where modular open systems architectures mandate interface standardization.
Satellite Communication Components Market Segmentation
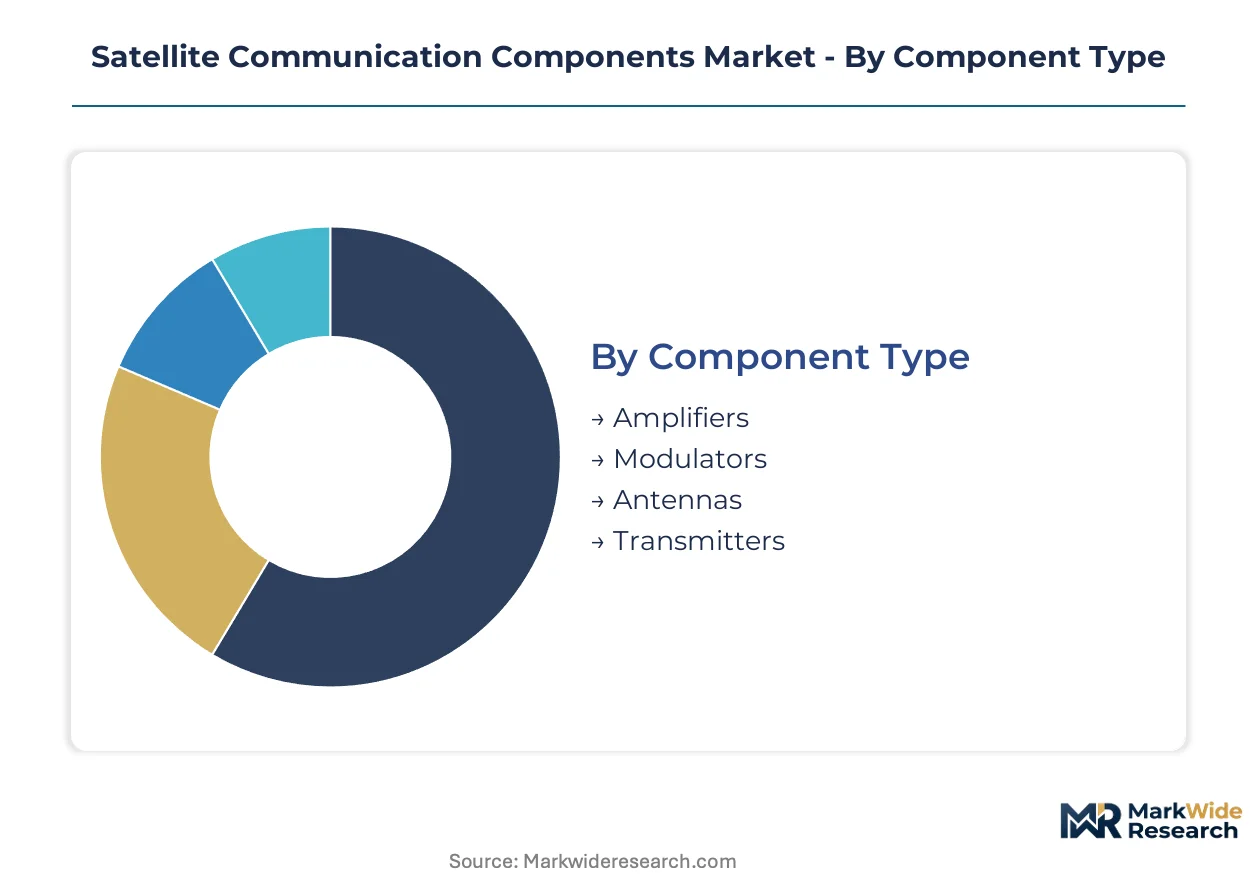
Component segmentation in satellite communications reveals divergent margin profiles across frequency bands and end-use verticals. Procurement patterns for amplifiers versus antennas differ substantially in contract duration and qualification requirements.
Component Type:
Mature amplifier architectures coexist with emerging phased array antenna designs across defense and commercial programs.
- Amplifiers:Solid-state power amplifiers and traveling wave tube amplifiers generate RF output for uplink chains. Defense procurement programs across NATO members are expanding adoption of gallium nitride-based units for hardened military terminals. Gallium nitride substrate fabrication concentrates among Japanese and U.S. wafer suppliers, exposing lead time volatility.
- Antennas:Parabolic reflectors and electronically steered phased arrays manage beam pointing and gain characteristics. Demand concentrates in the United States, driven by Space Force constellation deployments and commercial LEO broadband initiatives from SpaceX and Amazon. Ka-band and Q/V-band frequency allocations by the FCC and ITU are reshaping transponder design requirements for thermal management at higher power densities.
- Modulators:Baseband processing units encode data streams onto carrier signals per DVB-S2X and 5G-NTN standards.
- Transmitters:Integrated RF chains combine amplification, filtering, and frequency conversion for ground segment uplink facilities.
Amplifiers retain volume leadership; antennas hold the steepest expansion curve.
Technology:
Cost tier stratification separates legacy C-band infrastructure from premium Q/V-band development programs.
- Ku Band:Established frequency allocation dominates direct-to-home television and maritime connectivity applications. C-band clearing proceeds from FCC spectrum auctions are funding replacement satellite builds, creating aftermarket demand for Ku-band waveguide assemblies and legacy amplifier sustainment.
- Q/V Band:Millimeter-wave spectrum at 40-50 GHz enables terabit-class throughput for next-generation constellations. ITU-R coordination procedures are tightening orbital slot registration requirements and interference protection criteria for European and U.S. applicants as spectrum congestion intensifies.
- C Band:Legacy spectrum retains residual demand from government networks and rural broadcasting infrastructure.
- SES:Proprietary satellite operator technology platforms encompass end-to-end managed network services.
Ku Band commands installed base dominance; Q/V Band exhibits the most aggressive capacity expansion trajectory.
End User:
Application-driven procurement separates sovereign defense requirements from commercial service provider economics.
- Defense:Military SATCOM terminals require radiation-hardened components meeting MIL-STD-1540 testing protocols. ESA procurement rules and EU Space Programme funding criteria require European component sourcing for classified Galileo and GovSatCom payloads.
- Telecommunications:Commercial broadband operators source volume production runs of modems and user terminals. Software-defined radio implementations are virtualizing functions previously executed in discrete analog hardware, collapsing the traditional boundary between payload and ground segment suppliers.
- Aerospace:Aircraft connectivity systems integrate flat-panel antennas for in-flight broadband services.
- Maritime:Stabilized antenna platforms maintain link connectivity under vessel motion conditions.
Defense sustains premium pricing; telecommunications drives unit volume scaling.
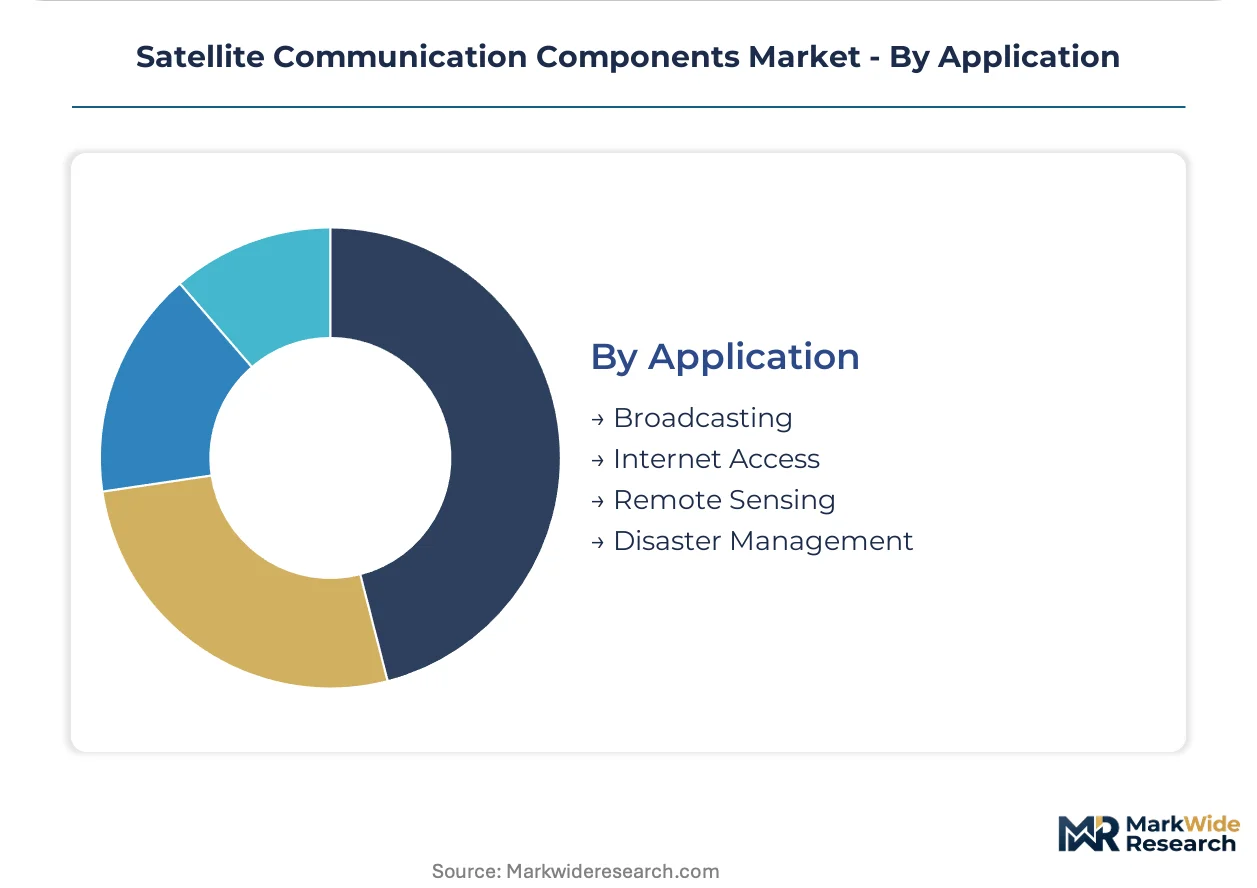
Application:
Customer type segmentation distinguishes mission-critical government services from consumer-oriented broadband delivery.
- Internet Access:LEO constellation broadband services demand mass-produced user terminals with electronically steered arrays. Commercial broadband initiatives from SpaceX, Amazon, and OneWeb are generating sustained demand for phased array antennas and radiation-hardened baseband processors.
- Broadcasting:Direct-to-home television distribution relies on Ku-band and C-band transponder capacity. Service unbundling is fragmenting traditional equipment-plus-support contracts into separate procurement streams for hardware, software licenses, and mission assurance.
- Remote Sensing:Earth observation downlinks require high-rate data acquisition and onboard storage systems.
- Disaster Management:Rapidly deployable terminals restore communications in infrastructure-damaged regions.
Internet Access captures investment momentum; Broadcasting maintains revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense buyers in the United States tolerate premium pricing for radiation-hardened components, while commercial telecommunications operators in Asia-Pacific drive aggressive cost compression on mass-produced terminals.
United States
Space Force constellation deployments and commercial LEO broadband initiatives from SpaceX and Amazon sustain demand for phased array antennas and baseband processors. FCC spectrum auctions for C-band clearing fund replacement satellite builds, creating aftermarket demand for Ku-band waveguide assemblies. Los Angeles and Denver host dense clusters of satellite terminal manufacturers and payload integrators serving both defense and commercial programs.
United Kingdom
UK Space Agency funding for sovereign satellite navigation capabilities drives procurement of radiation-hardened components for classified payloads. ESA procurement rules and EU Space Programme funding criteria require European component sourcing for GovSatCom programs. Harwell Science and Innovation Campus anchors payload engineering talent and satellite test facilities in Oxfordshire.
Germany
Airbus Defence and Space manufacturing in Munich and Bremen concentrates sovereign payload integration for European defense programs. German defense procurement mandates interoperability standards that favor suppliers with sovereign payload capabilities. Bavaria hosts specialized radiation effects modeling expertise concentrated at national laboratories and legacy defense contractors.
Japan
Mitsubishi Electric and domestic suppliers concentrate gallium nitride substrate fabrication for high-power amplifiers, exposing lead time volatility across the supply chain. METI industrial policy supports domestic satellite component manufacturing for both commercial and government applications. Tokyo-Yokohama corridor hosts precision manufacturing clusters for waveguide assemblies and antenna subsystems.
India
ISRO's commercial arm NSIL opens launch and manufacturing partnerships for foreign component suppliers meeting BIS certification requirements. Indian defense procurement programs expand adoption of hardened satellite terminals for sovereign communications networks. Bengaluru and Hyderabad concentrate satellite manufacturing facilities and component testing infrastructure.
Satellite Communication Components Market Competitive Landscape
Capability concentration sits with defense-heritage integrators possessing radiation-hardening expertise and sovereign security clearances; scale advantage sits with commercial electronics manufacturers serving volume LEO terminal production. The market structures around three tiers: legacy defense primes with sustainment footprints, European sovereign payload specialists, and commercial broadband component suppliers. Consolidation pressures intensify as software-defined architectures collapse traditional boundaries between payload and ground segment suppliers. Dominant competitive moves include strategic partnerships for gallium nitride supply security and modular open systems architecture certifications.
Within the defense-heritage tier, L3Harris Technologies Inc., RTX Corporation, and Thales Group exemplify contrasting geographic anchoring and capability positioning. L3Harris occupies a position tied to U.S. military SATCOM terminal sustainment and recurring overhaul contract capture. RTX Corporation sits within the gallium nitride power amplifier specialization vector for next-generation phased arrays. Thales Group anchors European defense program access through sovereign payload integration capabilities and ESA procurement compliance.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| RTX Corporation |
| Thales Group |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Honeywell International Inc. |
| General Dynamics Corporation |
| Airbus Defence and Space |
| Mitsubishi Electric Corporation |
| Others |
Value Network & Pricing Analysis
Los Angeles-Long Beach freight corridors impose steep logistics premiums on gallium nitride wafer shipments from Japanese foundries, compressing margins for amplifier manufacturers while amplifying price spreads between radiation-hardened defense components and commercial LEO terminal electronics.
Pricing Analysis
Long-term offtake contracts dominate procurement for radiation-hardened amplifiers and phased array subsystems, with spot purchasing limited to commodity waveguide assemblies and standard Ku-band components. Three-tier pricing structure across ITAR-restricted, ESA-compliant, and commercial-grade certification levels separates defense primes from European sovereign suppliers and volume LEO manufacturers. Cost compression in mass-produced user terminals intensifies as SpaceX and Amazon procurement teams drive component standardization. Commercial telecommunications operators exhibit acute price sensitivity; defense buyers tolerate substantial premiums for MIL-STD-1540 qualification and domestic sourcing mandates.
Supply Chain Analysis
ITAR export controls and Japan's foreign exchange law restrict gallium nitride substrate flows, concentrating high-power amplifier fabrication in Japanese, U.S., and select European facilities. Supply chains draw from Japanese wafer suppliers for GaN-on-SiC substrates, U.S. foundries for radiation-hardened baseband processors, and German precision manufacturers for waveguide assemblies. Single-source vulnerability pervades the GaN substrate tier, where Sumitomo Electric and Wolfspeed anchor global capacity. Distribution runs through defense-heritage integrators with security clearances for classified payloads, alongside commercial electronics distributors serving LEO constellation production lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation effects modeling expertise concentrates at a handful of national laboratories and legacy defense contractors, creating a persistent bottleneck for new component qualification and sustaining premium capture for incumbents with established testing relationships.
For Market Incumbents: Entrench sustainment footprints on military SATCOM terminals through recurring overhaul contracts and captive gallium nitride supply agreements. Expand backward integration into substrate fabrication via joint ventures with Japanese wafer suppliers to mitigate lead time volatility. Prioritize modular open systems architecture certifications for Space Force constellation deployments. For New Entrants and Emerging Players: Establish a beachhead in India's NSIL partnership framework by securing BIS certification for waveguide assemblies and antenna subsystems. Target the commercial LEO broadband supply chain for mass-produced baseband processors, where qualification timelines compress versus defense programs. Pursue software-defined payload convergence through FPGA-based beamforming partnerships with emerging constellation operators. For Investors and Strategic Acquirers: FCC spectrum auction timelines and ITU-R Q/V-band coordination deadlines reshape the acquisition landscape by accelerating demand for qualified component suppliers. Position for five-to-ten year holding periods centered on sovereign payload capabilities and radiation-hardening expertise. Monitor gallium nitride supply consolidation signals as the primary inflection indicator for margin expansion versus compression.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Supply Security Partnership | Locking substrate access with Japanese foundries insulates against lead time volatility for defense programs. |
| Radiation Hardness Qualification Investment | MIL-STD-1540 certification opens procurement pathways for classified Space Force and ESA payloads. |
| Software-Defined Payload Development | Digital beamforming algorithms collapse hardware refresh cycles and expand recurring software revenue. |
| Modular Open Systems Architecture Adoption | Interface standardization mandated by U.S. Space Force enables multi-vendor terminal integration. |
| India Manufacturing Partnership | NSIL certification requirements create protected access to ISRO launch and satellite production ecosystems. |
Research Methodology
The analysis maps amplifier architectures, antenna subsystems, baseband processors, and frequency conversion modules, each validated through payload engineering directors, defense procurement officers, satellite operator supply chain leads, and radiation effects specialists. Primary interviews with component qualification managers and ESA program executives combined with secondary validation from FCC spectrum auction filings, ITU-R coordination databases, SEC 10-K disclosures from listed defense primes, and ESA procurement registries. Bottom-up build-ups across component categories triangulated against top-down satellite manufacturing forecasts.
Assumption sets held fixed include ITAR and ESA procurement regime continuity, gallium nitride substrate supply concentration patterns, and LEO constellation deployment schedules from disclosed operator filings. Segmentation dimensions modeled encompass frequency band, component type, end-use vertical, and qualification tier across the projection horizon. CAGRs derived from unit economics analysis of constellation terminal production rates and defense program award timelines. Industry-specific inputs included MIL-STD-1540 testing queue durations and ITU-R filing approval probabilities.
Stress conditions across gallium nitride supply disruption severity, spectrum reallocation acceleration, and optical inter-satellite link substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense budget trajectory and commercial broadband subscriber penetration. Material shifts in FCC spectrum auction timing or ITU-R coordination precedent would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Nano GPS Chipset Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Gigabit Passive Optical Network (GPON) Chipset Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Global Application Specific Communications Analog IC Market
Communication Chips & Hardware
Interface Transceiver Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
Asia-Pacific Embedded Antenna Systems Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
5G PCB Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market