
 Ethernet Access Device Market | 2026-2036
Ethernet Access Device Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet Access Device Market Intelligence
Software-defined networking feature licensing is tilting the profit pool away from traditional hardware-centric sales toward more predictable recurring revenue models. Cisco Systems, Inc. leverages its extensive portfolio to integrate security and access functions. Juniper Networks, Inc. differentiates with its dedicated focus on high-performance networking for large-scale data centers and service providers. Allied Telesis competes by providing cost-effective and reliable access solutions tailored for small and medium businesses.
An Ethernet Access Device is network hardware that terminates an Ethernet circuit, connecting a service provider's network to a customer's LAN. It manages traffic shaping and quality of service, with port speeds often exceeding 10 Gbps to support carrier-grade services. While switches constitute a high-volume product type, advanced routers for telecommunication service providers offer greater margin potential. The data center and cloud networking application segments represent the fastest-growing areas for these devices.
Product compliance is shaped by standards from bodies like the US Federal Communications Commission (FCC) concerning electromagnetic interference and the EU's CE marking requirements. In addition, ISO/IEC standards define critical interoperability and performance benchmarks, which are essential for market access in countries like Japan and Germany. Vendor selection will increasingly hinge on the ability to deliver hardware that meets stringent energy efficiency targets and supports software-defined automation.
Market Dynamics
The fundamental dynamic reshaping the Ethernet Access Device market is the architectural shift driven by 5G network deployments and the escalating throughput demands of cloud networking. This dual pressure forces a move towards higher-capacity, more intelligent, and software-defined access hardware.
Growth Catalysts
- 5G Network Expansion:The rollout of 5G infrastructure by telecommunication service providers requires significant upgrades to backhaul and fronthaul networks, directly stimulating demand for access devices with port speeds exceeding 10 Gbps to handle increased mobile data traffic.
- Data Center Consolidation:Demand is intensifying within major data center clusters, particularly in the United States and Germany, where hyperscalers and cloud providers are building out capacity to support critical enterprise and consumer applications.
- Cloud Application Throughput:The growing adoption of data-intensive cloud networking applications, including AI/ML workloads and large-scale data analytics, necessitates higher-performance Ethernet access devices to ensure low-latency connectivity between servers and storage.
Market Restraints
- Semiconductor Supply Concentration:The market's reliance on a small number of advanced semiconductor foundries for high-speed networking chipsets creates a significant supply chain vulnerability, exposing manufacturers to potential production delays and component price volatility.
- Legacy System Integration:The complexity and cost associated with integrating new, software-defined access devices with entrenched legacy network infrastructure can slow down adoption cycles for some enterprise and service provider customers.
- High R&D Investment:Keeping pace with rapid advancements in Ethernet standards, such as 400GbE and beyond, requires continuous and substantial investment in research and development, creating a high barrier to entry for new players.
Strategic Opportunities
- Edge Computing Deployments:The emergence of edge computing creates a new frontier for specialized access devices, requiring compact, hardened, and low-latency hardware to be deployed closer to end-users in locations outside traditional data centers.
- Integrated Security Functions:Converging network access and security functions onto a single device platform offers a significant value proposition, allowing vendors to capture additional revenue streams through software and service licensing for features like threat detection.
- Digital Infrastructure Initiatives:Government programs, such as the EU's Digital Decade policy targets and smart city projects in nations like India, provide opportunities for vendors whose products align with public sector goals for enhanced connectivity and digital transformation.
Industry Challenges
- Multinational Compliance Burden:Manufacturers face the operational challenge of ensuring products simultaneously meet diverse regulatory requirements, including FCC electromagnetic interference rules in the US, CE marking in the EU, and specific ISO/IEC interoperability standards for market access in Japan.
- Automation Skill Gaps:A shortage of network engineers with expertise in software-defined networking, automation, and API integration hinders the ability of end-users to fully leverage the advanced capabilities of modern Ethernet access devices.
- Multi-Vendor Interoperability:Ensuring seamless functionality and consistent performance in complex network environments composed of hardware from multiple different vendors remains a persistent technical challenge for both manufacturers and their customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet Access Device Market |
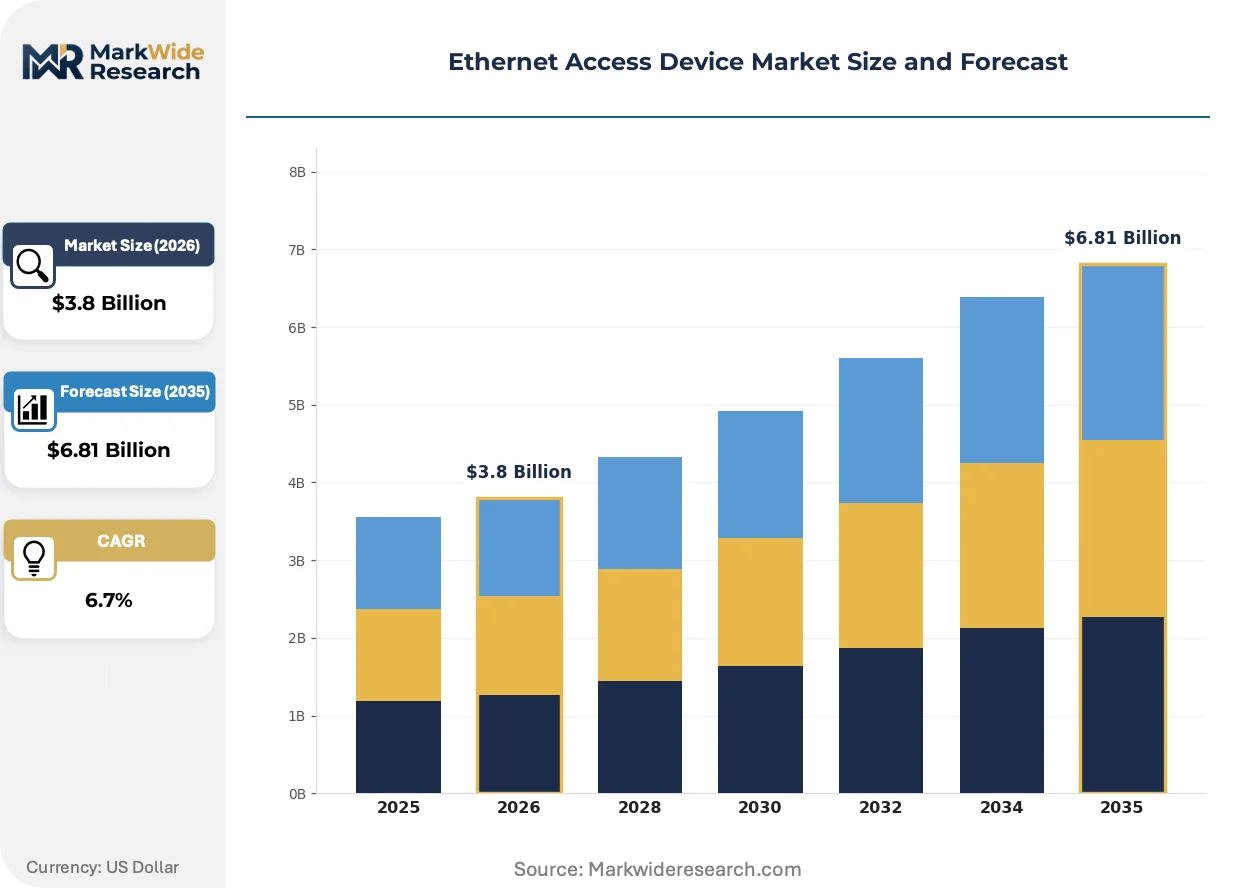
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Routers, Switches, Modems, Network Interface Cards Technology: Fiber Optic, Copper, Wireless, Ethernet over Coaxial Application: Data Centers, Telecommunication Service Providers, Cloud Networking, Network Security End User: Internet Service Providers, Managed Service Providers, Large Enterprises, Small & Medium Businesses |
| Companies Covered | Cisco Systems, Inc., Huawei Technologies, Juniper Networks, Inc., Arista Networks, Nokia Corporation, ALE International SAS, Allied Telesis, PLANET Technology Corporation, Telco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet Access Device Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot from hardware-centric sales to software-defined value. This transition favors flexible, programmable platforms and recurring revenue models over traditional, monolithic device sales.
Software-defined networking (SDN) provides an abstraction layer that decouples network control and forwarding functions from the physical hardware. Telecommunication service providers and large-scale data center operators are the primary adopters of this technology. This architectural shift toward centralized, programmable network management is rendering obsolete the traditional model of manually configuring individual hardware devices one by one.
Regulatory frameworks focused on sustainability are influencing hardware design. The EU's Ecodesign Directive, for instance, sets stringent energy efficiency requirements for network equipment, a principle mirrored in energy-saving initiatives in other regions. This forces manufacturers to prioritize designs that offer maximum data throughput for the lowest possible power consumption. The data center segment is most affected, with operators in Germany and the United States now using energy efficiency as a key criterion for vendor selection.
A significant behavioral shift is underway as customers move from perpetual hardware ownership to more flexible consumption models. The procurement preference is tilting towards subscription-based licensing for advanced software features, such as analytics, security, and automation. This change disrupts the business model of traditional channel partners who relied on hardware margins. The trend is most visible among enterprise customers in North America and Europe adopting opex-centric budgets for network infrastructure.
Ethernet Access Device Market Segmentation
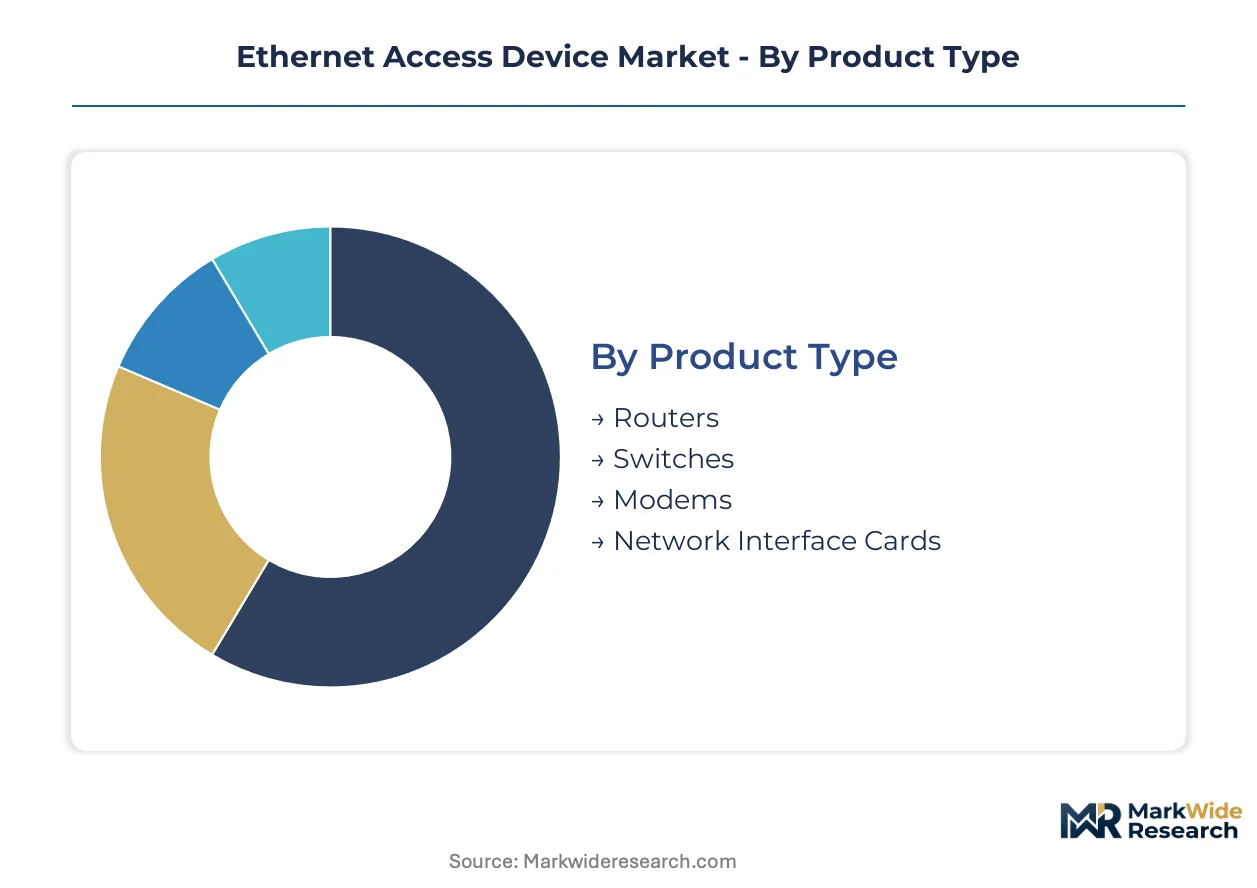
Understanding the segmentation within the Ethernet Access Device market provides critical insights into the varied technological demands and strategic deployments across different industry verticals. This granular view helps manufacturers tailor product development and service offerings to specific customer needs and market opportunities.
Product Type:
The diverse array of Ethernet access devices serves distinct networking requirements, ranging from core infrastructure management to customer premise connectivity.
- Routers:These devices direct data traffic between different networks, utilizing advanced protocols to determine the optimal path for packet delivery across wide area networks. Telecommunication service providers in Germany are driving router demand to manage complex 5G backhaul traffic.
- Switches:These devices forward data packets within a local area network, operating at Layer 2 or Layer 3 of the OSI model to connect multiple devices. Demand for switches is concentrating within large data center clusters in the United States, driven by the need for high-density port connectivity.
- Modems:Modems convert digital signals to analog and vice versa, enabling data transmission over various physical media types for internet access.
- Network Interface Cards:NICs are hardware components that allow a computer to connect to a network, providing physical layer and data link layer functionality.
The dominant share belongs to Switches, while Routers are expanding most quickly.
Technology:
Different underlying technologies dictate the performance, reach, and deployment flexibility of Ethernet access devices in various environments.
- Fiber Optic:This technology transmits data as light pulses through glass or plastic strands, offering extremely high bandwidth and long-distance capabilities with minimal signal degradation. Data centers in the United States rely heavily on fiber optic technology to support their massive throughput requirements.
- Wireless:Wireless technologies utilize radio waves for data transmission, providing flexible connectivity without physical cables, crucial for mobile and remote deployments. Edge computing initiatives in Europe are increasingly adopting wireless access solutions for localized data processing.
- Copper:Copper cabling, like Ethernet over twisted pair, provides reliable and cost-effective connectivity for shorter distances within enterprise networks.
- Ethernet over Coaxial:This technology enables Ethernet signals to be transmitted over existing coaxial cables, often used in multi-dwelling units and hospitality settings.
Fiber Optic technology underpins high-speed infrastructure, while Wireless solutions are gaining significant traction for flexible access.
Application:
The strategic application of Ethernet access devices varies significantly, addressing diverse operational priorities from core infrastructure to specialized services.
- Data Centers:These facilities house computing and storage infrastructure, requiring high-density, low-latency Ethernet access devices to interconnect servers and storage arrays. Hyperscale data centers in Germany are a primary consumer, supporting massive digital service demands.
- Cloud Networking:This application segment involves connecting distributed cloud resources and workloads, often demanding flexible and scalable access devices for hybrid and multi-cloud environments. The increasing adoption of AI/ML workloads drives demand for high-throughput devices in cloud networking.
- Telecommunication Service Providers:These entities deploy Ethernet access devices for backhaul, fronthaul, and enterprise connectivity, supporting 5G and broadband services.
- Network Security:Integrating security functions directly into access devices provides perimeter defense and threat detection capabilities at the network edge.
Data Centers and Cloud Networking collectively represent the fastest-growing areas for Ethernet access device applications.
End User:
End-user segments for Ethernet access devices are differentiated by their network scale, operational complexity, and specific service delivery requirements.
- Internet Service Providers:ISPs deploy Ethernet access devices at the network edge to deliver broadband internet and other communication services to residential and business customers. The expansion of fiber-to-the-home networks in Japan fuels demand for high-capacity access solutions.
- Large Enterprises:These organizations operate extensive internal networks, requiring robust Ethernet access devices to connect numerous branches, data centers, and employee workstations. Global corporations in the United States prioritize devices that integrate security and advanced management features.
- Managed Service Providers:MSPs utilize these devices to offer outsourced IT and network management services to their clients, requiring reliability and remote manageability.
- Small & Medium Businesses:SMBs typically seek cost-effective and easy-to-manage Ethernet access solutions for their more modest networking needs.
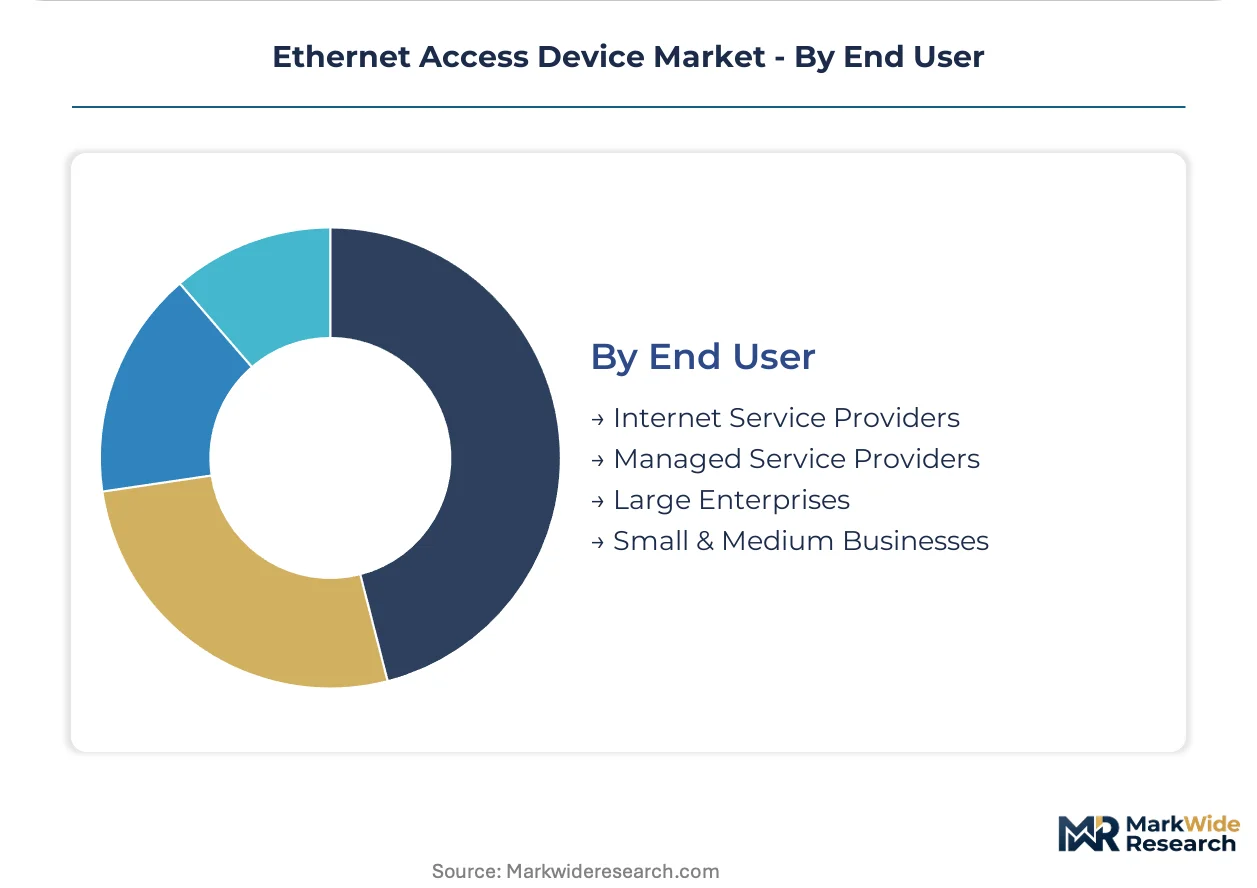
Internet Service Providers drive significant volume, while Large Enterprises demand devices with advanced software-defined capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ethernet Access Device market exhibits varying demand elasticity, with telecommunication service providers and hyperscale data centers demonstrating lower price sensitivity for advanced solutions. Conversely, small and medium businesses prioritize cost-effectiveness and ease of management. This dynamic shapes regional investment and deployment patterns across global markets.
United States
The United States experiences strong demand from hyperscale data centers requiring high-density port connectivity for cloud networking applications. FCC regulations influence product design for electromagnetic interference and compliance. Major data center clusters in Virginia and Texas are rapidly expanding capacity to support critical enterprise workloads and AI/ML processing.
Germany
Germany drives router demand for managing complex 5G backhaul traffic and supports massive digital service demands in data centers. CE marking requirements ensure product compliance for market access across the European Union. Hyperscale facilities in Frankfurt are key consumers, leveraging high-performance Ethernet access devices for cloud infrastructure.
Japan
Japan's internet service providers fuel demand for high-capacity access solutions, particularly with the expansion of fiber-to-the-home networks. ISO/IEC standards define critical interoperability benchmarks for market entry and product performance. Major metropolitan areas like Tokyo are seeing significant investments in advanced network infrastructure to enhance broadband services.
India
India's digital infrastructure initiatives and smart city projects stimulate demand for enhanced connectivity solutions. Government programs like the PLI scheme encourage local manufacturing and technology adoption in the telecommunications sector. Urban centers such as Bangalore are witnessing increased deployment of Ethernet access devices for public sector goals and enterprise connectivity.
Netherlands
The Netherlands shows growing traction for flexible access solutions, particularly for edge computing deployments. The EU's Ecodesign Directive influences hardware design, prioritizing energy efficiency for network equipment. Amsterdam's emerging edge data centers are adopting specialized access devices to bring processing closer to end-users and reduce latency.
Ethernet Access Device Market Key Industry Players
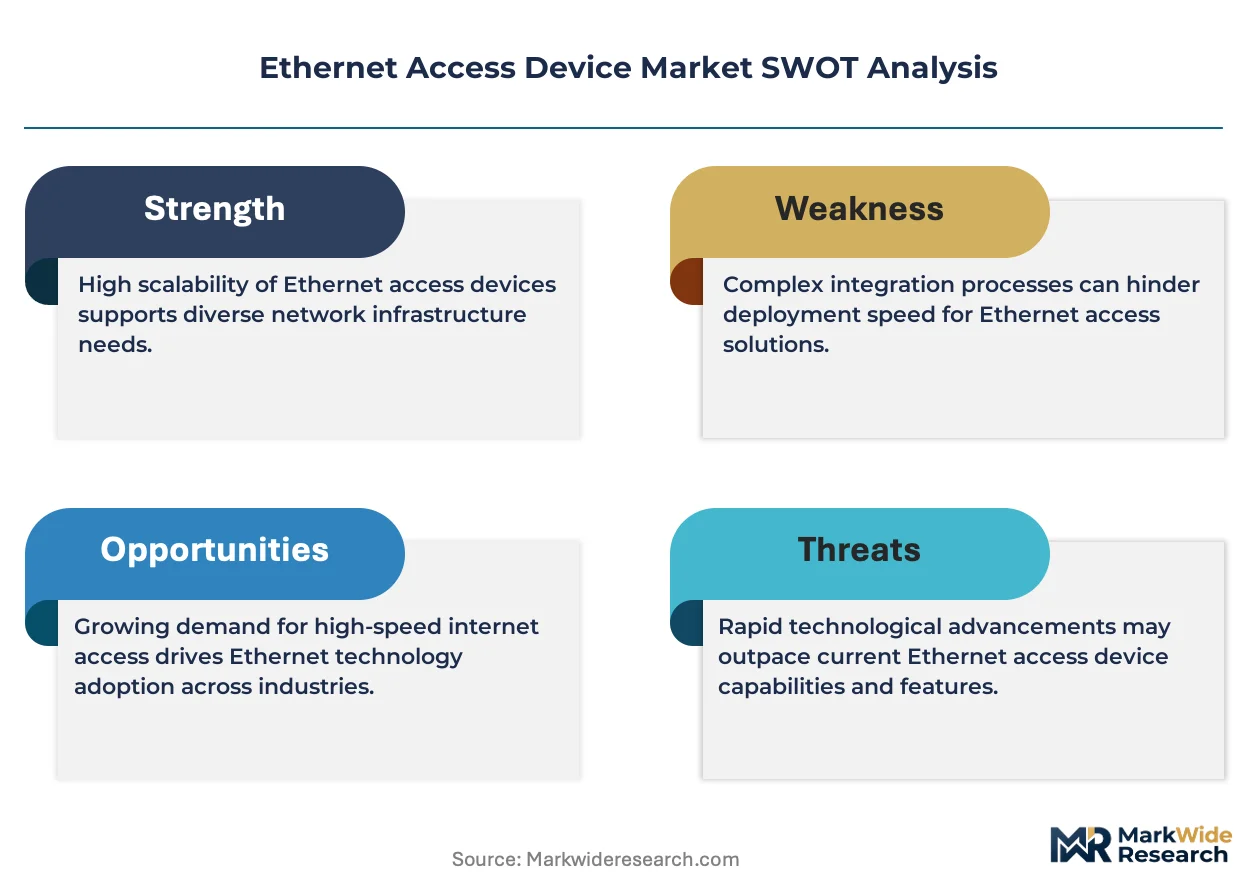
Capability concentration sits with one tier; scale advantage sits with another in the Ethernet Access Device market. The market structure features specialized high-performance providers alongside broad portfolio integrators. Cost-effective solution providers also carve out distinct niches. Strategic moves center on software licensing models and the convergence of network access with security functions.
Leading players exemplify distinct market approaches within the Ethernet Access Device sector. Companies like Cisco Systems, Inc. represent the broad portfolio integration archetype, leveraging extensive product lines to combine security and access functions for diverse customer needs. Juniper Networks, Inc. anchors the high-performance segment, focusing on dedicated networking solutions for large-scale data centers and service providers requiring maximum throughput. Allied Telesis occupies the cost-effective solutions niche, providing reliable access devices specifically tailored for the requirements of small and medium businesses.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Huawei Technologies |
| Juniper Networks, Inc. |
| Arista Networks |
| Nokia Corporation |
| ALE International SAS |
| Allied Telesis |
| PLANET Technology Corporation |
| Telco Systems |
| Others |
Cost & Logistics Intelligence
Advanced semiconductor foundries in Asia, particularly in Taiwan and South Korea, dictate component availability and influence downstream pricing power for Ethernet Access Device manufacturers. This concentration creates inherent volatility for device pricing. The market structure enables specialized high-performance providers to sustain premium pricing for advanced solutions.
Pricing Analysis
Subscription-based licensing for advanced software features forms the dominant pricing model, shifting revenue from hardware sales to recurring streams. Price differentiation stems from integrated security functions and compliance with stringent energy efficiency targets. Pricing softness affects traditional hardware-centric sales due to this software shift. Small and medium businesses exhibit the highest price sensitivity, prioritizing cost-effective solutions, while telecommunication service providers demonstrate lower price sensitivity for carrier-grade devices.
Supply Chain Analysis
The market's reliance on a small number of advanced semiconductor foundries creates a significant supply chain vulnerability, exposing manufacturers to potential production delays and component price volatility. Geographic supply concentration for high-speed networking chipsets primarily rests in Taiwan and South Korea. Raw material dependencies include specialized silicon wafers and rare earth elements for advanced circuitry. Distribution runs through a mix of direct sales to large enterprises and hyperscalers, alongside traditional channel partners for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Ethernet Access Device market represents a defensive-moat story, primarily due to the high switching costs associated with integrating new, complex network infrastructure into existing legacy systems.
For Market Incumbents: Pre-empt emerging competitive threats by aggressively expanding software-defined networking capabilities and integrated security features. Invest substantially in R&D for next-generation Ethernet standards, such as 400GbE and beyond, to maintain technological leadership. Focus on achieving global compliance certifications like ISO/IEC and CE marking to reinforce market access against new entrants. Leverage extensive customer bases to cross-sell advanced software licenses, securing predictable recurring revenue streams.
For New Entrants and Emerging Players: Pursue niche opportunities in rapidly expanding segments like edge computing, where compact, hardened, and low-latency hardware is essential. Target small and medium businesses with cost-effective, easy-to-manage solutions that simplify network deployment. Focus on specific digital infrastructure initiatives in countries like India, aligning product offerings with public sector goals for enhanced connectivity. Develop specialized devices that offer unique value propositions, such as ultra-low power consumption or advanced AI/ML acceleration at the network edge.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firms with strong intellectual property in software-defined networking and energy-efficient hardware design. The long-term viability of this market is strong, driven by persistent demand for higher-capacity access devices from 5G and cloud networking. Target acquisition archetypes include specialized software companies offering automation tools or security platforms. The signal to watch is the adoption rate of subscription-based software licensing models among enterprise and service provider customers, indicating a successful business model transition.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Feature Development | Enhances recurring revenue streams and customer lock-in for advanced capabilities. |
| Energy Efficiency Certification | Meets stringent regulatory requirements, especially for data center procurement in Germany. |
| Edge Computing Hardware Design | Captures demand for specialized, low-latency devices in emerging localized deployments. |
| Integrated Security Offerings | Addresses growing customer need for converged network access and threat detection. |
| Global Compliance Investment | Ensures market access across diverse regulatory environments like the EU and US. |
Research Approach
A spread of perspectives from telecommunication service providers, data center operators, enterprise IT managers, and network engineers converged on the working assumptions for this analysis. This involved primary interviews combined with rigorous secondary validation. Regulatory bodies like the FCC and EU's CE marking authorities, alongside ISO/IEC standards organizations, provided crucial compliance and interoperability benchmarks. Bottom-up and top-down triangulation ensured comprehensive data coverage.
Demand-supply balance formed the core of the analytical framework, projecting market trends over the projection horizon. The study modeled segmentation dimensions including product type, technology, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends, projected technology adoption, and economic indicators. Key forecast inputs included 5G network rollout schedules, cloud infrastructure investment trends, and energy efficiency mandates.
Sensitivities concentrate around semiconductor supply chain disruptions, rapid shifts in Ethernet standards, and unforeseen regulatory changes. Forecasts reflect assumptions regarding technological advancements and market dynamics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Bluetooth Smart and Smart Ready Market
Communication Chips & Hardware
Zigbee System-On-Chip Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Wireless Transmitter Chip Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Zigbee Enabled Devices Market
Communication Chips & Hardware
Industrial Internet Chip Market
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market