
 Smart TV Chip Market | 2026-2036
Smart TV Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Smart TV Chip Market Insights
Semiconductor design talent is rotating toward AI inference and video processing specializations, tightening availability for general-purpose TV chip architects. MediaTek leverages its integrated modem and graphics IP portfolio to sustain leadership in mid-range and premium 4K segments. Qualcomm anchors the high-performance tier with Snapdragon-based platforms that compete on gaming and AI assistant integration.
A Smart TV Chip is a purpose-built integrated circuit that combines CPU cores, GPU clusters, dedicated video decoders, and neural processing units onto a single die, typically fabricated at 7nm or smaller nodes to handle real-time 4K/8K HDR streaming with sub-10-watt thermal envelopes. SoC architectures dominate unit shipments and capture the largest margin pools by eliminating discrete component costs, while ASIC designs for branded OEMs represent the fastest-growing category as manufacturers seek differentiated feature sets. LED-backlit models still generate the highest chip volumes, though OLED and QLED technologies command premium silicon content per unit.
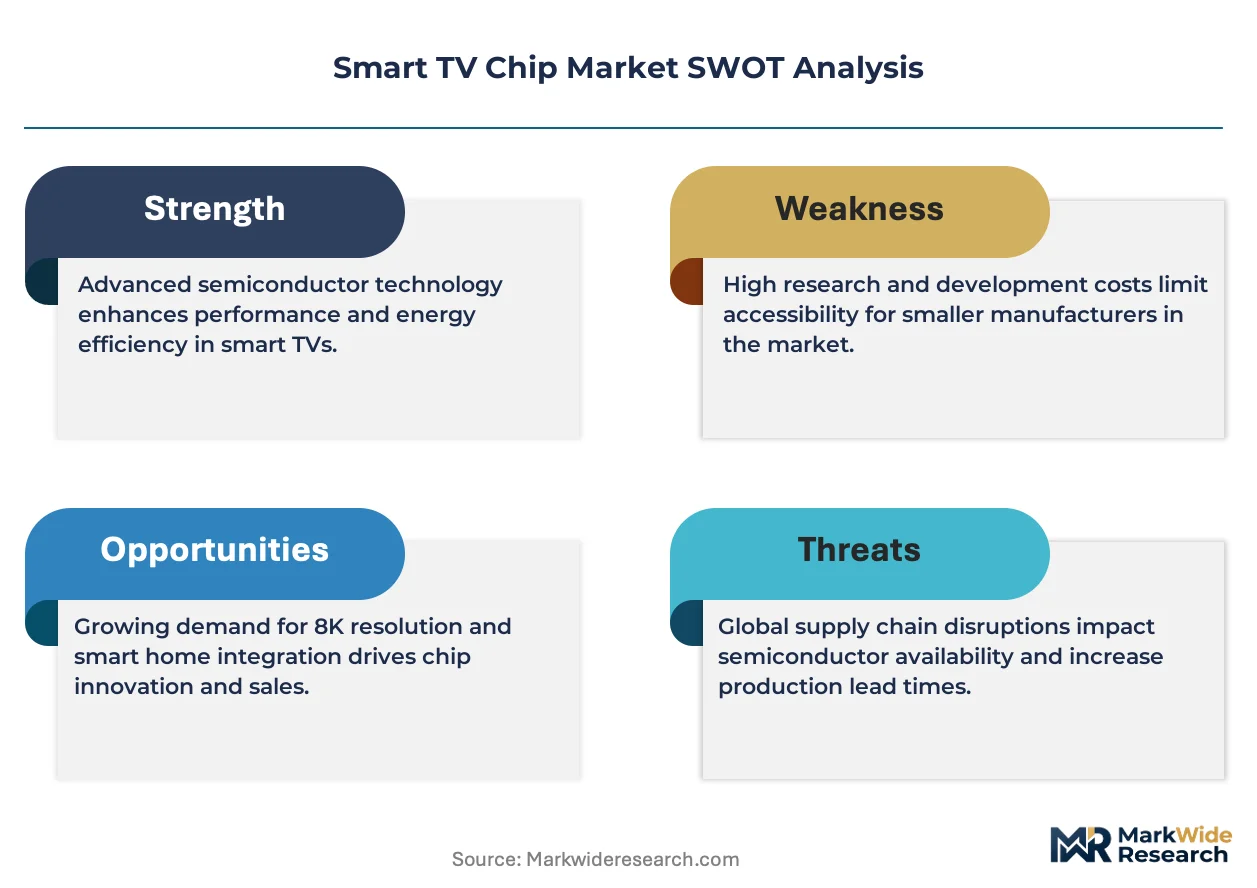
The FCC in the United States enforces electromagnetic compatibility and energy consumption standards that directly influence chip power budgets and RF shielding requirements, while CE marking under EU RoHS and REACH directives restricts hazardous substances in semiconductor packaging and substrates. China's MIIT and GB standards mandate cybersecurity and data handling protocols for connected televisions, adding firmware complexity to chip designs. Stakeholders must weigh regional certification burdens against the cost of region-specific silicon variants.
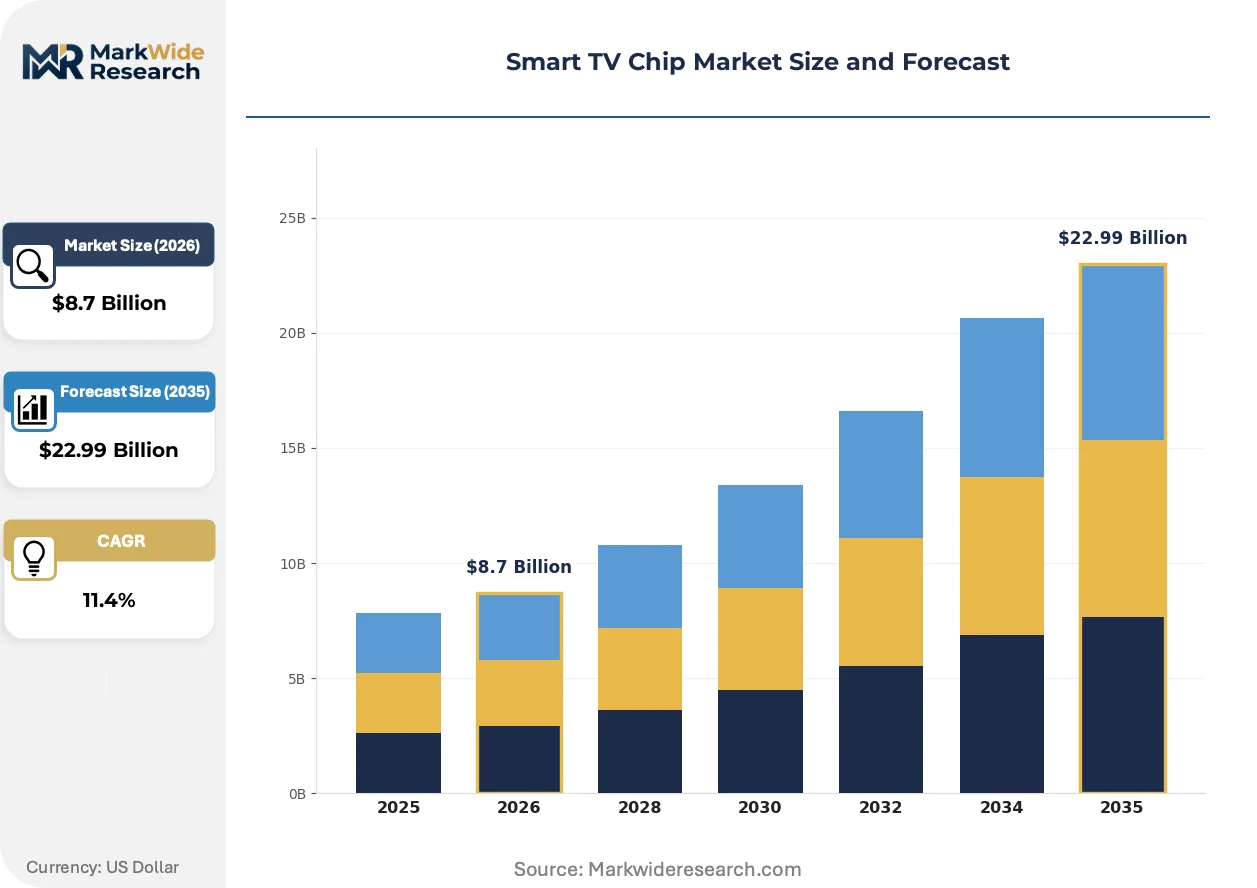
Market Dynamics
Display resolution escalation from 4K to 8K is compressing chip design cycles while the EU Ecodesign Directive forces simultaneous power efficiency gains, creating a thermal-performance squeeze that only advanced node migration can resolve.
Growth Catalysts
- EU Ecodesign Directive:Mandated standby power caps below 0.5 watts are forcing chip architects to innovate power management subsystems, creating upgrade demand across installed base televisions.
- AI inference engines:Neural processing unit integration for real-time upscaling and voice assistant processing is becoming standard in premium television lines, expanding silicon content per unit.
- China panel ecosystem:Domestic display manufacturers and streaming platform operators are consolidating procurement around integrated SoC solutions, concentrating volume orders with fewer chip vendors.
Market Restraints
- Advanced node cost:Migration to 5nm and 3nm fabrication for thermal envelope compliance is inflating mask set costs and NRE charges, squeezing mid-range product margins.
- Foundry concentration:Taiwan-based advanced logic capacity represents a single-point vulnerability for 7nm and smaller production, exposing supply continuity to geopolitical friction.
- GDPR firmware complexity:European data handling mandates are extending software validation timelines and requiring region-specific silicon variants, fragmenting production economics.
Strategic Opportunities
- India smart TV penetration:Sub-$200 television segments remain underpenetrated by advanced chipsets, offering white space for cost-optimized SoC architectures with localized content integration.
- Cloud gaming convergence:Low-latency game streaming is creating demand for chips with integrated Wi-Fi 6E/7 modems and hardware-accelerated decoding, merging television and console functions.
- US IRA efficiency incentives:Energy Star certification alignment is opening procurement channels through utility rebate programs for televisions meeting aggressive standby power targets.
Industry Challenges
- Video codec expertise scarcity:Engineers proficient in AV1 and VVC hardware decoder implementation command premium compensation, constraining R&D team scaling for second-tier vendors.
- Multi-regional certification overlap:Simultaneous FCC electromagnetic compatibility, CE marking under RoHS/REACH, and MIIT cybersecurity validation is extending time-to-revenue by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart TV Chip Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SoC, MPU, FPGA, ASIC Technology: LED, QLED, OLED, MicroLED End User: Consumer Electronics, OEMs, Retailers, Distributors Application: Media Streaming, Gaming, Smart Home, Interactive Advertising |
| Companies Covered | MediaTek, Qualcomm, Amlogic, Realtek Semiconductor, Novatek Microelectronics, HiSilicon, Rockchip, Broadcom, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart TV Chip Market Trends and Innovations
Chip architectures are splitting between premium AI-heavy designs and cost-optimized streaming-focused variants, with regulatory pressure and display technology divergence accelerating this specialization.
Neural processing unit integration for real-time 4K-to-8K upscaling and ambient intelligence is bifurcating the market into AI-capable premium tiers and stripped-down volume segments. High-end television manufacturers are mandating on-device inference for privacy-sensitive voice and gesture control. This capability compression is eliminating general-purpose mid-range chip viability.
REACH substance restrictions and RoHS hazardous material bans are forcing substrate and packaging material substitutions across European-bound shipments. Lead-free solder alternatives and halogen-free laminates are raising assembly costs while requiring reliability requalification. Television OEMs serving EU markets are consolidating suppliers to manage compliance documentation burden.
Streaming platform operators are vertically integrating into chipset specification, displacing traditional OEM-driven procurement with direct SoC co-development agreements. Netflix, Amazon Prime Video, and regional services are mandating hardware security module integration and dedicated content protection circuits. This buyer concentration is most visible in China, where iQIYI and Youku influence die-level feature prioritization.
Smart TV Chip Market Segmentation
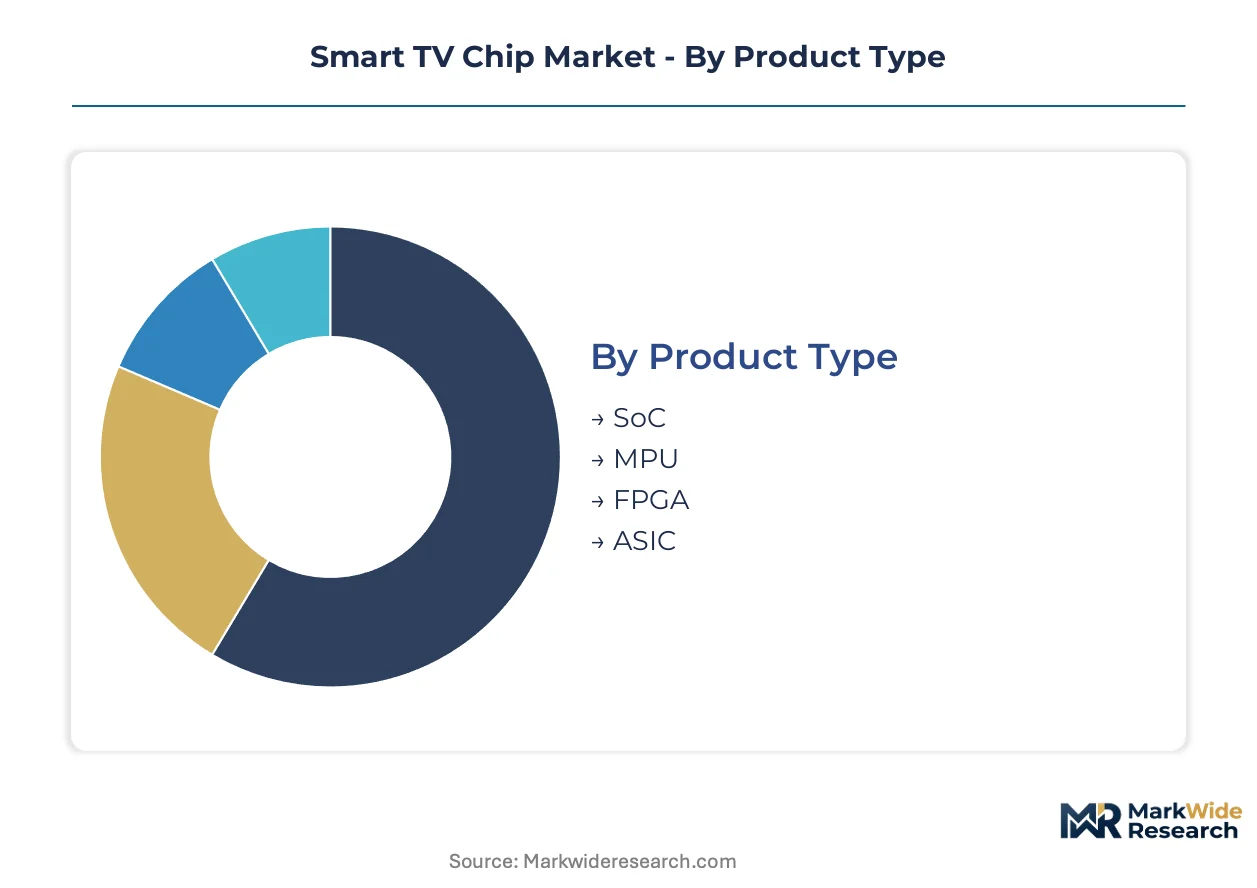
Chip procurement patterns diverge sharply across television industry channels, with streaming platform operators and panel manufacturers driving fundamentally different specification priorities than traditional retail distributors.
Product Type:
SoC architectures flow predominantly through direct OEM procurement channels, while discrete component categories serve specialized retrofit and premium customization markets.
- SoC:Integrates CPU cores, GPU clusters, video decoders, and neural processing units onto a single die fabricated at 7nm or smaller nodes. Demand concentrates with China-based panel makers and streaming platform operators consolidating procurement around integrated solutions for 4K/8K HDR streaming with sub-10-watt thermal envelopes.
- ASIC:Purpose-built designs for branded OEMs seeking differentiated feature sets including dedicated content protection circuits and hardware security modules. Expansion concentrates in direct co-development agreements with Netflix, Amazon Prime Video, and regional services mandating die-level customization.
- MPU:General-purpose microprocessor units serving legacy television retrofit markets and industrial display applications requiring modular upgrade paths.
- FPGA:Field-programmable gate arrays enabling rapid prototyping for emerging codec standards and regional certification variants before ASIC commitment.
SoC dominates installed base. ASIC is where expansion concentrates.
Technology:
Silicon content per unit scales directly with display technology maturity, creating three distinct cost tiers that reshape foundry allocation and margin capture.
- LED:Backlit LCD technology generating the highest chip volumes through mature supply chains and standardized driver IC requirements. Procurement flows through high-volume distributors serving mass-market retail channels.
- OLED:Self-emissive pixel technology commanding premium silicon content per unit with specialized timing controllers and compensation algorithms for burn-in mitigation. Demand concentrates in South Korean and Chinese panel maker captive procurement for premium television lines.
- QLED:Quantum dot enhancement layering requiring precise color management ICs and advanced HDR processing engines.
- MicroLED:Emerging direct-view technology with modular tile architectures demanding unprecedented pixel driver density and thermal management solutions.
LED commands volume leadership. MicroLED is climbing the fastest trajectory despite nascent commercialization.
End User:
Customer type determines specification authority, with downstream consolidation shifting influence from distributors to platform operators and panel manufacturers.
- Consumer Electronics:Branded television manufacturers specifying chips for retail shelf differentiation, increasingly ceding feature prioritization to streaming service certification requirements.
- OEMs:Original equipment manufacturers integrating chips into finished televisions, consolidating procurement power through direct foundry relationships and volume commitments.
- Retailers:Big-box and e-commerce channels influencing mid-range SKU mix through private-label specifications and regional bundle requirements.
- Distributors:Component wholesalers serving repair markets and regional assemblers with legacy inventory and cross-reference alternatives.
OEMs dominate installed base. Consumer electronics manufacturers are gaining share fastest as streaming certification reshapes specification authority.
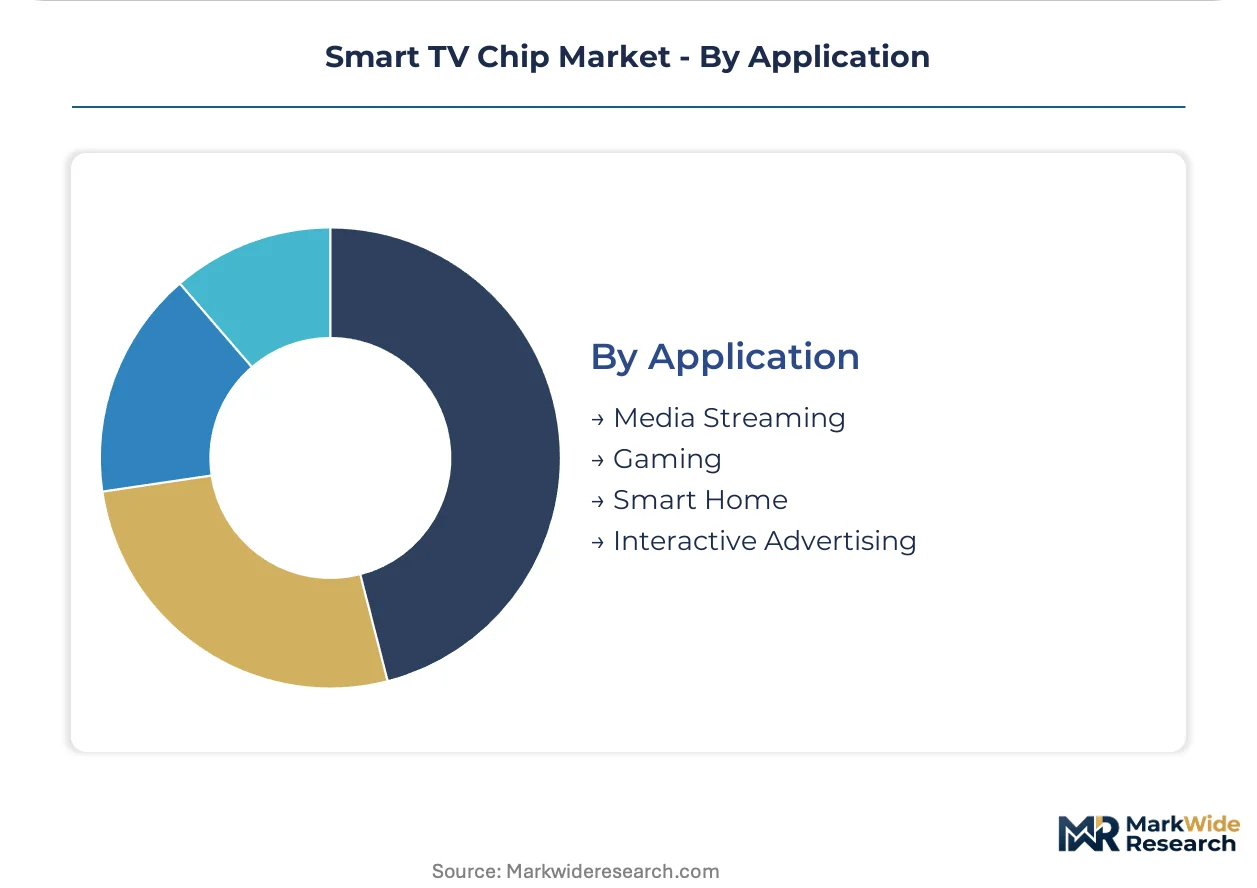
Application:
Use-case specialization is fragmenting chip architectures between premium AI-heavy designs and cost-optimized streaming-focused variants.
- Media Streaming:Hardware-accelerated AV1 and VVC decoding with DRM integration, representing the baseline requirement for all connected televisions.
- Gaming:Low-latency processing with integrated Wi-Fi 6E/7 modems and variable refresh rate support, merging television and console functions through cloud gaming convergence.
- Smart Home:Ambient intelligence and voice assistant processing requiring on-device neural inference for privacy-sensitive applications.
- Interactive Advertising:Targeted content delivery with viewer analytics and gesture recognition capabilities.
Media Streaming anchors volume. Gaming is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT cybersecurity mandates and GB standards for connected televisions are reshaping procurement patterns across China, while the FCC enforces electromagnetic compatibility thresholds that constrain power budgets for North American-bound chipsets.
China
Domestic panel manufacturers and streaming platform operators are consolidating volume orders for integrated SoC solutions. MIIT mandates require hardware security modules and data handling protocols that add firmware complexity. Shenzhen and Dongguan clusters host the densest concentrations of chip packaging and television assembly operations.
United States
FCC electromagnetic compatibility standards and Energy Star certification requirements are opening utility rebate procurement channels for low-standby-power designs. The IRA efficiency incentives align with aggressive sub-0.5-watt power targets. Austin and Silicon Valley house the primary design centers for high-performance gaming-television convergence chips.
South Korea
OLED panel makers are driving specialized timing controller and burn-in mitigation algorithm demand. REACH substance restrictions and RoHS hazardous material bans force substrate substitutions for European-bound shipments. Seoul and Suwon anchor the captive procurement relationships between display manufacturers and chip architects.
Germany
CE marking under EU Ecodesign Directive standby power caps below 0.5 watts is forcing power management subsystem redesigns. The EU Green Deal tightens networked standby efficiency mandates across the installed base. Dresden and Munich host foundry-adjacent design houses specializing in thermal-performance optimization.
India
Sub-$200 television segments remain underpenetrated by advanced chipsets, creating white space for cost-optimized architectures. BIS certification requirements and TRAI broadcasting standards shape regional feature prioritization. Noida and Bengaluru clusters are emerging as assembly hubs for localized content-integrated television platforms.
Smart TV Chip Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Smart TV Chip Market. MediaTek and Qualcomm anchor the consolidated premium segment through modem-graphics IP integration and Snapdragon-based gaming platforms respectively. Three archetypes dominate: integrated platform vendors with captive IP portfolios, fabless specialists focused on video codec acceleration, and captive silicon divisions of display ecosystem players. Competitive moves center on direct co-development agreements with streaming operators and migration to 5nm/3nm nodes for thermal envelope compliance.
Within the integrated platform tier, MediaTek Inc. and Qualcomm Incorporated exemplify the modem-graphics convergence strategy that sustains leadership in mid-range and premium segments. Amlogic Co., Ltd. anchors the cost-optimized streaming-focused archetype, occupying a position in high-volume emerging market procurement. These three entities represent the dominant competitive anchors against which specialist chip architects and captive display-maker silicon divisions position their alternative offerings.
| Leading Market Players |
|---|
| MediaTek |
| Qualcomm |
| Amlogic |
| Realtek Semiconductor |
| Novatek Microelectronics |
| HiSilicon |
| Rockchip |
| Broadcom |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Taiwan-based foundries and major SoC designers lock in wafer capacity allocation while providing price visibility across multi-year procurement cycles. These arrangements insulate volume buyers from spot-market volatility in advanced node pricing while committing foundry output to television chip architectures.
Pricing Analysis
China-to-Europe price spreads for equivalent 4K SoC tiers exceed those seen in other semiconductor categories due to MIIT certification overhead and REACH compliance costs. Three-tier pricing structure across premium AI-enabled, standard HDR-capable, and economy streaming-focused levels dominates procurement. Cost compression in mid-range segments intensifies as MediaTek and Amlogic compete for China panel maker volume. Retail distributors exhibit highest price sensitivity, while streaming platform operators prioritize die-level customization over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for 7nm and smaller nodes, while China concentrates back-end packaging and television assembly operations. Silicon content draws from specialized substrate suppliers, lead-free solder alternatives, and halogen-free laminates mandated by EU RoHS. Single-source vulnerability in Taiwan-based advanced logic capacity exposes continuity to geopolitical friction. Distribution runs through direct OEM procurement channels consolidated around panel makers and streaming operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Streaming platform vertical integration fragments specification authority, creating niche opportunities for architects who can bridge content protection requirements with thermal-performance constraints.
For Market Incumbents: Compound modem-graphics IP integration advantages through co-development agreements with Netflix and Amazon Prime Video that embed hardware security modules at die level. Add captive capacity reservation at Taiwan foundries to defend against emerging fabless specialists seeking 5nm allocation. Deepen backward integration into video decoder IP to offset AV1 expertise scarcity. For New Entrants and Emerging Players: Differentiate on India sub-$200 television segments where cost-optimized SoC architectures remain underpenetrated by advanced chipsets. Target white space in cloud gaming convergence chips requiring Wi-Fi 6E/7 modems with hardware-accelerated decoding. Pursue direct procurement relationships with domestic Indian assemblers in Noida and Bengaluru clusters. For Investors and Strategic Acquirers: Fabless video codec specialists with VVC hardware decoder capability represent priority acquisition targets given engineering talent scarcity and second-tier vendor R&D constraints. Long-term viability hinges on migration to 3nm nodes for thermal envelope compliance. Watch for MIIT cybersecurity mandate expansion as inflection indicator for firmware complexity investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Direct SoC Co-Development Agreement | Netflix and Amazon Prime Video mandate hardware security module integration at die level. |
| Advanced Node Migration | 5nm and 3nm fabrication commits address EU Ecodesign Directive thermal-performance squeeze. |
| Regional Certification Investment | CE marking, FCC electromagnetic compatibility, and MIIT validation extend time-to-revenue timelines. |
| Backward Integration into Video Decoder IP | AV1 and VVC hardware implementation expertise commands premium compensation in constrained talent pools. |
| India Localization Partnership | BIS certification and TRAI broadcasting standards enable sub-$200 television segment penetration. |
Research Methodology
Cross-validation between primary interviews with semiconductor design executives and secondary validation through SEC filings, customs trade data, and MIIT certification databases anchors the qualitative findings. Stakeholder roles span chip architects at fabless designers, procurement leads at China-based panel makers, regulatory affairs specialists navigating CE marking, and streaming platform hardware integration teams. Bottom-up unit shipment estimates triangulate against top-down foundry capacity allocation data.
Sensitivity analysis around EU Ecodesign Directive compliance timelines and Taiwan foundry utilization rates tests forecast robustness across the projection horizon. Segmentation dimensions span product architecture, display technology tier, end-user procurement authority, and regional regulatory cluster. CAGRs derive from node migration cost curves, AI inference engine penetration assumptions, and China panel ecosystem consolidation trajectories. Specific inputs include mask set cost inflation at 5nm and 3nm nodes, and AV1 decoder IP licensing velocity.
The analysis sits within stated boundaries; outcomes outside sustained China panel maker volume concentration or prolonged Taiwan foundry capacity constraints would require recalibration. Forecasts reflect assumptions about MIIT mandate enforcement intensity and REACH substance restriction expansion. Recalibration cycles align with material shifts in advanced node availability, streaming platform certification requirements, and EU standby power cap revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
GNSS Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Ceramic Chip Antenna Market
Communication Chips & Hardware
Global Network Processing Unit (NPU) Market
Communication Chips & Hardware
VR Device Chips Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Satellite Communication Components Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
Intelligent Cockpit Chip Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Communication Standard Logic IC Market