
 GNSS Chip Market | 2026-2036
GNSS Chip Market Size, Share, and Industry Trends Forecast 2026-2036
GNSS Chip Market Outlook
South Korea's semiconductor foundry expansion is reshaping GNSS chip fabrication capacity across East Asia. Qualcomm Technologies Inc. leverages its integrated modem-GNSS architecture to dominate smartphone socket wins. u-blox Holdings AG anchors its position through specialized automotive-grade modules with functional safety certification. STMicroelectronics N.V. competes on manufacturing scale, operating high-volume 40nm lines for cost-sensitive IoT applications.
A GNSS chip is a semiconductor device that receives and processes radio signals from multiple satellite constellations to compute precise position, velocity, and timing data, typically integrating RF front-ends, baseband processors, and embedded firmware within a single package. These chips enable location-aware functionality across commercial and industrial systems where spatial accuracy determines operational performance. Dual-Frequency technology leads in premium automotive and drone segments where ionospheric error correction justifies higher unit costs, while Single-Frequency modules occupy the high-volume consumer electronics tier with thinner margin pools. Real-Time Kinematic applications represent the fastest-growing technology category as precision agriculture and surveying operations demand centimeter-level accuracy without dedicated base stations.
The FCC enforces stringent out-of-band emission limits that shape RF front-end design requirements for US market access, while the EU's Radio Equipment Directive mandates interoperability testing across Galileo signal bands. Japan's MIC certifies QZSS augmentation compatibility as a condition for consumer device approvals. Stakeholders must monitor evolving multi-constellation mandates from regulators in China and India that will determine which signal combinations become baseline requirements for regional market entry.
Market Dynamics
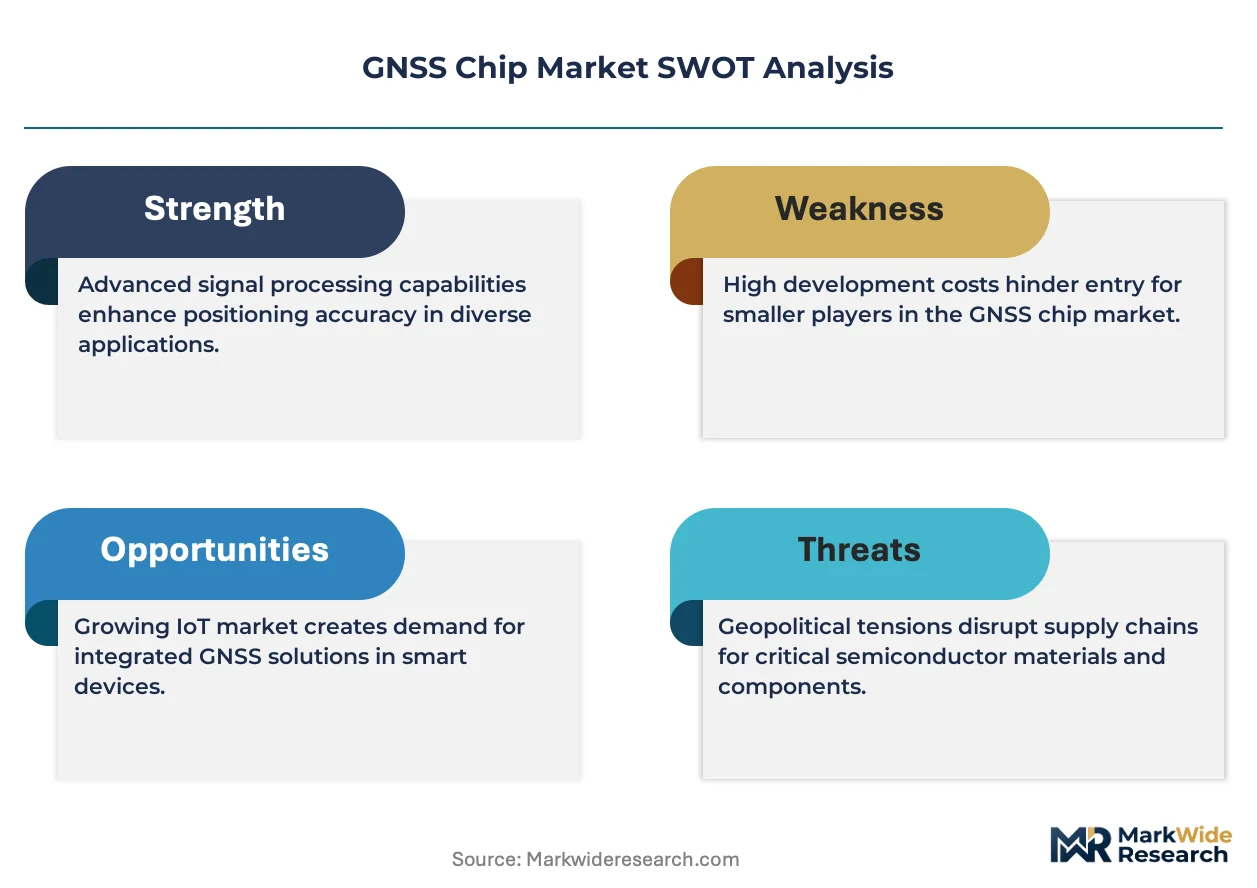
The GNSS chip market is experiencing structural pressure from multi-constellation mandates that force RF front-end redesigns and certification complexity across all major consumer and industrial sockets.
Growth Catalysts
- Dual-frequency automotive mandates:South Korean automotive OEMs embed dual-frequency GNSS modules for autonomous lane-keeping systems, creating specification pull through Tier-1 supplier chains.
- Precision agriculture expansion:Brazilian agribusiness operations deploy multi-constellation receivers across mechanized planting and harvesting fleets, demanding centimeter-level accuracy without dedicated base stations.
- FCC Part 25 integration rules:Tightened satellite integration benchmarks for chipset certification accelerate performance differentiation among RF architecture suppliers targeting US market access.
Market Restraints
- RF front-end cost structure:Multi-band L1/L5/E5a/E6 architectures require gallium arsenide low-noise amplifiers that concentrate in limited foundry capacity, creating input cost volatility.
- Foundry concentration risk:Advanced 40nm and 22nm GNSS baseband production clusters in Taiwanese and South Korean semiconductor fabrication facilities, exposing supply to geographic concentration.
- Ionospheric correction complexity:Dual-frequency ionospheric error correction algorithms demand 3x the digital signal processing resources of single-frequency alternatives, limiting cost-down trajectories in price-sensitive IoT tiers.
Strategic Opportunities
- Real-Time Kinematic white space:Surveying and construction operations in Germany and France adopt network-RTK services that eliminate dedicated base station infrastructure, opening chipset sockets for correction-service-integrated modules.
- EU Radio Equipment Directive tailwind:Mandated interoperability testing across Galileo E1/E5a/E6 signal bands creates certification-driven preference shifts toward multi-constellation-native architectures.
- Drone delivery channel innovation:Beyond-visual-line-of-sight logistics trials in Japan and Australia route through specialized UAV OEM channels that bypass traditional automotive and consumer electronics distribution.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-B qualification for automotive-grade GNSS modules extends development cycles 18-24 months, compressing competitive response windows.
- Multi-constellation firmware integration:Simultaneous GPS, GLONASS, Galileo, BeiDou, and NavIC tracking demands embedded software stacks that strain legacy real-time operating system architectures in existing automotive electronic control units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GNSS Chip Market |
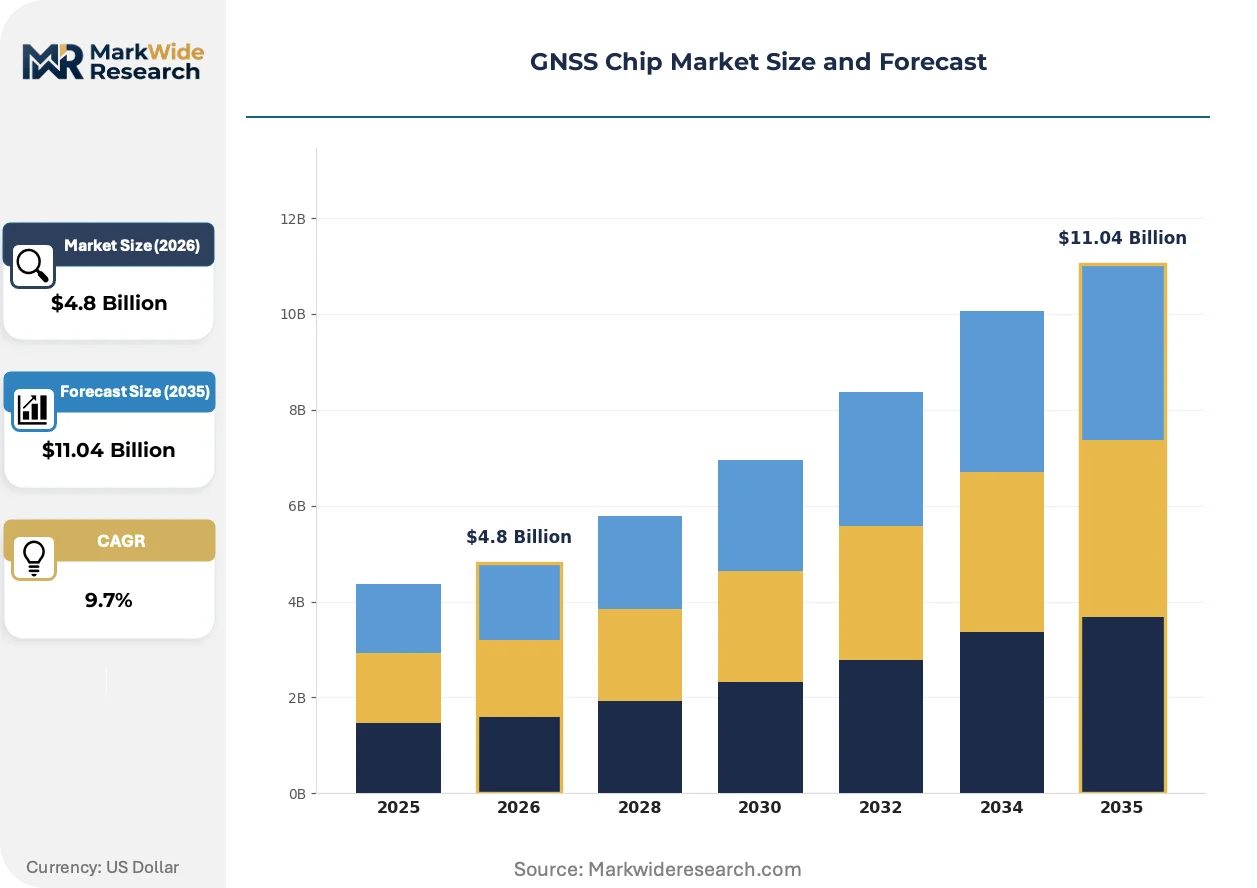
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
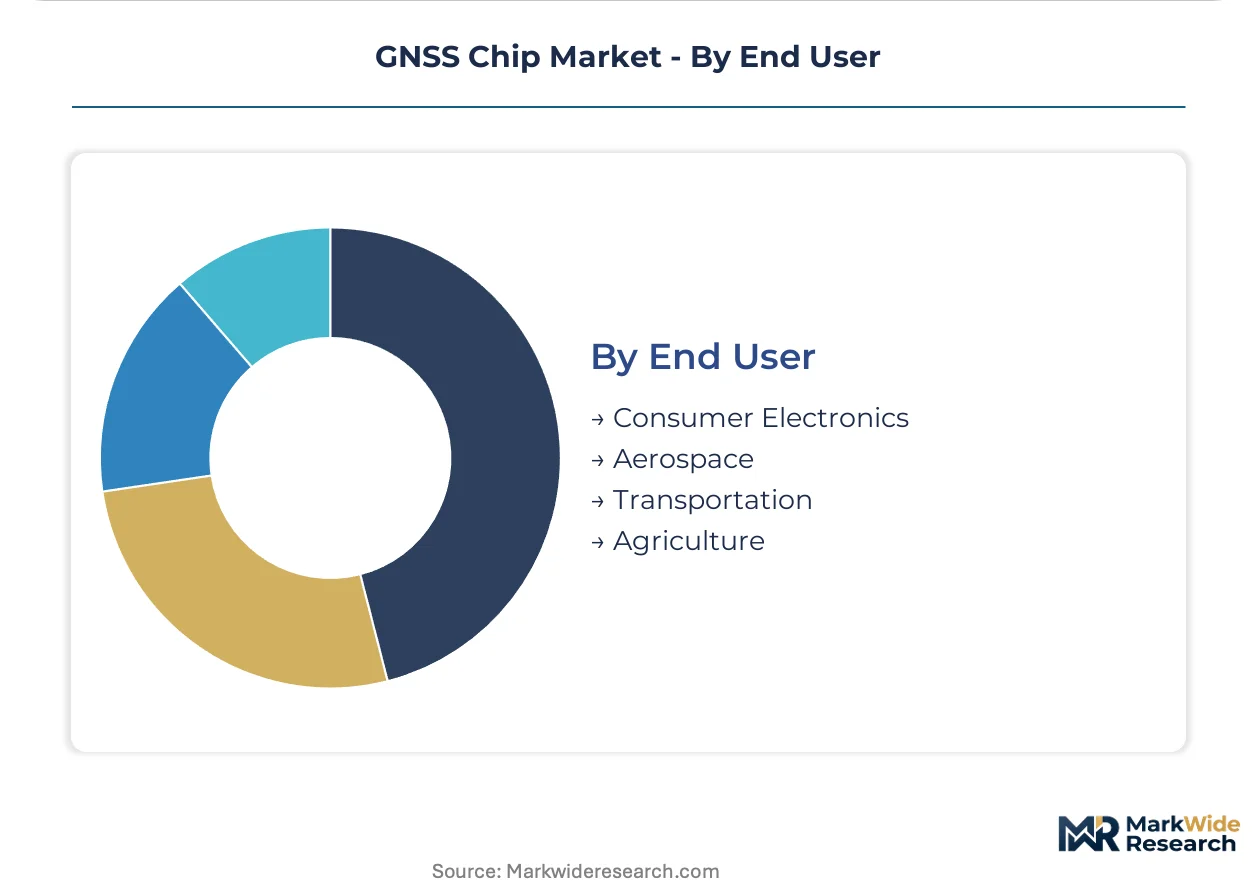
| Segmentation | Product Type: GPS, GLONASS, Galileo, BeiDou Application: Mobile Devices, Automotive, Drones, IoT Devices Technology: Dual-Frequency, Single-Frequency, Assisted GNSS, Real-Time Kinematic End User: Consumer Electronics, Aerospace, Transportation, Agriculture |
| Companies Covered | Broadcom Inc., u-blox Holdings AG, Qualcomm Technologies Inc., Trimble Inc., Skyworks Solutions Inc., STMicroelectronics N.V., Intel Corporation, Quectel Wireless Solutions Co. Ltd, Mediatek Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GNSS Chip Market Strategic Shifts
Signal processing architectures and procurement specifications are converging around multi-frequency, multi-constellation capability as baseline rather than premium tiering.
Triple-band RF front-ends integrating L1, L5, and E6 reception are migrating from high-end surveying equipment into mass-market automotive and smartphone platforms. Tier-1 automotive suppliers specify these architectures for highway pilot systems. The migration from discrete ceramic patch antennas to integrated conformal designs compresses module footprint and bill-of-materials cost.
Japan's MIC certification framework now mandates QZSS L1S/L5 signal compatibility as a condition for consumer device approvals. This regulatory requirement forces chipset vendors to embed augmentation service reception capability regardless of primary market targeting. Smartphone OEMs serving Japanese distribution channels absorb this as a non-negotiable design constraint.
Volume procurement specifications from Chinese smartphone OEMs now require simultaneous BeiDou B1I/B1C/B2a signal tracking alongside GPS and Galileo. This buyer-driven preference shift displaces single-constellation legacy modules from high-volume sockets. The specification compression is most visible in Shenzhen and Dongguan electronics manufacturing clusters where module vendors compete on constellation count rather than standalone GPS sensitivity metrics.
GNSS Chip Market Segmentation
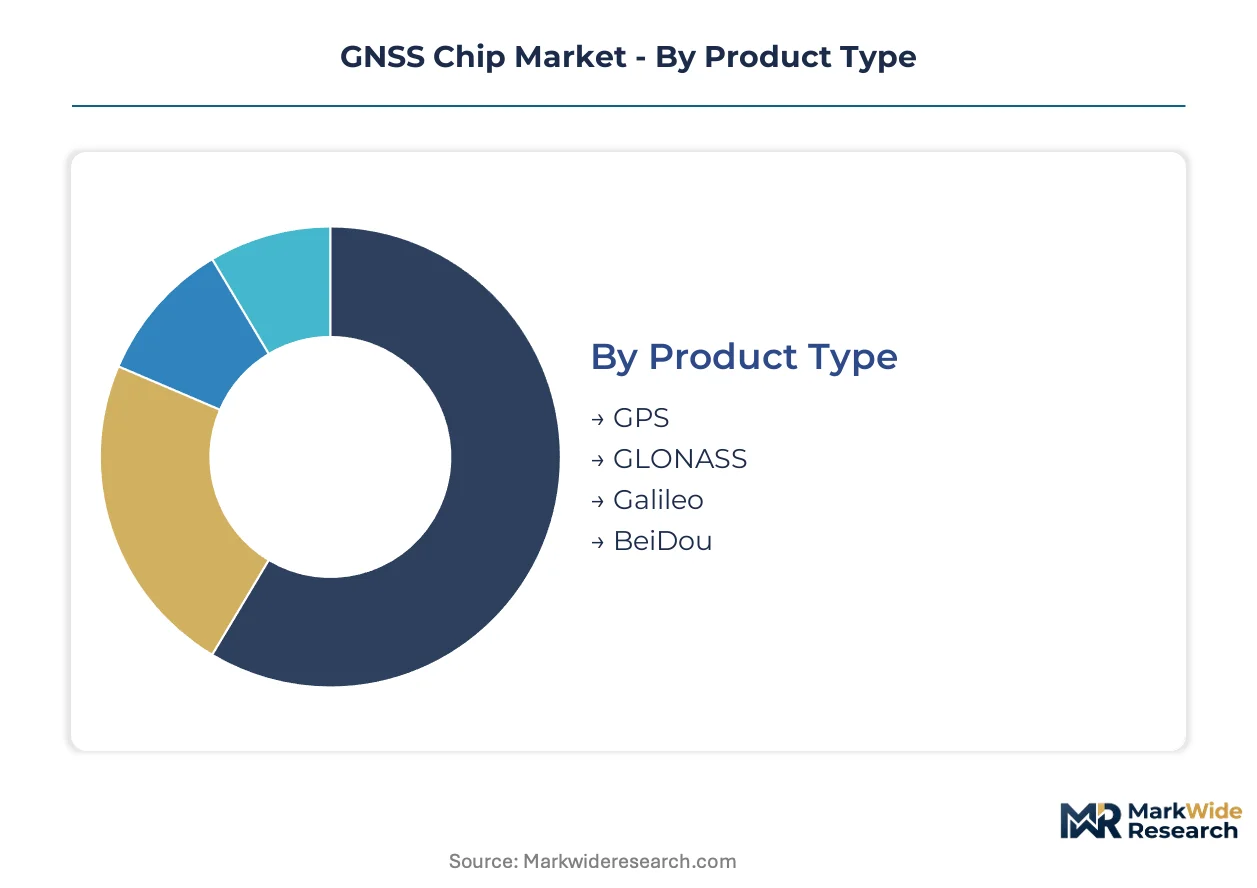
GNSS chip architectures fragment across signal constellation compatibility, frequency band processing capability, and precision tiering. Each segmentation axis carries distinct margin profiles and certification requirements that reshape supplier positioning across automotive, consumer, and industrial sockets.
Product Type:
Mature GPS-dominant designs coexist with emerging multi-constellation architectures as regulatory mandates and OEM specifications force signal diversity.
- GPS:Legacy L1 C/A code reception remains embedded in cost-constrained IoT trackers and basic wearables. South Korean automotive Tier-1s are phasing out GPS-only modules from new platform designs as dual-frequency mandates take effect.
- GLONASS:Russian FDMA signal tracking demands wider RF front-end bandwidth than GPS CDMA equivalents. Brazilian precision agriculture fleets specify GLONASS inclusion for high-latitude coverage where satellite geometry improves harvest-time positioning reliability.
- Galileo:European GNSS agency signal authentication features (OSNMA) enable spoofing-resistant positioning for financial timestamping and critical infrastructure.
- BeiDou:Chinese B1C/B2a signal structures enable PPP-B2b precise point positioning without terrestrial augmentation networks.
GPS retains volume leadership across legacy installed base; BeiDou holds the steepest expansion curve as Chinese OEM procurement specifications harden multi-constellation requirements.
Application:
Application segmentation traces divergent precision requirements and regulatory exposure across mobility platforms and connected devices.
- Mobile Devices:Smartphone GNSS modules prioritize power consumption and coexistence with cellular modem RF activity. FCC Part 15 emission limits constrain L5 band sensitivity in thin-form-factor designs where antenna aperture competes with 5G mmWave arrays.
- Automotive:ISO 26262 functional safety qualification separates qualified Tier-1 supply from consumer-grade alternatives. German KBA type approval processes for automated lane-keeping systems specify dual-frequency reception with defined availability metrics.
- Drones:Beyond-visual-line-of-sight regulations in Japan and Australia mandate multi-constellation reception for navigation integrity. UAV OEMs in Shenzhen specify RTK-ready modules for centimeter-level landing precision.
- IoT Devices:Asset trackers and smart city sensors operate on single-frequency architectures with assisted-GNSS ephemeris downloads to minimize time-to-first-fix.
Mobile Devices command the largest shipment volumes; Automotive generates the highest average selling prices per unit.
Technology:
Technology tiers stratify by signal processing complexity and ionospheric correction capability, with cost trajectories diverging sharply between precision and mass-market tiers.
- Dual-Frequency:L1/L5 or E1/E5a reception enables ionospheric error cancellation without network augmentation. South Korean automotive OEMs embed these modules for highway pilot systems where lane-level accuracy determines functional safety margins.
- Single-Frequency:L1-only architectures dominate price-sensitive consumer electronics where meter-level accuracy satisfies navigation and geotagging use cases.
- Assisted GNSS:Network-delivered ephemeris and almanac data compress cold-start acquisition time from 30+ seconds to under 5 seconds in urban canyon environments.
- Real-Time Kinematic:Carrier-phase differential processing achieves centimeter precision for surveying and precision agriculture. Brazilian agribusiness operations deploy network-RTK services that eliminate dedicated base station infrastructure.
Single-Frequency maintains the broadest installed base; Real-Time Kinematic is climbing the fastest as precision agriculture and construction automation expand.
End User:
End user categories reflect divergent procurement sophistication, with aerospace and transportation demanding traceable certification chains absent in consumer tiers.
- Consumer Electronics:Smartphone and wearable OEMs specify sensitivity and power metrics above absolute accuracy, with procurement concentrated among three dominant module vendors.
- Aerospace:Aviation GNSS receivers require DO-229D SBAS integrity standards for approach guidance, with dual-frequency multi-constellation architectures migrating from business aviation into commercial transport.
- Transportation:Fleet telematics and rail signaling systems specify availability and continuity metrics over raw precision, with EU ERTMS specifications driving multi-constellation adoption.
- Agriculture:Brazilian and Australian farming operations mechanize planting and harvesting with autosteering systems that demand sub-10cm pass-to-pass accuracy across growing seasons.
Consumer Electronics ships the highest unit volumes; Agriculture demonstrates the most rapid technology upgrade cycles as precision farming economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC enforces out-of-band emission limits that shape RF front-end design requirements for US market access, while regulators across Germany, South Korea, China, and Brazil impose constellation-specific mandates that fragment certification pathways.
United States
Automotive OEMs in Detroit and Silicon Valley specify dual-frequency modules for advanced driver-assistance systems. The FCC's Part 25 rules tighten satellite integration benchmarks for chipset certification. Austin and Phoenix semiconductor design clusters concentrate RF architecture development for consumer electronics sockets.
Germany
The KBA mandates dual-frequency reception with defined availability metrics for automated lane-keeping type approvals. German KBA processes compress competitive response windows for Tier-1 suppliers. Stuttgart and Munich automotive electronics clusters anchor functional safety qualification workflows for ISO 26262 ASIL-B modules.
South Korea
Seoul-based automotive OEMs embed dual-frequency GNSS modules for highway pilot systems. The country's national telecommunications regulator certifies augmentation compatibility as a condition for consumer device approvals. Suwon and Pyeongtaek foundry complexes expand 40nm and 22nm baseband fabrication capacity.
China
Shenzhen smartphone OEMs require simultaneous BeiDou B1I/B1C/B2a signal tracking alongside GPS and Galileo. The country's national radio regulation authority mandates multi-constellation interoperability testing. Dongguan electronics manufacturing clusters displace single-constellation legacy modules through constellation-count competition.
Brazil
Agribusiness operations in Mato Grosso and São Paulo deploy multi-constellation receivers across mechanized planting fleets. ANVISA coordinates with sector regulators on equipment import standards for precision agriculture. Campinas industrial clusters concentrate RTK service integration for network-based correction elimination.
GNSS Chip Market Competitive Environment
Integrated modem-GNSS architects and specialized automotive-grade module suppliers split the market along smartphone versus automotive socket lines. The vendor base concentrates around three tiers: premium automotive-qualified players, high-volume consumer electronics suppliers, and industrial-specialist niche operators. Dominant competitive moves include functional safety certification acceleration and multi-constellation firmware stack integration partnerships.
Within the integrated-architecture tier, Qualcomm Technologies Inc. and MediaTek Inc. exemplify modem-GNSS convergence strategies. u-blox Holdings AG and STMicroelectronics N.V. occupy positions within automotive-grade and cost-optimized IoT tiers respectively. These four entities anchor the competitive structure without exhausting its strategic diversity.
| Leading Market Players |
|---|
| Broadcom Inc. |
| u-blox Holdings AG |
| Qualcomm Technologies Inc. |
| Trimble Inc. |
| Skyworks Solutions Inc. |
| STMicroelectronics N.V. |
| Intel Corporation |
| Quectel Wireless Solutions Co. Ltd |
| Mediatek Inc. |
| Others |
Value Chain & Pricing Dynamics
Foundry undercapacity in Taiwanese 40nm and 22nm lines is compressing lead times for GNSS baseband wafers and forcing automotive module vendors toward dual-sourcing strategies that inflate qualification costs. This utilization squeeze transmits directly into pricing power for gallium arsenide low-noise amplifier suppliers serving multi-band RF front-ends.
Pricing Analysis
Geographic price spreads between South Korean automotive-grade modules and Shenzhen consumer electronics sockets exceed threefold, driven by ISO 26262 ASIL-B certification premiums versus thin-margin single-frequency alternatives. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer economy levels stratifies by functional safety investment and constellation count. Pricing pressure stems from Chinese smartphone OEMs demanding BeiDou B1I/B1C/B2a compatibility without unit cost premiums. Consumer electronics buyers exhibit extreme price sensitivity; aerospace and transportation segments absorb certification-driven premiums with minimal elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for RF front-end component sourcing. Gallium arsenide wafer processing concentrates in Taiwanese and South Korean foundries, while ceramic patch antenna substrates draw from Japanese and German specialty ceramics suppliers. Single-source vulnerability pervades advanced 22nm baseband production where TSMC and Samsung Foundry anchor capacity. Distribution runs through Tier-1 automotive electronics suppliers and Shenzhen module integrators serving divergent certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where network-RTK correction subscriptions and augmentation service bundles expand faster than discrete chip shipments. Recurring revenue from precision agriculture correction networks and automotive over-the-air firmware updates is reshaping supplier economics.
For Market Incumbents: Entrench functional safety certification leadership by accelerating ISO 26262 ASIL-B qualification cycles for dual-frequency architectures before emerging Chinese module vendors achieve automotive penetration. Deepen backward integration into gallium arsenide low-noise amplifier supply through captive foundry partnerships in South Korea, insulating against raw material volatility that threatens margin stability in multi-band RF front-ends. For New Entrants and Emerging Players: Establish a beachhead in network-RTK service-integrated modules for Brazilian and Australian precision agriculture operations where dedicated base station elimination creates immediate value capture. Target drone delivery OEM channels in Japan and Australia that bypass entrenched automotive supplier relationships; lead with centimeter-level landing precision specifications and QZSS L1S/L5 augmentation compatibility as differentiated entry credentials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-constellation firmware stack providers with embedded correction service distribution. Long-term viability centers on suppliers controlling both silicon architecture and augmentation service infrastructure across the analysis window. Acquisition priority targets automotive-qualified module vendors with established German KBA type approval track records; monitor FCC Part 25 certification velocity as inflection signal for US market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Constellation Firmware Integration | Simultaneous GPS, Galileo, BeiDou tracking satisfies Chinese OEM procurement mandates and Japanese MIC certification requirements. |
| Functional Safety Certification Acceleration | ISO 26262 ASIL-B qualification compresses competitive response windows for automotive lane-keeping system sockets. |
| Dual-Frequency RF Architecture Migration | L1/L5 reception enables ionospheric error cancellation for South Korean highway pilot specifications. |
| Network-RTK Service Partnership | German and French surveying operations eliminate base station infrastructure through correction-service-integrated module adoption. |
| Foundry Capacity Securement | Taiwanese and South Korean 40nm line access insulates against gallium arsenide low-noise amplifier input volatility. |
Study Parameters
The analysis maps RF front-end architecture tiers, baseband processing technology nodes, and augmentation service integration models, each validated through semiconductor procurement managers at Tier-1 automotive suppliers, smartphone OEM platform engineers, and precision agriculture fleet operators. Primary interviews with FCC certification consultants and German KBA type approval specialists combined with secondary validation against SEC semiconductor filings, FCC Part 25 docket records, and EU Radio Equipment Directive implementation guidance. Bottom-up shipment estimates by constellation compatibility and frequency band triangulated against top-down foundry capacity utilization disclosures.
Assumption sets held regulatory mandate timelines and multi-constellation interoperability requirements fixed while varying foundry capacity expansion scenarios and raw material price trajectories across the projection horizon. Segmentation dimensions modeled include signal constellation count, frequency band processing capability, precision tiering, and end-use application certification grade. CAGRs derived from unit shipment elasticity to automotive ADAS penetration curves and precision agriculture mechanization rates in Brazilian and Australian farming operations.
Stress conditions across gallium arsenide supply disruption, Taiwanese foundry capacity constraints, and FCC certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory mandate enforcement velocity and OEM specification adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
5G CPE Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
I2C Bus Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
Ethernet Access Device Market
Communication Chips & Hardware
Power Line Communication (PLC) Market
Communication Chips & Hardware
802.15.4 Chipset Market
Communication Chips & Hardware
ESP32 Module Market
Communication Chips & Hardware
Automotive Transceivers Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Semiconductors for Wireless Communications Market
Communication Chips & Hardware
Data Transmission Module Market