
 Taiwan Sensors Market | 2026-2036
Taiwan Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Sensors Market Insights
Market Context
Direct component distribution through Taiwanese electronics manufacturing service networks is reconfiguring how sensor suppliers reach end-equipment builders. Texas Instruments leverages its Dallas-based wafer fabrication with dedicated Taipei inventory hubs to sustain just-in-time delivery for motherboard integrators. STMicroelectronics competes through Geneva-coordinated R&D partnerships with National Cheng Kung University in Tainan. Bosch Sensortec anchors its position via Stuttgart-engineered MEMS dies packaged at Kaohsiung subcontractor facilities.
Technical Definition and Segments
Sensors are transducer devices that convert physical phenomena—temperature, pressure, light, proximity, acceleration—into measurable electrical signals, typically operating across voltage ranges from millivolts to standard logic levels for downstream processing. Their primary purpose spans process automation, environmental surveillance, human-machine interface control, and safety-critical feedback loops in electromechanical systems. Pressure sensors and MEMS-based inertial units capture expanding margin pools as Taiwanese automotive tier-1 suppliers adopt ISO 26262-compliant components for electric vehicle battery management. Wireless and digital technology segments outpace analog alternatives where Industrial Automation end users deploy LoRa and Bluetooth Low Energy protocols for factory floor mesh networks.
Regulatory Outlook
Taiwan's BSMI enforces compulsory product certification for sensors deployed in Building Automation and Healthcare Equipment, while the National Communications Commission regulates radio-frequency emissions from wireless sensor nodes. The Ministry of Economic Affairs Industrial Development Bureau coordinates with SEMI Taiwan to align local MEMS testing protocols with international IEC standards, creating compliance hurdles for uncertified imports. Stakeholders must monitor how forthcoming amendments to Taiwan's Cybersecurity Management Act reshape data governance requirements for sensors transmitting operational technology telemetry to cloud analytics platforms.
Market Dynamics
Semiconductor fabrication equipment procurement cycles in Hsinchu Science Park are compressing sensor qualification timelines, forcing suppliers to accelerate BSMI electromagnetic compatibility pre-certification before volume commitments.
Growth Catalysts
- Smart Factory Retrofits:Taichung's precision machinery cluster demands dense sensor arrays for predictive maintenance, pulling MEMS pressure and vibration units into retrofit contracts.
- BSMI Certification Alignment:Taiwan's Bureau of Standards, Metrology and Inspection mandates stricter electromagnetic compatibility protocols for industrial IoT devices, creating compliance-driven replacement cycles.
- Electric Vehicle Battery Management:Automotive tier-1 suppliers adopt ISO 26262-compliant pressure sensors and inertial measurement units for thermal runaway detection systems.
Market Restraints
- Wafer Supply Concentration:Advanced MEMS die fabrication concentrates among foundry operators in Hsinchu, exposing procurement to single-source disruption risk.
- Raw Material Volatility:Rare earth element pricing for magnetometer cores fluctuates with export quota adjustments from upstream suppliers.
- Technical Integration Limits:Legacy analog sensor architectures in existing factory floors resist seamless LoRa mesh network integration without signal conditioning retrofits.
Strategic Opportunities
- Underpenetrated Medical Wearables:Tainan's biomedical corridor shows minimal current sensor penetration for continuous glucose monitoring and cardiac telemetry devices.
- Cybersecurity Mandate Preparation:Forthcoming amendments to Taiwan's Cybersecurity Management Act will require encrypted telemetry transmission, favoring suppliers with pre-integrated hardware security modules.
- Bluetooth Low Energy Convergence:Factory automation buyers seek combined environmental and motion sensing in single BLE-enabled packages, collapsing multiple discrete sensor procurement into unified vendor relationships.
Industry Challenges
- MEMS Calibration Expertise Gap:Local packaging subcontractors in Kaohsiung lack sufficient yield engineers for sub-micron inertial sensor drift compensation.
- Multi-Standard Certification Burden:Simultaneous BSMI, IEC, and SEMI Taiwan protocol alignment extends product launch timelines by eight to fourteen months.
- Legacy System Integration Friction:Smart factory retrofits require protocol gateways to translate digital sensor outputs into analog PLC inputs, adding engineering cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Sensors Market |
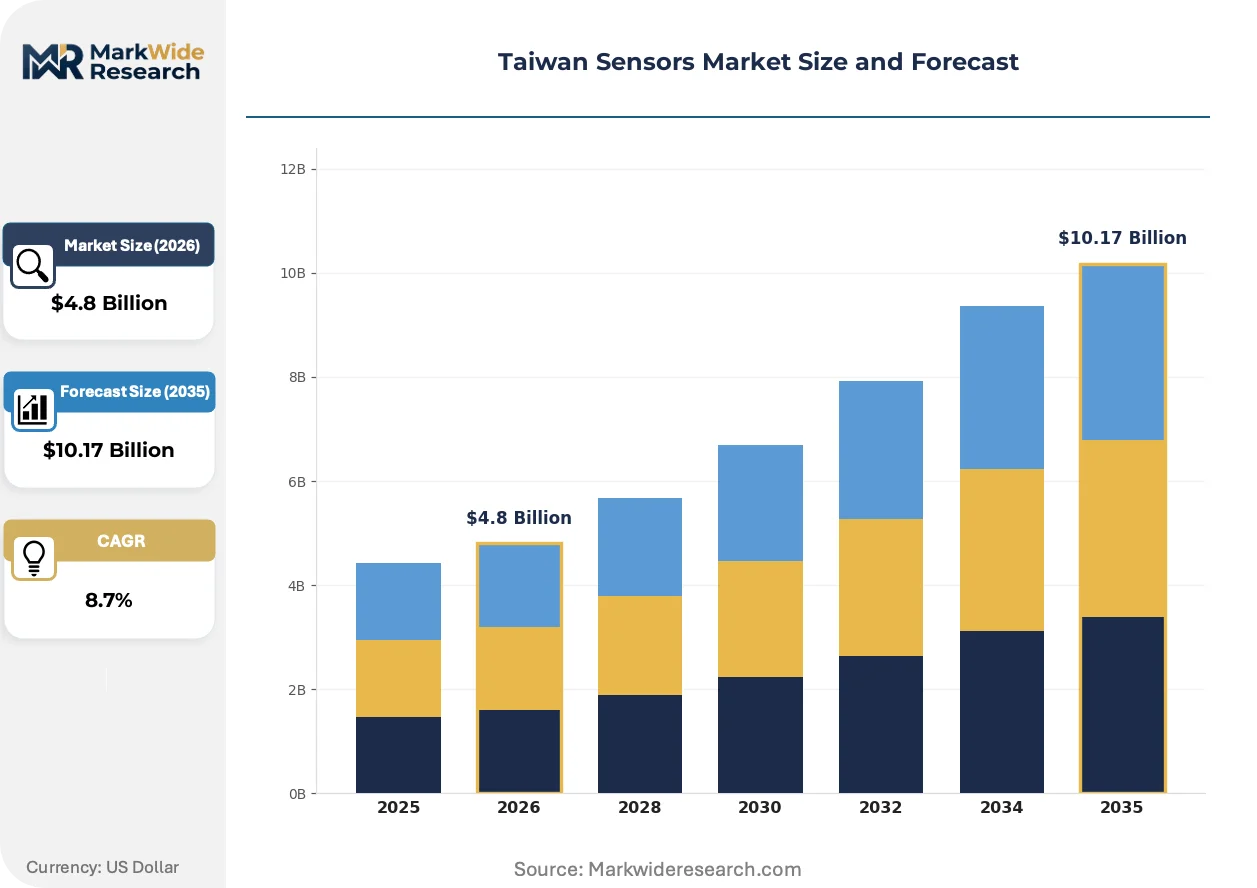
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Light Sensors Technology: Analog, Digital, Wireless, MEMS End User: Automotive Industry, Consumer Electronics, Healthcare Equipment, Industrial Automation Application: Building Automation, Smart Agriculture, Environmental Monitoring, Wearable Devices |
| Companies Covered | Texas Instruments Incorporated, STMicroelectronics Inc, Infineon Technologies AG, Bosch Sensortec GmbH, Honeywell International Inc, Vishay Intertechnology Inc, TDK Corporation, ams OSRAM AG, ABB Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Sensors Market Trends and Innovations
Sensor architectures in Taiwan are converging around wireless digital protocols and edge-computing capabilities, collapsing the traditional separation between sensing, processing, and transmission functions into unified modules.
Time-of-flight optical sensing is migrating from discrete proximity detection toward integrated 3D spatial mapping. Automated guided vehicle manufacturers in Taoyuan are adopting these modules for millimeter-precision warehouse navigation. The shift is compressing demand for conventional ultrasonic and infrared alternatives in logistics automation.
BSMI's phased implementation of stricter electromagnetic compatibility testing for industrial IoT devices is forcing component redesigns. Suppliers must now pre-validate shielding effectiveness and conducted emissions before factory acceptance trials. Medical equipment and building automation segments face the steepest compliance recertification schedules.
Buyer consolidation among motherboard integrators is collapsing distributor tiers. Direct component allocation from Taipei inventory hubs now reaches mid-sized equipment builders that previously relied on regional electronics distributors. Kaohsiung-based packaging subcontractors report shortened payment cycles and volume commitment pressures from this channel compression.
Taiwan Sensors Market Segmentation
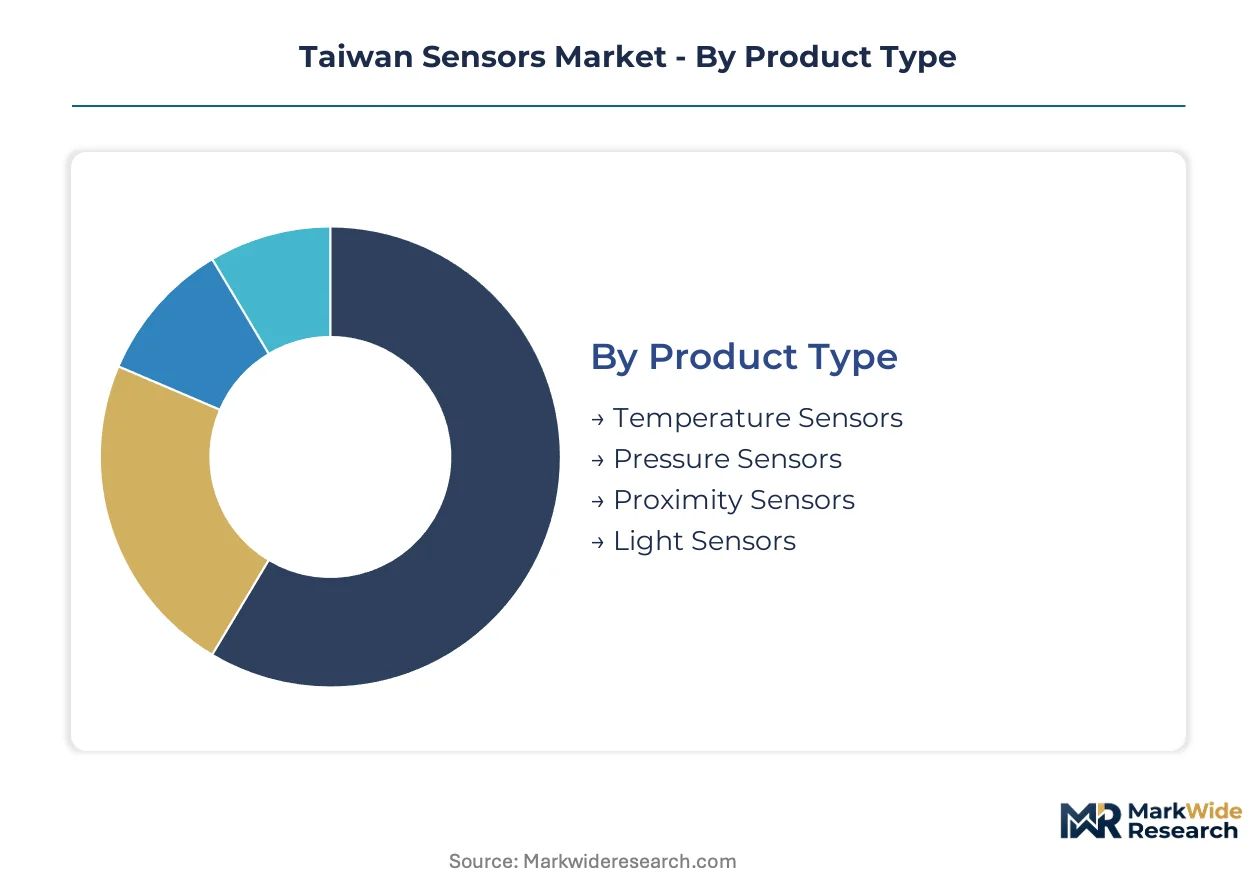
Taiwan's sensor market fragments across four critical dimensions that determine procurement priorities and margin structures. Product type and technology choices dictate foundry partnerships and certification pathways, while end-user concentration in Hsinchu and Taichung shapes regional demand patterns.
Product Type:
Mature commodity segments coexist with emerging precision categories across Taiwan's procurement landscape.
- Temperature Sensors:Thermocouple and RTD elements dominate process control installations in semiconductor fabrication facilities. Hsinchu Science Park equipment makers specify platinum thin-film devices for chamber thermal uniformity verification, driven by BSMI electromagnetic compatibility pre-certification requirements for new tool installations.
- Pressure Sensors:MEMS-based piezoresistive dies capture expanding automotive tier-1 procurement for electric vehicle battery management systems. Taichung precision machinery retrofits specify ceramic-capacitive variants for hydraulic system monitoring, pulled by predictive maintenance mandates in smart factory contracts.
- Proximity Sensors:Inductive and capacitive architectures serve industrial automation position detection. Automotive assembly lines in Taoyuan adopt time-of-flight optical modules for millimeter-precision component placement verification.
- Light Sensors:Ambient light and color-sensing photodiodes integrate into consumer electronics display management. Tainan biomedical device manufacturers evaluate spectral sensing for non-invasive diagnostic applications.
Pressure sensors handle the majority of throughput; MEMS-based pressure variants are climbing the fastest on share.
Technology:
Cost tier stratification separates legacy analog architectures from premium wireless and MEMS alternatives.
- Analog:Voltage-output transducers persist in legacy factory floor installations requiring minimal signal conditioning. Existing Taichung machinery retrofit projects face integration friction with these devices, forcing protocol gateway procurement.
- Digital:I2C and SPI-interfaced devices consolidate ADC functions on-die, reducing motherboard component count. Taipei inventory hubs stock digital output variants for just-in-time delivery to mid-sized equipment builders.
- Wireless:LoRa and Bluetooth Low Energy modules enable factory floor mesh networks without cable infrastructure. Industrial Automation end users in Taichung specify combined environmental and motion sensing in single BLE-enabled packages.
- MEMS:Micromachined silicon structures deliver miniaturized multi-axis sensing for inertial measurement. Kaohsiung packaging subcontractors report yield engineering gaps for sub-micron drift compensation in high-precision units.
Analog technology retains installed base dominance; wireless protocols are expanding most quickly in new procurement.
End User:
Application maturity varies sharply across Taiwan's industrial verticals, with automotive and industrial automation commanding premium component specifications.
- Automotive Industry:Tier-1 suppliers adopt ISO 26262-compliant pressure sensors and inertial measurement units for thermal runaway detection in electric vehicle battery packs. Component qualification timelines compress with semiconductor fabrication equipment procurement cycles.
- Consumer Electronics:Motherboard integrators source proximity and light sensors through direct allocation from Taipei inventory hubs. Channel compression eliminates regional distributor tiers for mid-sized equipment builders.
- Healthcare Equipment:BSMI enforces compulsory product certification for sensors deployed in diagnostic and patient monitoring devices. Tainan's biomedical corridor shows minimal current penetration for continuous glucose monitoring applications.
- Industrial Automation:Smart factory retrofits in Taichung demand dense sensor arrays for predictive maintenance, pulling MEMS pressure and vibration units into multi-year contracts.
Industrial Automation commands the largest procurement volume; Healthcare Equipment is gaining share fastest amid regulatory recertification cycles.
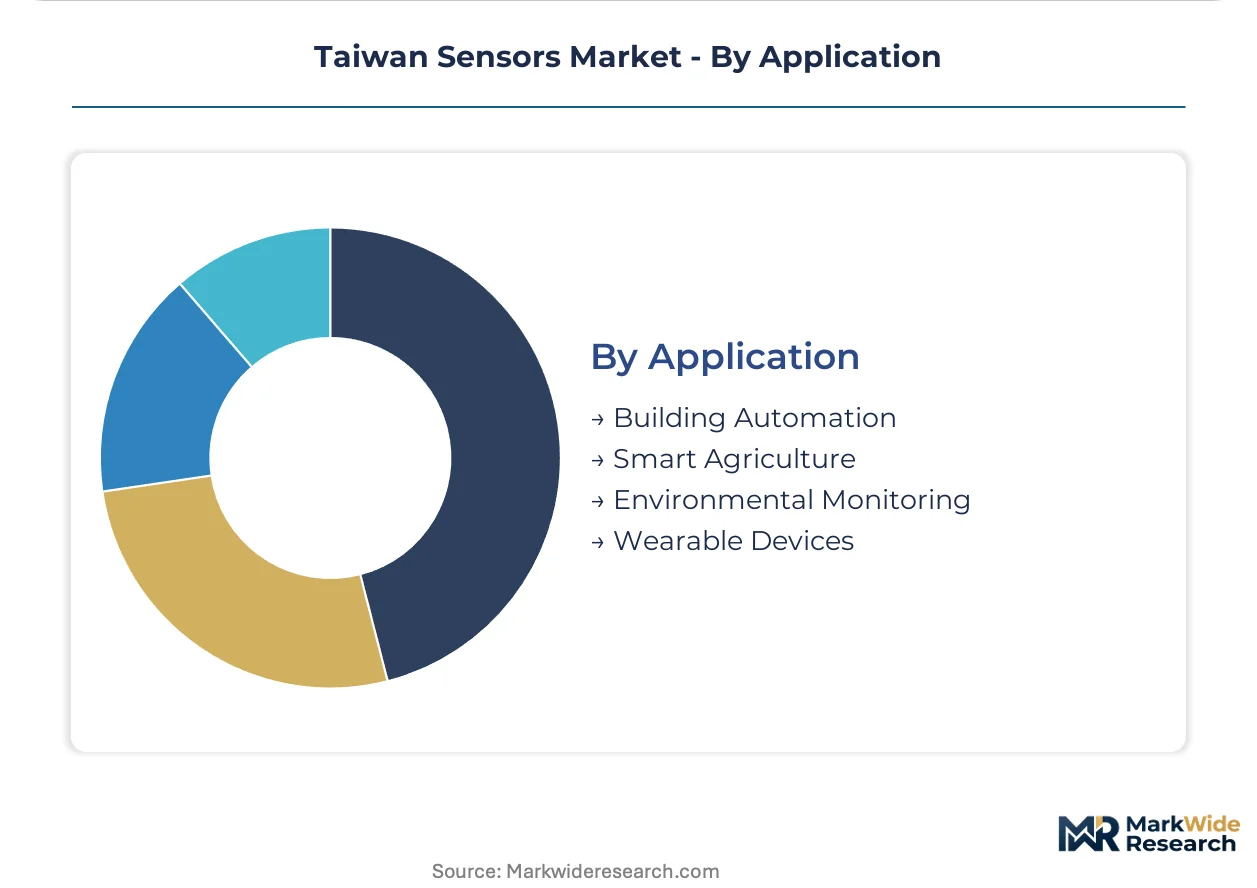
Application:
Geographic concentration of demand clusters around established industrial corridors, with emerging applications in agricultural and wearable segments.
- Building Automation:HVAC and lighting control systems require BSMI-certified environmental sensors for commercial real estate compliance. Electromagnetic compatibility testing protocol tightening forces component redesigns before factory acceptance trials.
- Smart Agriculture:Soil moisture and microclimate monitoring deploys wireless sensor nodes in central Taiwan agricultural zones. National Communications Commission radio-frequency emission regulations govern transmission equipment certification.
- Environmental Monitoring:Air quality and water contamination sensors serve regulatory compliance and industrial discharge verification. Ministry of Economic Affairs Industrial Development Bureau coordinates SEMI Taiwan alignment with international IEC standards.
- Wearable Devices:Motion and biometric sensing integration targets fitness and medical applications. Forthcoming Cybersecurity Management Act amendments will require encrypted telemetry transmission for cloud-connected devices.
Building Automation handles the majority of current deployment; Wearable Devices represents the steepest expansion trajectory ahead of regulatory mandate implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Taiwan's sensor procurement concentrates in Hsinchu and Taichung, while peripheral agricultural and medical corridors absorb higher logistics premiums for certified component delivery.
Northern Taiwan
Hsinchu Science Park equipment makers compress sensor qualification timelines for semiconductor fabrication tools. BSMI electromagnetic compatibility pre-certification now precedes volume procurement commitments from foundry operators. Taipei inventory hubs enable just-in-time delivery for motherboard integrators eliminating distributor tiers.
Central Taiwan
Taichung's precision machinery cluster demands dense MEMS pressure and vibration sensor arrays for smart factory predictive maintenance contracts. The Ministry of Economic Affairs Industrial Development Bureau coordinates SEMI Taiwan alignment with IEC standards for local retrofit projects. Kaohsiung packaging subcontractors face yield engineering gaps for sub-micron inertial sensor drift compensation.
Southern Taiwan
Tainan's biomedical corridor shows minimal current penetration for continuous glucose monitoring and cardiac telemetry sensors. Healthcare Equipment BSMI compulsory certification requirements tighten electromagnetic compatibility testing for diagnostic device deployments. National Cheng Kung University partnerships anchor Geneva-coordinated R&D collaboration for next-generation sensing architectures.
Western Coastal Agricultural Zones
Soil moisture and microclimate monitoring deploys LoRa-enabled wireless sensor nodes across central Taiwan farmland. National Communications Commission radio-frequency emission regulations govern transmission equipment certification for agricultural telemetry networks. Smart Agriculture buyers seek combined environmental sensing in single BLE-enabled packages collapsing discrete procurement.
Taiwan Sensors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin from MEMS die fabrication and calibration expertise. Market structure tilts toward consolidation among foundry-linked packaging subcontractors while independent distributors face channel compression. Two archetypes dominate: vertically integrated semiconductor houses with captive MEMS capacity, and fabless design houses reliant on Kaohsiung assembly partnerships. Competitive moves center on backward integration into wafer supply and accelerated BSMI pre-certification to compress qualification timelines.
Among US-based semiconductor houses, Texas Instruments Incorporated and Honeywell International Inc occupy positions anchored by domestic wafer fabrication and industrial automation heritage respectively. STMicroelectronics Inc represents the European fabless-tier archetype with Geneva-coordinated university partnerships. These three exemplify how geographic origin shapes regulatory navigation strategy and foundry relationship architecture in Taiwan's procurement environment.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| STMicroelectronics Inc |
| Infineon Technologies AG |
| Bosch Sensortec GmbH |
| Honeywell International Inc |
| Vishay Intertechnology Inc |
| TDK Corporation |
| ams OSRAM AG |
| ABB Limited |
| Others |
Pricing and Supply Chain Analysis
Kaohsiung Port container freight corridors feed directly into the pricing spread between configured MEMS pressure sensors and standard thermocouple elements. Hsinchu foundry concentration compresses logistics premiums for wafer-proximate buyers while Taichung retrofit contractors absorb elevated landed costs for certified component delivery.
Pricing Analysis
The customization-premium spread separates BSMI pre-certified MEMS inertial units from commodity analog temperature probes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume commitment scale. Cost compression in the economy tier intensifies because Kaohsiung packaging subcontractors compete on yield engineering for drift compensation. Industrial automation buyers in Taichung show highest price sensitivity due to multi-year predictive maintenance contract margins, while automotive tier-1 suppliers for electric vehicle battery management absorb premium positioning for ISO 26262 compliance.
Supply Chain Analysis
Contract-manufacturing concentration rests with Hsinchu foundry operators, Kaohsiung MEMS packaging subcontractors, and Taipei inventory hub distributors. Geographic supply concentration draws from Taiwan, Japan, and Germany for precision MEMS die fabrication. Raw material dependencies center on rare earth elements for magnetometer cores, platinum thin-film for temperature sensing elements, and specialized ceramic substrates for pressure sensor membranes. Single-source vulnerability concentrates in Hsinchu wafer fabrication for advanced MEMS architectures. Distribution runs through direct component allocation from Taipei inventory hubs to motherboard integrators, collapsing regional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges across Taiwan's sensor procurement landscape as smart factory retrofit mandates in Taichung and Hsinchu create specialized certification niches. The divergence between legacy analog installed base and wireless digital replacement cycles opens multiple entry paths.
For Market Incumbents: Harden qualification timeline advantages by accelerating BSMI electromagnetic compatibility pre-certification ahead of foundry equipment procurement cycles. Deepen captive MEMS calibration expertise in Kaohsiung to offset yield engineering gaps threatening sub-micron inertial sensor margins. Consolidate direct allocation relationships with Taipei inventory hubs before channel compression eliminates distributor leverage.
For New Entrants and Emerging Players: Tainan's biomedical corridor represents the most penetrable entry point for continuous glucose monitoring and cardiac telemetry sensors where current penetration remains minimal. Western coastal agricultural zones deploying LoRa-enabled soil moisture networks offer white-space expansion with lower certification burden than industrial automation. A go-to-market angle combining BLE-enabled environmental and motion sensing in single packages collapses discrete procurement into unified vendor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from European fabless design houses with Geneva-coordinated university partnerships seeking captive Taiwan packaging capacity. Long-term viability over the projection horizon hinges on regulatory alignment with forthcoming Cybersecurity Management Act amendments mandating encrypted telemetry transmission. The signal to watch is BSMI certification backlog length as proxy for compliance-driven replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| BSMI Pre-Certification Investment | Accelerates volume procurement commitments from Hsinchu semiconductor fabrication equipment makers. |
| Kaohsiung Packaging Partnership | Secures MEMS die assembly capacity with drift compensation yield engineering for automotive tier-1 suppliers. |
| BLE Convergence Product Launch | Collapses environmental and motion sensing procurement into single vendor relationships for Taichung factory automation buyers. |
| Tainan Biomedical Corridor Expansion | Captures underpenetrated demand for continuous glucose monitoring and cardiac telemetry sensor integration. |
| Hardware Security Module Integration | Positions for forthcoming Cybersecurity Management Act encrypted telemetry mandates in wearable and industrial applications. |
Research Methodology
A spread of perspectives from MEMS packaging engineers at Kaohsiung subcontractors, procurement directors at Taichung precision machinery clusters, regulatory affairs specialists navigating BSMI certification protocols, and semiconductor fabrication equipment planners in Hsinchu Science Park converged on the working assumptions. Secondary validation drew from BSMI electromagnetic compatibility testing bulletins, SEMI Taiwan MEMS protocol alignment documents, National Communications Commission radio-frequency emission regulations, and Ministry of Economic Affairs Industrial Development Bureau smart factory retrofit guidelines. Bottom-up sensor shipment estimates triangulated against top-down industrial automation capital expenditure patterns.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user vertical, and application geography. CAGRs derived from regression against historical procurement cycles in semiconductor fabrication equipment and precision machinery retrofit markets. Forecast inputs incorporated BSMI certification timeline compression effects and LoRa mesh network deployment rates in central Taiwan agricultural zones.
Macroeconomic conditions sit as an overlay; deviation in Taiwan dollar exchange rates, rare earth element export quotas, and semiconductor capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and foundry capacity expansion plans. Cross-checking against SEMI Taiwan equipment billings data and Hsinchu Science Park construction permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
North America Water Detection Sensors Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
France Air Purifier Market