
 Bluetooth in Automotive Market | 2026-2036
Bluetooth in Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth in Automotive Market Intelligence
A transition from single-source to multi-source procurement for Bluetooth modules is expanding across the automotive supply chain. General Motors leverages this strategy to de-risk its infotainment system development. Panasonic Corporation competes by offering highly integrated telematics control units to multiple OEMs. Toyota sustains its market position through long-term partnerships with a curated set of technology providers.
Bluetooth in automotive refers to the integration of short-range wireless communication technology operating in the 2.4 GHz ISM band. Its primary purpose is to enable seamless data exchange between vehicle infotainment systems, sensors, and consumer electronic devices. The adoption of Bluetooth 5.0 technology is displacing older standards due to its higher data rates and extended range. While In-Car Infotainment remains the largest application, systems supporting Driver Assistance and remote diagnostics represent the fastest-growing opportunity.
Compliance with radio frequency regulations from bodies like the U.S. FCC and China's MIIT is mandatory for market entry. Automotive safety standards set by the U.S. NHTSA and requirements for CE marking in Europe indirectly drive the integration of reliable connectivity for safety-critical functions. Stakeholders must now decide on investment priorities between enhancing cybersecurity for existing protocols and preparing for next-generation V2X communication standards.
Market Dynamics
The convergence of mandated safety features and the architectural shift toward software-defined vehicles is the central force shaping the market. Regulations like the EU's General Safety Regulation require connectivity that Bluetooth helps deliver for advanced driver-assistance systems.
Growth Catalysts
- Mandated Safety Systems:The European Union's General Safety Regulation compels the integration of features like intelligent speed assistance and driver drowsiness detection, which rely on robust internal vehicle connectivity that Bluetooth provides for sensor and system communication.
- Advanced EV Architectures:Demand from China's electric vehicle sector for sophisticated battery management systems (BMS) and remote diagnostics creates a significant pull for low-energy, reliable Bluetooth modules to transmit critical operational data.
- Technology Maturation:The adoption of Bluetooth 5.0 and its successors offers higher data throughput and extended range, enabling new applications beyond infotainment, such as digital key access and in-car payment systems.
Market Restraints
- Cybersecurity Vulnerabilities:The protocol's inherent susceptibility to exploits requires extensive and costly cybersecurity measures to protect vehicle networks from unauthorized access, adding complexity and cost to module development and integration.
- Spectrum Congestion:Operation in the crowded 2.4 GHz ISM band leads to potential interference from other devices like Wi-Fi routers and consumer electronics, posing a reliability risk for safety-critical applications.
- Regulatory Fragmentation:Divergent radio frequency certification requirements from bodies like the U.S. FCC and China's MIIT complicate the development of global vehicle platforms, forcing costly region-specific adaptations.
Strategic Opportunities
- V2X Communication Integration:There is a significant opportunity to integrate Bluetooth for short-range Vehicle-to-Pedestrian (V2P) and Vehicle-to-Device (V2D) communications as a complement to cellular V2X for enhanced safety.
- Sensor Fusion Platforms:Developing integrated modules that combine Bluetooth with other technologies like Ultra-Wideband (UWB) and NFC can create powerful platforms for secure vehicle access and personalization.
- Aftermarket Telematics:Underpenetration in the commercial vehicle and older passenger car segments offers an opportunity for aftermarket plug-in devices that use Bluetooth to connect to a driver's smartphone for fleet management and diagnostics.
Industry Challenges
- System Integration Complexity:Ensuring seamless interoperability between Bluetooth modules and a vehicle's numerous, often proprietary, electronic control units (ECUs) and legacy bus systems is a major technical hurdle for automotive engineers.
- Lifecycle Management:The challenge of managing firmware updates and security patches for Bluetooth components over a vehicle's ten-to-fifteen-year lifespan is a significant operational burden for OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth in Automotive Market |
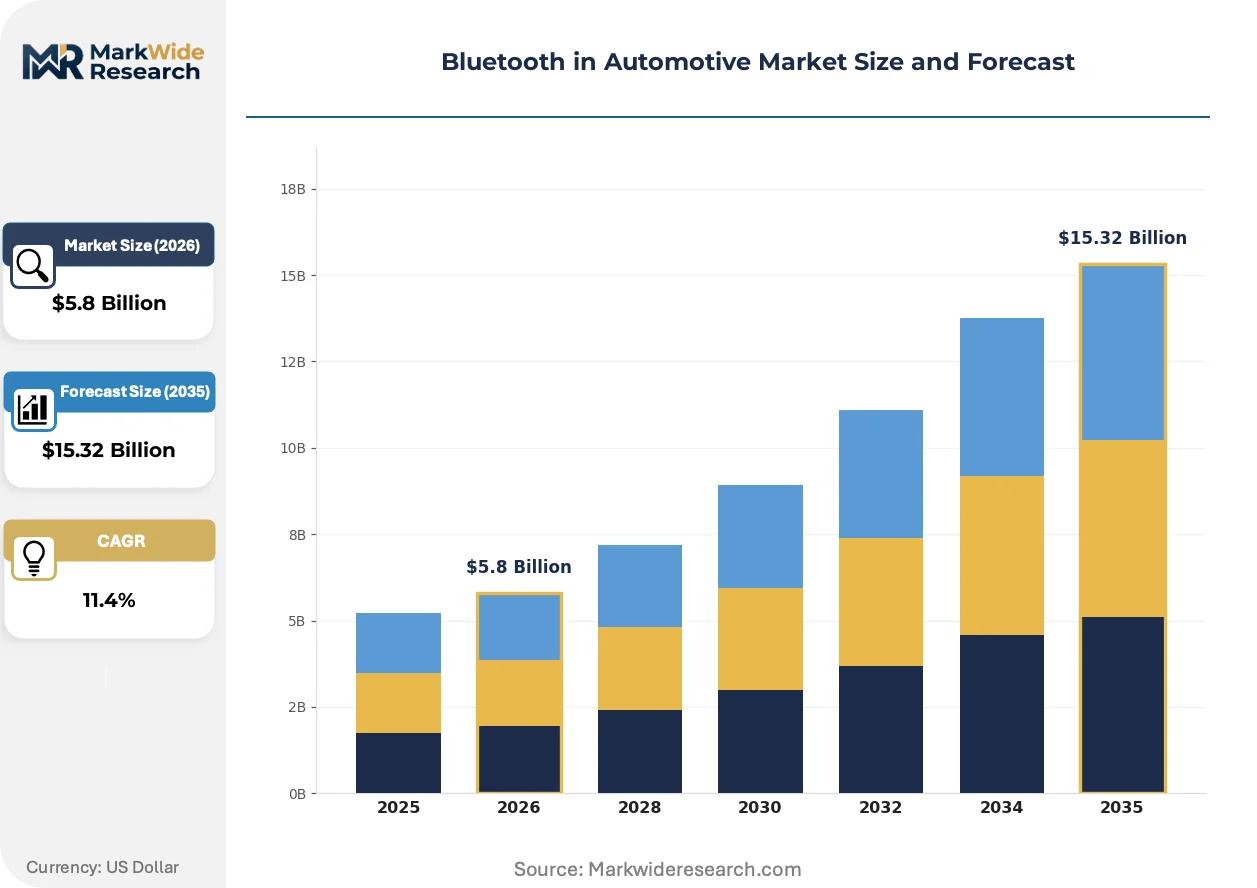
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Car Infotainment, Hands-Free Kits, Telematics Devices, Vehicle Sensors Technology: Bluetooth Classic, Bluetooth Low Energy, Bluetooth 5.0, Bluetooth Mesh Application: Driver Assistance, Navigation, Remote Diagnostics, Entertainment Systems, Fleet Management End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Volkswagen, Honda, Ford, FCA, Toyota, Volvo, Nissan, Panasonic Corporation, General Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth in Automotive Market Strategic Shifts & Innovations
Bluetooth's role is transforming from a peripheral for consumer convenience into an integral component of the vehicle's core operational and safety architecture. This evolution is driven by the industry's push towards more connected, intelligent, and software-defined automobiles.
Technology Evolution
Bluetooth Low Energy (BLE) provides persistent, low-power connectivity for a new class of in-vehicle sensors. Automakers are adopting BLE for functions like tire pressure monitoring systems and wireless battery sensors in electric vehicles. This technology is expanding into a foundational data layer for predictive maintenance services and real-time vehicle health monitoring, creating new service revenue streams.
Regulatory Shift
The UNECE WP.29 R155 regulation on cybersecurity is forcing a fundamental change in how connectivity features are designed and validated. This global standard mandates a certified Cybersecurity Management System, compelling automakers to secure all wireless interfaces, including Bluetooth, against potential threats. Tier-1 suppliers and module vendors are most affected, now required to prove security-by-design principles throughout the product lifecycle.
Demand-Side Shift
Automotive OEMs are increasingly adopting a multi-source strategy for commodity components like Bluetooth modules to de-risk supply chains. This change disrupts the traditional model of exclusive, long-term contracts with large Tier-1 suppliers, creating openings for smaller, specialized module manufacturers. This procurement pattern is most evident in North American and European automotive manufacturing hubs as they seek greater cost control and supply chain resilience.
Bluetooth in Automotive Market Segmentation
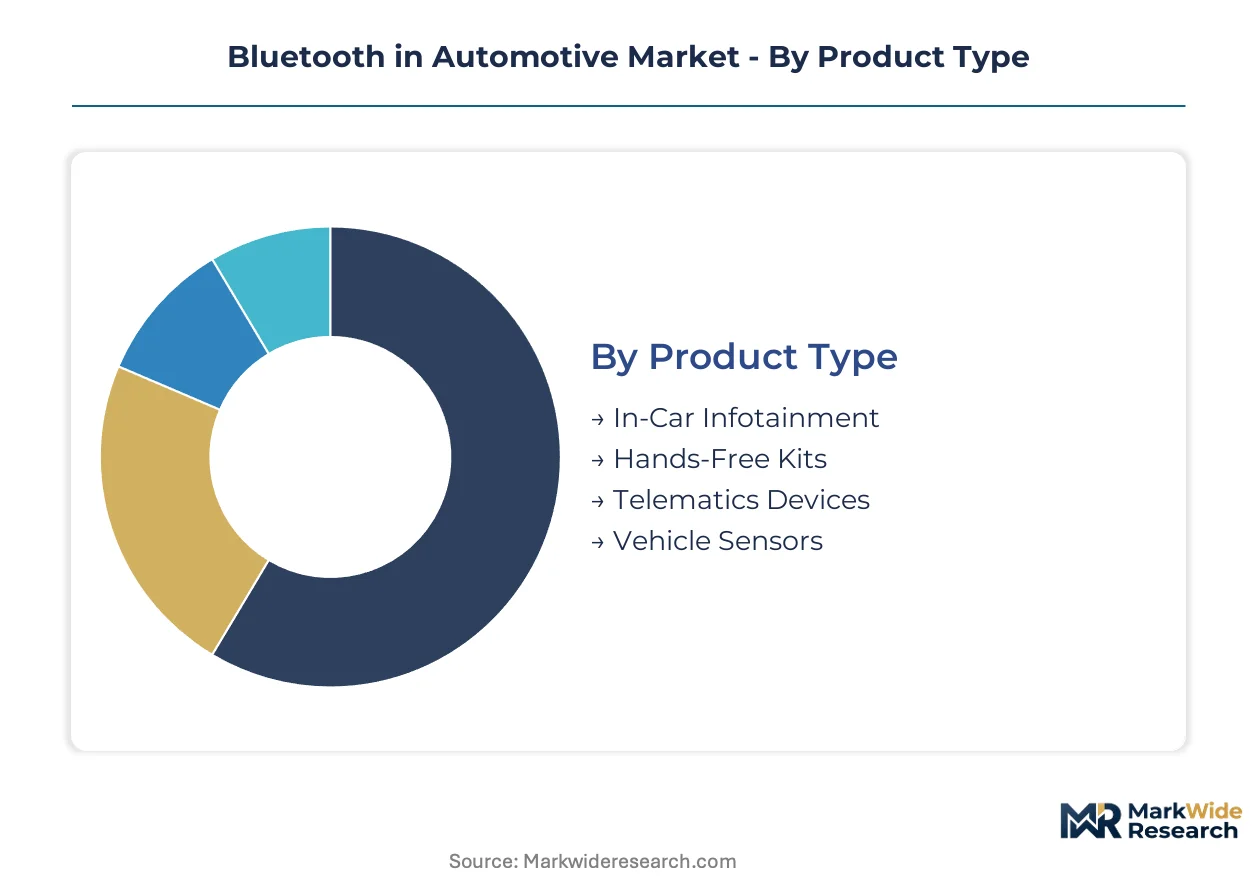
Bluetooth integration in automotive demands precise segmentation to understand varied market dynamics. This analysis dissects the market by product type, underlying technology, diverse applications, and distinct end-user categories. Understanding these segments illuminates specific growth vectors and competitive landscapes within vehicle connectivity.
Product Type:
The product type segmentation highlights the volume-driven components versus more specialized, premium offerings within automotive Bluetooth.
- In-Car Infotainment:In-Car Infotainment systems integrate Bluetooth for audio streaming, smartphone connectivity, and navigation data exchange. Demand concentrates in new vehicle sales across China, driven by consumer expectations for advanced digital cockpits.
- Hands-Free Kits:Bluetooth-enabled devices facilitating safe communication without manual phone interaction.
- Telematics Devices:Integrated units providing remote diagnostics, emergency calls, and vehicle tracking capabilities.
- Vehicle Sensors:Vehicle Sensors leverage Bluetooth Low Energy for transmitting data from tire pressure monitoring systems and battery management units. This segment sees significant pull from European OEMs due to mandated safety features and advanced EV architectures.
Mature deployment sits with Hands-Free Kits. Newer deployment is concentrated in Vehicle Sensors.
Technology:
Technology segmentation reveals the evolution from foundational standards to advanced, high-performance Bluetooth protocols.
- Bluetooth Classic:Older standard primarily used for audio streaming and basic data exchange in infotainment systems.
- Bluetooth Low Energy:Bluetooth Low Energy (BLE) provides continuous, energy-efficient wireless communication for various in-vehicle sensors and peripherals. This technology is increasingly vital for electric vehicle battery management systems and real-time health monitoring in the US market.
- Bluetooth 5.0:Bluetooth 5.0 offers enhanced data throughput, extended range capabilities, and improved energy efficiency for automotive applications. Its adoption is accelerating in newer vehicle platforms in Germany, supporting digital key access and advanced infotainment systems.
- Bluetooth Mesh:Enables large-scale device networks for lighting control and environmental sensing within vehicle cabins.
Bluetooth 5.0 represents the fastest-growing trajectory, while Bluetooth Classic maintains a legacy presence.
Application:
Application-based segmentation distinguishes between core convenience features and safety-critical functions within the vehicle.
- Driver Assistance:Driver Assistance applications utilize Bluetooth for sensor communication supporting features like intelligent speed assistance and driver drowsiness detection. Mandates from the EU's General Safety Regulation significantly drive the integration of these systems across European vehicle fleets.
- Navigation:Bluetooth connects smartphones for map data and traffic updates, enhancing in-car navigation experiences.
- Remote Diagnostics:Remote Diagnostics employs Bluetooth modules to transmit critical operational data for vehicle health monitoring and predictive maintenance services. This application is gaining substantial traction in China's electric vehicle sector for sophisticated battery management systems.
- Entertainment Systems:Facilitates audio streaming, multimedia playback, and connectivity for passenger devices.
- Fleet Management:Aftermarket solutions use Bluetooth to connect to driver smartphones for tracking and operational data collection.
Driver Assistance applications are expanding most quickly, while Entertainment Systems remain a foundational offering.
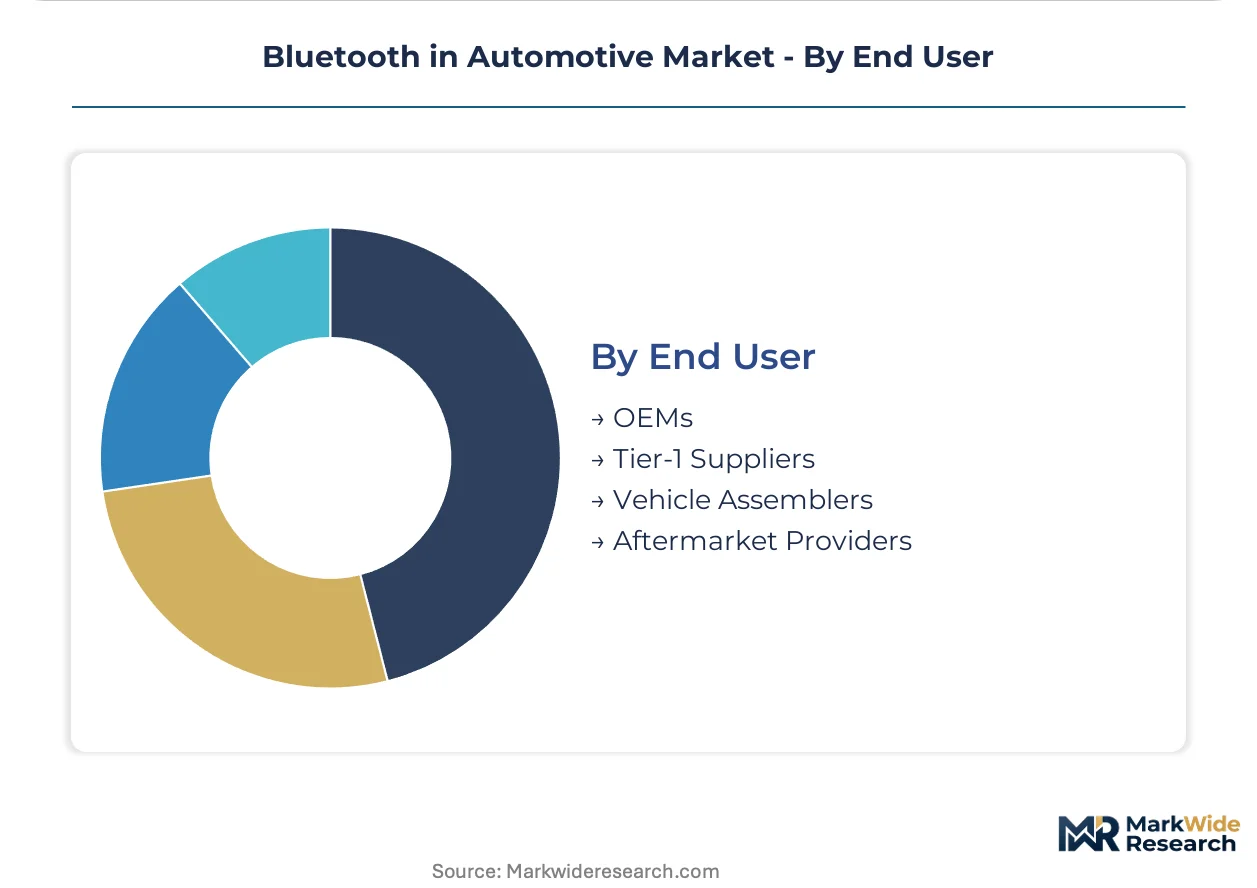
End User:
End-user segmentation clarifies the distinct roles and procurement patterns across the automotive supply chain.
- OEMs:Original Equipment Manufacturers (OEMs) integrate Bluetooth modules directly into new vehicle designs during the production phase. Companies like General Motors are increasingly adopting multi-source procurement strategies to de-risk their infotainment system development.
- Tier-1 Suppliers:Tier-1 Suppliers develop and provide integrated Bluetooth solutions, such as telematics control units, directly to automotive OEMs. Panasonic Corporation competes by offering highly integrated telematics control units to multiple vehicle manufacturers globally.
- Vehicle Assemblers:Focus on integrating pre-assembled modules and systems into the final vehicle structure.
- Aftermarket Providers:Supply Bluetooth-enabled devices for installation in existing vehicles, targeting segments like commercial fleets.
OEMs dictate initial integration strategies, while Aftermarket Providers address existing vehicle fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for advanced Bluetooth applications in automotive is evident across key global markets. China's electric vehicle sector creates significant pull for sophisticated battery management systems. European OEMs also drive adoption through mandated safety features requiring robust connectivity.
China
China's expansive electric vehicle sector drives significant demand for Bluetooth modules in battery management systems and remote diagnostics. The MIIT enforces strict radio frequency regulations, shaping module design for market entry. Cities within the Yangtze River Delta serve as hubs for advanced EV manufacturing and connectivity solution integration.
Germany
German automotive manufacturers accelerate Bluetooth 5.0 adoption for digital key access and sophisticated infotainment systems. Compliance with CE marking and the EU's General Safety Regulation mandates reliable connectivity for safety-critical functions. Bavaria's automotive industry clusters lead in developing integrated telematics control units.
United States
United States vehicle manufacturers increasingly integrate Bluetooth Low Energy for EV battery management systems and real-time health monitoring. The NHTSA's automotive safety standards indirectly drive demand for reliable connectivity in driver assistance applications. Michigan's automotive corridor focuses on developing advanced sensor fusion platforms.
Japan
Japanese automakers, including Toyota, maintain market position through long-term technology partnerships for integrated infotainment and sensor communication. METI's industrial policies encourage innovation in vehicle connectivity and digital key access systems. The Chubu region's automotive production cluster focuses on seamless module integration.
France
French automotive OEMs prioritize Bluetooth integration for driver assistance applications and robust internal vehicle connectivity. The EU's General Safety Regulation mandates features that rely on secure and reliable wireless communication. Île-de-France's automotive R&D centers explore V2X communication integration with Bluetooth.
Bluetooth in Automotive Market Key Industry Players
Procurement strategy shifts dominate the current landscape, reshaping how Bluetooth modules are sourced across the automotive supply chain. The market structure features a blend of large Original Equipment Manufacturers, established Tier-1 suppliers, and emerging specialized module manufacturers. Multi-source procurement strategies represent a dominant competitive move, de-risking supply chains for commodity components. Offering highly integrated telematics control units is another key strategy for market participants.
Among global automotive players, General Motors exemplifies the strategic shift towards multi-source procurement to enhance supply chain resilience. Panasonic Corporation, a prominent Tier-1 supplier, occupies a position focused on offering highly integrated telematics control units to various OEMs. Toyota, another major Original Equipment Manufacturer, anchors its market presence through long-term partnerships with a curated set of technology providers. These companies collectively illustrate the diverse approaches to integrating Bluetooth technology within the automotive ecosystem.
| Leading Market Players |
|---|
| Volkswagen |
| Honda |
| Ford |
| FCA |
| Toyota |
| Volvo |
| Nissan |
| Panasonic Corporation |
| General Motors |
| Others |
Cost & Logistics Intelligence
The transition to software-defined vehicles and advanced EV architectures reshapes Bluetooth module cost economics and concentrates sourcing towards specialized embedded systems providers. This shift influences both component pricing and the resilience of the overall supply chain.
Pricing Analysis
Warranty and service bundling significantly influences the effective price of Bluetooth modules, particularly for safety-critical applications. The dominant pricing structure is contract-based long-term offtake for OEMs, ensuring supply stability. Certification level, such as CE marking compliance, and customization for specific vehicle platforms drive price differentiation. Pricing softness reflects intense competition and the commoditization of basic Bluetooth Classic modules. Aftermarket providers are most price-sensitive, while OEMs prioritize reliability and long-term support.
Supply Chain Analysis
Reverse logistics for Bluetooth modules focuses on managing returns and facilitating firmware updates over the vehicle's lifecycle, impacting long-term operational costs. Automotive component supply concentrates in China, Germany, and Japan, leveraging established manufacturing ecosystems. The market relies on semiconductor chips and specialized antenna components as critical inputs. A structural risk is single-source vulnerability for advanced Bluetooth 5.0 chipsets. Distribution primarily runs through Tier-1 suppliers to OEMs for new vehicle integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bluetooth in automotive market is poised for consolidation, driven by stringent regulatory compliance costs that disproportionately burden smaller module manufacturers. Strategic positioning is critical for all market participants.
For Market Incumbents:Hedge against the commoditization of basic Bluetooth modules by investing in next-generation V2X communication integration. Deepen vertical integration into specialized software stacks for advanced driver assistance systems, securing long-term contracts with key OEMs. The threat of new entrants offering highly specialized, cost-effective solutions for specific EV architectures necessitates this focus. R&D in cybersecurity for existing protocols provides a critical lever to maintain market leadership.
For New Entrants and Emerging Players:Automotive aftermarket distributors represent a significant channel for new entrants to penetrate under-served commercial vehicle segments. Target the integration of Bluetooth Low Energy for advanced battery management systems in China's electric vehicle sector. The commercial fleet management segment is most penetrable due to demand for cost-effective remote diagnostics. Partner with telematics service providers to offer integrated plug-and-play solutions.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized module manufacturers with robust cybersecurity expertise or unique sensor fusion capabilities. The market demonstrates long-term viability over the next decade, driven by mandated safety features and software-defined vehicle trends. Target archetype includes firms possessing proprietary intellectual property in Bluetooth 5.0 and UWB integration. Monitor OEM multi-source procurement patterns for early signals of vendor consolidation or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bluetooth 5.0+ R&D | Enhances data rates and range for new safety-critical and convenience applications in German vehicles. |
| Secure Cybersecurity Certifications | Ensures compliance with UNECE WP.29 R155, protecting vehicle networks for European OEMs. |
| Form EV-focused Partnerships | Captures demand for sophisticated battery management systems in China's electric vehicle sector. |
| Develop Sensor Fusion Modules | Integrates Bluetooth with UWB/NFC for secure vehicle access and personalization in US markets. |
| Expand Aftermarket Telematics | Addresses underpenetration in commercial vehicle segments for fleet management solutions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. Interviews included OEM platform engineers, Tier-1 supplier procurement leads, automotive aftermarket distributors, and telematics service providers. Additional secondary sources comprised vehicle production databases, technology whitepapers, and financial reports of key market participants. A rigorous bottom-up and top-down triangulation process validated all data points.
Market volume and value were modeled at granular levels across product type, technology, application, and end-user segments. Compound Annual Growth Rates were derived from historical trends, expert projections, and future technology adoption curves over the projection horizon. Key forecast inputs included electric vehicle production forecasts and anticipated regulatory mandates from bodies like the EU's General Safety Regulation.
Caveats apply where unforeseen geopolitical events or rapid technological breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding the pace of software-defined vehicle adoption and cybersecurity investment. Practitioners should monitor evolving V2X communication standards and global radio frequency regulations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market