
 Automotive Over-The-Air (OTA) Market | 2026-2036
Automotive Over-The-Air (OTA) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Over-The-Air (OTA) Market Outlook
Automotive software distribution channels is narrowing as OEMs build proprietary update pipelines and tier-one suppliers race to embed themselves deeper. Tesla sustains end-to-end control over its fleet update cycles, while Robert Bosch GmbH anchors a broad supplier position across multiple OEM programs. Continental AG differentiates through integrated hardware-software stacks that span gateway modules to cloud backends.
Automotive Over-The-Air (OTA) refers to remote software and firmware delivery systems that transmit encrypted update packages to vehicle electronic control units via cellular, Wi-Fi, or satellite links, typically using differential compression to minimize payload size and ensure integrity through cryptographic verification. The technology enables bug fixes, feature activation, and security patching without physical service visits. Cellular technology leads deployment for its ubiquitous coverage, while edge computing architectures are gaining traction among fleet operators seeking localized update orchestration to reduce latency and bandwidth costs. Safety applications remain the highest-margin segment due to regulatory compliance requirements and liability exposure.
UN ECE R156 mandates cybersecurity management systems for vehicle type approval across UNECE member states, directly compelling OEMs to implement validated OTA capabilities. The EU AI Act and GDPR impose additional data governance requirements on cloud-based update infrastructures handling driver behavior telemetry. Stakeholders must weigh the capital intensity of in-house update platforms against supplier dependency risks as software-defined vehicle architectures become the primary competitive battleground.
Market Dynamics
Software-defined vehicle architectures are compressing hardware refresh cycles while expanding firmware monetization potential, forcing OEMs to choose between captive update platforms and supplier dependency.
Growth Catalysts
- UN ECE R156:European type-approval mandates for cybersecurity management systems compel validated OTA capabilities across UNECE member states, eliminating non-compliant vehicle configurations from sale.
- Differential compression algorithms:Payload minimization techniques reduce cellular bandwidth consumption by transmitting only binary deltas rather than full firmware images, cutting operational costs for fleet-scale deployments.
- Edge computing architectures:Fleet operators in Germany, the United States, and China deploy localized update orchestration nodes to reduce latency and satellite backhaul expenses for commercial vehicle pools.
Market Restraints
- Gateway hardware lock-in:Proprietary electronic control unit communication protocols create switching costs that bind OEMs to incumbent tier-one suppliers for multiple vehicle generations.
- Cellular infrastructure dependency:Rural coverage gaps in Brazil, India, and Australia force fallback to Wi-Fi tethering, fragmenting update reliability and customer experience consistency.
- EU AI Act data governance:Cloud-based update infrastructures processing driver behavior telemetry face expanded audit obligations and cross-border transfer restrictions that inflate compliance overhead.
Strategic Opportunities
- Feature-on-demand monetization:Heated seats, advanced driver-assistance functions, and battery capacity unlocks create recurring revenue streams from hardware already installed at production.
- India and Southeast Asia:Low connected-vehicle penetration relative to production volume offers first-mover advantage for localized OTA infrastructure partnerships with domestic OEMs.
- Satellite-to-vehicle direct links:Low-earth orbit constellations bypass terrestrial cellular gaps, enabling update delivery to mining trucks, agricultural equipment, and remote fleet assets.
Industry Challenges
- Cryptographic key lifecycle management:Fleet-scale certificate rotation and revocation across millions of vehicles demands specialized DevSecOps talent scarce in traditional automotive engineering organizations.
- Multi-ECU rollback coordination:Interdependent control units require atomic update orchestration where partial failures risk bricking powertrain or braking systems, complicating validation matrices.
- GDPR telemetry anonymization:Update systems must strip personally identifiable data from diagnostic logs without degrading failure-analysis utility, stretching data engineering capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Over-The-Air (OTA) Market |
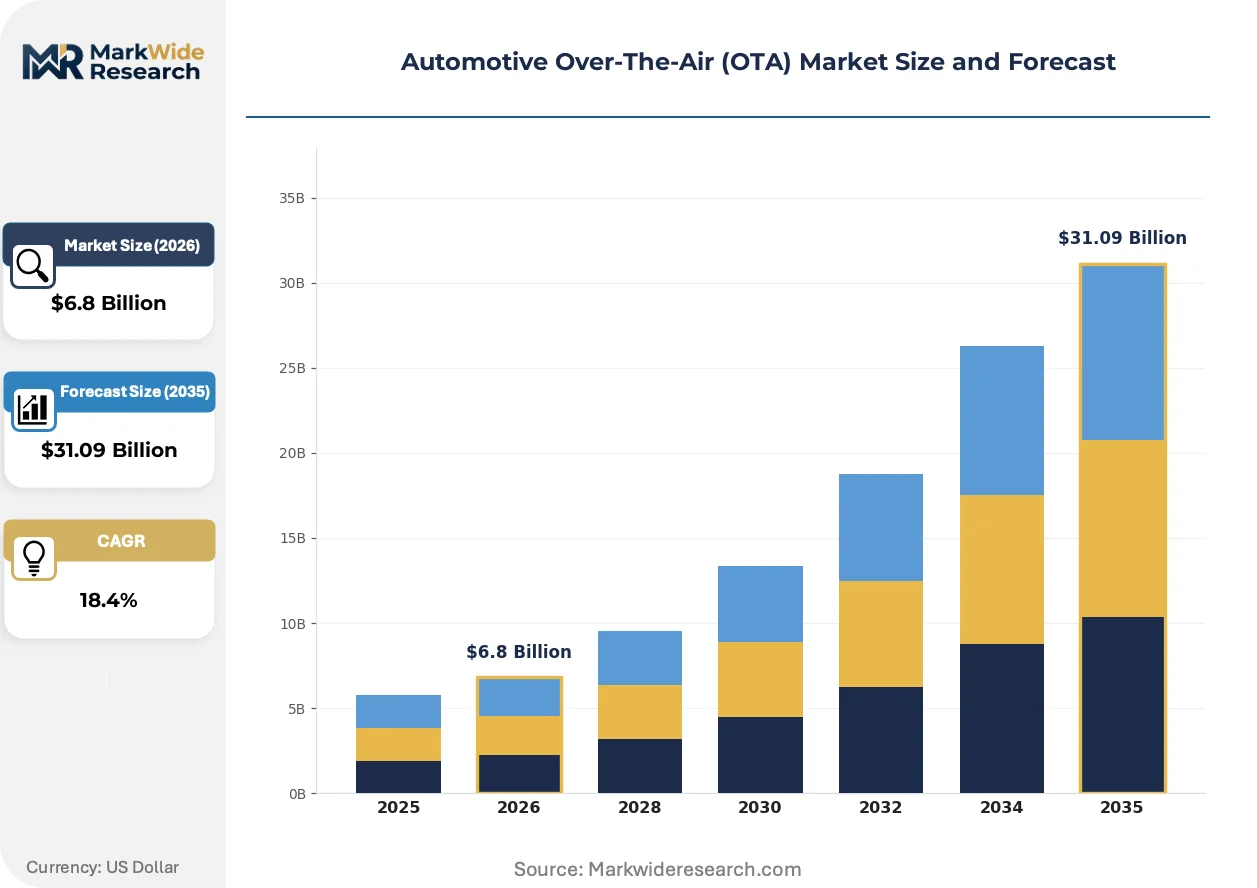
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cellular, Wi-Fi, Satellite, Bluetooth Application: Infotainment, Vehicle Control, Navigation, Safety End User: OEMs, Fleet Operators, Aftermarket Providers, Consumers Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | Tesla, Robert Bosch GmbH, Continental AG, HARMAN International, Aptiv PLC, NXP Semiconductors, Qualcomm Technologies, Inc., Denso Corporation, Airbiquity Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Over-The-Air (OTA) Market Strategic Shifts
Firmware delivery architectures are fragmenting across cellular, satellite, and edge pathways while regulatory mandates harden security requirements and buyer expectations shift toward continuous feature access.
Automotive OTA is migrating from monolithic full-image downloads to containerized micro-update architectures. Tier-one suppliers and OEM software divisions adopt modular packaging that isolates powertrain, infotainment, and chassis domains. This migration from legacy all-or-nothing updates compresses validation timelines and enables granular rollback capabilities that reduce warranty exposure.
UN ECE R156 and the EU AI Act together impose layered compliance obligations on European-bound vehicles. Cybersecurity management system documentation must accompany type approval, while AI-enabled features delivered via OTA face algorithmic transparency requirements. German and French OEMs respond by segregating European update infrastructures from global stacks, duplicating cloud expenditure to satisfy divergent regulatory regimes.
Fleet procurement departments now specify update service-level agreements as distinct contract line items separate from vehicle acquisition. Commercial operators in the United States negotiate guaranteed patch delivery windows and downtime compensation clauses. This behavioral shift forces OEMs to price OTA reliability as a standalone performance metric rather than bundled warranty coverage.
Automotive Over-The-Air (OTA) Market Segmentation
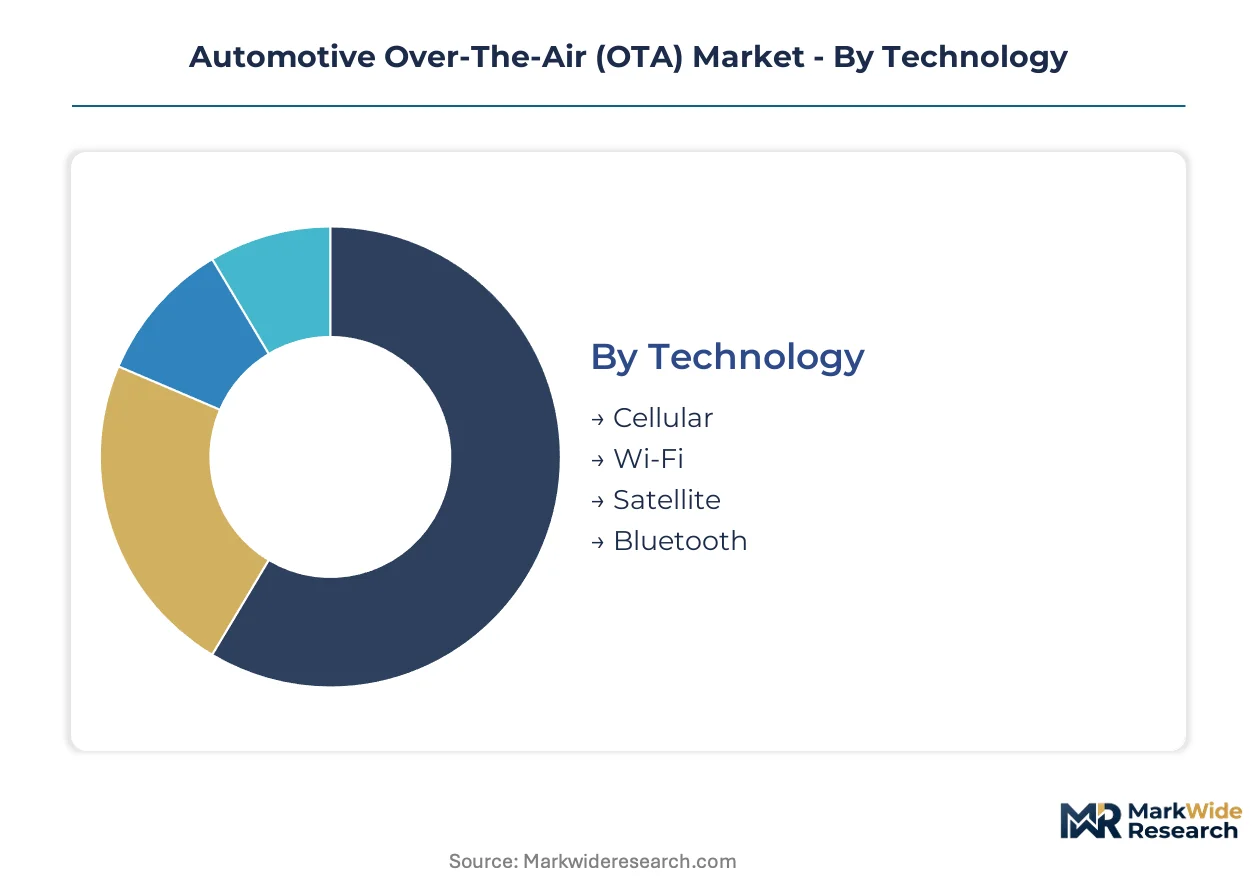
OTA segmentation reveals how update delivery economics vary sharply by connectivity pathway and customer archetype. After-sales-service intensity differs dramatically between fleet operators managing thousands of vehicles and individual consumers receiving intermittent feature patches.
Technology:
After-sales-service intensity varies by connectivity pathway, with cellular networks demanding continuous carrier relationship management while satellite links require specialized ground station coordination.
- Cellular:Dominant deployment mode leveraging 4G/5G networks for encrypted payload transmission with differential compression. Demand concentrates in Germany, the United States, and China where carrier infrastructure density supports fleet-scale orchestration and regulatory mandates for continuous security patching drive operational priority.
- Wi-Fi:Secondary pathway for garage-based updates and residential charging scenarios, reducing cellular bandwidth costs for large firmware downloads. Adoption clusters in suburban North American markets and European multi-vehicle households where home connectivity reliability exceeds public network consistency.
- Satellite:Essential for remote fleet assets including mining trucks and agricultural equipment operating beyond terrestrial coverage.
- Bluetooth:Limited to localized diagnostic bridging and smartphone-tethered update initiation in legacy vehicle architectures.
By volume, Cellular leads. By growth pace, Satellite is expanding most quickly as low-earth orbit constellations achieve commercial viability.
Application:
Application segmentation tracks how software-defined vehicle architectures redistribute engineering investment across functional domains, with safety-critical systems commanding stricter validation protocols.
- Safety:Highest-margin segment encompassing advanced driver-assistance system calibrations, braking module updates, and airbag control unit patches. UN ECE R156 mandates in Europe and NHTSA guidance in the United States impose cryptographic verification standards that inflate development overhead but create pricing power through compliance necessity.
- Infotainment:Most frequent update category enabling streaming service integrations, user interface refreshes, and third-party application ecosystems. Consumer expectations for smartphone-parity experience in Germany and the United States drive compressed release cycles that strain traditional automotive quality gates.
- Vehicle Control:Powertrain and chassis domain updates requiring atomic rollback capabilities.
- Navigation:Map data and route optimization algorithm refreshes with lower criticality thresholds.
Safety commands premium pricing. Infotainment generates the highest update frequency.
End User:
End user segmentation exposes divergent procurement behaviors, with fleet operators negotiating service-level agreements while consumers absorb bundled warranty coverage.
- Fleet Operators:Commercial vehicle managers specifying guaranteed patch delivery windows and downtime compensation in standalone contracts. United States-based logistics companies and German rental car aggregators increasingly separate OTA reliability metrics from vehicle acquisition pricing, forcing OEMs to operationalize update infrastructure as a subscription service.
- OEMs:Captive software divisions and tier-one supplier partnerships building proprietary update pipelines. Volkswagen Group, General Motors, and BYD maintain end-to-end control over fleet orchestration to preserve data sovereignty and accelerate feature monetization timelines.
- Aftermarket Providers:Independent service networks retrofitting connectivity modules to legacy vehicle populations.
- Consumers:Individual vehicle owners receiving updates as embedded warranty provisions or feature-on-demand purchases.
Fleet Operators drive contract innovation. OEMs capture the deepest margin capture.
Deployment:
Deployment architecture selection reflects tradeoffs between cloud scalability and data residency requirements, with European GDPR obligations compelling infrastructure duplication.
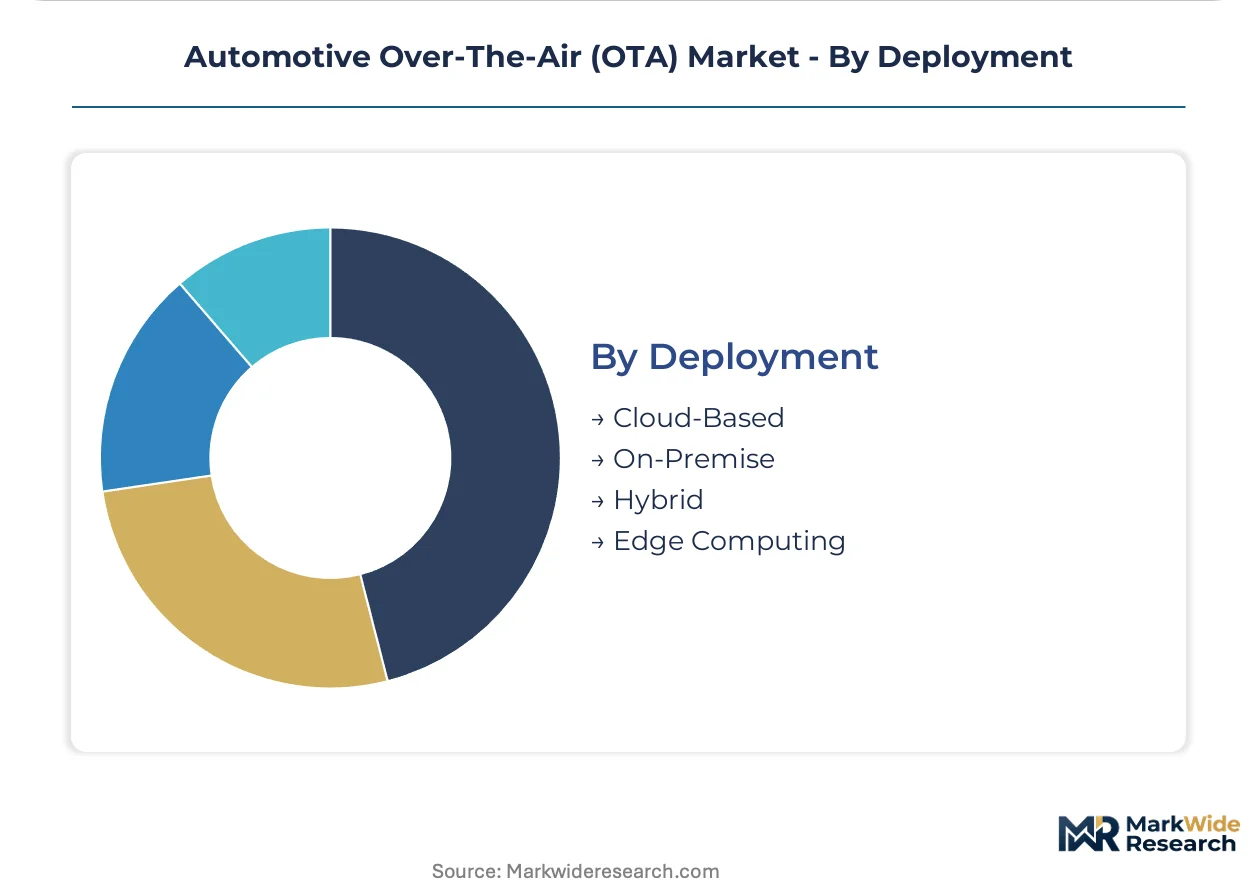
- Cloud-Based:Centralized update orchestration through hyperscaler partnerships enabling elastic capacity for global fleet events. German and French OEMs segregate European instances from global stacks to satisfy EU AI Act algorithmic transparency requirements and GDPR cross-border transfer restrictions, doubling infrastructure expenditure.
- Edge Computing:Localized update nodes reducing latency for commercial vehicle pools and autonomous testing fleets. Mining operations in Western Australia and agricultural cooperatives in Brazil deploy edge architectures to bypass cellular coverage gaps and minimize satellite backhaul costs.
- Hybrid:Architectures balancing cloud coordination with regional edge execution.
- On-Premise:Fully captive infrastructure for defense and government vehicle programs with air-gapped security requirements.
Cloud-Based dominates new deployments. Edge Computing is gaining share fastest in resource extraction and remote logistics segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UN ECE R156 cybersecurity mandates and software-defined vehicle investments are concentrating OTA infrastructure development in Germany, the United States, and China, where connected fleet penetration and regulatory enforcement are deepest.
United States
Fleet operators in Michigan and California negotiate standalone OTA service-level agreements with guaranteed patch windows. NHTSA guidance on cybersecurity best practices shapes validation protocols for safety-critical updates. Detroit's automotive engineering corridor hosts captive software divisions at General Motors and Ford developing proprietary update pipelines.
Germany
Volkswagen Group and BMW maintain end-to-end control over fleet orchestration to preserve data sovereignty under GDPR constraints. KBA type-approval processes enforce UN ECE R156 documentation requirements for cybersecurity management systems. Stuttgart and Munich anchor tier-one supplier clusters where Robert Bosch GmbH and Continental AG integrate gateway hardware with cloud backends.
China
BYD and NIO deploy OTA capabilities across mass-market and premium electric vehicle lineups with compressed feature monetization timelines. MIIT regulations on intelligent connected vehicle data security impose localization requirements on cloud infrastructure. Shenzhen and Shanghai concentrate domestic OTA platform development alongside battery and semiconductor supply chains.
Japan
Denso Corporation and Toyota Motor anchor integrated hardware-software development for hybrid and battery-electric architectures. METI guidelines on automotive cybersecurity management systems align domestic standards with UN ECE frameworks. Nagoya's Chubu region hosts concentrated ECU manufacturing and validation facilities serving Asia-Pacific export markets.
South Korea
Hyundai Motor Group and Kia accelerate OTA deployment across electric vehicle platforms with over-the-air feature activation capabilities. MFDS-aligned cybersecurity frameworks for connected vehicles shape supplier qualification processes. Seoul Capital Area concentrates R&D investment in differential compression and cryptographic verification technologies.
Automotive Over-The-Air (OTA) Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: captive OEM software divisions controlling end-to-end update cycles, diversified tier-one suppliers embedding across multiple vehicle programs, and specialized connectivity pure-plays. Competitive positioning hinges on gateway hardware-software integration depth and regulatory validation speed. Dominant moves include strategic partnerships between semiconductor vendors and cloud hyperscalers, plus geographic expansion of update infrastructure to satisfy data residency mandates.
Within the captive OEM tier, Tesla exemplifies vertical control over fleet update cycles from cloud backend to vehicle gateway. Among diversified tier-one suppliers, Robert Bosch GmbH and Continental AG occupy anchor positions across European and North American OEM programs. HARMAN International represents the specialized connectivity archetype, bridging infotainment domain expertise with broader vehicle network integration.
| Leading Market Players |
|---|
| Tesla |
| Robert Bosch GmbH |
| Continental AG |
| HARMAN International |
| Aptiv PLC |
| NXP Semiconductors |
| Qualcomm Technologies, Inc. |
| Denso Corporation |
| Airbiquity Inc. |
| Others |
Value Chain & Pricing Dynamics
Gateway module manufacturing concentrates in Germany and China, anchoring margin capture downstream with Tier 1 suppliers who bundle hardware with cloud orchestration software and multi-year update service contracts.
Pricing Analysis
Volume-discount tiering structures dominate fleet procurement negotiations, with commercial operators securing per-vehicle rate reductions above 10,000-unit commitments. Pricing stratifies across premium, standard, and economy tiers based on update frequency guarantees and cryptographic certification levels. Cost compression in economy-tier cellular connectivity packages is intensifying because carrier wholesale rates face downward pressure from low-earth orbit satellite alternatives. Fleet operators exhibit highest price sensitivity, while captive OEM software divisions absorb bundled infrastructure costs to accelerate feature monetization timelines.
Supply Chain Analysis
Export-control regimes limiting semiconductor manufacturing equipment flows to China are fragmenting chip sourcing strategies across automotive electronics suppliers. Taiwan, South Korea, and the United States anchor wafer fabrication for vehicle gateway processors, while Malaysia and Vietnam handle backend packaging and testing operations. The supply chain draws from automotive-grade NAND flash memory, cellular baseband modems, and hardware security modules as critical inputs. Single-source vulnerability in advanced node semiconductor fabrication creates concentration risk. Distribution runs through Tier 1 supplier direct programs to OEM platform engineering teams, bypassing traditional aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OTA infrastructure sits in early-cycle expansion as UN ECE R156 mandates force laggard OEMs to retrofit cybersecurity management systems across vehicle lineups previously sold without validated update capabilities.
For Market Incumbents: Pre-empt feature-on-demand revenue erosion by locking fleet operators into multi-year update service agreements before satellite-to-vehicle direct link providers achieve commercial scale. Acquire differential compression algorithm specialists to defend margin position against cloud hyperscalers entering automotive verticals. Deepen gateway hardware-software integration to raise switching costs for OEMs evaluating supplier consolidation.
For New Entrants and Emerging Players: Build out localized OTA infrastructure partnerships with domestic OEMs in India and Southeast Asia, where connected-vehicle penetration remains below 15 percent of production volume despite accelerating electric vehicle adoption. Target agricultural equipment and mining truck segments in Brazil and Western Australia, where cellular coverage gaps create immediate demand for satellite-to-vehicle update delivery. Lead with edge computing architectures that minimize satellite backhaul costs as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive connectivity pure-plays that consolidated infotainment domain expertise but lack powertrain and chassis network integration capabilities. The 5-to-10-year viability window favors platforms with validated UN ECE R156 cybersecurity management system documentation already embedded in European type-approval processes. Watch for Tier 1 suppliers divesting non-core telematics divisions as the signal for acquisition timing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Volkswagen Group and General Motors accelerate proprietary update pipeline development to preserve data sovereignty under GDPR constraints. |
| Platform Standardization | Robert Bosch GmbH and Continental AG push unified gateway architectures across multiple OEM programs to amortize validation costs. |
| Battery Supply Agreement | Cellular module suppliers secure long-term capacity commitments from semiconductor foundries in Taiwan and South Korea. |
| Geographic Manufacturing Footprint | BYD and NIO localize cloud infrastructure in Shenzhen and Shanghai to satisfy MIIT data security regulations. |
| Charging Infrastructure Partnership | Fleet operators in Michigan negotiate guaranteed patch delivery windows tied to vehicle charging downtime schedules. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with automotive cybersecurity officers, OEM platform engineers, Tier 1 supplier procurement leads, and fleet operations directors; and secondary validation against vehicle production databases, UN ECE R156 type-approval filings, IHS Markit registration data, and carrier infrastructure deployment disclosures. Bottom-up triangulation of update-enabled vehicle shipments by connectivity pathway and region converged with top-down market sizing derived from software-defined vehicle investment announcements and regulatory mandate implementation timelines.
Forecast inputs span technology adoption curves across cellular, satellite, and edge computing pathways; application segmentation across safety, infotainment, and vehicle control domains; and end-user archetypes from fleet operators to captive OEM divisions. CAGRs were derived from logistic diffusion models fitted to historical connected-vehicle penetration rates, adjusted for regulatory compliance deadlines and differential compression algorithm maturation. Content-per-vehicle trajectories for gateway modules and cloud orchestration software license intensity served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by low-earth orbit satellite constellation operators or cloud hyperscalers entering automotive verticals would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Latin America Automotive Camera Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
Automotive Secondary Wiring Harness Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
In-Car Gaming System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market