
 Europe Automotive Smart Keys Market | 2026-2036
Europe Automotive Smart Keys Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Smart Keys Market Foresight
The EU Green Deal is hardening emission reduction mandates across European automotive supply chains, pushing OEMs to bundle smart key systems with EV-native electronics architectures. Continental AG leverages its integrated body electronics portfolio to anchor keyless entry contracts with German premium manufacturers. Robert Bosch GmbH competes through its semiconductor and sensor divisions, sustaining R&D intensity in ultra-wideband positioning for centimeter-level key localization. Valeo SA specializes in software-defined access modules, differentiating its offerings through over-the-air update capabilities that extend product lifecycles beyond hardware replacement cycles.
Europe automotive smart keys are electronic access and authorization devices that replace mechanical ignition systems through encrypted radio-frequency communication, typically operating at 315 MHz or 433 MHz with AES-128 encryption protocols and immobilizer transponder integration. Their primary commercial purpose is to eliminate physical key insertion while enabling passive entry, push-button start, and biometric driver authentication across passenger and commercial vehicle platforms. The technology segment shows key fob configurations still occupying the dominant volume share, though mobile app-based access is registering the fastest expansion as smartphone-native digital key standards from the Car Connectivity Consortium penetrate OEM lineups. By feature, keyless entry systems retain the broadest installed base, while security system integration captures margin concentration through subscription-enabled stolen vehicle tracking and geofencing services.
The European Automobile Manufacturers Association coordinates with ECHA under REACH to restrict hazardous substances in printed circuit assemblies, while CE marking mandates electromagnetic compatibility testing for all radio-transmitting key devices sold across EU member states. Germany's KBA enforces type approval for immobilizer and alarm system interoperability, directly shaping product development roadmaps for suppliers seeking homologation on domestic production lines. Stakeholders must monitor how the EU AI Act categorizes biometric authentication algorithms in smart keys, as pending compliance requirements could force architecture redesigns before the next platform cycle locks.
Market Dynamics
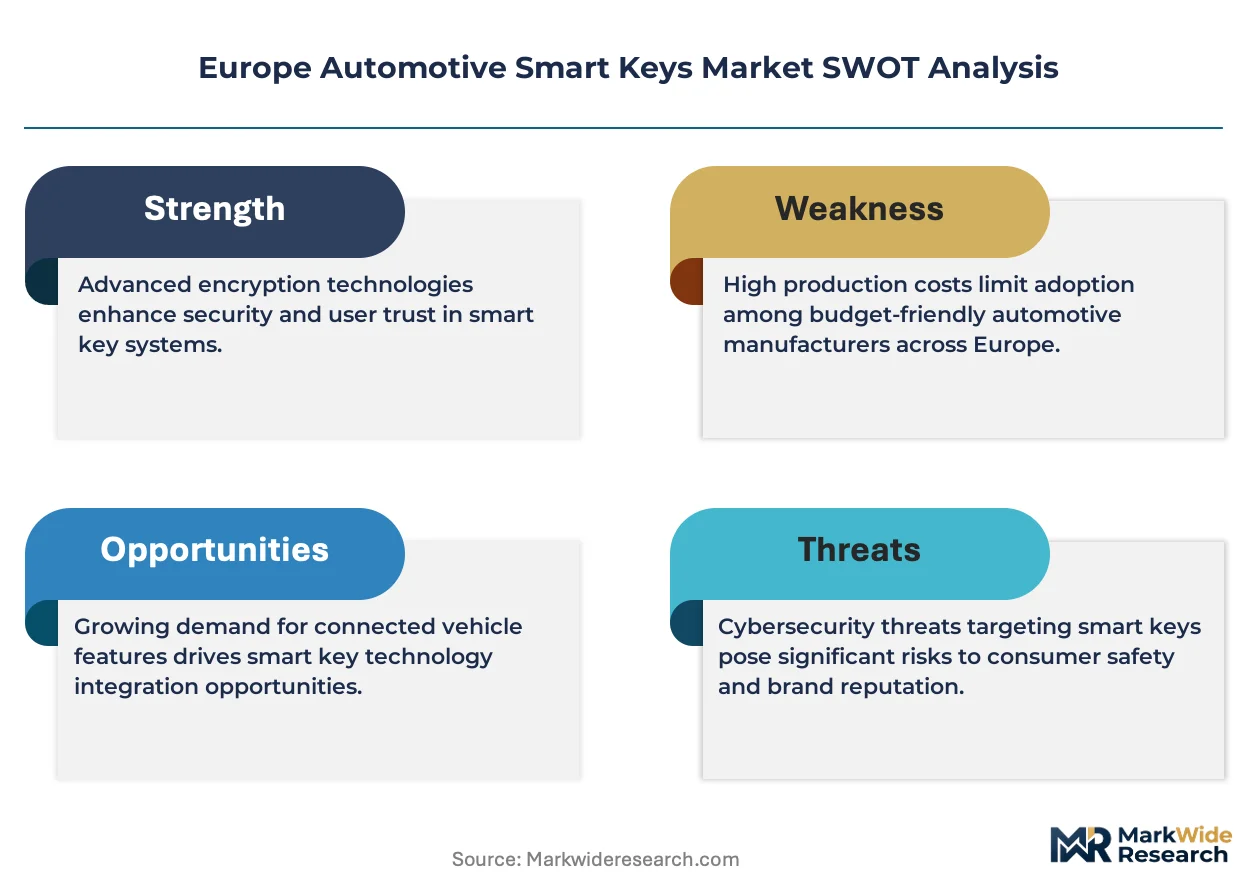
EU Green Deal mandates are compressing vehicle electrification timelines, forcing smart key architectures to migrate toward EV-native electronics platforms that demand higher encryption standards and over-the-air update capabilities.
Growth Catalysts
- EU AI Act compliance pressure:Pending biometric authentication requirements are accelerating R&D investment in facial-recognition-enabled access systems before the next platform cycle locks.
- German premium OEM expansion:Bavaria-based manufacturers are bundling keyless entry with connected vehicle subscriptions, creating captive demand for software-defined access modules.
- Ultra-wideband positioning:Centimeter-level key localization is displacing legacy RF protocols in high-theft-risk urban markets across France and the United Kingdom.
Market Restraints
- Semiconductor input volatility:AES-128 encryption chip supply concentrates with Taiwanese foundries, exposing European module assemblers to geopolitical supply shocks.
- REACH substance restrictions:ECHA limitations on hazardous materials in printed circuit assemblies are forcing redesigns of immobilizer transponder housings.
- Mobile device substitution:Smartphone-native digital keys from the Car Connectivity Consortium threaten to compress key fob volume share within premium segments.
Strategic Opportunities
- Eastern European fleet electrification:Poland and Czechia commercial vehicle operators remain underpenetrated by connected access systems, offering first-mover positioning.
- Subscription-enabled security services:Stolen vehicle tracking and geofencing create recurring revenue streams beyond hardware replacement cycles.
- CE marking harmonization:Electromagnetic compatibility testing standardization across EU member states reduces fragmentation costs for cross-border suppliers.
Industry Challenges
- Firmware-over-the-air talent scarcity:Embedded software engineers with automotive cybersecurity credentials command premium wages in Stuttgart and Munich labor markets.
- Homologation timeline compression:Germany's KBA type approval for immobilizer interoperability extends development cycles by 8-14 months for new platform integrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Smart Keys Market |
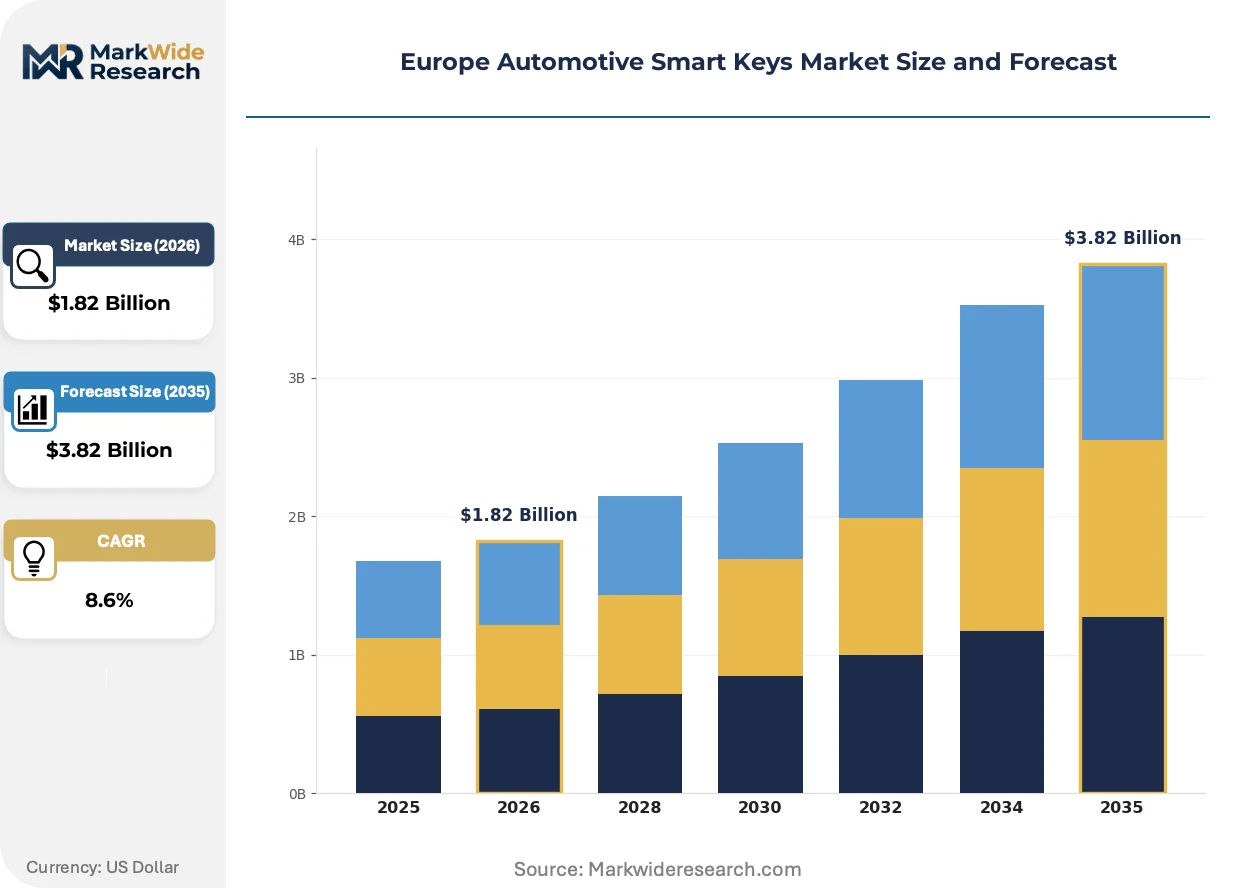
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Key Fob, Mobile App, Biometric, RFID End User: OEMs, Aftermarket Providers, Vehicle Owners, Fleet Managers Feature: Keyless Entry, Remote Start, Security System, Tracking System Form: Remote, Integrated, Smart Card, Wearable |
| Companies Covered | Continental AG, ZF Friedrichshafen AG, Denso Corporation, Alpha Corporation, Robert Bosch GmbH, Huf Hulsbeck & Furst GmbH & Co. KG, HELLA GmbH & Co. KGaA, Valeo SA, Hyundai Mobis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Smart Keys Market Shifts & Advancements
Software-defined vehicle architectures are dissolving the boundary between access hardware and digital identity management, repositioning smart keys as edge computing nodes within broader mobility ecosystems.
Ultra-wideband ranging technology is electrifying passive entry systems by enabling precise spatial awareness between key fobs and vehicle receivers. German luxury manufacturers are adopting this standard across 2026 model year lineups to eliminate relay attack vulnerabilities. The shift is compressing demand for legacy 315 MHz RF transponders while elevating semiconductor content per unit.
REACH compliance deadlines under ECHA oversight are forcing material substitutions in printed circuit assembly substrates. Suppliers must validate halogen-free flame retardants without compromising signal integrity for encrypted immobilizer communication. French module integrators face the steepest reformulation costs due to earlier national implementation of substance restrictions.
Fleet operators in the United Kingdom are unbundling after-sales access management from vehicle procurement contracts. Third-party mobility service providers now negotiate direct software licenses for digital key provisioning, bypassing traditional OEM captive finance structures. This disintermediation is most visible in London-based corporate car-sharing programs where smartphone authentication has displaced physical fob distribution.
Europe Automotive Smart Keys Market Segmentation
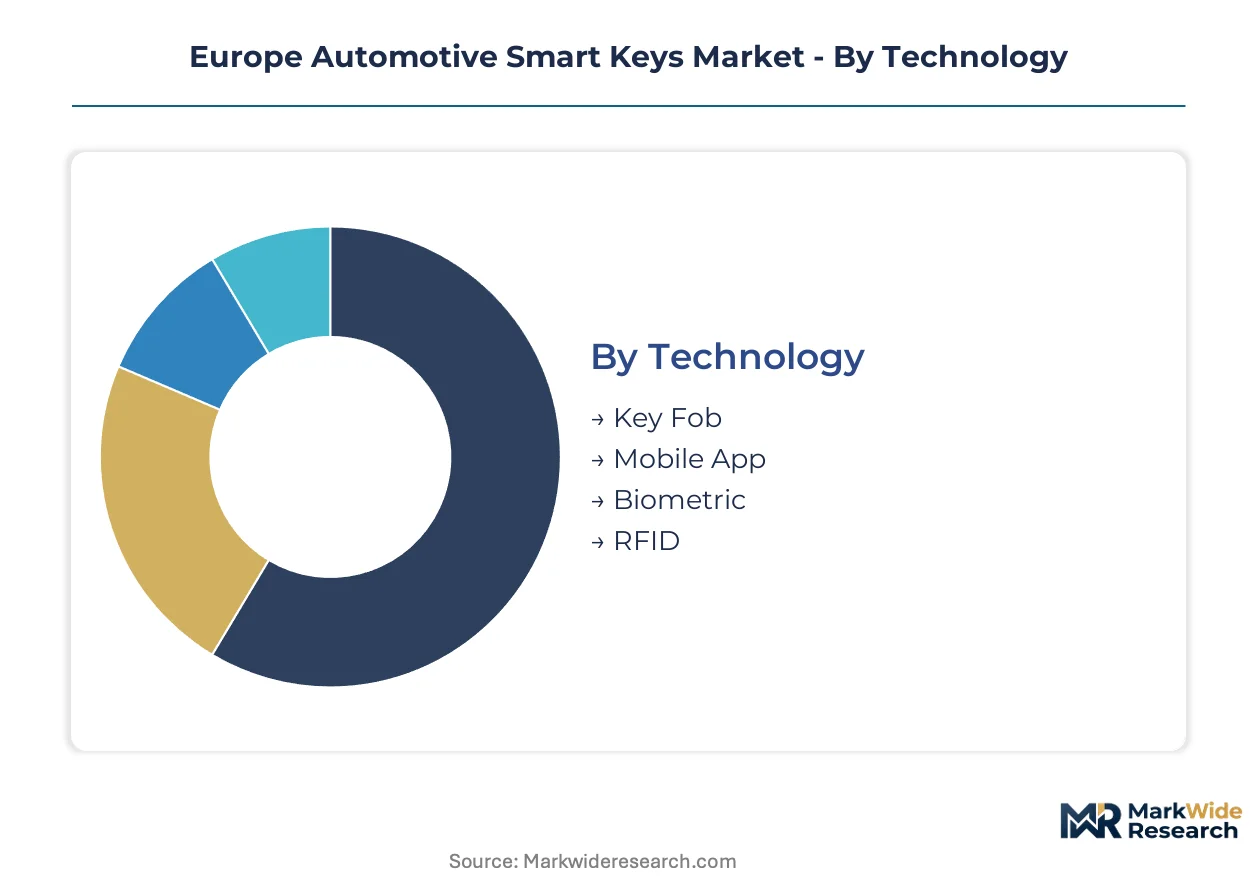
Smart key architectures in Europe fragment across four distinct dimensions that determine integration complexity and value capture. Technology choices dictate semiconductor content and encryption requirements. End-user structures reveal where purchasing power concentrates versus where margin compression threatens.
Technology:
Standalone fob-based systems dominate installed base, while embedded smartphone and biometric platforms reshape R&D allocation.
- Key Fob:Dedicated hardware devices operating at 315 MHz or 433 MHz with AES-128 encryption and immobilizer transponder integration. German premium OEMs in Bavaria and Baden-Württemberg sustain volume concentration through bundled connected vehicle subscriptions, though Taiwan-sourced encryption chip exposure creates supply vulnerability.
- Mobile App:Smartphone-native digital keys leveraging Car Connectivity Consortium standards for Bluetooth Low Energy and ultra-wideband communication. Fleet operators in London corporate car-sharing programs are disintermediating OEM captive finance structures through direct software licensing, compressing physical fob demand in premium segments.
- Biometric:Facial recognition and fingerprint authentication modules requiring EU AI Act compliance architecture. Pending biometric algorithm categorization under the regulation is forcing pre-platform-cycle redesigns.
- RFID:Passive radio-frequency identification tags for basic entry authorization with lower encryption overhead. Eastern European commercial fleets in Poland and Czechia represent underpenetrated demand for cost-optimized configurations.
Key fob configurations lead volumes today; mobile app access is gaining share fastest.
End User:
Procurement authority splits between vehicle-build-phase integration and post-sale service channels.
- OEMs:Original equipment manufacturers specifying smart key modules during platform development. German KBA type approval requirements for immobilizer interoperability extend German premium manufacturer development cycles by 8-14 months.
- Aftermarket Providers:Independent distributors and installers serving vehicle replacement and upgrade demand. REACH substance restrictions on printed circuit assemblies force reformulation of transponder housings across French module integrators.
- Vehicle Owners:Individual consumers purchasing replacement keys or upgrade accessories. United Kingdom urban markets with high theft risk drive ultra-wideband localization adoption for relay attack protection.
- Fleet Managers:Commercial operators managing access across multiple vehicles and drivers. Poland and Czechia commercial vehicle electrification programs remain underpenetrated by connected access systems.
OEMs command the largest contract values; fleet managers are expanding procurement fastest.
Feature:
Functional bundles determine recurring revenue potential beyond hardware shipment.
- Keyless Entry:Passive authorization systems eliminating physical key insertion. French and United Kingdom markets with deepest connected vehicle penetration anchor installed base concentration.
- Remote Start:Engine activation from outside vehicle cabin. Cold-climate Nordic markets sustain seasonal demand spikes.
- Security System:Immobilizer and alarm integration with stolen vehicle tracking capability. Subscription-enabled geofencing services create recurring revenue streams extending product lifecycles.
- Tracking System:Real-time location monitoring for asset recovery. Fleet operators unbundle after-sales access management from procurement contracts.
Keyless entry retains broadest installed base; security system integration captures margin concentration.
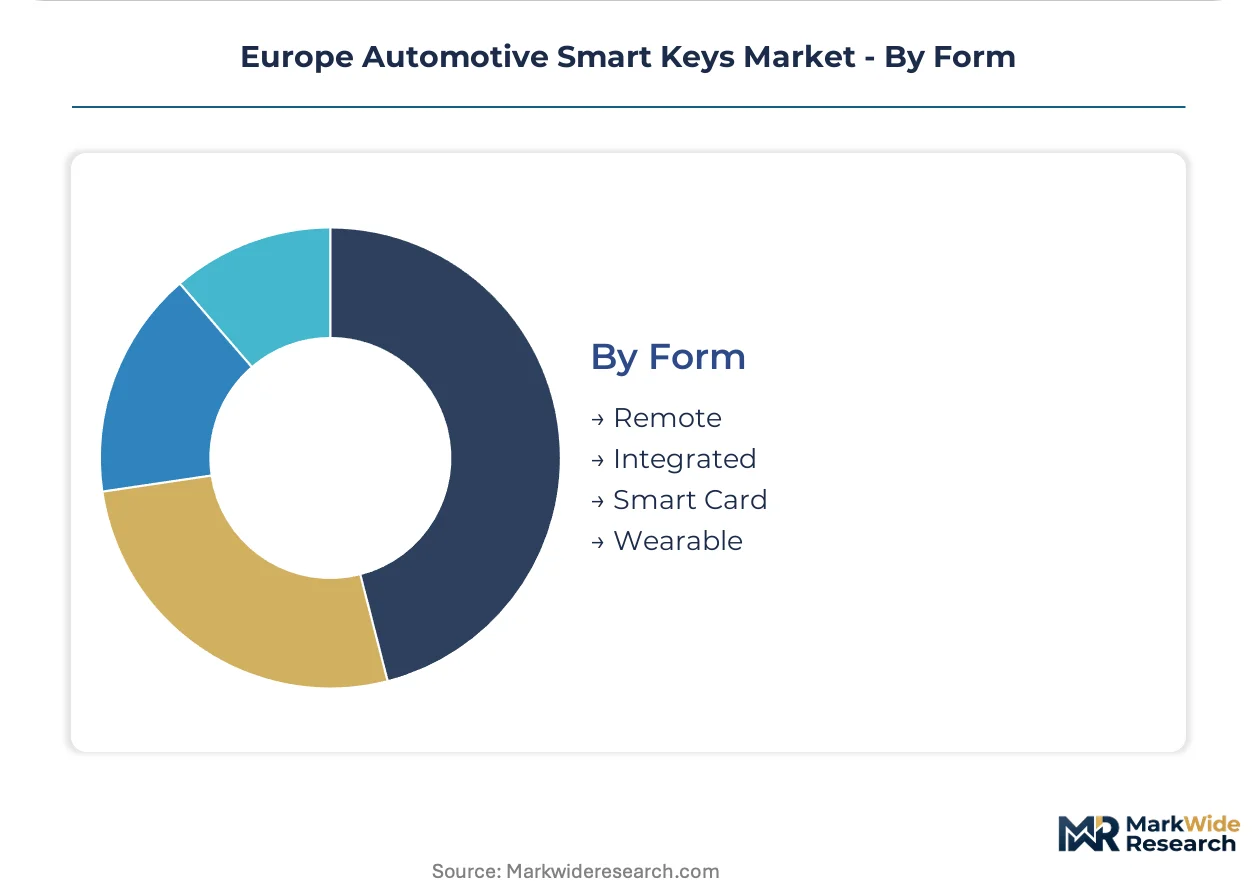
Form:
Physical packaging choices reflect ergonomics, durability, and brand differentiation requirements.
- Remote:Handheld transmitters with discrete buttons for lock, unlock, and auxiliary functions. Legacy 315 MHz RF transponder demand compresses as ultra-wideband displaces protocols.
- Integrated:Key blades fused with electronic transponder for mechanical backup. German premium manufacturers balance electronic convenience with regulatory mechanical override mandates.
- Smart Card:Credit-card-format credentials for wallet storage. Urban car-sharing programs in Paris and London favor slim form factors.
- Wearable:Wristband or keychain-integrated devices for active lifestyle positioning. Niche positioning in athletic and outdoor vehicle segments.
Remote form factors dominate production; smart card configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering heritage established automotive smart key standards through Bavarian premium OEM platform development, spreading manufacturing expertise across Rhine-Ruhr and Stuttgart industrial corridors before continental adoption.
Germany
Bavarian premium manufacturers bundle keyless entry with connected vehicle subscriptions, creating captive demand for software-defined access modules. Germany's KBA enforces type approval for immobilizer interoperability, extending development cycles by 8-14 months. Stuttgart and Munich labor markets face acute scarcity of embedded software engineers with automotive cybersecurity credentials.
France
Paris-based luxury OEMs drive ultra-wideband localization adoption for relay attack protection in high-theft-risk urban environments. ECHA REACH deadlines force halogen-free flame retardant validation in printed circuit assemblies without signal integrity compromise. Module integrators in Île-de-France absorb steepest reformulation costs from earlier national substance restriction implementation.
United Kingdom
London corporate car-sharing programs disintermediate OEM captive finance through direct software licensing for smartphone-native digital keys. Fleet operators unbundle after-sales access management from procurement contracts, compressing physical fob demand. Birmingham and Manchester manufacturing clusters adapt to CE marking harmonization for electromagnetic compatibility testing standardization.
Poland
Commercial vehicle electrification programs in Warsaw and Kraków metropolitan areas remain underpenetrated by connected access systems. EU Green Deal vehicle electrification timelines create first-mover positioning for cost-optimized RFID configurations. Silesian industrial zones attract module assembly investment serving Eastern European fleet operators.
Czechia
Prague and Brno automotive supplier ecosystems support German OEM platform integration with lower labor cost structures. CE marking mandates for radio-transmitting devices align national regulatory frameworks with EU-wide electromagnetic compatibility requirements. Moravian manufacturing corridors specialize in immobilizer transponder housing production for premium segment supply.
Europe Automotive Smart Keys Market Competitive Landscape
Capital-heavy semiconductor foundries compete with asset-light module designers for smart key contract allocation, creating tiered supply structures. The vendor base stratifies between integrated Tier 1 automotive suppliers, specialized access technology developers, and electronics manufacturing service providers. Three archetypes dominate: diversified automotive electronics conglomerates, dedicated security module specialists, and Asian component scale players. Competitive moves concentrate on firmware-over-the-air capability acquisition and ultra-wideband patent licensing.
Within the diversified conglomerate tier, Continental AG and Robert Bosch GmbH anchor German premium OEM relationships through integrated body electronics portfolios. Valeo SA occupies a position among French specialists leveraging software-defined access architectures with over-the-air update capabilities. Denso Corporation represents Asian scale-driven supply to European transplant manufacturing facilities.
| Leading Market Players |
|---|
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Alpha Corporation |
| Robert Bosch GmbH |
| Huf Hulsbeck & Furst GmbH & Co. KG |
| HELLA GmbH & Co. KGaA |
| Valeo SA |
| Hyundai Mobis |
| Others |
Supply & Pricing Matrix
Silicon wafer spot indices from Taiwanese foundries cascade through European module assemblers into three distinct pricing tiers for AES-128 encryption chips, compressing margins at the standard tier while premium ultra-wideband configurations retain pricing power through German OEM bundling strategies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates European smart key procurement, with differentiation anchored in encryption certification grade and after-sales service bundling rather than hardware alone. Cost compression in standard-tier key fobs is intensifying because Taiwanese foundry concentration exposes module assemblers to input volatility. Fleet managers in Poland and Czechia exhibit the highest price sensitivity, while Bavarian premium OEMs accept premium tier pricing for software-defined access modules with over-the-air capabilities.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and French premium manufacturers, while aftermarket distributors serve fragmented replacement demand across Eastern European markets. Semiconductor inputs draw from Taiwan, South Korea, and Japan, with AES-128 encryption chips and ultra-wideband transceivers representing critical dependencies. Single-source vulnerability in Taiwanese foundry supply creates structural risk for European module integrators facing KBA homologation timelines. Distribution runs through Tier 1 automotive electronics suppliers with captive relationships to Stuttgart and Munich engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act biometric authentication mandate compounds demand for compliant smart key architectures, creating regulatory-driven upgrade cycles before platform lock-in. This regulatory compounding accelerates R&D investment timelines across supplier tiers.
For Market Incumbents: To counter mobile app substitution from Car Connectivity Consortium standards, Continental AG and Robert Bosch GmbH should deepen firmware-over-the-air capability acquisition and anchor ultra-wideband patent licensing. Securing embedded software engineering talent in Stuttgart and Munich labor markets provides defensive moat against subscription-enabled security service competitors.
For New Entrants and Emerging Players: Capture underpenetrated Eastern European commercial fleet demand in Poland and Czechia through cost-optimized RFID configurations with EU Green Deal electrification alignment. Direct software licensing to London-based corporate car-sharing programs bypasses OEM captive finance structures and establishes beachhead in fastest-growing mobile app segment.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized access technology developers holding ultra-wideband patent portfolios and software-defined vehicle architecture expertise. Five-to-ten year viability hinges on firmware-over-the-air talent density and REACH compliance infrastructure. Monitor ECHA substance restriction implementation timelines as inflection indicator for module integrator consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-wideband Patent Licensing | Centimeter-level key localization eliminates relay attack vulnerabilities in German luxury lineups. |
| Firmware-over-the-air Capability Acquisition | Software-defined access modules extend product lifecycles beyond hardware replacement cycles. |
| Eastern European Fleet Partnership | Poland and Czechia commercial electrification programs remain underpenetrated by connected systems. |
| REACH Compliance Infrastructure Investment | Halogen-free flame retardant validation secures ECHA substance restriction continuity. |
| Embedded Cybersecurity Talent Recruitment | Automotive cybersecurity credentials command premium wages in Stuttgart and Munich markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operations managers with secondary validation against vehicle production databases, IHS Markit registration data, KBA type approval filings, and ECHA REACH substance restriction updates. Bottom-up module shipment estimates triangulated against top-down OEM platform content analysis.
Historical reference periods anchored the projection horizon to established electrification timelines and regulatory compliance deadlines, with segmentation modeling across technology type, end-user procurement authority, feature bundle, and vehicle propulsion architecture. CAGRs derived from encrypted communication protocol adoption curves and connected vehicle penetration patterns across EU member states, incorporating semiconductor input cost trajectories and labor market scarcity indicators.
Geopolitical supply shocks, ECHA substance restriction acceleration, and EU AI Act biometric algorithm categorization are the dominant revision risks to forecast outputs. Forecasts reflect assumptions about Taiwanese foundry capacity allocation and German premium OEM platform cycle timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Navigation System Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive Connectivity Control Unit Market
Automotive Electronics & Wiring
Automotive Smart Antenna Market
Automotive Electronics & Wiring
Automotive Fuse Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
Automotive Human Interface System Market