
 Automotive Radiator Water Temperature Sensor Market | 2026-2036
Automotive Radiator Water Temperature Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Radiator Water Temperature Sensor Market Insights
Modular sensor packaging is hardening as the dominant configuration pattern, with tier-1 suppliers bundling temperature, pressure, and flow sensors into single thermal management modules. Robert Bosch GmbH leverages its integrated electronics portfolio to anchor multi-sensor contracts with European OEMs. Denso Corporation sustains manufacturing scale advantages across Asian vehicle assembly corridors. Sensata Technologies Inc. differentiates through high-temperature material specialization for commercial vehicle applications.
An automotive radiator water temperature sensor measures coolant thermal state using NTC thermistor or resistance temperature detector elements, converting temperature variation into electrical signals for engine control unit processing. Its primary purpose is preventing thermal damage, optimizing combustion efficiency, and enabling cold-start emission reduction across internal combustion and hybrid powertrains. Electronic sensors lead product type segmentation due to precision requirements in turbocharged and downsized engines, while NTC thermistor technology occupies the fastest-growing technology tier driven by electric vehicle thermal loop expansion. OEM end users dominate volume offtake, though aftermarket providers compete on replacement cycle acceleration in aging vehicle parcs.
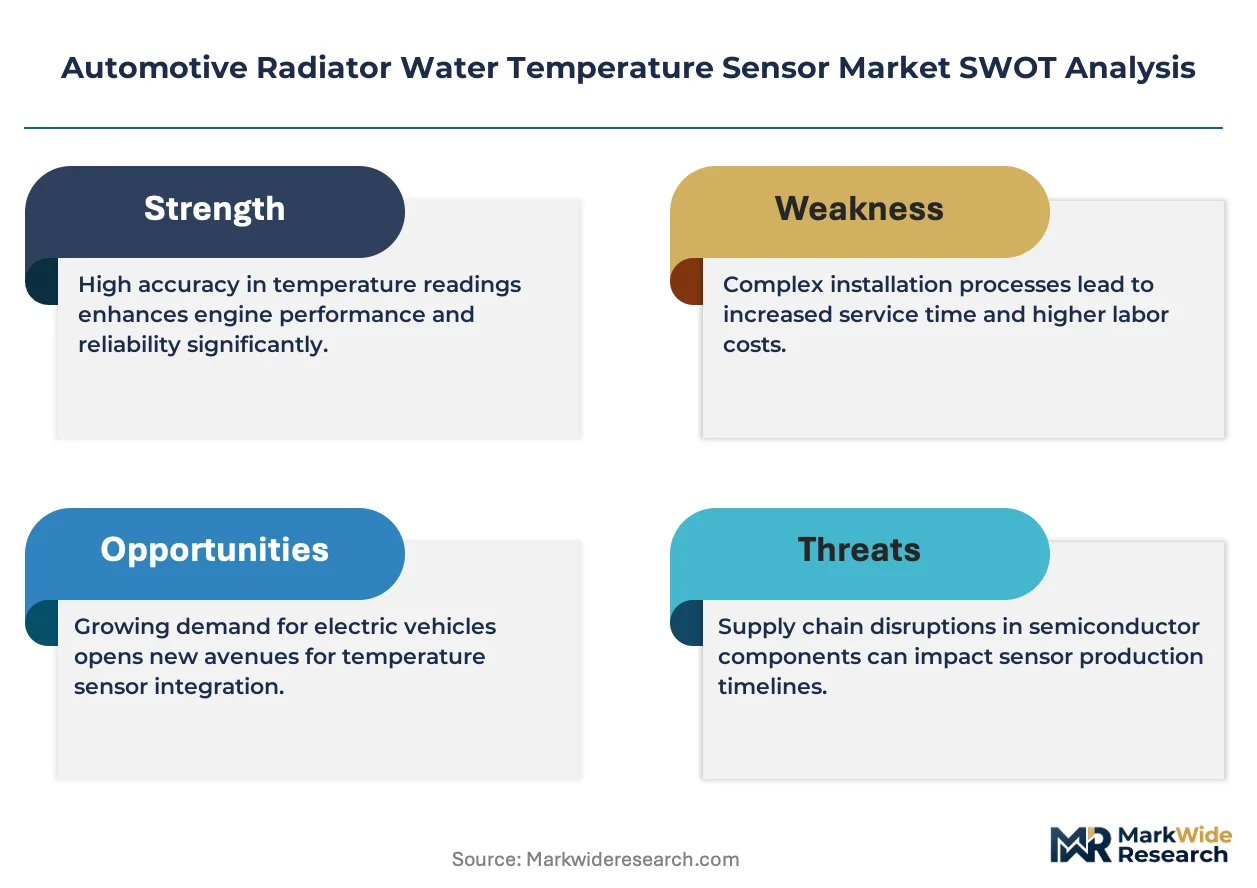
NHTSA safety standards and EPA emission regulations in the United States, plus EU Green Deal thermal efficiency mandates enforced by ECHA REACH compliance, shape sensor accuracy thresholds and material composition requirements. China's MIIT enforces GB standards for new energy vehicle thermal management, creating parallel certification demands for suppliers serving domestic EV manufacturers. Stakeholders must monitor regulatory divergence between combustion-engine legacy rules and emerging electric vehicle thermal protocols when allocating R&D budgets and qualification timelines.
Market Dynamics
Modular thermal management architectures are compressing discrete component procurement cycles as OEMs consolidate multi-sensor sourcing into single module awards, forcing suppliers to requalify entire subsystems rather than individual temperature sensing elements.
Growth Catalysts
- EPA Tier 4 emissions enforcement:Commercial vehicle operators in the United States face mandatory thermal monitoring upgrades to maintain compliance certification, expanding replacement sensor demand across aging heavy-duty fleets.
- NTC thermistor precision gains:Material science advances in ceramic-metal oxide formulations enable tighter temperature resolution for turbocharged downsized engines, satisfying powertrain calibration requirements.
- China NEV thermal loop expansion:Battery electric and hybrid architectures require redundant coolant monitoring for power electronics and cabin conditioning, doubling sensor count per vehicle platform.
Market Restraints
- Platinum-group metal cost volatility:Resistance temperature detector elements depend on platinum thin-film deposition, exposing sensor margins to precious metal commodity swings.
- Asian supply concentration:Ceramic substrate and thermistor bead manufacturing clusters in East Asia create geographic vulnerability for European and North American module assemblers.
- Silicon-based temperature sensing substitution:Integrated circuit temperature monitors embedded in power modules threaten discrete sensor attachment points in next-generation thermal architectures.
Strategic Opportunities
- India commercial vehicle thermal retrofit:BS-VI emission enforcement creates aftermarket sensor replacement demand across truck and bus parcs lacking factory-installed precision monitoring.
- Wireless sensor mesh integration:Bluetooth Low Energy and UWB protocols eliminate harness connector points, reducing assembly labor and warranty leak liability for OEM thermal module suppliers.
- EU Green Deal thermal efficiency mandates:Ecodesign regulations for vehicle climate systems reward suppliers offering combined temperature-pressure-flow sensing with embedded diagnostic algorithms.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-rated sensor designs require 18-24 month validation cycles, compressing product refresh windows against platform launch schedules.
- Legacy harness integration complexity:New digital output sensors must maintain analog signal compatibility with decade-old engine control units, constraining protocol architecture choices.
- Calibration technician scarcity:Precision thermistor characterization demands specialized metrology expertise increasingly concentrated at tier-1 suppliers rather than distributed aftermarket service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Radiator Water Temperature Sensor Market |
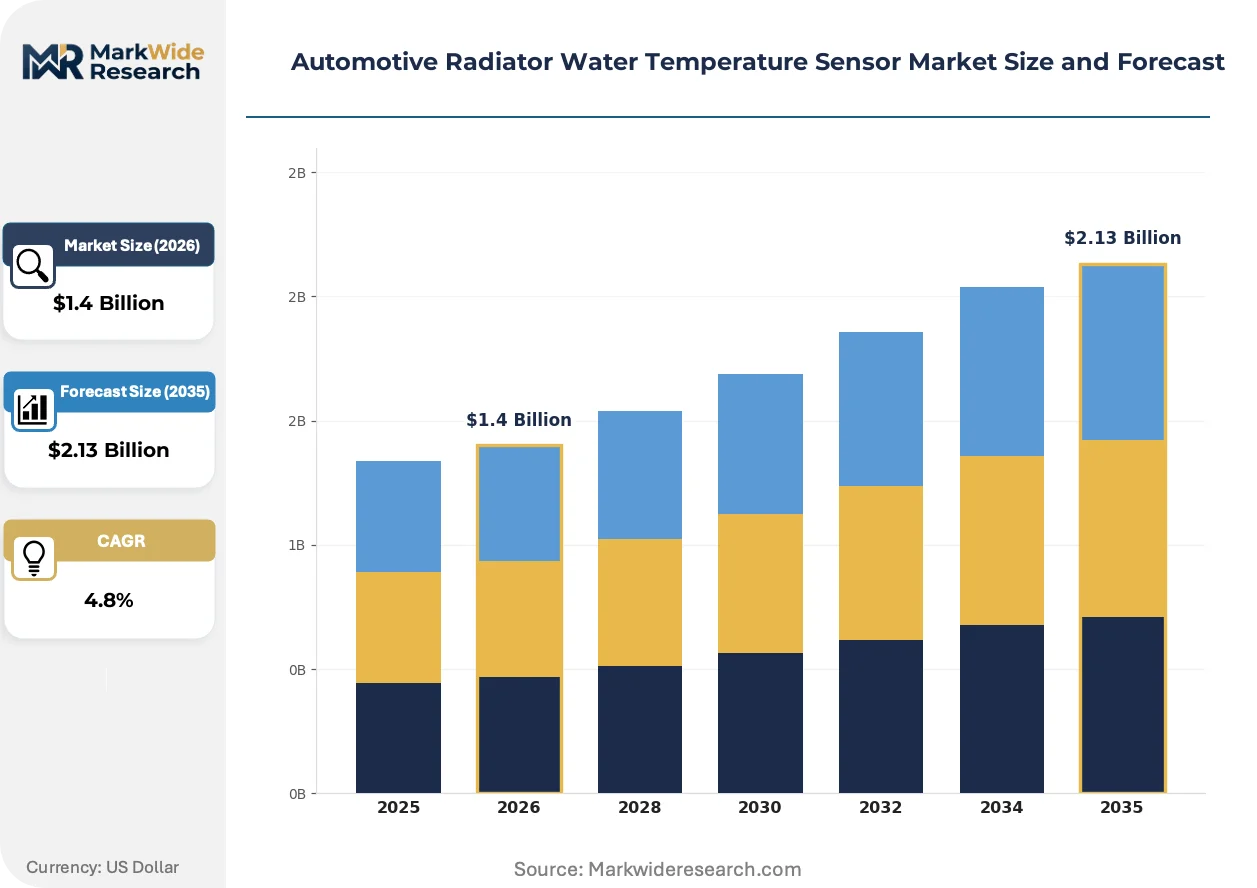
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Sensors, Electronic Sensors, Infrared Sensors, Capacitance Sensors Technology: Resistance Temperature Detectors, Thermocouples, Bimetallic Sensors, NTC Thermistors End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Heavy-Duty Trucks |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Panasonic Corporation, NXP Semiconductors N.V., Sensata Technologies Inc., Continental AG, Mitsubishi Electric, Aptiv, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Radiator Water Temperature Sensor Market Trends and Innovations
Digital output protocols and embedded diagnostics are displacing analog voltage signaling across temperature sensor architectures, enabling predictive maintenance integration and reducing harness complexity in densely packaged engine compartments.
Multi-sensor fusion modules is overtaking discrete temperature-only components in premium thermal management contracts. These integrated packages combine coolant temperature, pressure, and flow rate sensing within a single housing with shared electronics and connector. European OEM powertrain divisions are specifying fused modules for new hybrid platforms launching through 2027. The technology is overtaking standalone sensor procurement by collapsing three discrete part numbers into one qualified assembly, compressing supplier count and simplifying vehicle-level BOM management.
ECHA REACH substance restrictions on cadmium and lead in electronic components are forcing ceramic formulation changes across NTC thermistor manufacturing. Suppliers must revalidate temperature coefficient curves and long-term drift characteristics using alternative dopant chemistries. Commercial vehicle sensor providers serving European export markets face the steepest reformulation burden, as their products typically operate in higher-temperature regimes where traditional heavy-metal stabilizers performed critical structural functions.
Fleet operators are consolidating thermal sensor procurement through vehicle-as-a-service providers rather than fragmented aftermarket channels. Leasing and full-service maintenance contracts bundle component replacement under fixed-rate agreements, shifting volume concentration toward tier-1 direct supply relationships. North American heavy-duty trucking corridors show this pattern most visibly, where mega-fleets operating thousands of units negotiate enterprise pricing with sensor module manufacturers for standardized across-brand thermal monitoring upgrades.
Automotive Radiator Water Temperature Sensor Market Segmentation
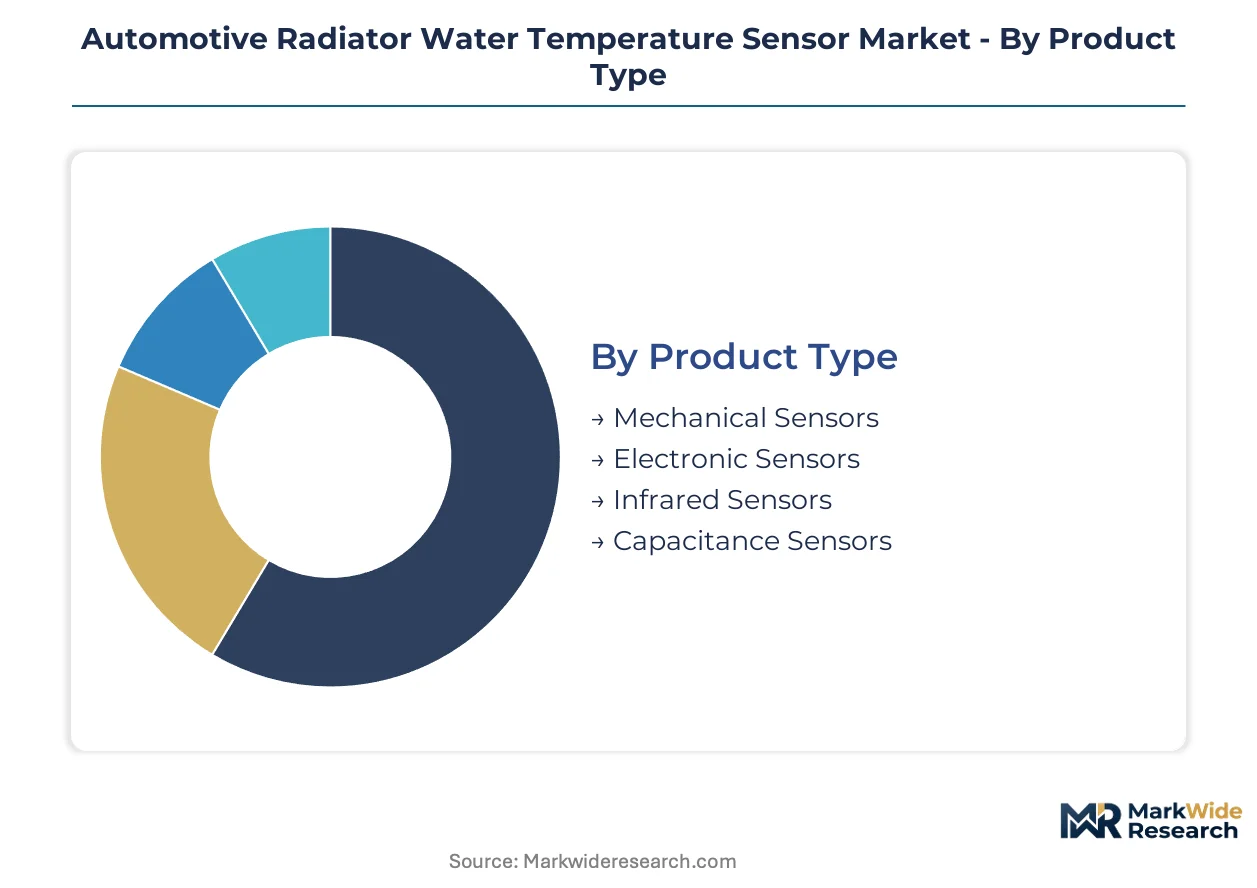
Automotive radiator water temperature sensors fragment across sensing physics, integration depth, and thermal regime requirements. Procurement patterns diverge sharply between legacy internal combustion platforms and emerging electric vehicle architectures, forcing suppliers to maintain parallel qualification tracks.
Product Type:
Standardization dominates mechanical and infrared formats, while electronic sensors command premium customization for engine-specific calibration curves.
- Mechanical Sensors:Bimetallic strip or liquid-expansion elements trigger cooling fan engagement through direct mechanical linkage. Demand concentrates in emerging market commercial fleets where electronic control unit penetration remains incomplete, constrained by durability limitations in vibration-intensive heavy-duty applications.
- Electronic Sensors:Semiconductor-based transduction enables millisecond-response digital output compatible with modern powertrain control modules. OEM procurement for turbocharged gasoline direct injection engines drives volume, as precise thermal mapping prevents knock and enables lean combustion calibration.
- Infrared Sensors:Non-contact thermal radiation measurement suits exhaust-aftertreatment monitoring where coolant contamination risks exist.
- Capacitance Sensors:Dielectric property variation enables combined temperature-fluid level sensing in integrated reservoir modules.
Leading the category by volume: Electronic Sensors. Growing fastest: Infrared Sensors.
Technology:
Cost tiers separate precious-metal precision from ceramic-based economy solutions, with thermocouples occupying the mid-range for extreme-temperature resilience.
- Resistance Temperature Detectors:Platinum thin-film elements deliver linear resistance-temperature correlation across -200°C to 850°C. European commercial vehicle manufacturers specify RTDs for exhaust gas recirculation cooler monitoring, though platinum price volatility constrains margin stability.
- Thermocouples:Dissimilar metal junctions generate thermoelectric voltage proportional to temperature differential. Foundry and casting transport applications in Germany favor Type K thermocouples for molten metal proximity sensing where standard coolant sensors fail.
- Bimetallic Sensors:Differential thermal expansion drives mechanical switching without electrical excitation.
- NTC Thermistors:Negative temperature coefficient ceramic oxides exhibit exponential resistance decay with warming.
Highest precision: Resistance Temperature Detectors. Steepest expansion trajectory: NTC Thermistors.
End User:
Volume concentration sits with direct OEM supply, while aftermarket channels fragment across service network density and vehicle parc age distribution.
- OEMs:Original equipment manufacturers specify sensor performance envelopes during platform development, locking in multi-year supply agreements. Ford, Toyota, and Volkswagen thermal system engineering groups in Michigan, Aichi, and Wolfsburg respectively drive specification evolution toward multi-sensor fusion modules.
- Aftermarket Providers:Independent distributors and service chains target replacement cycles in aging vehicle populations. NAPA Auto Parts and O'Reilly Automotive in the United States consolidate procurement for domestic pickup truck cooling system maintenance.
- Vehicle Assemblers:Contract manufacturers without captive sensor design capability rely on tier-1 module integration.
- Tier-1 Suppliers:Thermal management specialists bundle sensing with pumps, valves, and heat exchangers.
Dominant procurement volume: OEMs. Fastest channel expansion: Aftermarket Providers.
Application:
Thermal regime severity and regulatory exposure separate passenger vehicle commodity supply from commercial vehicle premium positioning.
- Passenger Vehicles:Downsized turbocharged engines demand rapid-response sensors for thermal protection during transient load cycles. Chinese domestic brands in Shanghai and Guangzhou specify compact electronic sensors for integration into plastic intake manifolds, prioritizing packaging efficiency over absolute precision.
- Commercial Vehicles:EPA Tier 4 and Euro VI emission enforcement mandates precise coolant temperature feedback for selective catalytic reduction dosing calibration. Freightliner and Volvo Trucks specifications in North America require extended temperature range validation for desert and arctic operation.
- Electric Vehicles:Battery thermal management and power electronics cooling create redundant sensor requirements per platform.
- Heavy-Duty Trucks:Mining and logging applications in Western Canada and Western Australia specify shock-hardened sensor housings.
Largest installed base: Passenger Vehicles. Fastest application growth: Electric Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian ceramic substrate clusters while consumption spreads across German precision engineering, American heavy-duty fleets, and Chinese new energy vehicle assembly corridors. This geographic split forces module assemblers to manage transcontinental supply exposure against localized thermal specification demands.
China
Domestic NEV manufacturers in Shanghai and Shenzhen drive redundant coolant sensor procurement for battery thermal management and power electronics cooling. MIIT enforces GB standards for new energy vehicle thermal systems, creating parallel certification tracks for suppliers serving BYD and NIO production lines. Yangtze River Delta automotive corridors concentrate tier-1 module integration facilities for export and domestic OEM programs.
Germany
Commercial vehicle EGR cooler monitoring and passenger hybrid platform launches sustain RTD and multi-sensor fusion demand in Stuttgart and Wolfsburg engineering centers. ECHA REACH substance restrictions force ceramic reformulation for thermistor suppliers serving European export markets. Bavaria-based thermal management specialists anchor multi-sensor module contracts with premium OEM powertrain divisions.
United States
EPA Tier 4 enforcement across heavy-duty trucking fleets in Michigan and Texas generates replacement sensor demand for thermal monitoring upgrades. NHTSA safety standards shape accuracy thresholds for engine control unit integration in Detroit Three platform development. Southwest desert operation specifications from Freightliner and Volvo Trucks require extended temperature range validation.
Japan
Toyota thermal system engineering in Aichi Prefecture drives specification evolution toward compact electronic sensors for downsized turbocharged engines. METI industrial policy supports precision ceramic manufacturing for thermistor elements serving domestic and export assembly. Kansai region suppliers maintain scale advantages in thermistor bead production for Asian vehicle corridors.
India
BS-VI emission enforcement creates aftermarket sensor replacement demand across commercial vehicle parcs in Maharashtra and Tamil Nadu lacking factory-installed precision monitoring. The country's national automotive regulator mandates thermal efficiency compliance for heavy-duty truck and bus fleets. Chennai and Pune automotive clusters concentrate tier-1 module assembly for domestic OEM supply and export programs.
Automotive Radiator Water Temperature Sensor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the supplier base, creating a tiered structure where electronics-integrated module providers capture premium contracts. The market consolidates around three strategic archetypes: integrated thermal management module suppliers, precision sensor component specialists, and diversified automotive electronics conglomerates. Dominant competitive moves include multi-sensor fusion portfolio expansion and geographic qualification for NEV platform sourcing in China.
Within the diversified conglomerate tier, Robert Bosch GmbH and Denso Corporation exemplify scale-driven positioning through integrated electronics portfolios and manufacturing corridor presence. Sensata Technologies Inc. occupies a specialist position exemplifying high-temperature material expertise for commercial vehicle applications. These three anchors represent distinct competitive vectors: European multi-sensor module integration, Asian manufacturing scale, and North American precision engineering specialization.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Panasonic Corporation |
| NXP Semiconductors N.V. |
| Sensata Technologies Inc. |
| Continental AG |
| Mitsubishi Electric |
| Aptiv |
| Hanon Systems |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up ceramic substrate specialists in East Asia anchor supply-side discipline, translating concentrated ownership into synchronized capacity management that buffers platinum-group metal volatility while preserving margin structures for European module assemblers.
Pricing Analysis
Margin tightening in the NTC thermistor tier reflects platinum thin-film deposition cost swings and REACH-driven ceramic reformulation expenses. Three-tier pricing structure across premium RTD, standard thermistor, and economy bimetallic levels separates precision calibration grades. Cost compression accelerates because OEMs consolidate multi-sensor module awards, collapsing discrete part premiums. Aftermarket distributors show highest price sensitivity; commercial vehicle fleet operators demonstrate lowest.
Supply Chain Analysis
Trans-Pacific freight rate volatility and container availability constraints shape inventory positioning for North American module assemblers sourcing from Yangtze River Delta ceramic corridors. Supply concentrates in China, Japan, and Germany for thermistor beads, platinum thin-film substrates, and precision RTD elements respectively. Raw material dependencies rest on ceramic-metal oxide powders, platinum group metals, and high-purity alumina substrates. Single-source vulnerability concentrates in East Asian thermistor bead manufacturing. Distribution runs through tier-1 thermal management module suppliers to OEM platform engineering groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from modular thermal architecture mandates is eliminating discrete component specialists unable to requalify entire subsystems, compressing viable supplier counts to integrated module providers.
For Market Incumbents: Acquire wireless protocol engineering capabilities and high-temperature material characterization assets to defend against silicon-based temperature sensing substitution. Deepen backward integration into ceramic substrate production to secure supply continuity amid Asian concentration risks. Prioritize ISO 26262 ASIL certification investment to compress validation timelines against platform launch schedules. For New Entrants and Emerging Players: Capture India commercial vehicle aftermarket retrofit demand created by BS-VI enforcement across Maharashtra and Tamil Nadu truck parcs. Target wireless sensor mesh integration for OEM thermal module suppliers seeking harness reduction. Lead with Bluetooth Low Energy protocol expertise as the go-to-market wedge against legacy analog incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision thermistor specialists with captive ceramic formulation capabilities in Germany and Japan. Five-to-ten-year viability hinges on electric vehicle thermal loop expansion sustaining redundant sensor demand per platform. Watch for MIIT GB standard revisions as the signal for China NEV procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Module Expansion | Collapses three discrete part numbers into single qualified assemblies for European hybrid platforms. |
| Wireless Protocol Integration | Eliminates harness connector points, reducing warranty leak liability for OEM suppliers. |
| High-Temperature Material Specialization | Secures commercial vehicle contracts requiring extended desert and arctic validation ranges. |
| REACH-Compliant Ceramic Reformulation | Maintains European market access as ECHA restrictions eliminate cadmium and lead stabilizers. |
| India Manufacturing Footprint Establishment | Positions for BS-VI aftermarket demand across Maharashtra and Tamil Nadu commercial corridors. |
Research Methodology
SEC 10-K filings, IHS Markit vehicle production databases, and ECHA REACH substance restriction registers formed the secondary backbone. Primary interviews with tier-1 thermal module procurement officers, OEM platform engineers, aftermarket distribution channel heads, and ceramic substrate manufacturing directors validated demand assumptions. Bottom-up sensor content-per-vehicle estimates combined with top-down regional production forecasts through triangulation.
Bottom-up modeling anchored volume projections across vehicle class, propulsion architecture, and content-per-vehicle segmentation dimensions. CAGRs derived from regression analysis against EPA Tier 4 enforcement timelines and China NEV penetration curves. Platinum group metal price indices and ceramic substrate capacity utilization rates informed cost-side forecast sensitivity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon-based temperature sensing substitution rates and wireless protocol standardization timing. Forecasts reflect documented assumptions about modular thermal architecture adoption and REACH substance restriction enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Russia Automotive Camera Market
Automotive Electronics & Wiring
Russia Automotive Reed Sensors Switches Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Brazil Automotive Adaptive Lighting System Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Data Logger Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Global Vehicle Camera Market