
 Automotive Glow Plug Market | 2026-2036
Automotive Glow Plug Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Glow Plug Market Analysis
Modular glow plug kits bundled with control units and temperature sensors is broadening buyer choice beyond standalone replacement parts. Robert Bosch GmbH leverages its sensor-integration expertise to dominate bundled system configurations. NGK Spark Plug Co. Ltd anchors the ceramic element segment through proprietary high-alumina formulations. Denso Corporation sustains OEM channel control with just-in-time delivery contracts across Japanese and Thai assembly plants.
An automotive glow plug is a resistive heating element, typically comprising a metal sheath or ceramic body with an embedded heating coil, designed to pre-heat combustion chambers in diesel engines for reliable cold starts; ceramic variants withstand sheath temperatures exceeding 1,300°C while drawing lower amperage than conventional metal designs. Ceramic glow plugs command premium positioning as diesel engines adopt higher-pressure direct injection architectures demanding faster heat-up cycles. Fast-heating variants represent the fastest-expanding product category, though standard metal plugs still occupy the bulk of aftermarket volume in price-sensitive regions. OEM installation channels concentrate margin pools through long-term supply agreements, while replacement installation segments compete on logistics density and catalog breadth.
The US EPA and California Air Resources Board enforce particulate emission thresholds that effectively mandate glow plug reliability for diesel cold-start compliance, while the EU F-Gas Regulation and Euro 7 standards from the European Commission pressure heating-element efficiency benchmarks. India's BIS certification requirements for automotive electrical components create incremental compliance costs for import-dependent suppliers. Stakeholders must monitor the pace of diesel engine phase-out commitments against residual fleet replacement demand to calibrate capacity and inventory positions.
Market Dynamics
China's MIIT emission mandates for compression-ignition engines are tightening material specifications for heating elements, forcing suppliers to requalify ceramic formulations and metal alloys against stricter thermal efficiency benchmarks. This regulatory compression is reshaping supplier relationships across the diesel cold-start component ecosystem.
Growth Catalysts
- Ceramic fast-heating architectures:High-alumina formulations withstand sheath temperatures exceeding 1,300°C while drawing lower amperage, enabling OEMs to meet Euro 7 pre-heating efficiency thresholds without auxiliary battery upgrades.
- Indonesia's logistics corridor expansion:Port-based trucking operators in Jakarta and Surabaya require reliable pre-heating systems for high-sulfur fuel environments, sustaining replacement demand for heavy-duty glow plug configurations.
- US EPA particulate emission thresholds:Cold-start compliance mandates effectively require glow plug reliability for diesel fleet operators, embedding these components into emission control system architectures.
Market Restraints
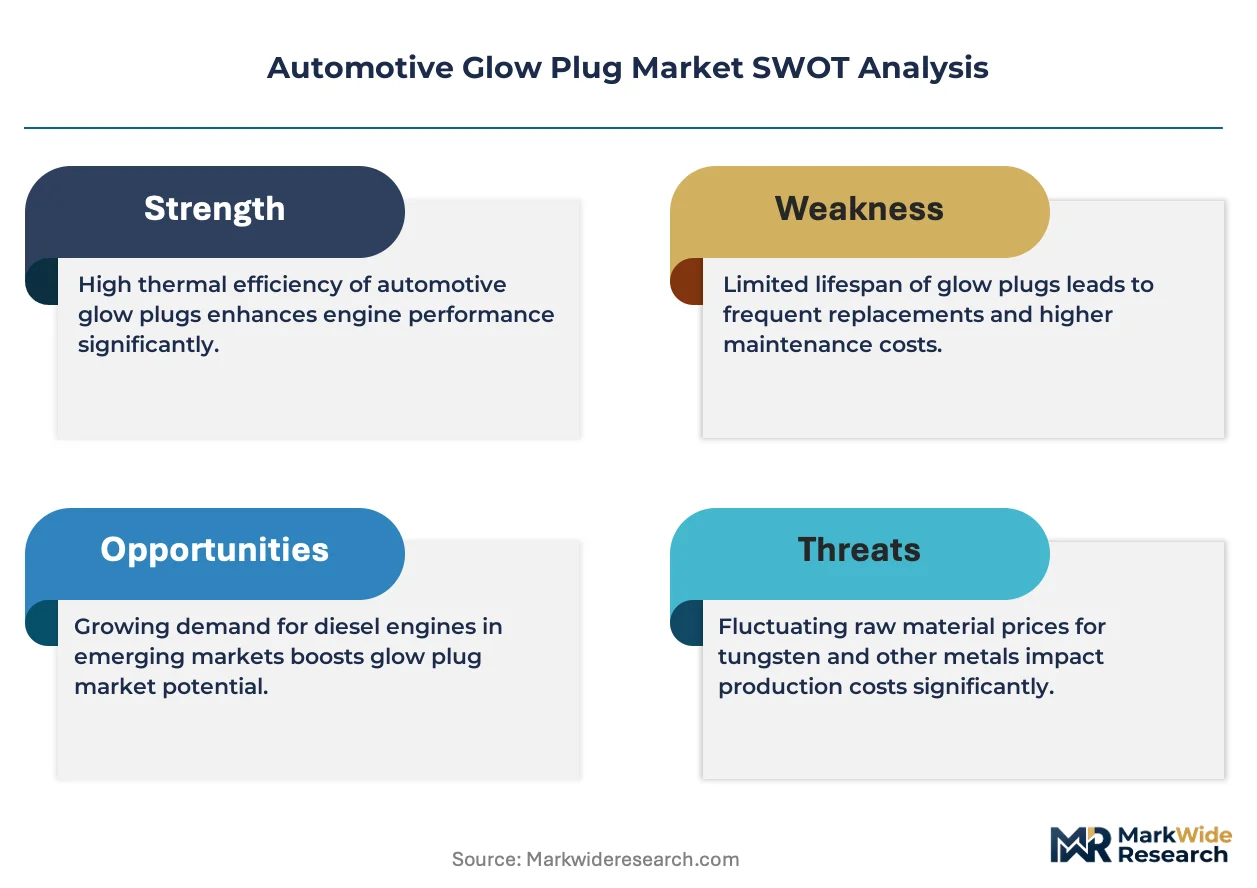
- Platinum-group metal cost volatility:Heating coil alloys depend on ruthenium and palladium feedstocks, exposing manufacturers to London Metal Exchange price swings that compress margin on standard metal plug categories.
- Supply concentration in Japanese ceramic substrate production:Proprietary high-alumina formulation expertise concentrates among limited specialty refractory suppliers, creating single-source vulnerability for fast-heating variant OEM qualification.
- Diesel engine phase-out commitments:France, Germany, and the United Kingdom have announced combustion engine sunset dates that depress long-term capacity planning confidence among component manufacturers.
Strategic Opportunities
- Modular bundled system penetration:Control unit and temperature sensor integration creates attach-rate expansion beyond standalone replacement parts, capturing margin pools currently held by separate electronics suppliers.
- India's BIS certification barrier:Import-dependent suppliers face incremental compliance costs for automotive electrical components, creating first-mover advantage for domestic manufacturing investments or joint venture structures with local Tier 1s.
- EU F-Gas Regulation efficiency benchmarks:Heating-element performance standards are accelerating OEM specification upgrades, opening premium positioning for ceramic variants in European light commercial vehicle platforms.
Industry Challenges
- Ceramic metallization process yield:Embedded heating coil bonding to alumina substrates requires vacuum brazing expertise that concentrates among aging specialist technicians, constraining production scaling for fast-heating variants.
- Legacy fleet compatibility certification:Aftermarket suppliers must maintain backward-compatible part numbers across decades of diesel engine architectures, fragmenting inventory and complicating catalog management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Glow Plug Market |
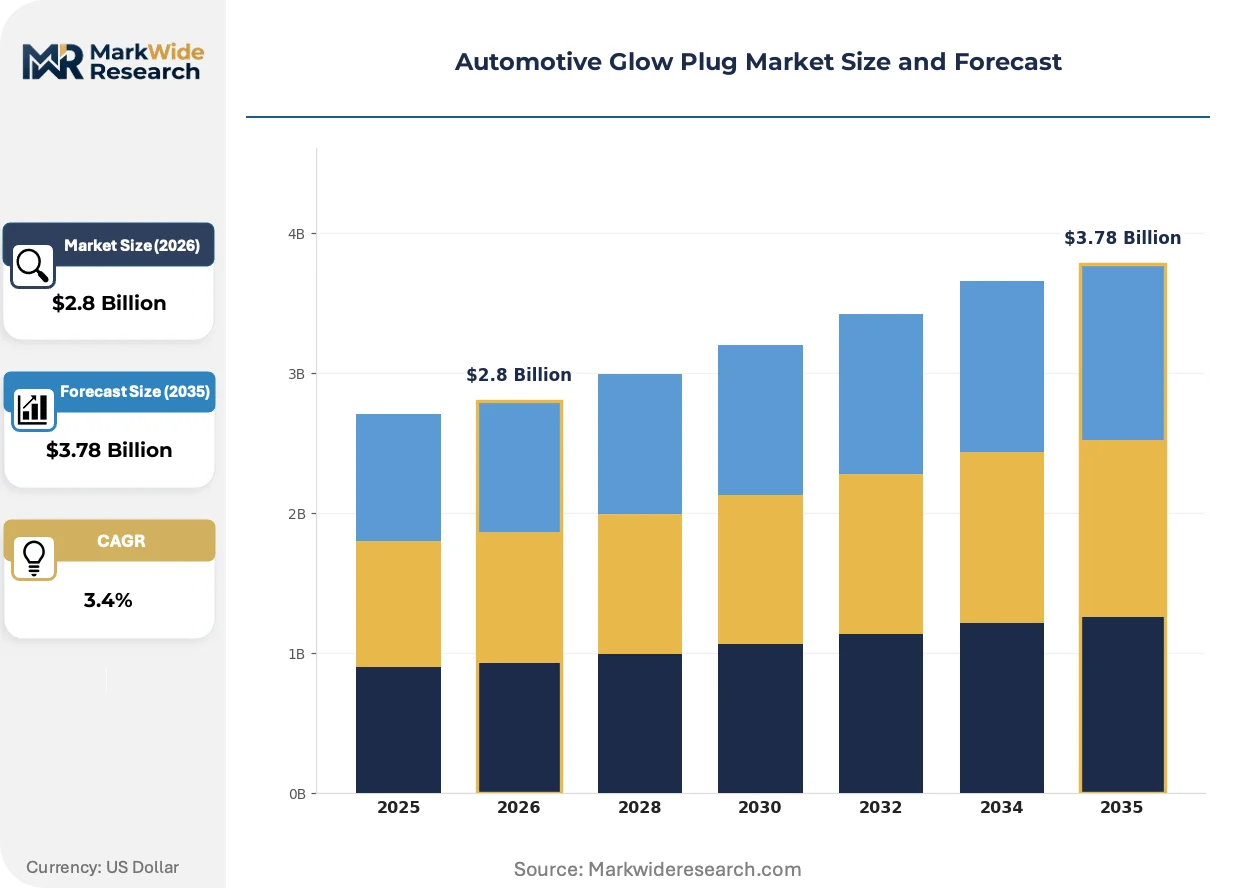
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Glow Plugs, Ceramic Glow Plugs, Fast-Heating Glow Plugs, Standard Glow Plugs Application: Light Duty Vehicles, Heavy Duty Vehicles, Agricultural Equipment, Marine Applications End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Installation Type: OEM Installation, Replacement Installation, Integrated System, Standalone Units |
| Companies Covered | Denso Corporation, NGK Spark Plug Co. Ltd, Robert Bosch GmbH, BorgWarner Inc., Tenneco Inc., Valeo SA, Kyocera Corporation, Marelli Holdings Co. Ltd, Niterra Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Glow Plug Market Emerging Trajectories
Ceramic glow plug technology is absorbing engineering investment as diesel architectures evolve, while regulatory pressure on cold-start emissions intensifies specification requirements. Distribution and procurement patterns are compressing traditional channel structures.
Silicon nitride ceramic substrates are absorbing the thermal stress loads previously managed by metal sheath designs, enabling faster heat-up cycles for high-pressure direct injection architectures. European and Japanese OEMs are adopting these variants for next-generation light commercial platforms. The technology is absorbing margin from conventional metal plug categories as specification premiums widen.
EU F-Gas Regulation amendments are tightening heating-element efficiency benchmarks for automotive applications, forcing suppliers to document watt-per-degree performance across operating temperature ranges. Component manufacturers must requalify existing product lines against revised test protocols. Fast-heating ceramic variants face the steepest compliance trajectory given their higher thermal output claims.
Fleet procurement is consolidating replacement part purchasing through authorized dealer networks, squeezing independent aftermarket distributors in Southeast Asian logistics corridors. Indonesian and Thai port-based operators now specify OEM-certified glow plug kits with integrated sensors, displacing standalone component sourcing. This concentration is most visible in Jakarta's container terminal trucking fleets, where maintenance contracts bundle cold-start system replacement cycles.
Automotive Glow Plug Market Segmentation
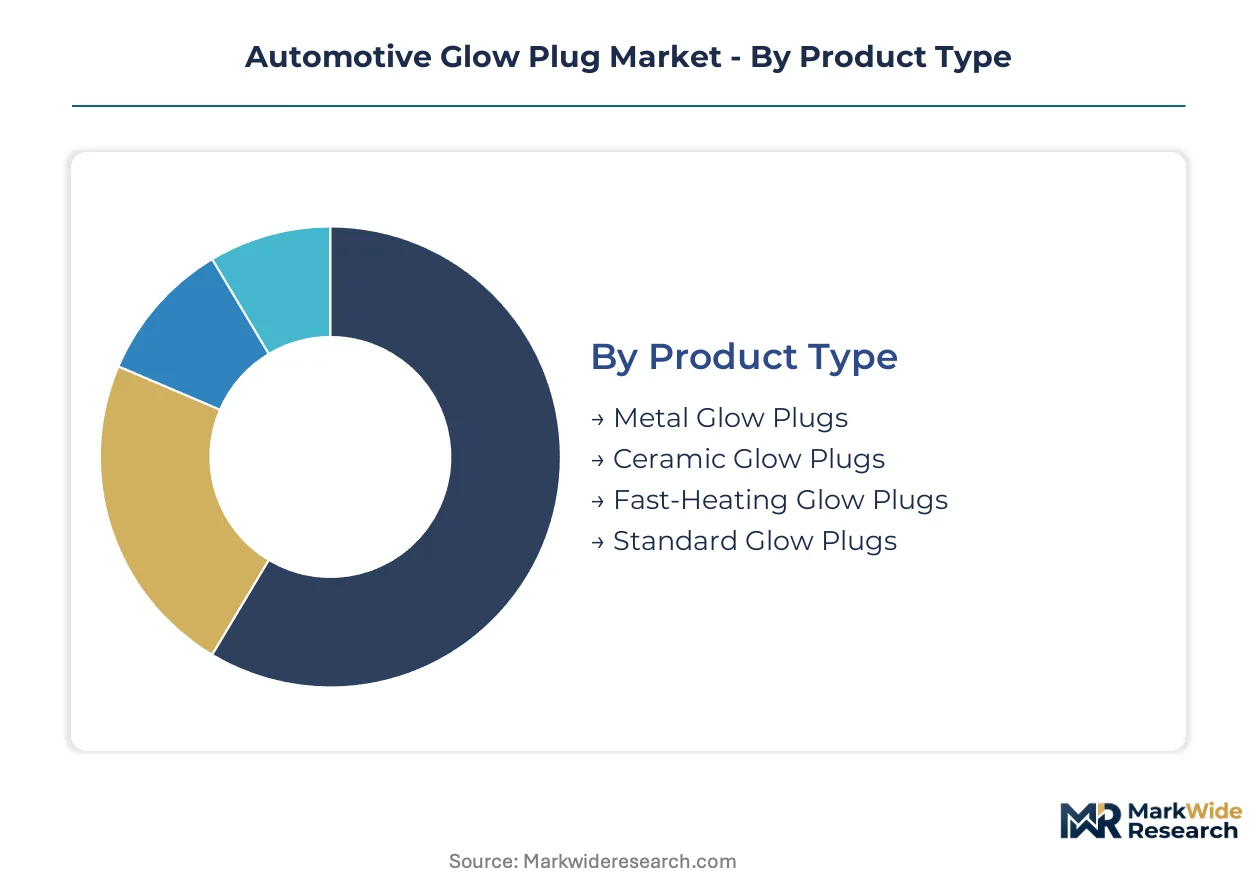
Segmentation in the automotive glow plug market reveals how capital deployment, technical specifications, and channel structures determine competitive positioning across heating element categories. Product architecture choices and installation modalities shape supplier economics more dramatically than in many other engine component segments.
Product Type:
Capital intensity concentrates in ceramic formulations requiring vacuum brazing infrastructure and metallization expertise, while metal variants demand less specialized equipment but face raw material cost volatility.
- Ceramic Glow Plugs:High-alumina substrates withstand sheath temperatures exceeding 1,300°C while drawing lower amperage than metal alternatives. European OEMs specify these for Euro 7-compliant light commercial platforms where pre-heating efficiency thresholds tighten.
- Fast-Heating Glow Plugs:Silicon nitride architectures absorb thermal stress loads previously managed by metal sheaths, enabling heat-up cycles under two seconds for high-pressure direct injection diesel engines. Japanese and German OEMs are qualifying these variants for next-generation compression-ignition architectures.
- Metal Glow Plugs:Conventional resistive heating elements comprising metal sheaths with embedded coils dominate aftermarket volume in price-sensitive Southeast Asian markets.
- Standard Glow Plugs:Legacy metal designs serve replacement demand across aging diesel fleets where backward compatibility constrains specification upgrades.
Metal glow plugs absorb the bulk of installed capacity; fast-heating variants are expanding most quickly.
Application:
Volume concentration follows diesel engine deployment patterns across transportation and off-road equipment categories, with duty cycles determining replacement frequency and specification requirements.
- Heavy Duty Vehicles:Port-based trucking operators in Indonesia's logistics corridor require reliable pre-heating systems for high-sulfur fuel environments, sustaining demand for heavy-duty glow plug configurations with extended service intervals.
- Light Duty Vehicles:Euro 7 and EPA particulate emission thresholds embed glow plug reliability into cold-start compliance architectures for diesel passenger cars and light commercial fleets.
- Agricultural Equipment:Seasonal cold-start requirements in temperate climates drive replacement cycles for tractors and harvesters with intermittent duty patterns.
- Marine Applications:Salt-air corrosion resistance specifications differentiate marine glow plug designs from automotive variants.
Light duty vehicles command the largest addressable base; heavy duty vehicles generate the highest per-unit replacement revenue.
End User:
Channel control patterns diverge sharply between captive OEM supply relationships and fragmented aftermarket procurement structures.
- OEMs:Long-term supply agreements with just-in-time delivery requirements concentrate margin pools through qualification barriers and technical integration mandates.
- Aftermarket Providers:Independent distributors compete on logistics density and catalog breadth across fragmented repair shop networks.
- Vehicle Assemblers:Thai and Japanese assembly plants maintain tight supplier relationships for bundled glow plug and sensor system configurations.
- Repair Shops:Technical labor constraints favor pre-assembled kits over component-level sourcing in emerging markets.
OEMs lock in the majority of primary manufacturing capacity; aftermarket providers are gaining procurement consolidation leverage.
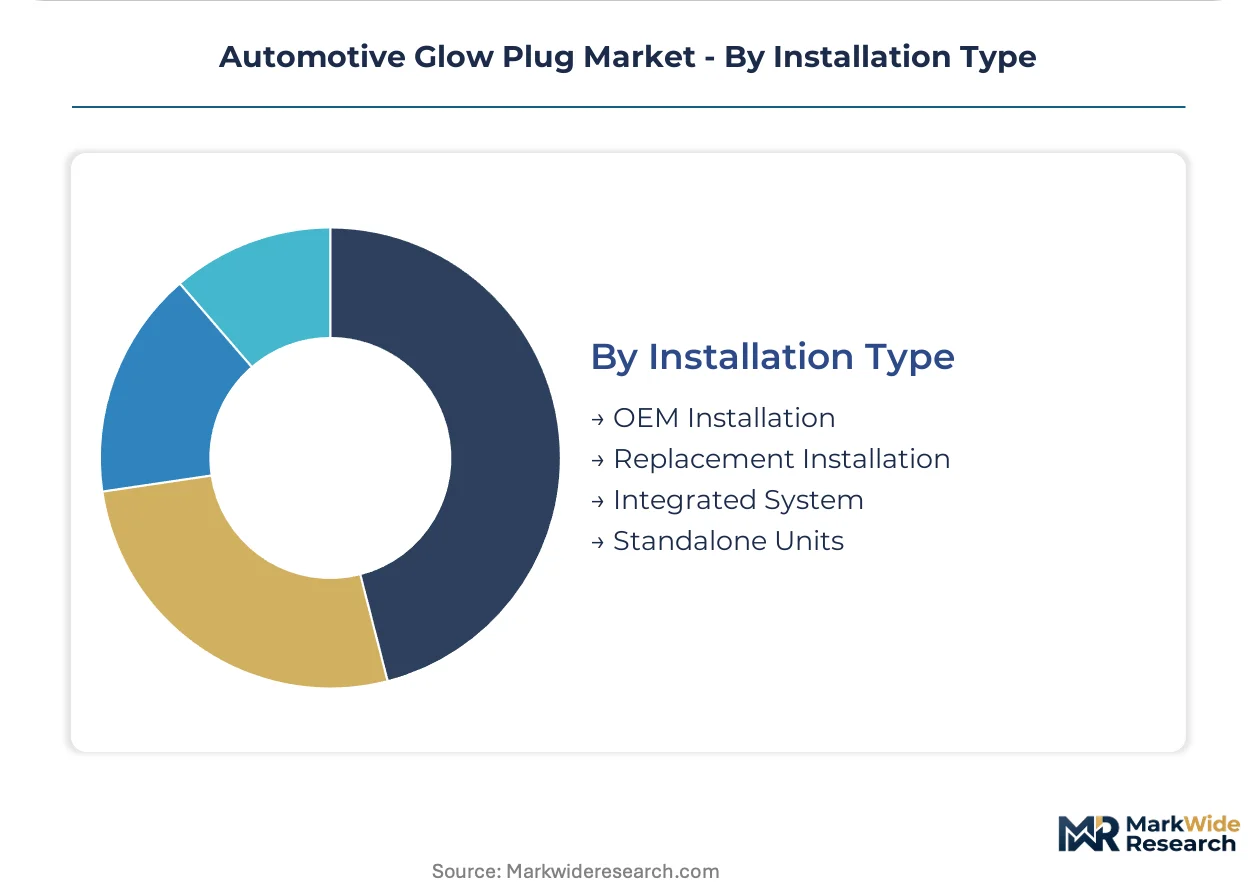
Installation Type:
System integration depth determines supplier margin capture and technical barrier height across installation modalities.
- Integrated System:Control unit and temperature sensor bundling creates attach-rate expansion beyond standalone replacement parts, capturing margin pools from separate electronics suppliers.
- OEM Installation:Factory-fit specifications embed glow plugs within engine management system architectures with proprietary calibration protocols.
- Replacement Installation:Jakarta's container terminal trucking fleets now specify OEM-certified kits with integrated sensors, displacing standalone component sourcing.
- Standalone Units:Price-sensitive regions still favor unbundled glow plug procurement for legacy fleet maintenance.
Replacement installation handles the greatest transaction volume; integrated systems are climbing the fastest in revenue per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's port-based logistics corridors function as specialized economic zones concentrating diesel fleet replacement demand. Cold-start component procurement concentrates around Jakarta and Surabaya container terminals.
China
MIIT emission mandates for compression-ignition engines force ceramic formulation requalification across supplier networks. GB standards for automotive electrical components now incorporate thermal efficiency benchmarking for heating elements. Yangtze River Delta manufacturing clusters absorb the bulk of ceramic substrate qualification testing.
Germany
KBA vehicle type-approval protocols embed glow plug reliability into Euro 7 cold-start compliance architectures. The EU F-Gas Regulation pressures heating-element efficiency documentation across watt-per-degree performance ranges. Bavarian automotive supplier parks coordinate just-in-time delivery contracts for bundled sensor-integrated systems.
United States
EPA particulate emission thresholds mandate glow plug functionality for diesel fleet cold-start compliance. California Air Resources Board enforcement extends these requirements to port-based drayage operators. Midwest logistics corridors maintain replacement cycles for heavy-duty configurations serving intermodal freight terminals.
Japan
METI industrial standards guide ceramic glow plug metallization process specifications for domestic OEM supply. JIS certification requirements create qualification barriers for imported heating element substrates. Kanto region assembly plants maintain tight supplier relationships for fast-heating variant integration.
India
BIS certification requirements for automotive electrical components impose compliance costs on import-dependent glow plug suppliers. DGFT import regulations shape sourcing patterns for ceramic substrate materials. Maharashtra-based Tier 1 suppliers explore joint venture structures to capture domestic manufacturing incentives.
Automotive Glow Plug Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the glow plug supplier base. The market structure concentrates primary manufacturing capacity among vertically integrated automotive component groups. Three archetypes dominate: sensor-integration conglomerates, ceramic formulation specialists, and exhaust-system integrators. Competitive moves center on bundled system attach-rate expansion and ceramic substrate supply security.
Within the sensor-integration tier, Robert Bosch GmbH and Denso Corporation exemplify diversified conglomerate positioning. NGK Spark Plug Co. Ltd anchors the ceramic formulation specialist archetype. These three occupy positions reflecting distinct capability foundations: control unit integration expertise, just-in-time delivery infrastructure, and high-alumina substrate metallization know-how.
| Leading Market Players |
|---|
| Denso Corporation |
| NGK Spark Plug Co. Ltd |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Tenneco Inc. |
| Valeo SA |
| Kyocera Corporation |
| Marelli Holdings Co. Ltd |
| Niterra Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Silicon nitride ceramic substrate adoption simultaneously compresses per-unit manufacturing costs and concentrates production expertise among Japanese and German refractory specialists with vacuum brazing capabilities. This dual effect reshapes supplier economics as OEMs demand faster heat-up cycles for Euro 7-compliant architectures.
Pricing Analysis
Short lead-time premiums of ceramic fast-heating variants command pricing power against standard metal plugs stocked for spot replacement. Three-tier pricing structure across premium ceramic, standard metal, and economy legacy configurations stratifies by thermal efficiency certification and OEM qualification status. Price erosion runs through standard metal categories as Indonesian and Thai fleet operators consolidate procurement through authorized dealer networks. Aftermarket distributors remain most price-sensitive; OEM-integrated system suppliers capture least elastic demand through bundled sensor configurations.
Supply Chain Analysis
Vacuum brazing technician scarcity in Japan's Kanto region and Germany's Bavarian supplier parks constrains production scaling for ceramic fast-heating variants. Raw material sourcing draws from Chinese high-alumina substrate production, South Korean silicon nitride powder refinement, and Russian palladium feedstock channels. Single-source vulnerability concentrates in Japanese ceramic metallization expertise. Distribution runs through Tier 1 supplier consolidation toward OEM assembly plants and authorized dealer networks in Southeast Asian logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with captive ceramic substrate production as Euro 7 efficiency mandates eliminate marginal metal-plug manufacturers lacking qualification resources.
For Market Incumbents: Deepen backward integration into high-alumina substrate production to secure supply against Japanese refractory concentration. Acquire vacuum brazing specialist shops in Germany and Japan to capture aging technician expertise before retirement waves. Lock in long-term supply agreements with Indonesian and Thai port-based fleet operators to defend replacement channel share against OEM-certified kit penetration. For New Entrants and Emerging Players: Launch via joint venture structures with Maharashtra-based Tier 1 suppliers to exploit India's BIS certification barrier against import-dependent competitors. Target India's domestic manufacturing incentives as the most penetrable geography. Pursue white-space positioning in ceramic glow plug aftermarket for aging European diesel fleets requiring backward-compatible specifications. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified automotive sensor conglomerates seeking heating-element integration capabilities. Long-term viability hinges on residual diesel fleet replacement demand against announced combustion engine phase-out commitments. Monitor France, Germany, and United Kingdom policy implementation pace as the critical inflection signal for capacity planning confidence.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Captive high-alumina production insulates margin from Japanese refractory supply concentration. |
| Vacuum Brazing Specialist Acquisition | Aging technician expertise in Kanto and Bavaria represents non-replicable production capacity. |
| Modular System Bundling | Control unit and sensor integration captures margin pools from separate electronics suppliers. |
| India Joint Venture Structure | BIS certification barrier creates first-mover advantage for domestic manufacturing investments. |
| Indonesian Fleet Maintenance Contracts | Jakarta and Surabaya port-based operators consolidate procurement through authorized channels. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this automotive glow plug market analysis. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations validated demand assumptions. Secondary sources incorporated MIIT emission mandate documentation, EU F-Gas Regulation amendments, EPA enforcement patterns, and vehicle production databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation combined shipment volume tracking with OEM specification upgrade timelines and aftermarket replacement cycle frequencies. Segmentation dimensions modeled include product architecture, vehicle duty class, installation modality, and regional regulatory cluster. CAGRs derived from regression analysis of historical replacement demand against diesel fleet age distributions and emission mandate implementation schedules. Industry-specific inputs incorporated ceramic substrate yield rates and platinum-group metal price volatility indices.
The model assumes a particular technology adoption path; alternative pathways for silicon nitride fast-heating architectures would alter the outlook if OEM qualification timelines accelerate or stall. Forecasts reflect assumptions regarding residual diesel fleet longevity and regulatory phase-out enforcement consistency. Material deviation in Euro 7 implementation rigor or Southeast Asian logistics corridor expansion pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Asia-Pacific Automotive Smart Key Market
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Automotive NFC Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Automotive Antenna Module Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
India Automotive Lighting Market