
 Two-Wheeler Connectivity Systems Market | 2026-2036
Two-Wheeler Connectivity Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Connectivity Systems Market Analytics
The gap between premium integrated systems and basic standalone devices is broadening. Robert Bosch GmbH leverages its tier-1 automotive relationships to anchor OEM installation pipelines across European and Asian motorcycle brands. Continental AG competes through dedicated V2X communication modules that satisfy emerging safety mandates. NXP Semiconductors specializes in automotive-grade connectivity chipsets that power both smart helmets and embedded connectivity modules.
Two-wheeler connectivity systems encompass hardware and software solutions that enable real-time data exchange between motorcycles or scooters, riders, infrastructure, and cloud platforms, typically operating over Bluetooth Low Energy, cellular LTE/5G, or dedicated short-range communication at 5.9 GHz. These systems serve collision avoidance, stolen-vehicle tracking, remote diagnostics, and fleet optimization purposes in both consumer and commercial contexts. Connectivity modules and smartphone apps currently occupy the largest addressable base, while V2X communication represents the fastest-growing technology segment as regulators embed cooperative intelligent transport into road safety frameworks. Fleet operators and ride-sharing services concentrate margin pools due to recurring software-as-a-service revenue models and bulk procurement contracts.
The European Union's F-Gas Regulation and CE marking requirements shape thermal management and electromagnetic compatibility standards for connectivity hardware, while India's Ministry of Road Transport and Highways pushes AIS-140 compliance for commercial two-wheeler telematics. The US National Highway Traffic Safety Administration evaluates V2X communication protocols for motorcycle integration under broader intelligent transportation system roadmaps. Stakeholders must monitor how cellular-to-V2X technology transitions and evolving cybersecurity mandates reshape product roadmaps and supplier qualification timelines.
Market Dynamics
Cellular-to-V2X technology transitions are compressing product lifecycles as fleet operators and OEMs recalibrate connectivity roadmaps around emerging safety mandates and data monetization architectures.
Growth Catalysts
- Cellular V2X mandates:The EU's cooperative intelligent transport framework and India's AIS-140 compliance push are embedding dedicated short-range communication into commercial two-wheeler specifications.
- Fleet telematics expansion:Ride-sharing and last-mile delivery operators are deploying bulk connectivity contracts with recurring software-as-a-service revenue models.
- Urban density corridors:São Paulo, Ho Chi Minh City, and Bangalore concentrate aftermarket installation demand as congestion management prioritizes connected mobility infrastructure.
Market Restraints
- Automotive-grade chipset supply concentration:Semiconductor fabrication for 5G and V2X modules clusters among a limited set of foundry operators, creating input bottlenecks.
- Electromagnetic compatibility certification costs:CE marking and F-Gas Regulation compliance in Europe extend hardware qualification timelines and inflate development expenditure.
- Bluetooth-to-cellular transition friction:Legacy standalone devices face substitution pressure from integrated systems, stranding installed base investments.
Strategic Opportunities
- Vietnam aftermarket penetration:Motorcycle density in Hanoi and Ho Chi Minh City outpaces integrated OEM adoption, creating white space for retrofit connectivity modules.
- 5G-V2X convergence:Dual-mode communication architectures that blend cellular low-latency networks with direct vehicle-to-vehicle protocols are opening new product categories.
- India PLI scheme alignment:Production-linked incentive frameworks for automotive electronics are attracting component localization investments that reduce import dependency.
Industry Challenges
- Cybersecurity engineering talent scarcity:Embedded systems security expertise for over-the-air update architectures remains concentrated among a narrow specialist pool.
- Multi-protocol integration complexity:Hardware engineers must reconcile Bluetooth Low Energy, LTE, 5G, and DSRC stacks within constrained power and thermal envelopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Connectivity Systems Market |
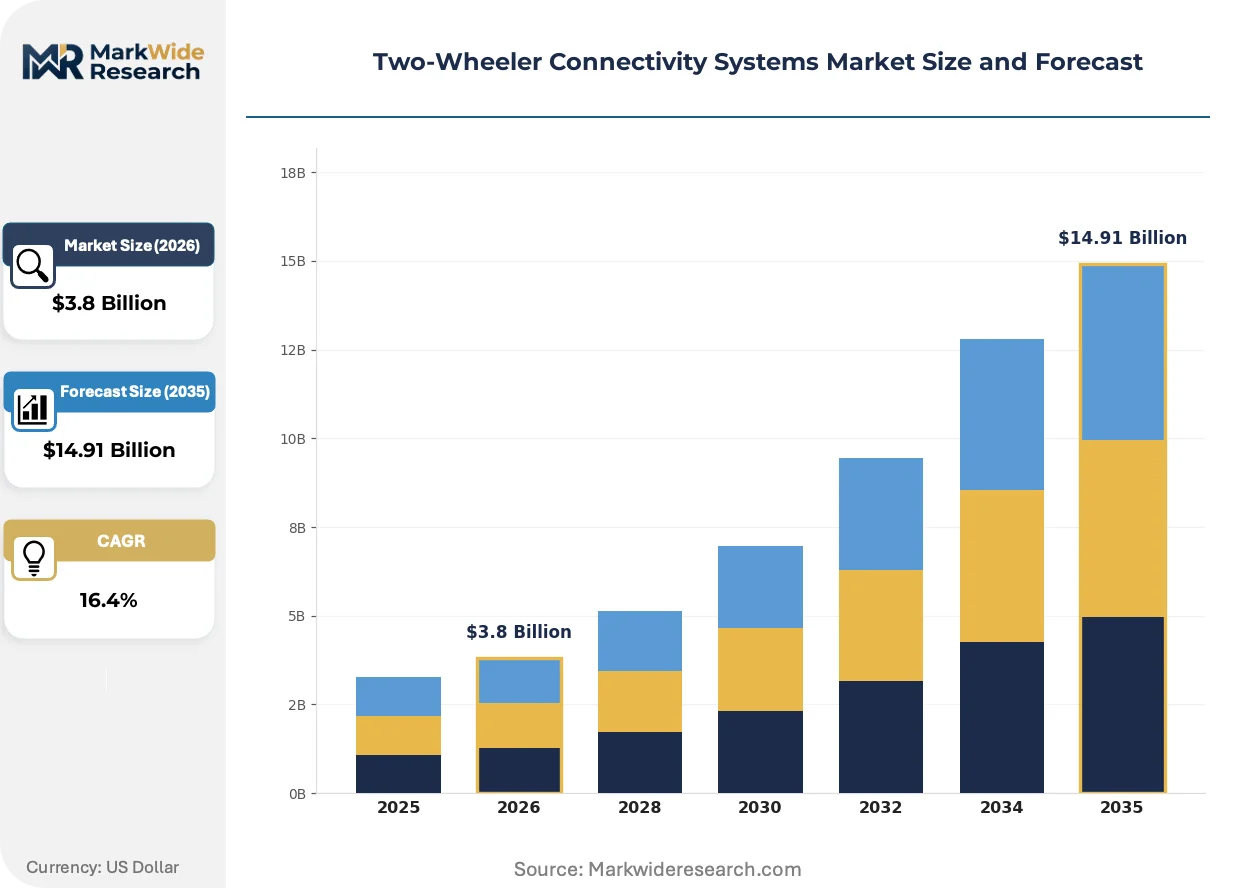
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, GPS Navigation Devices, Connectivity Modules, Smartphone Apps Technology: Bluetooth, Wi-Fi, Cellular, V2X Communication End User: Individual Riders, Fleet Operators, Commercial Users, Ride-Sharing Services Installation Type: OEM Installation, Aftermarket Installation, Integrated Systems, Standalone Devices |
| Companies Covered | NXP Semiconductors, Autotalks Ltd, Robert Bosch GmbH, Aeris Communications, KPIT Technologies Limited, Continental AG, Panasonic Corporation, Starcom Systems Ltd, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Connectivity Systems Market Evolving Landscape
Real-time data architectures are redefining value capture in two-wheeler mobility, compressing the boundary between hardware sales and ongoing service revenue.
Edge-enabled telematics units are rewriting fleet economics. These devices process collision detection and route optimization algorithms locally before cloud transmission. Logistics operators in Brazil and India are adopting them at scale to reduce latency and data costs. The technology is rewriting how connectivity providers structure pricing, shifting from device margins to usage-based subscription tiers.
Europe's F-Gas Regulation and electromagnetic compatibility directives are tightening hardware design constraints. Manufacturers must now integrate thermal management solutions that satisfy both environmental and signal integrity standards. Premium motorcycle OEMs are responding by consolidating supplier qualification around tier-1 automotive partners with established compliance track records.
Fleet procurement patterns are fragmenting as operators unbundle hardware from software contracts. Large ride-sharing platforms now source connectivity modules through separate RFPs from telematics platform licenses. This bifurcation is most pronounced in India, where Swiggy and Zomato delivery cooperatives negotiate device procurement independently from cloud analytics subscriptions.
Two-Wheeler Connectivity Systems Market Segmentation
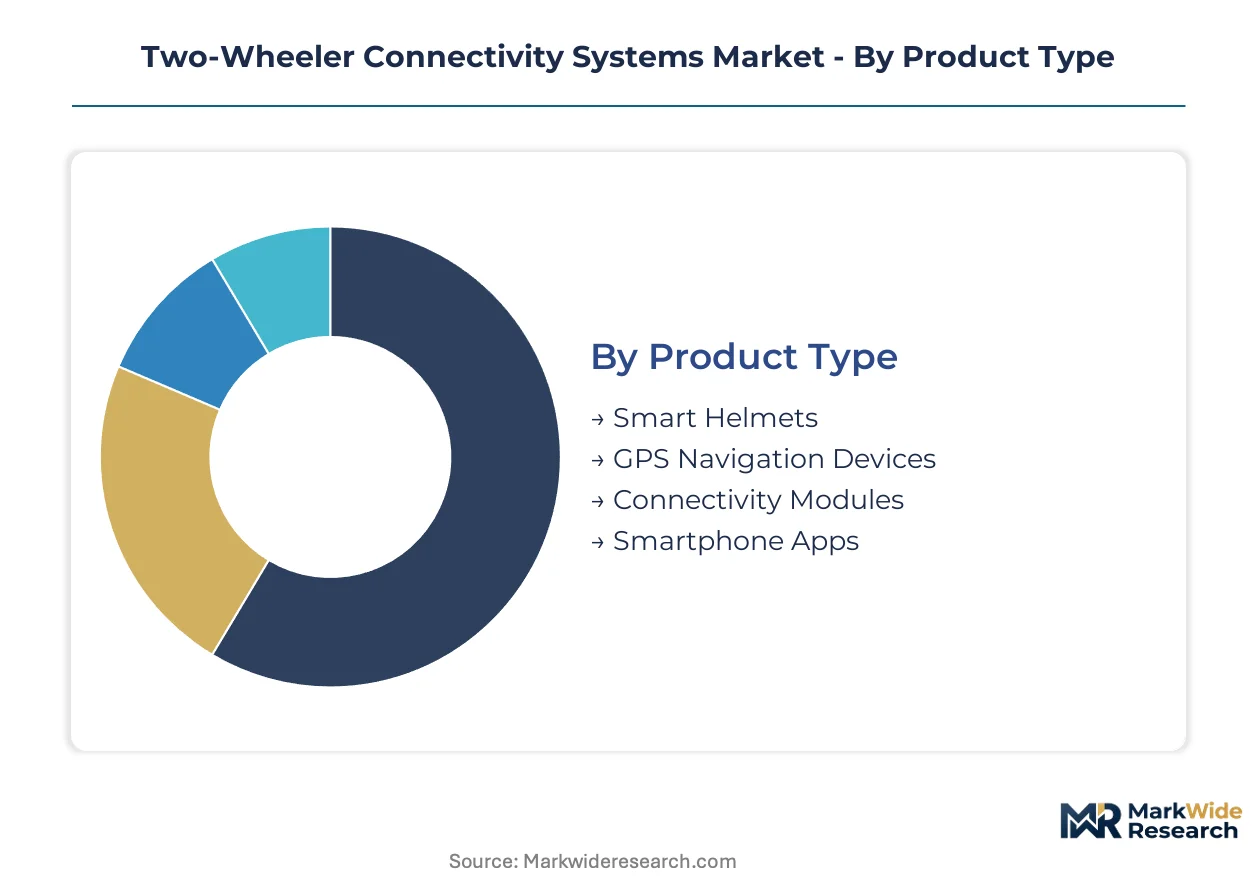
Two-wheeler connectivity systems fragment across four dimensions that determine regulatory exposure, margin structure, and supplier qualification requirements. Each category carries distinct certification burdens and procurement patterns that reshape competitive positioning.
Product Type:
CE marking and electromagnetic compatibility testing requirements vary sharply across product categories, with head-worn devices facing additional personal protective equipment standards.
- Smart Helmets:Integrated audio, navigation, and communication systems embedded within protective headgear. Demand concentrates among premium motorcycle owners in Germany and Italy where ECE 22.06 helmet standards mandate connectivity compatibility testing.
- GPS Navigation Devices:Dedicated handlebar-mounted units with turn-by-turn routing and traffic integration. Fleet operators in São Paulo and Bangalore deploy these at scale for last-mile delivery optimization where cellular coverage exceeds smartphone mounting reliability.
- Connectivity Modules:Telematics hardware enabling stolen-vehicle tracking and remote diagnostics.
- Smartphone Apps:Software platforms pairing with onboard hardware for ride analytics and community features.
Connectivity Modules sits at the top of the volume ranking, with Smart Helmets climbing the fastest.
Technology:
Cost tiers separate legacy short-range protocols from emerging cellular and direct-vehicle architectures that command premium pricing.
- Bluetooth:Low-energy pairing for helmet-to-phone audio and basic telemetry exchange. Individual riders in Vietnam and Brazil still favor this protocol for aftermarket retrofit where device cost sensitivity dominates purchasing decisions.
- Cellular:LTE and 5G modules enabling real-time cloud connectivity and over-the-air updates. Fleet operators in India mandate AIS-140 compliant cellular telematics for commercial two-wheeler registration renewal.
- Wi-Fi:Local area networking for garage-based diagnostics and firmware updates.
- V2X Communication:Dedicated short-range communication at 5.9 GHz for cooperative intelligent transport.
Bluetooth retains the largest installed base, though V2X Communication gains share fastest as EU safety mandates advance.
End User:
Customer type determines procurement scale and recurring revenue potential, with commercial operators unbundling hardware from software contracts.
- Fleet Operators:Ride-sharing and delivery cooperatives purchasing connectivity in bulk with SaaS analytics subscriptions. Zomato and Swiggy procurement teams in India negotiate device volumes separately from cloud platform licenses.
- Ride-Sharing Services:Platform-mediated mobility providers requiring driver monitoring and passenger safety verification. Grab and Gojek specifications in Vietnam drive regional hardware standardization.
- Individual Riders:Consumer purchasers selecting connectivity for theft recovery and navigation convenience.
- Commercial Users:Corporate and government fleet managers with duty-of-care compliance obligations.
Fleet Operators dominate procurement volumes, while Ride-Sharing Services show the steepest expansion trajectory.
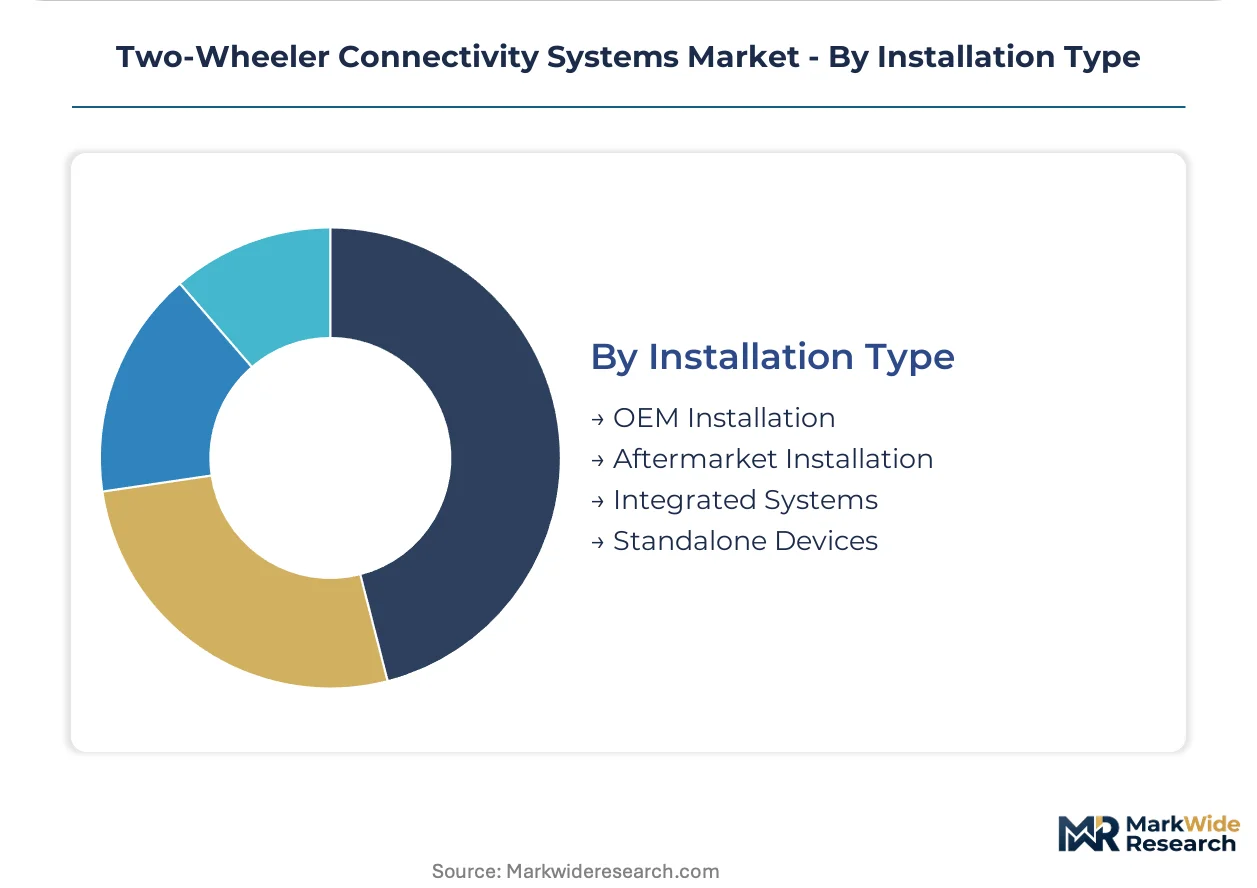
Installation Type:
Supply concentration clusters around tier-1 automotive suppliers for OEM channels, while aftermarket distribution fragments across electronics retailers and service garages.
- OEM Installation:Factory-integrated connectivity specified during motorcycle assembly. Robert Bosch GmbH and Continental AG anchor European and Asian motorcycle brand supply chains through multi-year platform contracts.
- Aftermarket Installation:Retrofit modules installed post-purchase through dealer networks or independent garages. Ho Chi Minh City and Hanoi service corridors concentrate Vietnam's highest installation density.
- Integrated Systems:Connectivity embedded within instrument clusters and vehicle electronics architectures.
- Standalone Devices:Self-contained units with independent power and mounting systems.
Aftermarket Installation leads current volumes, with OEM Installation expanding most quickly as premium motorcycle brands standardize connectivity platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates aftermarket installation volumes while Germany anchors premium OEM integration pipelines, with both markets diverging sharply in regulatory drivers and supplier qualification requirements.
India
Fleet operators and ride-sharing cooperatives drive bulk procurement of cellular telematics modules. The Ministry of Road Transport and Highways enforces AIS-140 compliance for commercial two-wheeler registration renewal. Bangalore and Mumbai logistics corridors concentrate the highest density of retrofit connectivity installations for last-mile delivery optimization.
Germany
Premium motorcycle OEMs specify factory-integrated connectivity platforms through multi-year supplier contracts. The F-Gas Regulation and CE marking requirements shape electromagnetic compatibility and thermal management standards for connectivity hardware. Bavaria-based tier-1 automotive suppliers anchor European motorcycle brand supply chains with established compliance track records.
United States
The National Highway Traffic Safety Administration evaluates V2X communication protocols for motorcycle integration under broader intelligent transportation system roadmaps. California and Texas metropolitan areas concentrate early-adopter demand for connected safety systems among premium motorcycle owners. FCC spectrum allocation decisions at 5.9 GHz directly impact DSRC deployment timelines for cooperative intelligent transport.
Brazil
Urban congestion in São Paulo accelerates aftermarket adoption of GPS navigation devices and stolen-vehicle tracking modules. ANVISA and national telecommunications regulators shape device certification requirements for cellular-connected automotive electronics. São Paulo state service corridors concentrate the highest installation density of retrofit connectivity modules for fleet and individual riders.
Vietnam
Motorcycle density in Hanoi and Ho Chi Minh City outpaces integrated OEM adoption, creating white space for retrofit connectivity vendors. The national transport ministry advances commercial vehicle telematics frameworks aligned with regional intelligent transport initiatives. Ho Chi Minh City service corridors concentrate Vietnam's highest aftermarket installation activity for Bluetooth and cellular connectivity modules.
Two-Wheeler Connectivity Systems Market Competitive Landscape
Top-tier vendors anchor OEM installation pipelines through multi-year platform contracts, while mid-tier specialists compete for aftermarket retrofit volumes and fleet SaaS contracts. Tier-1 automotive suppliers leverage established electromagnetic compatibility and thermal management expertise to qualify for premium motorcycle brand specifications. Strategic archetypes include automotive electronics conglomerates, semiconductor specialists, and dedicated telematics platform providers. Competitive moves concentrate on geographic expansion into high-density motorcycle markets and portfolio diversification across Bluetooth-to-cellular-to-V2X technology stacks.
Within the tier-1 automotive electronics tier, Robert Bosch GmbH and Continental AG exemplify vendors with established OEM installation pipelines and compliance track records under European regulatory frameworks. NXP Semiconductors occupies a position among semiconductor specialists providing automotive-grade connectivity chipsets that power both embedded modules and smart helmet architectures. These three entities represent the dominant competitive archetypes shaping supplier qualification timelines and technology roadmap convergence across premium and commercial segments.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Autotalks Ltd |
| Robert Bosch GmbH |
| Aeris Communications |
| KPIT Technologies Limited |
| Continental AG |
| Panasonic Corporation |
| Starcom Systems Ltd |
| TE Connectivity |
| Others |
Value Network & Pricing Analysis
Automotive-grade silicon wafer pricing indices cascade through two-wheeler connectivity supply chains, compressing margins on cellular modules while amplifying differentiation premiums for V2X-compliant architectures in European and Indian procurement pipelines.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for Bluetooth retrofit modules, yet 5G-V2X chipsets retain premium positioning due to TSMC fabrication constraints. Three-tier pricing structure across premium, standard, and economy levels separates AIS-140 certified cellular telematics from basic GPS trackers. Cost compression in economy-tier Bluetooth devices is intensifying because of unbranded Shenzhen assembly capacity. Fleet operators exhibit lowest price sensitivity due to SaaS bundling, while individual riders in Brazil and Vietnam drive hard bargaining on standalone hardware.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries supplying automotive-grade 5G modems and V2X chipsets to tier-1 module integrators. Manufacturing concentrates in China, Taiwan, and South Korea for semiconductor fabrication, with final assembly clustering in Vietnam and India for cost arbitrage. Raw material dependencies span silicon wafers, gallium arsenide substrates, and rare-earth magnet components for antenna assemblies. Tariff exposure on Chinese electronics imports into India and Brazil elevates landed cost volatility. Distribution runs through tier-1 automotive supplier networks for OEM channels, while aftermarket flows fragment across electronics retailers and service garages in Ho Chi Minh City, São Paulo, and Bangalore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI scheme for automotive electronics offers 4-6 percentage point cost advantages against ASEAN assembly, while EU F-Gas compliance burdens inflate European hardware qualification timelines relative to Asian certification pathways.
For Market Incumbents: Cement tier-1 automotive relationships through multi-year platform contracts with European and Japanese motorcycle OEMs before V2X mandates harden supplier qualification timelines. Deepen backward integration into automotive-grade chipset sourcing to offset TSMC allocation constraints. Defend against mid-tier telematics specialists by locking fleet SaaS contracts with exclusive data-analytics bundling. For New Entrants and Emerging Players: AIS-140 compliance push in India opens a window for domestic assembly of cellular telematics modules serving Swiggy and Zomato delivery cooperatives. Target Vietnam's aftermarket retrofit corridor where motorcycle density outpaces integrated OEM adoption. Pursue white-label manufacturing partnerships with Ho Chi Minh City service garages as the primary go-to-market channel. For Investors and Strategic Acquirers: Consolidation pressure builds where cybersecurity engineering talent scarcity constrains over-the-air update architecture development. Frame long-term viability around 5G-V2X convergence timelines and regulatory mandate acceleration across EU and Indian commercial vehicle frameworks. Target acquisition archetype: mid-tier telematics platform providers with established AIS-140 certification and recurring SaaS revenue bases. Watch NHTSA V2X protocol finalization as the inflection signal for US market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| 5G-V2X Dual-Mode Module Development | EU cooperative intelligent transport mandates accelerate DSRC-cellular hybrid adoption timelines. |
| AIS-140 Certification Fast-Track | India's Ministry of Road Transport compliance deadlines create first-mover registration advantages. |
| Cybersecurity Engineering Acquisition | Embedded systems security expertise scarcity constrains over-the-air update roadmap execution. |
| Vietnam Aftermarket Distribution Partnership | Ho Chi Minh City service corridor density outpaces OEM integrated system penetration rates. |
| PLI Scheme Manufacturing Localization | Indian production-linked incentives reduce import dependency for cellular modem assembly. |
Research Methodology
Multiple input streams — primary interviews with tier-1 supplier procurement heads, fleet telematics platform directors, and automotive semiconductor product managers; secondary validation through vehicle production databases, AIS-140 compliance registries, and FCC spectrum allocation filings; plus customs trade data on cellular module imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment volumes were cross-referenced against panel input from connectivity module manufacturers and ride-sharing fleet operators to anchor baseline assumptions. Segmentation modeling spanned product type, communication technology, end-user archetype, and installation channel across the projection horizon. CAGRs were derived from installed base penetration curves and replacement cycle analysis, with fleet telematics contract values and consumer aftermarket retrofit frequencies serving as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden 5G spectrum reallocation decisions or accelerated V2X mandate implementation. Forecasts reflect documented assumptions on regulatory timeline adherence and semiconductor foundry capacity expansion plans. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Saudi Arabia Automotive Sensors Market
Automotive Electronics & Wiring
Germany Automotive Camera Market
Automotive Electronics & Wiring
Inertial Systems in Transportation Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Global Automotive Holographic Display Market
Automotive Electronics & Wiring
Surround View System Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Germany Automotive Relay Market
Automotive Electronics & Wiring
Car Digital Video Recorder (DVR) Market
Automotive Electronics & Wiring
Portable Automotive Wi-Fi Router Market