
 India Connected Car Market | 2026-2036
India Connected Car Market Size, Share, and Industry Trends Forecast 2026-2036
India Connected Car Market Outlook
Tamil Nadu's automotive electronics manufacturing base is recalibrating output to serve embedded connectivity modules for domestic OEMs. Tata Motors leverages in-house software development to control telematics architecture across its passenger and commercial portfolios. Maruti Suzuki anchors volume deployment through its widespread dealership network, while Hyundai Motor India differentiates via over-the-air update capabilities integrated at the factory level.
Connected cars integrate cellular modems, GPS receivers, and onboard diagnostic systems to enable real-time data exchange between vehicles, infrastructure, and cloud platforms. The technology relies on embedded SIM technology operating across 4G and emerging 5G networks to transmit telemetry on engine health, location, and driver behavior to centralized fleet dashboards. Passenger cars currently occupy the largest product type segment due to rising consumer expectations for smartphone-integrated infotainment and remote diagnostics. Fleet management applications within the end-user category represent the fastest-expanding demand pool, as logistics companies adopt V2X communication protocols to reduce idle time and accident rates across highway corridors.
BIS certification requirements for automotive electronics and TRAI regulations governing spectrum allocation for connected vehicle services shape product design cycles and market entry timelines. The Ministry of Road Transport and Highways enforces AIS-140 compliance for public transport and commercial fleets, mandating GPS connectivity and emergency response buttons. Stakeholders must monitor evolving MEE guidelines on e-waste disposal for connected hardware and anticipate how CEA standards for electric vehicle charging infrastructure will intersect with telematics data streams as the EV product type segment matures.
Market Dynamics
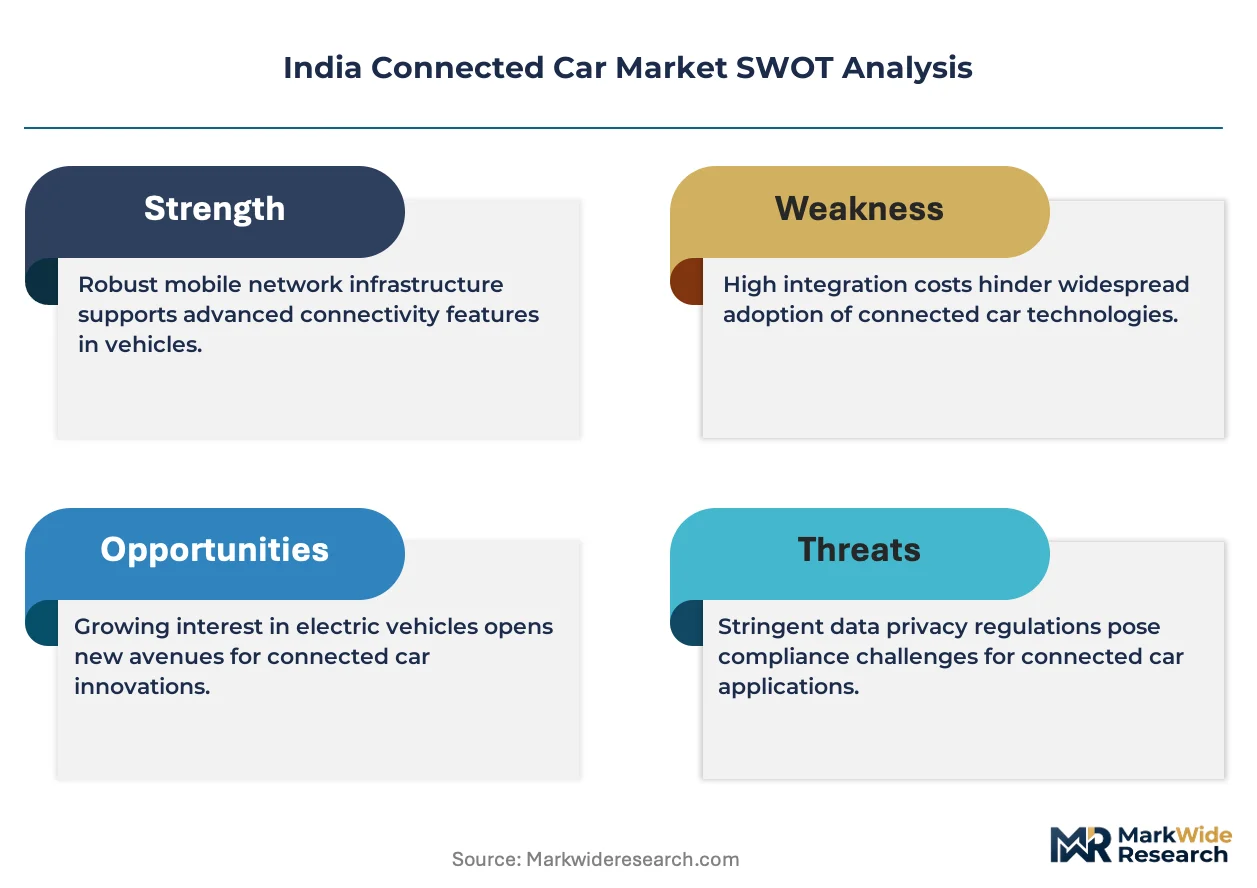
AIS-140 compliance deadlines are compressing deployment timelines across commercial fleets, forcing rapid integration of GPS-enabled telematics hardware into vehicles that previously operated without connectivity infrastructure.
Growth Catalysts
- Telematics hardware:Embedded cellular modems and GPS receivers are becoming standard fitment in new vehicle production lines across passenger and commercial categories.
- Fleet management demand:Logistics operators in Maharashtra, Gujarat, and Tamil Nadu are mandating real-time route optimization and fuel monitoring systems to reduce operational leakage.
- AIS-140 mandate:The Ministry of Road Transport and Highways requires GPS connectivity and emergency response buttons in all public transport and commercial vehicles, creating compulsory replacement cycles.
Market Restraints
- Semiconductor supply concentration:Dependence on imported cellular modem chipsets exposes domestic module assemblers to allocation constraints from East Asian foundries.
- Spectrum allocation uncertainty:TRAI deliberations on dedicated connected vehicle frequency bands delay product certification cycles and lock in 4G architectures.
- Aftermarket installation costs:Retrofitting AIS-140 hardware into existing commercial fleets requires specialized labor and vehicle downtime that owner-operators resist absorbing.
Strategic Opportunities
- EV-telematics convergence:CEA standards for electric vehicle charging infrastructure will intersect with battery health monitoring data streams, creating unified platform requirements.
- Tier-2 city penetration:Connected service demand from logistics corridors in Karnataka, Telangana, and Haryana remains underdeveloped relative to established manufacturing clusters.
- Over-the-air revenue models:Software update capabilities embedded at factory level enable recurring service architectures that hardware-centric competitors cannot replicate.
Industry Challenges
- Embedded systems engineering talent:Shortage of firmware developers capable of integrating V2X protocols with legacy vehicle bus architectures constrains OEM in-house development.
- BIS certification timelines:Automotive electronics testing queues at accredited laboratories extend product launch schedules by quarters.
- Multi-standard interoperability:Fragmentation between cellular V2X and DSRC communication protocols forces module suppliers to support redundant hardware configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Connected Car Market |
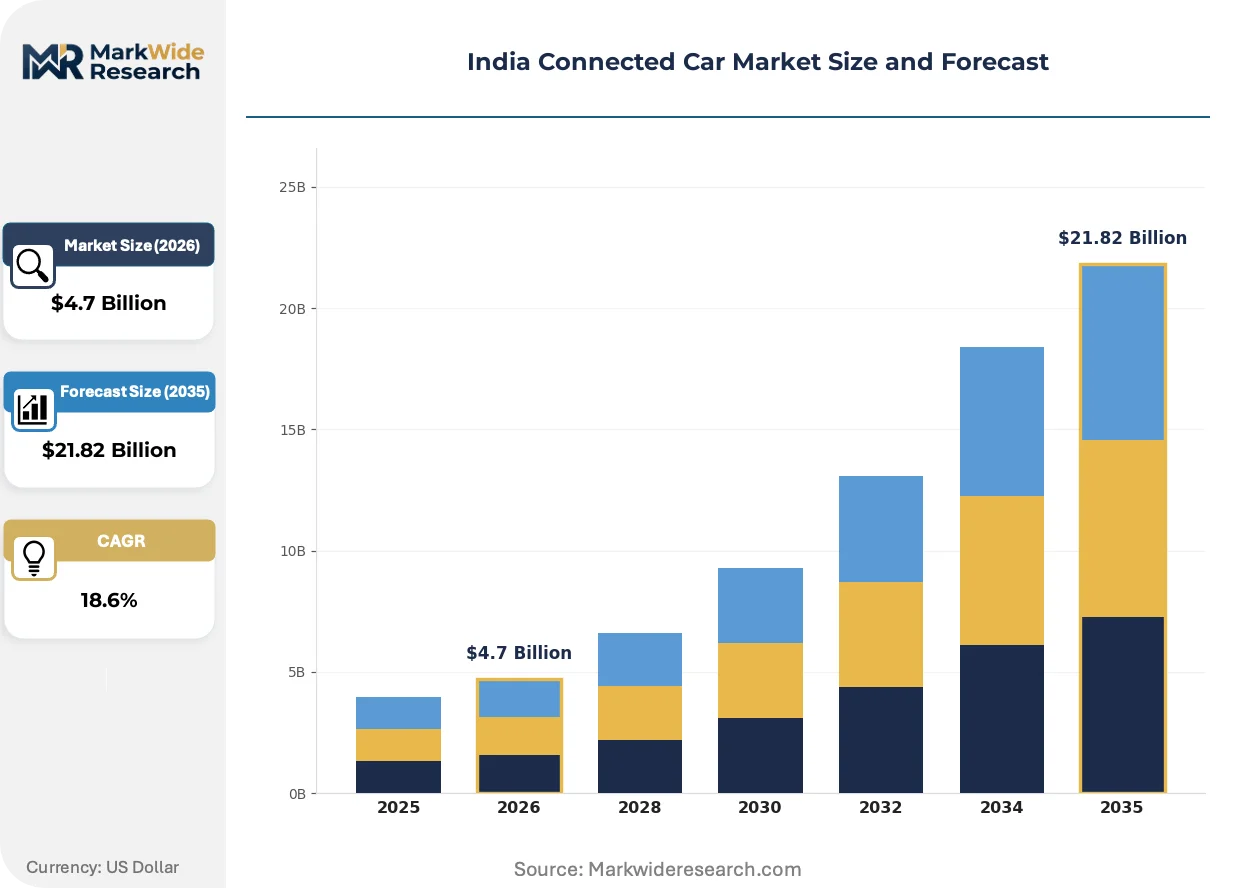
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Technology: Telematics, V2X Communication, Cloud Computing, In-Car Infotainment End User: Fleet Operators, Individual Consumers, Automotive OEMs, Insurance Providers Application: Fleet Management, Navigation, Safety & Security, Entertainment |
| Companies Covered | Mahindra & Mahindra, JSW MG Motor India, Maruti Suzuki India, Toyota Motor Corporation, BMW Group India, Hyundai Motor India, Kia India, BYD, Tata Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Connected Car Market Strategic Shifts
Cellular connectivity architectures are displacing tethered smartphone dependencies, while regulatory data mandates and fleet digitization are rewriting competitive requirements for domestic OEMs and tier-1 suppliers.
5G-ready embedded SIM technology is rewriting how vehicles transmit telemetry. The modules enable continuous engine health, location, and driver behavior data streams to centralized cloud platforms without driver intervention. Fleet operators in highway logistics corridors are adopting these systems fastest, compressing the competitive window for aftermarket retrofit solutions.
TRAI spectrum allocation frameworks for dedicated connected vehicle services are reshaping hardware design cycles. Manufacturers must pre-certify modules for frequency bands not yet commercially deployed, locking capital in inventory with uncertain activation timelines. Passenger car OEMs with integrated R&D capabilities are absorbing this uncertainty better than tier-1 module suppliers dependent on external chipset roadmaps.
Logistics procurement teams now require V2X-enabled vehicles as a contractual condition for fleet operators serving their contracts. The specification is displacing price-only tender evaluation in long-haul trucking and last-mile delivery segments. Tamil Nadu and Gujarat-based fleet owners are responding fastest, using the capability to differentiate in contract bids against unconnected competitors.
India Connected Car Market Segmentation
Segmentation in the India Connected Car Market reveals distinct capital allocation patterns across hardware-intensive and software-centric categories. OEMs and suppliers configure product portfolios differently depending on whether the revenue model depends on embedded electronics, recurring service fees, or one-time hardware sales.
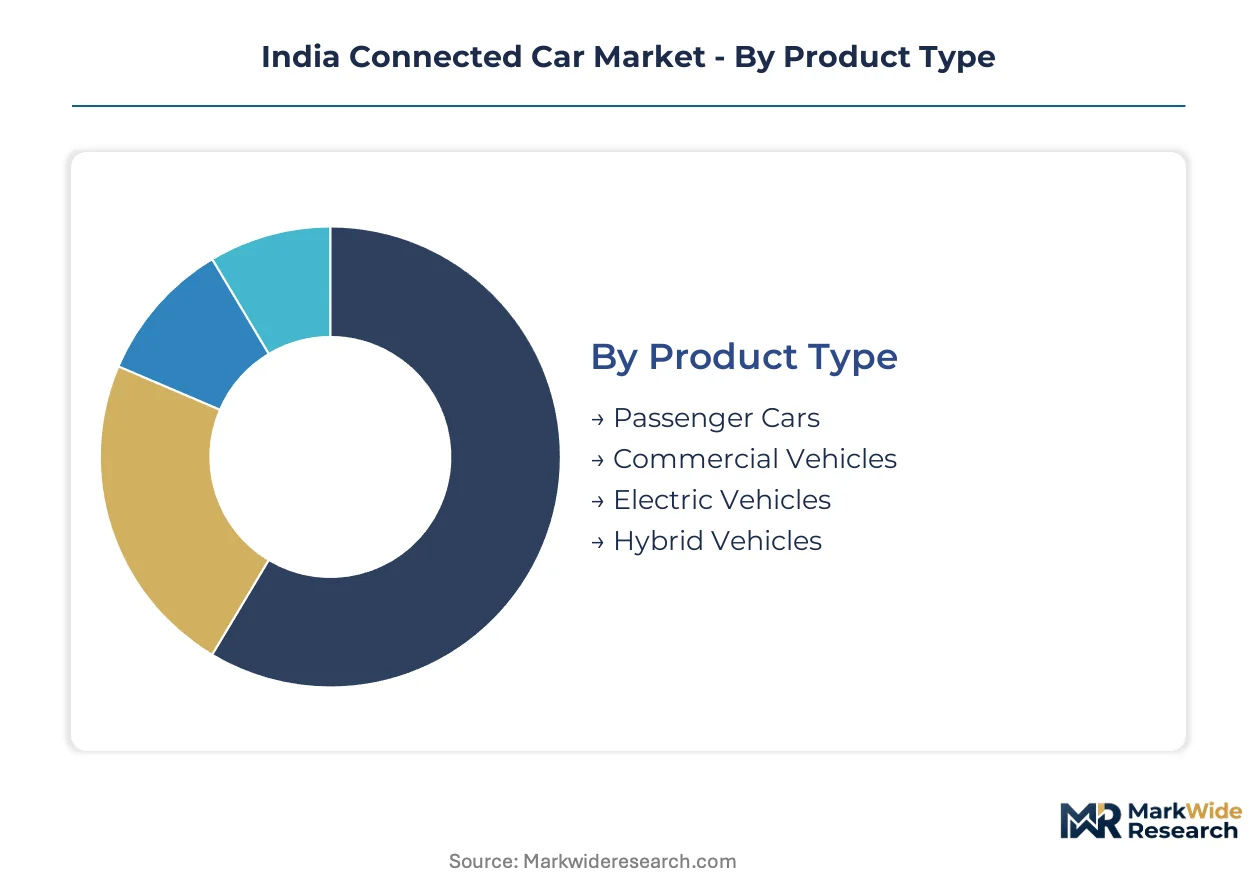
Product Type:
Embedded connectivity modules require substantial upfront investment in semiconductor sourcing, thermal management, and vehicle bus integration, with capital intensity varying sharply across powertrain architectures.
- Passenger Cars:Cellular modems, GPS receivers, and onboard diagnostic systems integrate into centralized infotainment head units. Maharashtra and Tamil Nadu manufacturing clusters absorb the highest deployment volumes as domestic OEMs embed connectivity at the factory level to meet consumer expectations for smartphone-integrated services.
- Commercial Vehicles:AIS-140 mandate compliance drives compulsory GPS and emergency button installation across public transport and freight fleets. Retrofit hardware costs and vehicle downtime create resistance among owner-operators, compressing margins for aftermarket suppliers relative to factory-fit solutions.
- Electric Vehicles:Battery health monitoring and charging infrastructure telemetry demand unified platform architectures under evolving CEA standards.
- Hybrid Vehicles:Dual powertrain complexity necessitates sophisticated engine control unit integration with connectivity modules.
Most installed capacity flows through Passenger Cars. Expansion is steepest in Electric Vehicles.
Technology:
Technology segments diverge by R&D burn rate, with protocol development and cloud infrastructure demanding sustained engineering investment versus mature hardware integration.
- Telematics:Engine health, location, and driver behavior data streams transmit via 4G and emerging 5G embedded SIM technology to centralized fleet dashboards. Fleet operators in Gujarat logistics corridors mandate these systems fastest, displacing tethered smartphone dependencies.
- V2X Communication:Vehicle-to-everything protocols reduce idle time and accident rates across highway corridors. Fragmentation between cellular V2X and DSRC standards forces module suppliers to support redundant hardware configurations, elevating engineering costs.
- Cloud Computing:Over-the-air update capabilities enable recurring service architectures that hardware-centric competitors cannot replicate.
- In-Car Infotainment:Consumer-facing interfaces integrate smartphone mirroring and voice assistance with lower marginal hardware cost.
Revenue concentration sits with Telematics. Capability investment is climbing fastest in V2X Communication.
End User:
End user segments separate by procurement scale and contract structure, with enterprise fleet purchasing creating volume concentration unavailable in fragmented consumer markets.
- Fleet Operators:Real-time route optimization and fuel monitoring systems reduce operational leakage for logistics companies serving long-haul trucking and last-mile delivery contracts. Procurement teams now require V2X-enabled vehicles as a contractual condition, displacing price-only tender evaluation.
- Individual Consumers:Remote diagnostics and infotainment integration drive replacement demand in premium and mid-tier vehicle segments. Dealership networks anchor volume deployment through point-of-sale activation.
- Automotive OEMs:In-house software development controls telematics architecture across passenger and commercial portfolios.
- Insurance Providers:Usage-based pricing models leverage driver behavior telemetry from connected vehicle data streams.
Procurement volume concentrates with Fleet Operators. Policy innovation is expanding fastest among Insurance Providers.
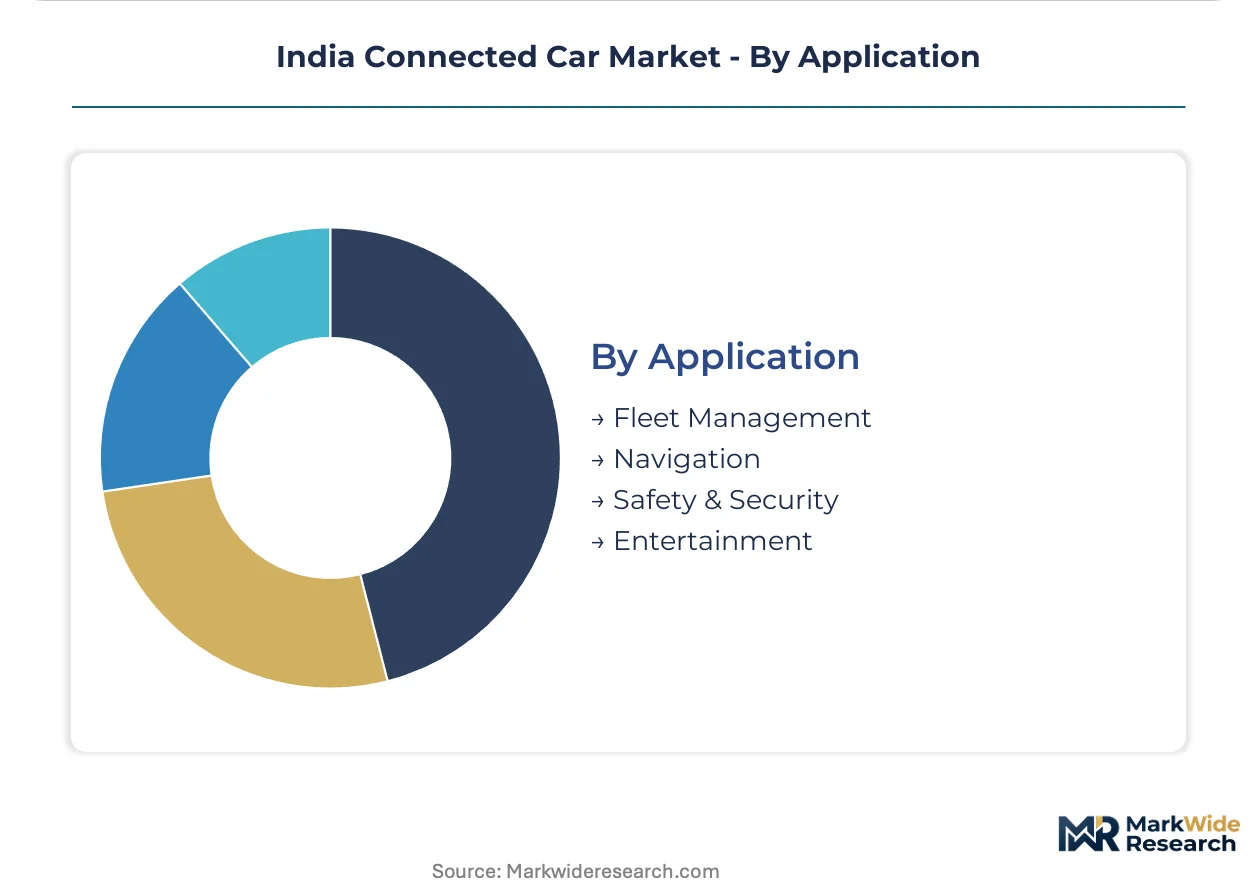
Application:
Application segments map directly to regulatory compliance requirements and operational efficiency targets, with safety mandates creating non-discretionary demand distinct from discretionary entertainment spending.
- Fleet Management:Telemetry on engine health, location, and driver behavior enables centralized dashboard control for logistics operators. Karnataka and Telangana corridors remain underdeveloped relative to established manufacturing clusters, presenting expansion opportunity.
- Safety & Security:AIS-140 GPS connectivity and emergency response buttons are mandatory for public transport and commercial vehicles under Ministry of Road Transport and Highways enforcement.
- Navigation:Real-time traffic integration and predictive routing leverage cellular data connectivity.
- Entertainment:Streaming audio and video services compete with smartphone-native applications for consumer attention.
Regulatory obligation secures Safety & Security. Value-added service growth is strongest in Fleet Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics concentrate connected car module assembly in states where BIS certification timelines and state-level EV incentives create cost-of-compliance advantages over neighboring jurisdictions.
Maharashtra
Pune and Mumbai automotive corridors drive embedded connectivity module demand as Tata Motors and Mahindra & Mahindra integrate factory-fit telematics. The state's Industrial Policy offers capital subsidies for electronics manufacturing units serving automotive OEMs. Chakan and Talegaon industrial zones host tier-1 suppliers recalibrating output for domestic OEM embedded systems.
Tamil Nadu
Chennai's automotive electronics manufacturing base supplies connectivity hardware to Hyundai Motor India and Kia India production lines. The Tamil Nadu EV Policy mandates telematics integration in state-procured electric buses under MTC fleet modernization. Sriperumbudur and Oragadam industrial belts concentrate semiconductor packaging operations for cellular modem chipsets.
Gujarat
Sanand and Halol logistics corridors generate fleet operator demand for AIS-140 compliant GPS tracking and emergency response systems. The Gujarat Electronics Policy provides GST reimbursement for automotive electronics manufacturing investments. Mundra and Hazira port zones anchor aftermarket telematics hardware distribution networks serving western India freight operators.
Karnataka
Bengaluru's software engineering talent pool supports V2X protocol development and cloud platform architectures for connected vehicle services. The Karnataka EV Policy requires battery health monitoring telemetry in state-registered electric commercial vehicles. Electronic City and Whitefield technology parks host firmware development centers serving domestic OEM telematics programs.
Haryana
Gurugram and Manesar manufacturing clusters produce infotainment head units with integrated cellular connectivity for Maruti Suzuki India. The Haryana EV Policy mandates GPS tracking in state-subsidized electric three-wheelers under last-mile delivery schemes. IMT Manesar hosts tier-1 electronics suppliers serving NCR-based passenger car OEMs.
India Connected Car Market Competitive Environment
Domestic OEMs anchor one tier through in-house software development; international joint ventures hold differentiated positions via global technology transfer. The market structures around three archetypes: vertically integrated domestic manufacturers controlling telematics architecture, international OEMs leveraging parent-company connectivity platforms, and emerging EV specialists capturing battery-telemetry convergence opportunities. Competitive moves center on factory-level OTA capability deployment and AIS-140 compliance acceleration for commercial fleet contracts.
Within the domestic integrated tier, Tata Motors and Mahindra & Mahindra exemplify in-house telematics control across passenger and commercial portfolios. Maruti Suzuki occupies a volume-leadership position through dealership network penetration, while Hyundai Motor India represents the international joint venture archetype with factory-embedded update capabilities. JSW MG Motor India and BYD illustrate the emerging EV specialist pattern converging battery monitoring with connectivity platforms.
| Leading Market Players |
|---|
| Mahindra & Mahindra |
| JSW MG Motor India |
| Maruti Suzuki India |
| Toyota Motor Corporation |
| BMW Group India |
| Hyundai Motor India |
| Kia India |
| BYD |
| Tata Motors |
| Others |
Value Chain & Pricing Dynamics
Cellular modem chipset pricing indices from East Asian foundries cascade through module assembly tiers, compressing margins for domestic assemblers while OEMs with captive software development absorb component volatility through subscription revenue architectures.
Pricing Analysis
Distributor margins for aftermarket AIS-140 hardware compress under fleet operator procurement consolidation, while factory-fit telematics command premium positioning through embedded software licensing. Three-tier pricing structure across premium OTA-enabled, standard connected, and economy retrofit levels separates OEM-integrated systems from tier-1 module suppliers. Price differentiation hinges on BIS certification grade and volume scale in state fleet tenders. Pricing pressure stems from semiconductor allocation constraints, with owner-operators in Gujarat and Maharashtra corridors exhibiting highest price sensitivity due to retrofit downtime costs.
Supply Chain Analysis
Cellular modem supply rests on Taiwanese and South Korean semiconductor foundries, with GPS receiver chipsets drawing from Chinese and Japanese specialty component manufacturers. Embedded SIM substrates and thermal management materials feed from German and Japanese precision suppliers. Single-source vulnerability concentrates in 5G-ready modem architectures where TRAI spectrum uncertainty locks capital in pre-certified inventory. Distribution runs through Tamil Nadu and Maharashtra electronics manufacturing clusters to OEM assembly lines, with aftermarket channels serving western India freight corridors via Gujarat port zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Connected Car Market represents a late-cycle quality story as fleet procurement shifts toward V2X-enabled vehicles with factory-embedded update capabilities, displacing price-only tender evaluation.
For Market Incumbents: Lock in AIS-140 compliance acceleration through backward integration into GPS module firmware development, defending against emerging EV specialists converging battery telemetry with connectivity platforms. Channel control through dealership network activation anchors volume deployment against aftermarket retrofit competitors. Certification investment in pre-5G module architectures preserves optionality pending TRAI spectrum allocation clarity. For New Entrants and Emerging Players: Begin with Karnataka and Telangana logistics corridors where connected service penetration lags established manufacturing clusters, targeting tier-2 fleet operators with V2X-enabled vehicle procurement mandates. White-space exists in battery health monitoring telemetry for electric commercial vehicles under evolving CEA standards. Go-to-market angle emphasizes unified platform architectures integrating charging infrastructure data streams. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware development capability scarcity constrains OEM in-house telematics programs. Long-term viability favors vertically integrated domestic manufacturers controlling software-defined vehicle architectures over hardware-centric module assemblers. Acquisition target archetype: tier-1 suppliers with embedded systems engineering talent and BIS certification track records. Signal to watch: MEE e-waste disposal guideline enforcement accelerating hardware replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | OTA update capabilities enable recurring revenue models that hardware competitors cannot replicate. |
| Battery Supply Agreement | CEA standards for EV charging infrastructure intersect with telematics data streams, creating unified platform requirements. |
| Platform Standardization | AIS-140 mandate compliance across passenger and commercial portfolios reduces certification redundancy. |
| Geographic Manufacturing Footprint | Tamil Nadu and Maharashtra electronics clusters concentrate semiconductor packaging for cellular modem production. |
| Charging Infrastructure Partnership | CEA standards alignment positions connectivity providers for EV-telematics convergence opportunities. |
Study Parameters
Direct dialogue with OEM platform engineers, tier-1 supplier procurement leads, fleet operator logistics directors, and TRAI regulatory affairs specialists grounded qualitative assessment, cross-referenced with BIS certification databases, Ministry of Road Transport and Highways enforcement circulars, state EV policy documents, and vehicle production registration data. Bottom-up and top-down triangulation validated segment-level assumptions across the analysis window.
Bottom-up modeling aggregated content-per-vehicle trajectories by propulsion architecture and OEM tier, while top-down analysis calibrated against state-level fleet procurement mandates and AIS-140 compliance timelines. Segmentation dimensions spanned vehicle class, connectivity technology generation, end-user procurement scale, and regional manufacturing cluster concentration. CAGRs derived from installed base penetration curves and replacement cycle compression under regulatory deadlines, incorporating semiconductor supply allocation scenarios and spectrum deployment uncertainty.
Several conditions sit outside the modeled scope, including TRAI frequency band allocation timing, MEE e-waste enforcement intensity, and CEA standard finalization for EV charging telemetry integration. Forecasts reflect documented assumptions regarding AIS-140 compliance adherence rates and logistics operator digitization cadence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
North America Automotive Infotainment System Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Next Generation in-Vehicle Networking (IVN) Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Motor Racing Telematics Market