
 Inertial Systems in Transportation Market | 2026-2036
Inertial Systems in Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Inertial Systems in Transportation Market Insights
MEMS-based inertial measurement is fragmenting across multiple performance tiers as foundries scale production of low-cost sensors for commercial transportation. Honeywell International Inc. leverages its aerospace heritage to dominate high-reliability fiber optic gyroscope supply for maritime and aviation applications. Safran Electronics & Defense anchors European defense and rail markets through tightly integrated navigation suites. VectorNav Technologies LLC specializes in compact MEMS IMUs that compete aggressively for autonomous vehicle and drone platform design wins.
Inertial systems in transportation comprise gyroscopes, accelerometers, and integrated IMUs that measure angular rate and linear acceleration to determine position, velocity, and attitude without external references. These systems rely on Coriolis effect detection in MEMS structures or Sagnac interference in optical fibers, achieving drift rates from degrees per hour in tactical grades to thousandths of a degree in navigation grades for precise vehicle localization. IMUs and MEMS sensors capture expanding volume as automotive OEMs adopt them for advanced driver assistance and autonomous navigation, while fiber optic gyroscopes retain premium positioning in aerospacecraft and maritime vessels where GPS denial resilience commands priority. Quantum sensing approaches are emerging from research institutions but remain outside commercial transportation deployment timelines.
FAA airworthiness standards shape aerospacecraft sensor certification timelines and testing burdens, while U.S. DOT automated vehicle guidance imposes functional safety expectations on IMU suppliers to autonomous trucking platforms. EU Green Deal emissions targets and CSRD disclosure rules indirectly pressure fleet operators to adopt precise inertial routing for fuel optimization across commercial trucks and rail networks. Stakeholders must monitor how quantum inertial prototypes transition from laboratory demonstration to transportation-qualified production as defense funding flows toward dual-use navigation applications.
Market Dynamics
MEMS fabrication scaling is compressing sensor costs while autonomous vehicle fleets multiply sensor counts per platform, creating a volume-price tension that rewards foundries with automotive qualification experience.
Growth Catalysts
- FAA airworthiness certification pathways:Streamlined validation protocols for integrated navigation suites accelerate deployment timelines in commercial aerospacecraft retrofit programs.
- Germany's automotive manufacturing corridor:OEM platform integration mandates for advanced driver assistance systems pull tactical-grade IMUs into production vehicle lines at scale.
- Coriolis-effect MEMS structures:Foundry process improvements enable six-axis inertial measurement in packages under 10 cubic centimeters for drone navigation.
Market Restraints
- Optical-grade fiber coil supply:Specialized wound fiber for FOG gyros concentrates among Japanese and US specialty manufacturers, creating single-source vulnerability.
- Navigation-grade drift specifications:Ring laser gyroscopes and quantum prototypes face thousand-fold performance gaps versus operational requirements for submarine inertial navigation.
- EU CSRD disclosure rules:Supply chain traceability mandates impose documentation burdens on MEMS foundries serving European rail and commercial vehicle OEMs.
Strategic Opportunities
- Indian commercial trucking retrofit:Fleet operators under Bureau of Indian Standards fuel efficiency norms seek low-cost inertial routing for highway optimization.
- Quantum atom interferometry convergence:Cold-atom inertial sensors paired with photonic integrated circuits promise GPS-denied navigation for defense-to-civil technology transfer.
- Direct OEM contracting:Autonomous vehicle developers bypass traditional tier-one distributors to negotiate multi-year MEMS IMU supply agreements with foundries.
Industry Challenges
- Silicon photonics packaging expertise:FOG manufacturers competing with MEMS entrants face acute shortages of fiber-to-chip alignment specialists.
- ISO 26262 functional safety certification:Automotive IMU suppliers endure 18-24 month validation cycles for ASIL-D qualification against hardware failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inertial Systems in Transportation Market |
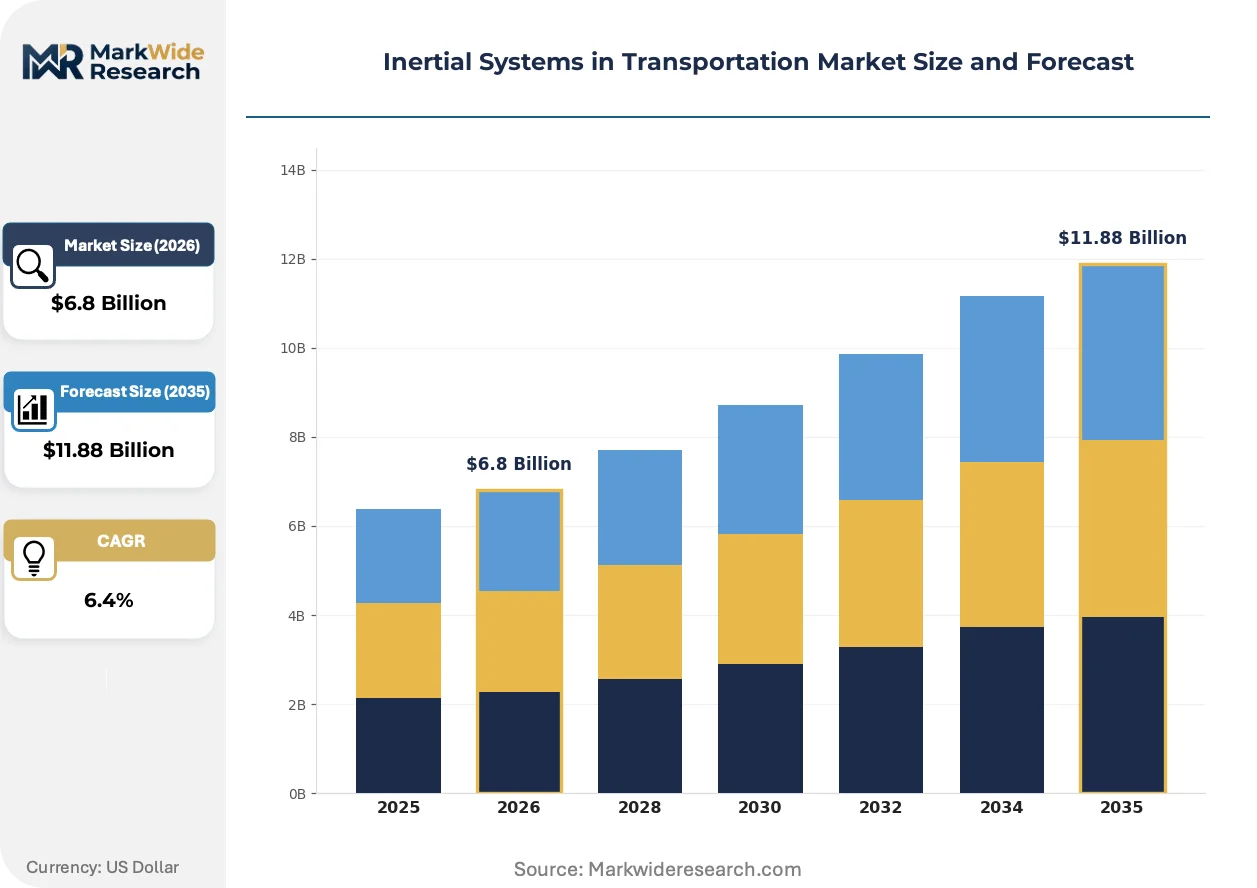
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gyroscopes, Accelerometers, IMUs, Fibre Optic Gyroscopes, Ring Laser Gyroscopes, MEMS Sensors Transportation Mode: Rail, Maritime Vessels, Aerospacecraft, Commercial Trucks, Autonomous Vehicles, Delivery Drones Technology: Mechanical, Optical, MEMS, Quantum, Hybrid, Electromechanical End User: OEMs, Tier-1 Suppliers, Fleet Operators, Logistics Companies, Research Institutions, Public Transit Authorities |
| Companies Covered | Honeywell International Inc., Northrop Grumman Corporation, Safran Electronics & Defense, Thales Group, Collins Aerospace, Teledyne Technologies Incorporated, L3Harris Technologies Inc., VectorNav Technologies LLC, Gladiator Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inertial Systems in Transportation Market Trends and Innovations
Sensor fusion architectures are redefining value capture in navigation systems, with software compensation algorithms eroding the premium historically commanded by hardware precision alone.
Photonic integrated circuits are digitizing inertial measurement by embedding Sagnac interferometers on silicon substrates. Maritime gyrocompass manufacturers adopt these devices for satellite-denied heading reference. The technology is digitizing supply chain economics by collapsing optical alignment labor into semiconductor batch processing.
EU AI Act risk classification rules now capture autonomous vehicle perception systems that incorporate inertial data for localization validation. Tier-one suppliers restructure product architectures to isolate safety-critical IMU outputs from AI-driven decision layers. German KBA type-approval processes are adapting to verify this separation in production vehicle platforms.
Fleet operators now unbundle sensor procurement from system integrator contracts, negotiating direct volume agreements with MEMS foundries for standardized IMU modules. Traditional navigation system houses respond by repositioning around software calibration and fusion algorithms. This pattern is most visible in US autonomous trucking corridors where Werner, Schneider, and J.B. Hunt operate pilot programs.
Inertial Systems in Transportation Market Segmentation
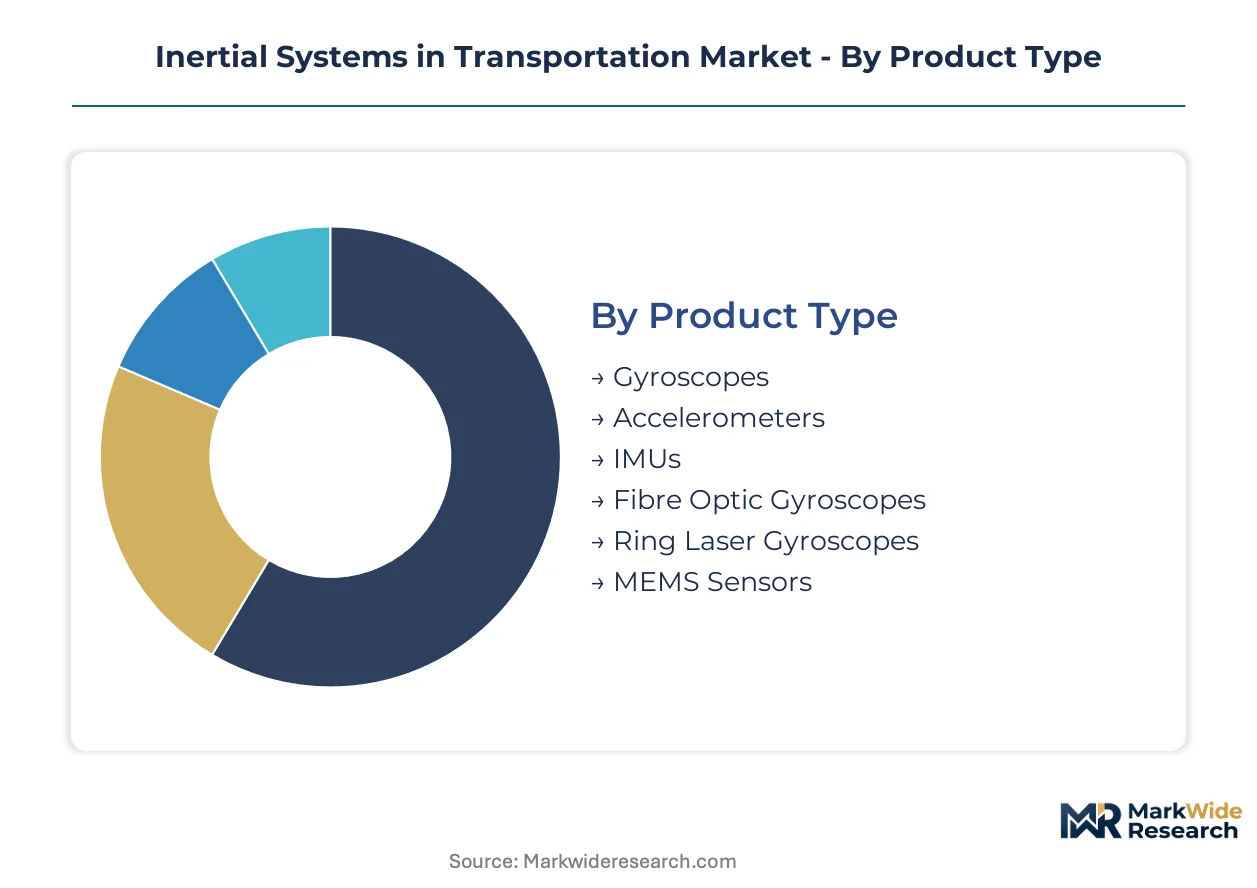
Inertial systems fragment across performance grades that command radically different replacement cycles. Tactical MEMS sensors turn over every 3-5 years in automotive platforms, while navigation-grade fiber optic gyroscopes persist 15-20 years in maritime installations. Procurement patterns diverge accordingly.
Product Type:
Cycle times stretch from months for commodity MEMS to decades for precision optical instruments, creating tiered inventory strategies across supplier portfolios.
- IMUs:Integrated six-axis packages combine gyroscopic and accelerometric sensing in compact enclosures. German OEMs embed these into production vehicle platforms for advanced driver assistance, pulling volume through automotive qualification pipelines.
- MEMS Sensors:Silicon-fabricated Coriolis structures achieve tactical-grade performance at foundry scale. Drone manufacturers in the United States and China compete aggressively for design wins based on size and power specifications.
- Gyroscopes:Rotational rate sensors span mechanical, optical, and microelectronic implementations.
- Accelerometers:Linear acceleration measurement devices range from piezoelectric to capacitive MEMS architectures.
- Fibre Optic Gyroscopes:Sagnac interferometry in wound fiber coils delivers navigation-grade precision for GPS-denied environments.
- Ring Laser Gyroscopes:Helium-neon cavity instruments maintain ultra-low drift for submarine and strategic aerospace applications.
Fibre optic gyroscopes dominate installed base in premium maritime and defense applications. MEMS sensors are where expansion concentrates.
Transportation Mode:
Application environments impose distinct shock, vibration, and temperature specifications that filter supplier eligibility.
- Autonomous Vehicles:Robotic platforms require redundant inertial channels for safety-critical localization. Developers in California and Arizona negotiate direct MEMS supply agreements, bypassing traditional tier-one distributors.
- Commercial Trucks:Long-haul fleets under fuel efficiency mandates adopt inertial routing for highway optimization. Indian operators retrofit legacy vehicles under Bureau of Indian Standards norms.
- Aerospacecraft:FAA airworthiness certification governs sensor validation timelines for retrofit and new-build programs.
- Maritime Vessels:IMO navigation standards drive gyrocompass replacement in merchant shipping.
- Rail:European networks integrate inertial measurement for track geometry monitoring and train positioning.
- Delivery Drones:Last-mile aerial platforms prioritize weight-minimized IMUs for flight control stability.
Commercial trucks anchor current volume. Autonomous vehicles are climbing the fastest.
Technology:
Cost tiers separate laboratory-grade prototypes from field-deployable production units, with hybrid architectures bridging the gap.
- MEMS:Semiconductor batch processing enables six-axis integration below 10 cubic centimeters.
- Optical:Fiber and laser gyroscopes retain premium positioning where GPS denial resilience commands priority.
- Mechanical:Spinning mass instruments persist in legacy aerospace and defense installations.
- Quantum:Cold-atom interferometry prototypes promise GPS-denied navigation but remain outside commercial transportation deployment.
- Hybrid:Multi-technology fusion combines MEMS agility with optical stability in integrated navigation suites.
- Electromechanical:Tuning fork and vibrating beam architectures serve niche industrial applications.
Optical technology commands highest unit margins. MEMS is gaining share fastest.
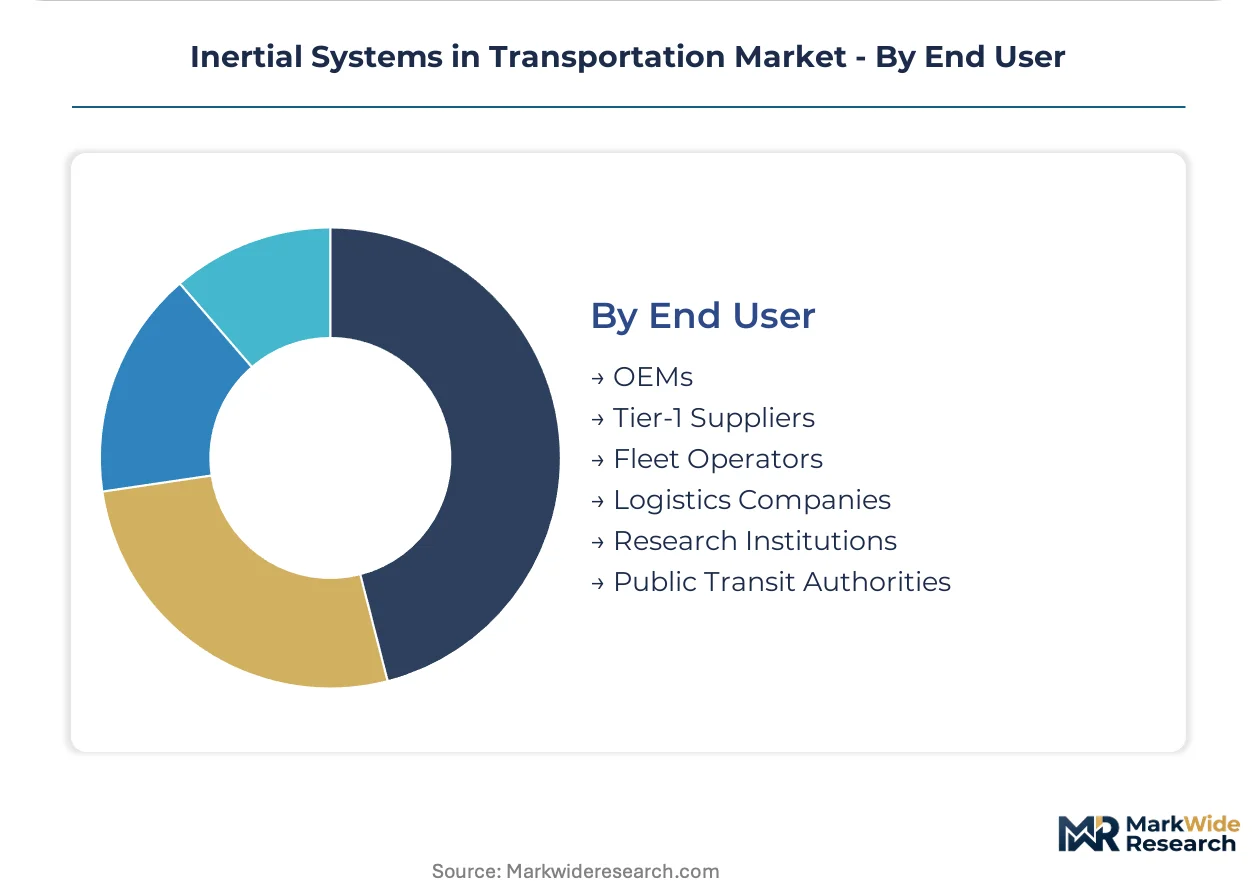
End User:
Procurement authority is shifting from system integrators toward direct foundry relationships as volumes standardize.
- Fleet Operators:Trucking and maritime fleets now unbundle sensor procurement from integrator contracts. Werner, Schneider, and J.B. Hunt negotiate direct volume agreements for standardized IMU modules.
- OEMs:Vehicle manufacturers mandate platform-integrated inertial sensing for advanced driver assistance. German automotive corridors pull tactical-grade units into production lines at scale.
- Tier-1 Suppliers:Traditional navigation houses reposition around software calibration and fusion algorithms.
- Logistics Companies:Parcel and freight operators adopt inertial tracking for asset visibility.
- Research Institutions:University and government laboratories prototype quantum and photonic integrated approaches.
- Public Transit Authorities:Municipal rail operators deploy inertial measurement for passenger safety and schedule adherence.
OEMs dominate design-in authority. Fleet operators are where procurement innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and automotive OEMs concentrate procurement authority across distinct national manufacturing corridors, with regulatory frameworks in Germany, the United States, India, Japan, and China each pulling different performance tiers of inertial hardware into their domestic transportation platforms.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria mandate platform-integrated IMUs for advanced driver assistance systems, pulling tactical-grade sensors into production lines at scale. The KBA type-approval process verifies safety-critical separation between inertial outputs and AI-driven decision layers under EU AI Act risk classifications. Stuttgart and Munich anchor the densest concentration of foundry-qualified sensor procurement for production vehicle platforms.
United States
Autonomous trucking fleets in California and Arizona negotiate direct MEMS supply agreements, bypassing traditional tier-one distributors as volumes standardize. FAA airworthiness certification governs sensor validation timelines for aerospacecraft retrofit programs, while DOT automated vehicle guidance tightens performance requirements for localization systems. The Southwest corridor hosts pilot programs where Werner, Schneider, and J.B. Hunt test inertial routing for highway optimization.
India
Commercial trucking operators under Bureau of Indian Standards fuel efficiency norms seek low-cost inertial routing for legacy vehicle retrofit. The PLI scheme for automotive components indirectly supports domestic sensor assembly capacity expansion. Maharashtra and Gujarat host emerging clusters where fleet operators unbundle sensor procurement from system integrator contracts.
Japan
Specialized wound fiber for FOG gyros concentrates among domestic manufacturers, creating supply vulnerability for maritime gyrocompass replacement under IMO navigation standards. METI industrial policy supports photonic integrated circuit development for satellite-denied heading reference. Nagoya and Yokohama maintain precision optical manufacturing heritage serving defense and merchant shipping applications.
China
Drone manufacturers compete aggressively for MEMS IMU design wins based on size and power specifications for last-mile aerial platforms. MIIT standards govern automotive sensor qualification timelines for domestic OEM platform integration. The Yangtze River Delta and Pearl River Delta concentrate foundry capacity scaling six-axis integration below ten cubic centimeters.
Inertial Systems in Transportation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered performance grades, with aerospace heritage houses dominating high-reliability optical supply while MEMS foundries capture automotive volume. The vendor base organizes around three strategic archetypes: aerospace-defense conglomerates with fiber optic gyroscope legacies, automotive-qualified MEMS foundries with direct OEM contracting capabilities, and compact navigation specialists targeting drone and autonomous vehicle platforms. Dominant competitive moves include direct foundry contracting that bypasses traditional tier-one distributors, and strategic repositioning around software calibration and fusion algorithms as hardware commoditizes.
Among aerospace-defense conglomerates, Honeywell International Inc. and Northrop Grumman Corporation exemplify the high-reliability tier with fiber optic and ring laser gyroscope legacies serving maritime and strategic applications. Safran Electronics & Defense anchors European positioning through tightly integrated navigation suites. At the compact MEMS specialist end, VectorNav Technologies LLC occupies a position competing for autonomous vehicle and drone platform design wins. These named entities represent distinct capability concentrations rather than exhaustive market coverage, with each archetype facing pressure from photonic integrated circuit entrants and quantum sensing prototypes.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Northrop Grumman Corporation |
| Safran Electronics & Defense |
| Thales Group |
| Collins Aerospace |
| Teledyne Technologies Incorporated |
| L3Harris Technologies Inc. |
| VectorNav Technologies LLC |
| Gladiator Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta foundry cluster compresses MEMS sensor costs through six-axis integration below ten cubic centimeters, concentrating pricing power among automotive-qualified suppliers while optical-grade fiber coil wound in Nagoya and Yokohama sustains premium positioning for maritime gyrocompass applications.
Pricing Analysis
Cost-plus contracts with rare-earth element indexation govern fiber optic gyroscope procurement for defense and maritime buyers. Three-tier pricing structure across navigation-grade, tactical-grade, and commercial-grade performance levels separates thousandths-of-a-degree drift specifications from degrees-per-hour MEMS alternatives. Cost compression in tactical-grade MEMS is intensifying because foundry scale economies outpace automotive demand growth. Fleet operators negotiating direct volume agreements exhibit highest price sensitivity; submarine navigation programs show lowest sensitivity due to GPS-denied resilience requirements.
Supply Chain Analysis
TSMC, GlobalFoundries, and SMIC hold dominant MEMS foundry capacity for automotive IMU production. Germany, China, and Japan anchor precision optical manufacturing for fiber coil winding and photonic integrated circuit fabrication. Specialized wound fiber for Sagnac interferometry draws from Japanese and US specialty manufacturers, creating single-source vulnerability. Distribution runs through direct OEM contracting that bypasses traditional tier-one navigation system houses as volumes standardize.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
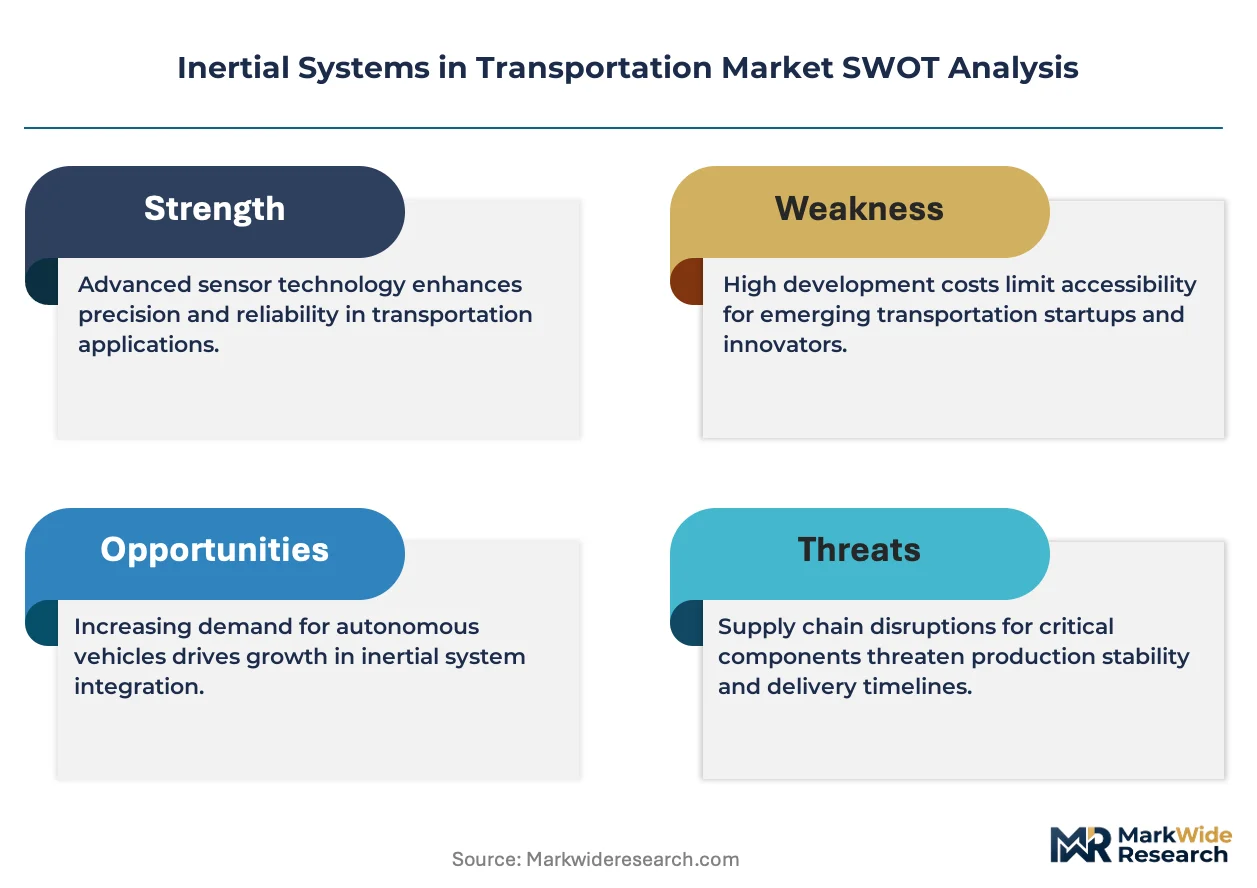
Scarcity of silicon photonics packaging expertise and fiber-to-chip alignment specialists constrains FOG manufacturers competing with MEMS entrants, creating asymmetric capability gaps that reshape competitive positioning across performance tiers.
For Market Incumbents: Build certification moats through accelerated ASIL-D qualification pipelines that extend validation cycle advantages over emerging MEMS entrants. Deepen backward integration into specialized wound fiber supply to mitigate single-source exposure in Japanese optical-grade coil manufacturing. Prioritize software calibration and fusion algorithm development as hardware commoditization erodes standalone sensor premiums. For New Entrants and Emerging Players: Build out Indian commercial trucking retrofit channels where Bureau of Indian Standards fuel efficiency norms create unmet demand for low-cost inertial routing modules. Target delivery drone platforms in the United States and China where weight-minimized IMU specifications favor compact MEMS specialists over legacy optical houses. Lead with direct foundry contracting value propositions that match autonomous vehicle developer procurement innovation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automotive-qualified MEMS foundries with established OEM platform integration track records over pure-play optical instrument houses facing silicon photonics disruption. Long-term viability rests on dual-use navigation capability spanning defense-funded quantum prototypes to civil transportation qualification timelines. Monitor defense-to-civil technology transfer acceleration in cold-atom interferometry as inflection indicator for next-generation GPS-denied navigation investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Foundry Contracting | Bypasses tier-one distributors to capture margin from autonomous vehicle fleet procurement centralization. |
| Photonic Integrated Circuit Development | Collapses optical alignment labor into semiconductor batch processing for maritime gyrocompass digitization. |
| ASIL-D Functional Safety Certification | Creates 18-24 month validation barriers against unqualified MEMS entrants in automotive platforms. |
| Quantum Sensing R&D Partnership | Positions for defense-to-civil technology transfer in GPS-denied navigation applications. |
| Software Fusion Algorithm Investment | Captures value as hardware precision premiums erode across sensor fusion architectures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, FAA airworthiness certification databases, EU CSRD disclosure records, and automotive production data from IHS Markit. Primary interviews engaged MEMS foundry operations directors, Tier 1 supplier procurement managers, autonomous vehicle platform engineers, maritime gyrocompass technical directors, and rail network signaling specialists. Bottom-up sensor shipment analysis triangulates against top-down OEM platform integration mandates across the analysis window.
Forecast inputs span performance grade segmentation, transportation mode application environments, technology cost tiers, and end-user procurement authority shifts. Modeled dimensions include drift specification grades, vehicle class integration depth, propulsion architecture sensor counts, and regional regulatory cluster adoption patterns. CAGRs derive from volume-price elasticity curves calibrated to foundry capacity expansion timelines and automotive qualification pipeline throughput.
Stress conditions across rare-earth fiber supply disruption, MEMS foundry yield volatility, and autonomous vehicle regulatory delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense funding continuity for quantum prototype development and EU AI Act implementation timelines for safety-critical separation verification. Quarterly review of KBA type-approval backlog, FAA certification queue depth, and PLI scheme disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Global Body Control Modules Market
Automotive Electronics & Wiring
China Automotive Smart Keys Market
Automotive Electronics & Wiring
Bluetooth in Automotive Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Two-Wheeler Connectivity Systems Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market
Automotive Electronics & Wiring
Vehicle Networking Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Automotive Data Logger Market