
 China Automotive Smart Keys Market | 2026-2036
China Automotive Smart Keys Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Smart Keys Market Outlook
Yangtze River Delta capacity expansion is reshaping component sourcing patterns for proximity-based entry systems. YF Tech leverages its Shenzhen R&D base to anchor Bluetooth Low Energy module production for domestic brands. Kostal competes through specialized antenna design capabilities serving European joint ventures operating in China.
China automotive smart keys are electronic access devices integrating radio frequency transceivers, encryption processors, and motion sensors to enable passive entry and push-button ignition without physical key insertion. Manufacturing relies on surface-mount assembly of ceramic resonators and secure-element chips within injection-molded housings rated for automotive temperature extremes. Smart keyless entry products now dominate value contribution as OEMs phase out blade-key architectures across B-segment and above vehicles. Biometric recognition represents the fastest-growing technology dimension, though RFID maintains volume leadership due to cost parity with legacy fob systems.
MIIT mandatory cybersecurity standards for intelligent connected vehicles, SAMR product quality certification requirements, and GB/T national standards for automotive electronic subsystems collectively mandate encrypted communication protocols and tamper-resistant hardware. These frameworks elevate compliance costs for aftermarket providers while creating specification barriers for imported alternatives. Stakeholders must weigh biometric integration roadmaps against the installed base of RFID-dominated vehicle fleets still under warranty coverage.
Market Dynamics
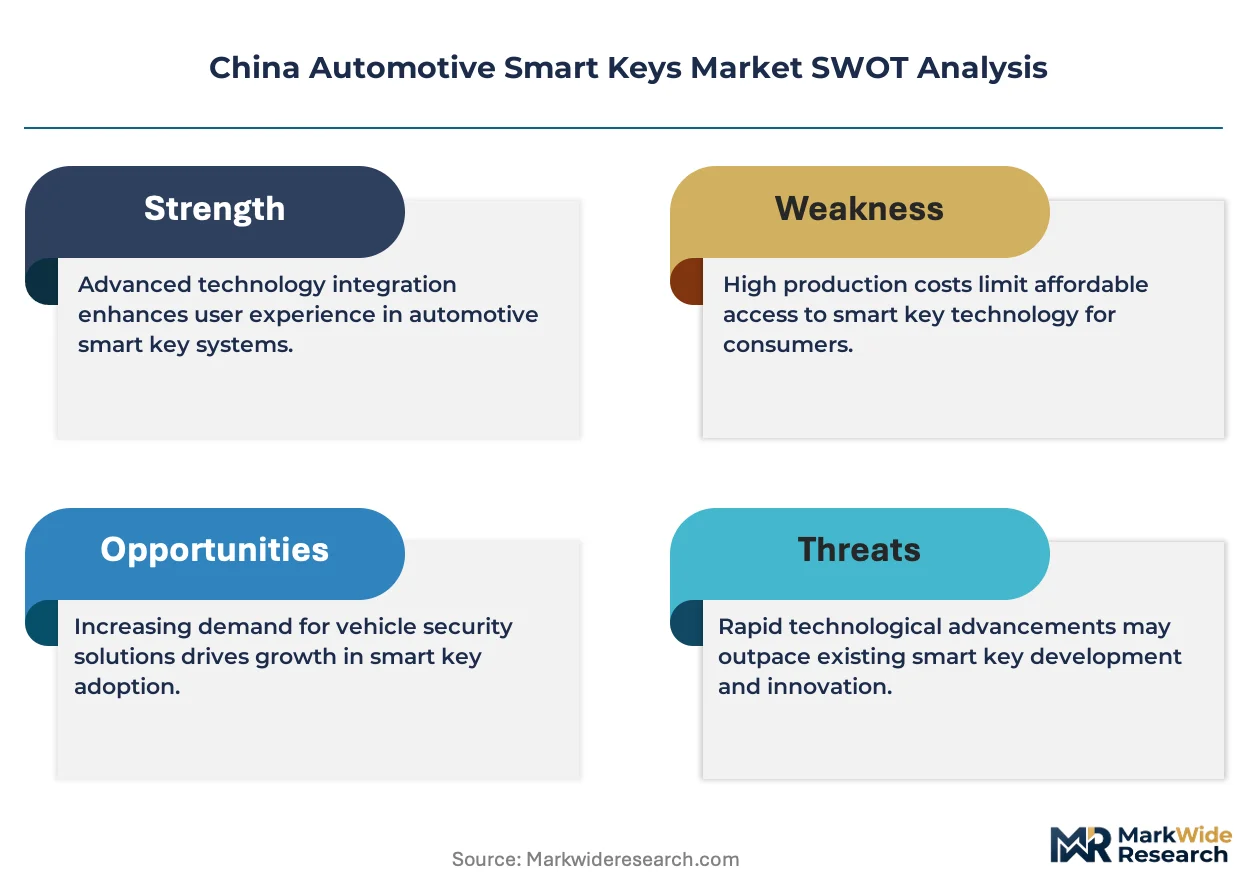
MIIT cybersecurity mandates for connected vehicles are forcing authentication protocol upgrades across domestic supply chains. Component suppliers face recertification cycles for encryption processors while OEMs consolidate sourcing around compliant module vendors.
Growth Catalysts
- GB/T automotive electronic subsystem standards:National standards mandate tamper-resistant hardware across B-segment and above vehicles. This creates specification pull for secure-element chip integration.
- Yangtze River Delta manufacturing cluster:Proximity of Shanghai-based vehicle assembly plants to component suppliers compresses logistics lead times for proximity-based entry system modules.
- Biometric recognition technology:Fingerprint and facial authentication modules are penetrating mid-tier lineups as domestic OEMs differentiate feature sets.
Market Restraints
- Ceramic resonator supply concentration:Surface-mount assembly lines depend on limited qualified suppliers for temperature-stable frequency components.
- SAMR certification timelines:Product quality certification requirements extend hardware validation cycles for aftermarket providers.
- RFID cost parity:Legacy fob systems maintain volume leadership due to manufacturing scale economies that compress biometric alternatives' pricing room.
Strategic Opportunities
- Central China vehicle production bases:Wuhan and Chongqing assembly corridors remain underpenetrated by proximity entry system penetration relative to coastal clusters.
- Bluetooth Low Energy convergence:Smartphone-as-key protocols are converging with passive entry architectures to enable OEM-branded digital key ecosystems.
- Dual carbon policy alignment:Energy efficiency mandates for connected vehicle subsystems favor low-power radio frequency transceiver designs.
Industry Challenges
- Encryption processor talent scarcity:Firmware development for secure-element integration requires specialized automotive cybersecurity expertise concentrated in Shenzhen and Beijing.
- Legacy blade-key warranty coverage:Service network obligations for RFID-dominated vehicle fleets constrain rapid biometric retrofit programs.
- Injection-molded housing thermal validation:Automotive temperature extreme ratings require extended qualification protocols for new material formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Smart Keys Market |
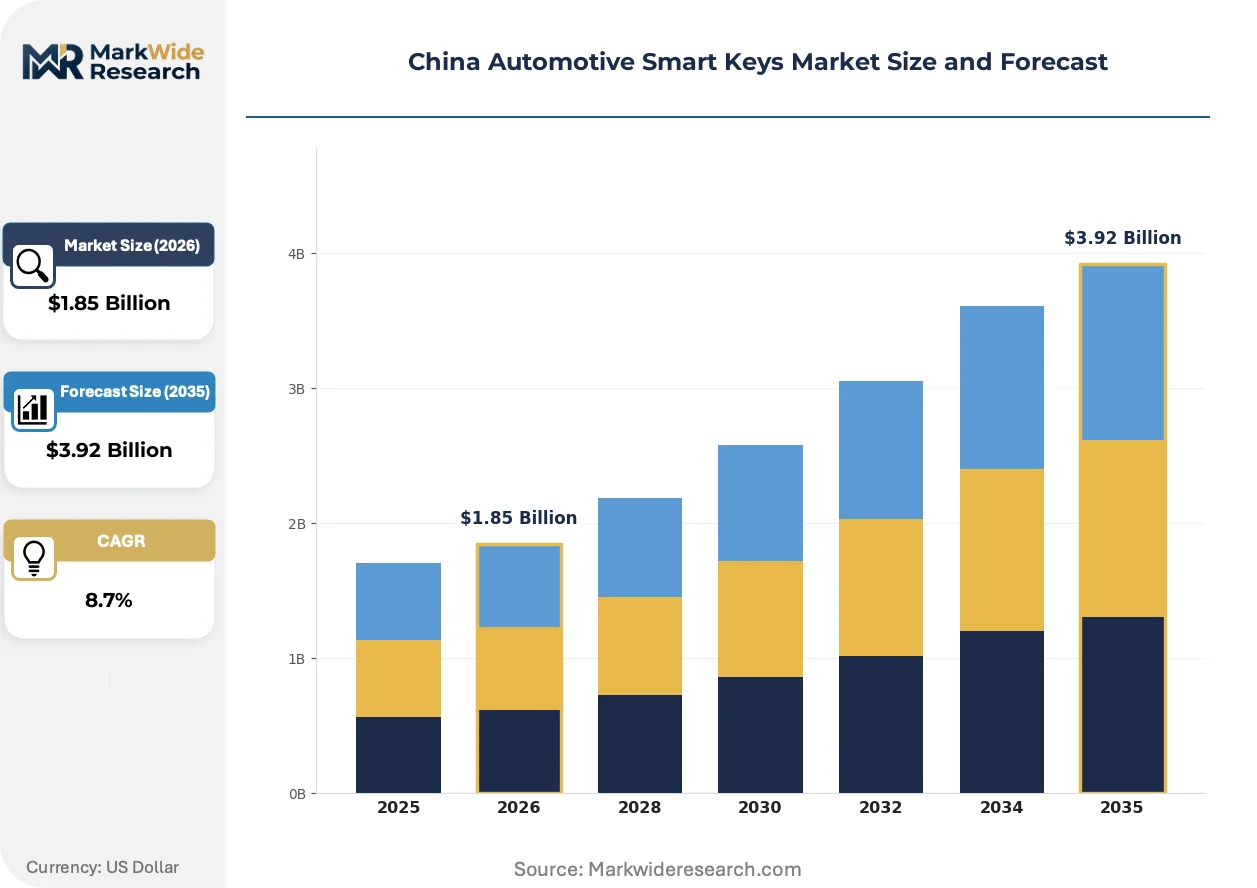
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Keys, Key Fobs, Smart Keyless Entry, Remote Start Keys Technology: RFID, Bluetooth, NFC, Biometric Recognition End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Installation: Factory Installed, Aftermarket Installation, DIY Installation, Integrated Systems |
| Companies Covered | YF Tech, Pektron, Gosuncn, UAES, Kostal, Huf Group, Marquardt, Jingwei Hirain, Alps Alpine, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Smart Keys Market Strategic Shifts
Authentication architectures are migrating toward multi-factor verification stacks. This shift compresses single-technology supplier margins while rewarding module integrators with cross-protocol capabilities.
Ultra-wideband positioning chips are migrating from premium vehicle lineups to standard equipment tiers. Domestic OEMs in the Yangtze River Delta cluster are adopting UWB modules for centimeter-level localization accuracy. This is migrating from a premium differentiator to a baseline specification that compresses RFID-only supplier relevance.
MIIT mandatory cybersecurity standards for intelligent connected vehicles now require encrypted communication protocols for all wireless entry systems. The regulation elevates compliance costs for hardware vendors without certified secure-element integration. Aftermarket providers face the steepest recertification burden while tier-one module suppliers absorb compliance into existing quality systems.
Fleet procurement of smart key systems is fragmenting across ownership models. Leasing companies and mobility operators are demanding separate digital key provisioning from physical fob distribution. This unbundling is most visible in Shanghai and Beijing, where corporate fleet managers negotiate API-accessible key management platforms independent of vehicle purchase contracts.
China Automotive Smart Keys Market Segmentation
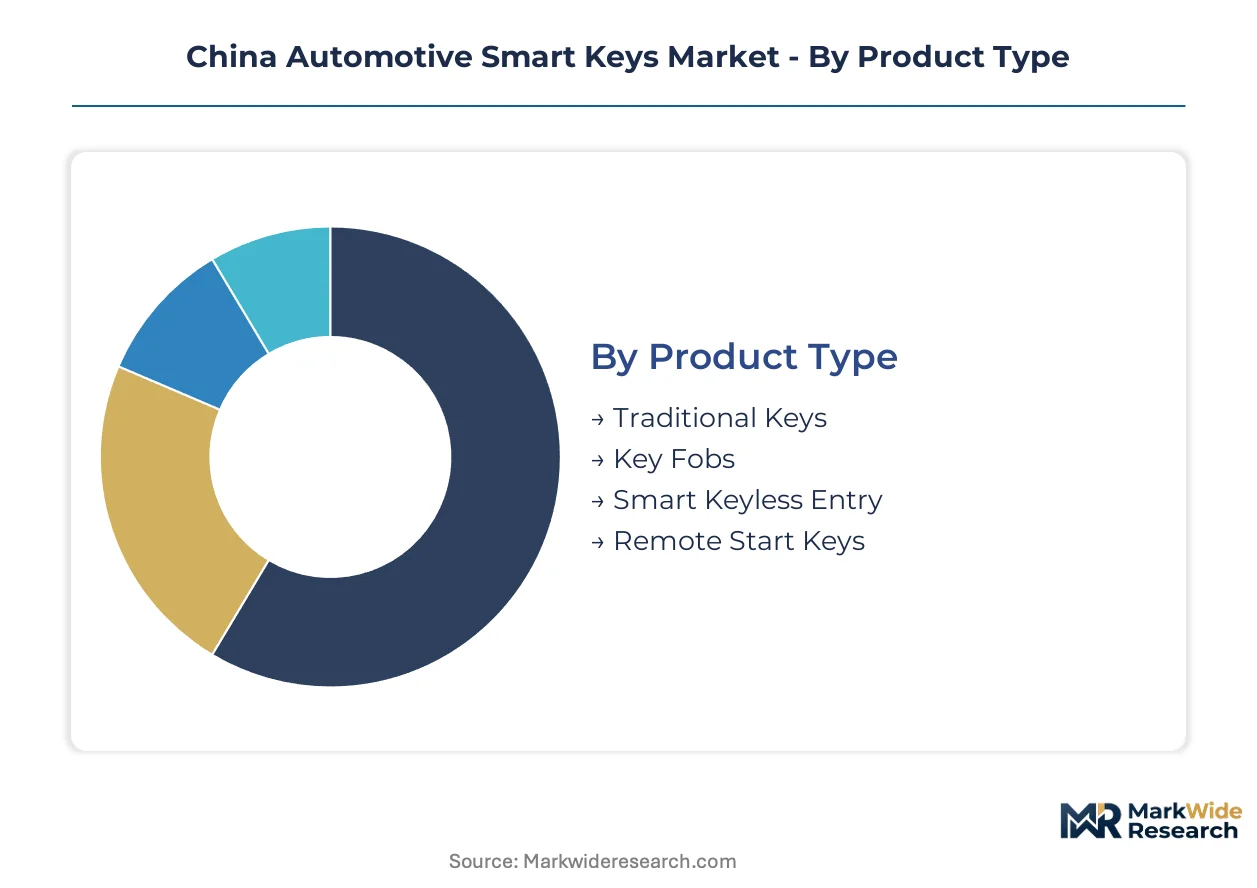
Smart key architectures in China fragment across four critical dimensions that determine pricing power, certification burden, and channel access. OEM sourcing strategies favor integrated module suppliers capable of spanning multiple technology protocols, while aftermarket channels remain segmented by installation complexity and cybersecurity compliance tiers.
Product Type:
The use-case spectrum spans blade-key replacement through fully passive entry systems, with value concentration shifting toward proximity-based architectures as domestic OEMs standardize keyless ignition across mid-tier lineups.
- Smart Keyless Entry:Passive entry modules integrating radio frequency transceivers with encrypted secure-element processors enable hands-free door unlocking and push-button ignition. Yangtze River Delta assembly plants are standardizing these systems across B-segment and above vehicles to meet GB/T automotive electronic subsystem requirements.
- Key Fobs:Remote transmitter devices combining lock/unlock buttons with panic alarm functionality represent the transitional architecture bridging blade keys and full proximity systems. Domestic brands in Shanghai manufacturing corridors maintain volume demand here due to cost parity pressures against biometric alternatives.
- Traditional Keys:Mechanical blade keys with embedded immobilizer transponders serve entry-level vehicle segments and legacy fleet replacement demand.
- Remote Start Keys:Extended-range transmitter modules enabling engine pre-conditioning command premium positioning in cold-climate provinces.
The dominant share belongs to Key Fobs, while Smart Keyless Entry is closing the gap fastest.
Technology:
Authentication protocols stratify by security tier and power consumption, with regulatory pressure from MIIT cybersecurity mandates elevating encrypted communication standards across all wireless entry categories.
- RFID:Low-frequency passive transponder technology operating at 125 kHz dominates volume production due to manufacturing scale economies and established supply chains for ceramic resonator components.
- Biometric Recognition:Fingerprint and facial authentication modules penetrate mid-tier domestic OEM lineups as differentiation features, with Shenzhen R&D clusters driving firmware development for secure-element integration.
- Bluetooth:Low-energy protocols enable smartphone-as-key convergence with passive entry architectures, supporting OEM-branded digital key ecosystems.
- NFC:Near-field communication supports tap-to-unlock functionality for backup authentication scenarios and fleet key provisioning APIs.
RFID maintains installed-base leadership, though Biometric Recognition is expanding most quickly among technology categories.
End User:
Customer-type concentration shapes procurement patterns, with fleet digitization in Beijing and Shanghai creating unbundled demand for API-accessible key management platforms separate from physical fob distribution.
- OEMs:Vehicle manufacturers consolidate sourcing around MIIT-compliant module vendors capable of integrating encryption processors with surface-mount assembly lines.
- Fleet Operators:Leasing companies and mobility platforms negotiate independent digital key provisioning contracts, fragmenting traditional bundled sales models.
- Aftermarket Providers:Independent installers face SAMR certification timeline extensions and recertification burdens for hardware validation cycles.
- Individual Consumers:Retail replacement demand concentrates on lost-key scenarios and aesthetic customization for premium vehicle ownership.
OEMs command specification authority, while Fleet Operators are gaining procurement influence fastest.
Installation:
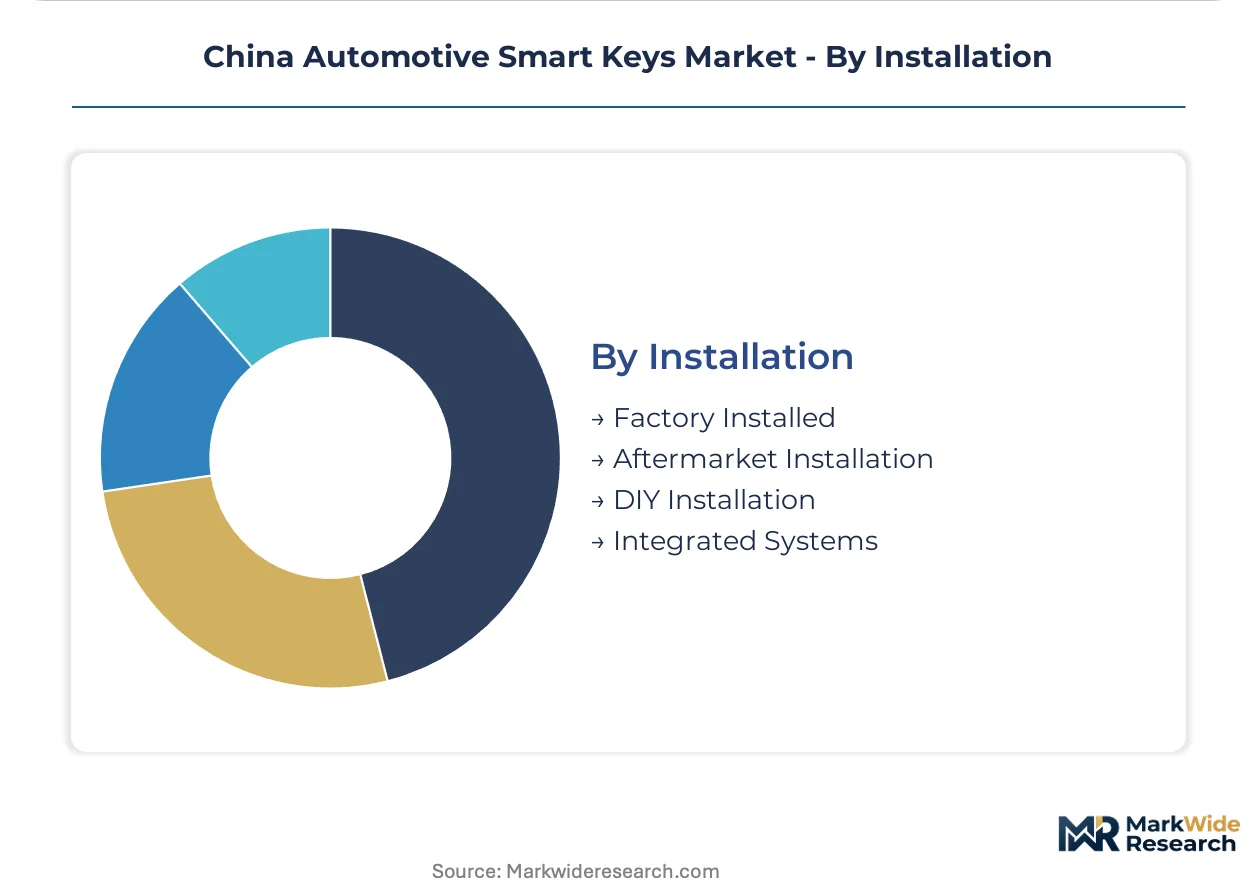
Channel configuration determines margin capture and warranty liability, with factory integration absorbing cybersecurity compliance costs that burden aftermarket alternatives.
- Factory Installed:Assembly-line integration at Yangtze River Delta vehicle plants ensures thermal validation and encrypted protocol compliance through tier-one module supplier relationships.
- Integrated Systems:Pre-engineered keyless entry modules bundled with telematics and infotainment architectures reduce per-unit installation labor.
- Aftermarket Installation:Professional installer networks handle retrofit demand for legacy RFID-dominated fleets still under warranty coverage.
- DIY Installation:Consumer self-installation kits remain limited by firmware programming complexity and secure-element initialization requirements.
Factory Installed holds volume dominance, while Integrated Systems are climbing the fastest as OEMs consolidate subsystem sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters in eastern China dominate proximity-based entry system supply, with Yangtze River Delta assembly corridors absorbing over half of domestic module output. Provincial industrial policies and MIIT cybersecurity mandates are redistributing capacity toward interior vehicle production bases.
Shanghai-Jiangsu Corridor
SAIC Motor and Tesla Shanghai anchor demand for encrypted secure-element modules across B-segment and above lineups. MIIT mandatory cybersecurity standards for intelligent connected vehicles require tamper-resistant hardware validation at regional certification centers. The Suzhou-Wuxi-Changzhou manufacturing belt concentrates surface-mount assembly lines for ceramic resonator integration.
Guangdong Province
Shenzhen R&D clusters drive firmware development for Bluetooth Low Energy smartphone-as-key convergence. SAMR product quality certification timelines extend hardware validation cycles for biometric recognition module suppliers. BYD's Shenzhen headquarters and Guangzhou-based GAC Motor standardize proximity entry across mid-tier electric vehicle platforms.
Beijing-Tianjin-Hebei
BAIC Group and Great Wall Motor procurement concentrates on RFID-dominated architectures for fleet replacement demand. GB/T national standards for automotive electronic subsystems mandate encrypted communication protocols at regional testing facilities. Tianjin port logistics facilitate imported secure-element chip distribution to northern assembly plants.
Sichuan-Chongqing
Changan Automobile and Seres expand keyless entry penetration in underpenetrated interior markets. Dual carbon policy alignment favors low-power radio frequency transceiver designs at Chengdu-based component suppliers. Chongqing's vehicle production corridor remains below coastal proximity system penetration rates, creating specification upgrade opportunities.
Hubei Province
Dongfeng Motor procurement is accelerating for next-generation passive entry modules across Wuhan assembly bases. SAMR certification burdens for aftermarket providers limit independent installer network expansion in central China. Wuhan's automotive electronics industrial park attracts encryption processor talent from coastal migration.
China Automotive Smart Keys Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in radio frequency and secure-element supply. The vendor base stratifies across three tiers: multinational module suppliers with MIIT certification infrastructure, domestic integrators leveraging Yangtze River Delta manufacturing proximity, and specialized antenna design houses. Competitive positioning depends on backward integration into secure-element chip sourcing and firmware development capacity concentrated in Shenzhen and Beijing.
Among multinational suppliers with China-based operations, Kostal and Huf Group occupy positions emphasizing specialized hardware capabilities, while YF Tech anchors domestic Bluetooth Low Energy module production from its Shenzhen R&D base. These three exemplify divergent archetypes: European joint-venture service, premium antenna engineering, and cost-optimized proximity system integration.
| Leading Market Players |
|---|
| YF Tech |
| Pektron |
| Gosuncn |
| UAES |
| Kostal |
| Huf Group |
| Marquardt |
| Jingwei Hirain |
| Alps Alpine |
| Others |
Value Chain & Pricing Dynamics
Ceramic resonator supply concentration in Japan and Taiwan feeds directly into margin capture at tier-one module integrators serving Yangtze River Delta OEMs. Pricing power clusters with vendors capable of backward integration into secure-element chip sourcing, while downstream assemblers face cost pass-through pressure on temperature-stable frequency components.
Pricing Analysis
MIIT cybersecurity mandates dictate the pricing tier structure across authentication module categories. Three-tier pricing structure across premium, standard, and economy levels separates UWB-enabled biometric systems from RFID-dominated key fobs and basic remote transmitters. Cost compression in standard-tier Bluetooth Low Energy modules is intensifying because Shenzhen R&D clusters are multiplying qualified firmware developers. Fleet operators exhibit the highest price sensitivity due to unbundled digital key procurement, while premium OEMs absorb biometric premiums for differentiation.
Supply Chain Analysis
Secure-element chip fabrication draws from Taiwan, South Korea, and Germany for automotive-grade encryption processors. Surface-mount assembly lines rest on ceramic resonator inputs from Murata and NDK, plus injection-molded housings from domestic petrochemical suppliers. Single-source vulnerability concentrates in qualified antenna substrate vendors serving European joint ventures. Distribution runs through tier-one module suppliers with MIIT certification infrastructure, bypassing aftermarket channels burdened by SAMR timeline extensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware development talent for secure-element integration remains scarce relative to demand from Yangtze River Delta OEMs. This capability gap rewards vendors with captive Shenzhen R&D capacity and punishes module assemblers dependent on external encryption processor sourcing.
For Market Incumbents: Harden certification infrastructure against SAMR timeline volatility by pre-validating alternate secure-element chip suppliers. Absorb MIIT compliance costs into existing quality systems to widen the specification barrier facing aftermarket competitors. Prioritize antenna design capabilities as UWB modules displace RFID-only architectures in B-segment and above vehicles. For New Entrants and Emerging Players: Build out Bluetooth Low Energy module production targeting Wuhan and Chongqing assembly corridors where proximity entry penetration lags coastal clusters. Exploit the fleet digitization trend in Beijing and Shanghai by offering API-accessible key management platforms separate from physical fob distribution. Lead with smartphone-as-key convergence protocols that domestic OEMs are standardizing across mid-tier electric vehicle platforms. For Investors and Strategic Acquirers: Capital is best deployed toward tier-one module suppliers with MIIT certification infrastructure and backward integration into secure-element chip sourcing. Long-term viability favors vendors spanning multiple authentication protocols as single-technology margins compress. Watch for UWB module adoption inflection in standard-equipment tiers as the signal that RFID-only supplier relevance is entering terminal decline.| Strategic Initiative | Industry Significance |
|---|---|
| Secure-Element Chip Backward Integration | Captures margin pools currently flowing to Taiwan and South Korea semiconductor vendors. |
| Shenzhen R&D Capacity Expansion | Addresses encryption processor talent scarcity constraining firmware development timelines. |
| Wuhan-Chongqing Distribution Buildout | Penetrates underexploited central China vehicle production corridors before incumbent saturation. |
| Fleet Key Management Platform Launch | Captures unbundled procurement from leasing companies and mobility operators in Beijing and Shanghai. |
| UWB Module Cost Reduction Program | Accelerates migration from premium differentiator to baseline specification across domestic OEM lineups. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with tier-one supplier procurement officers, OEM platform engineers, aftermarket distributors, and SAMR certification specialists; and secondary validation against vehicle production databases, MIIT regulatory filings, GB/T standard documentation, and customs records for secure-element chip imports. Bottom-up triangulation of module shipment volumes converged with top-down OEM vehicle production estimates.
Forecast inputs span product type, technology protocol, end-user category, and installation channel across the analysis window. CAGRs derive from segment-level growth rate blending weighted by value contribution shifts, with particular sensitivity to biometric recognition penetration curves and UWB module cost decline trajectories. MIIT cybersecurity mandate implementation timelines and dual carbon policy alignment for low-power radio frequency designs shape the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by domestic module suppliers would shift outcomes beyond modeled ranges. Cross-checking against IHS Markit vehicle registration data and MIIT connected vehicle certification disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Automotive Relay Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive Digital Mirror Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
North America Automotive Display Market