
 Vietnam Metal Packaging Market | 2026-2036
Vietnam Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Metal Packaging Market Analytics
Vietnam's Extended Producer Responsibility framework is pivoting metal packaging producers toward higher recycled content thresholds. Showa Aluminum Can Corporation leverages its integrated aluminum rolling capacity to secure raw material stability. My Chau Printing & Packaging Corporation anchors domestic supply through its diversified container and decorative tin operations. TBC-Ball Beverage Can VN Ltd dominates the beverage can segment with large-scale two-piece aluminum manufacturing near Binh Duong.
Vietnam metal packaging encompasses steel and aluminum substrates formed through deep drawing, three-piece welding, or two-piece drawing-and-ironing processes, typically ranging from 0.15 mm to 0.40 mm in wall thickness, serving barrier protection and shelf-life extension for consumable and industrial goods. Containers and cans lead volume throughput, with cans capturing the fastest expansion trajectory driven by beer and soft drink bottler procurement. The rigid packaging format sustains premium margin pools through high-barrier coating requirements and precision printing specifications that command technical differentiation.
Vietnam's Ministry of Natural Resources and Environment implements circular economy roadmaps that mandate recyclability disclosures, while the country's national standards body enforces food-contact metal safety protocols aligned with regional ASEAN harmonization. These frameworks elevate compliance costs for importers and incentivize localized coating and laminating technology investments. Stakeholders must monitor enforcement granularity around recycled content verification mechanisms to calibrate capital deployment timing.
Market Dynamics
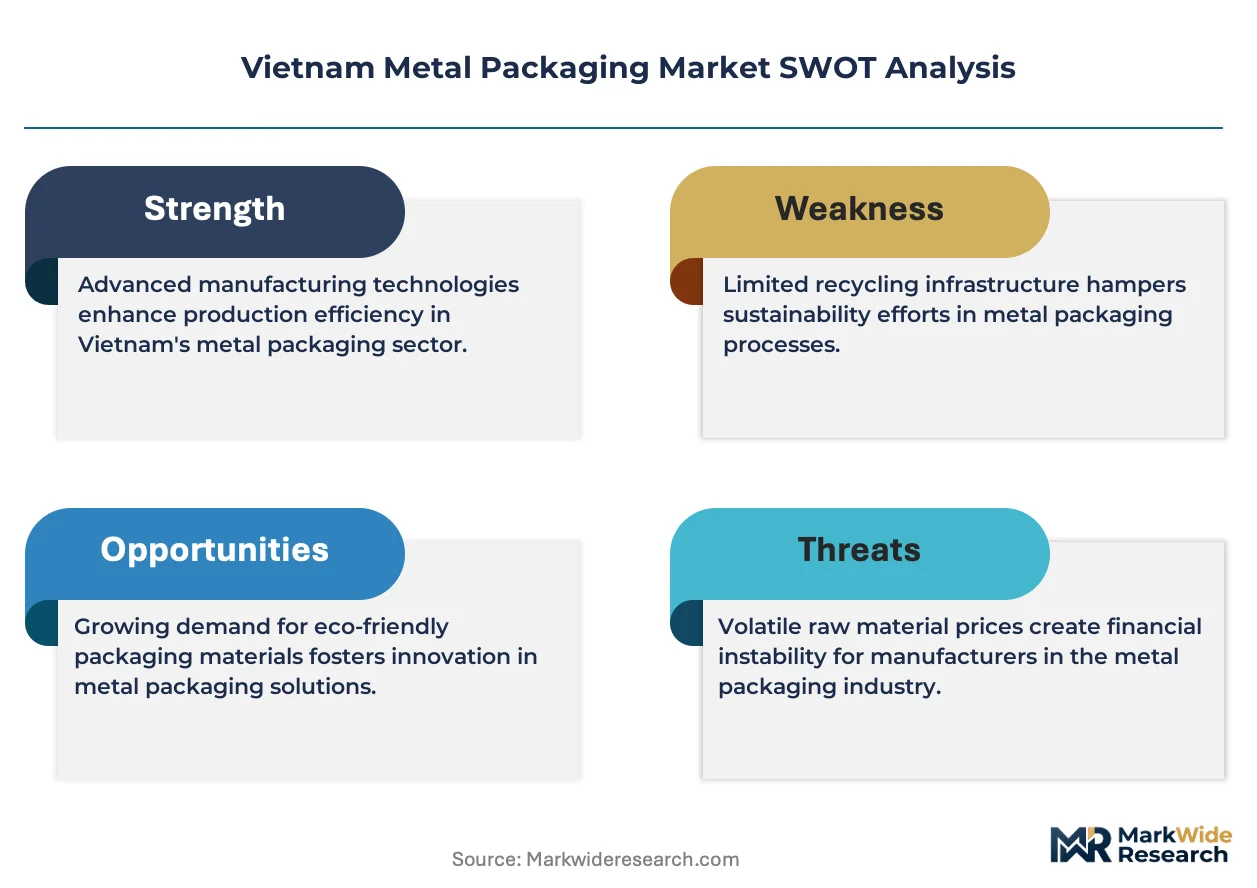
Vietnam's Extended Producer Responsibility framework is compressing design-to-recycle timelines while aluminum sheet supply concentration near Binh Duong creates raw material access hierarchies among can manufacturers.
Growth Catalysts
- ASEAN Food-Contact Harmonization:Regional safety protocol alignment accelerates cross-border tinplate container acceptance for processed food exporters targeting Thai and Philippine retail chains.
- Red River Delta Manufacturing Cluster:Hanoi-Hai Phong industrial corridor concentration enables just-in-time steel coil delivery for three-piece can fabricators serving northern beverage bottlers.
- Two-Piece Drawing-and-Ironing:Process technology migration from three-piece welding cuts unit production costs for aluminum beverage cans while improving metal utilization rates.
Market Restraints
- Primary Aluminum Import Dependence:Vietnam lacks bauxite-to-rolling capacity, forcing can makers to source ingot from Australian and Indonesian smelters exposed to LME price volatility.
- Epoxy Phenolic Coating Certification:Food-contact resin approvals require 18-24 month migration testing cycles under Ministry of Health protocols, delaying new product launches.
- Flexible Pouch Substitution:Stand-up pouches with metallized film barriers capture shelf-stable sauce and condiment volumes previously held by tinplate cans.
Strategic Opportunities
- Mekong Delta Underpenetration:Can Tho and An Giang provinces lack localized two-piece can supply, creating white space for satellite plants serving Mekong beverage distributors.
- Recycled Content Mandates:Vietnam's circular economy roadmap incentivizes post-consumer aluminum scrap integration through tax credits for verified closed-loop collection systems.
- Digital Printing Convergence:UV-cured inkjet decoration on metal substrates enables short-run customized can designs for craft beer and seasonal promotional campaigns.
Industry Challenges
- Deep-Draw Tooling Expertise Gap:Vietnam's technical education pipeline produces insufficient die maintenance engineers for precision ironing press operations.
- Legacy Lacquer Line Retrofit Costs:Converting solvent-based coating systems to water-based alternatives requires seven-figure capital outlays with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Metal Packaging Market |
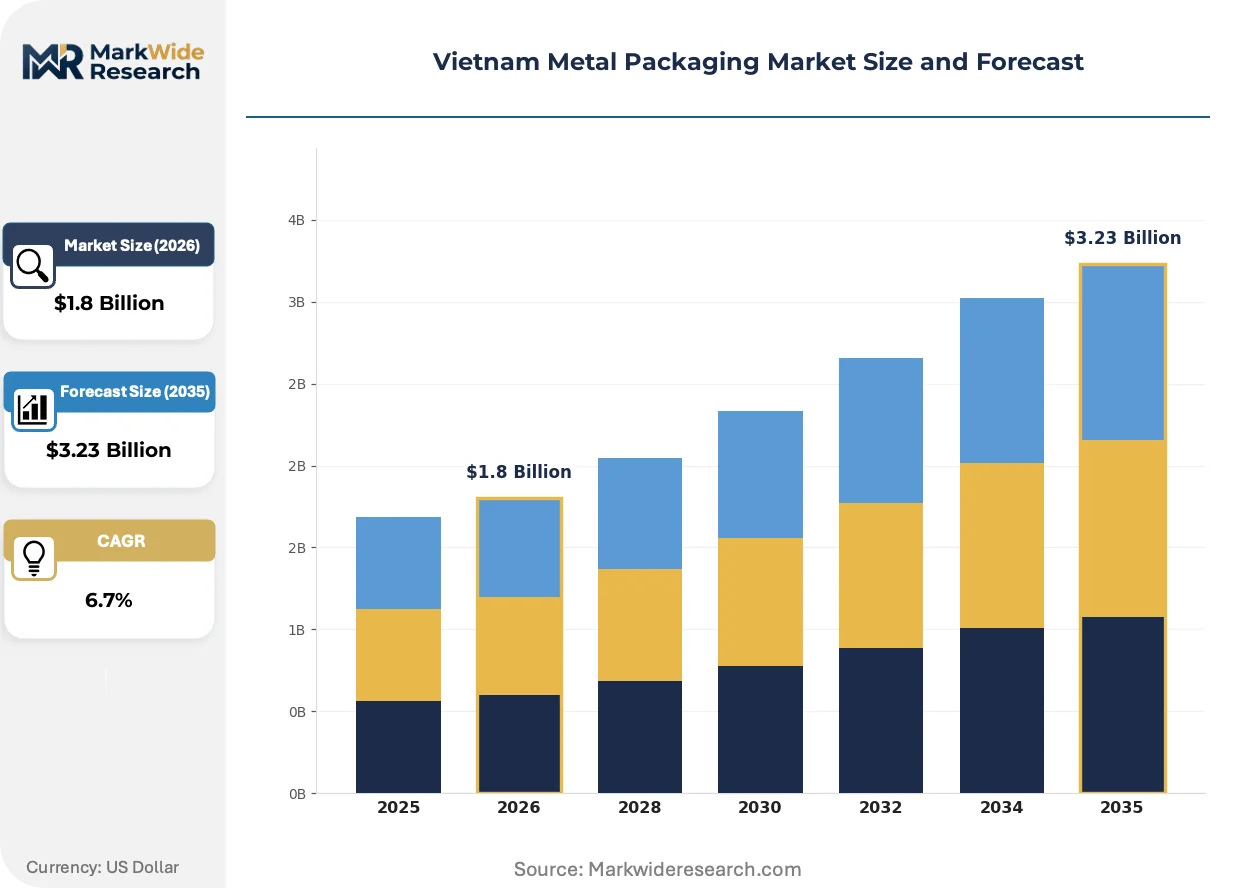
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Cans, Foil, Lids End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Technology: Printing, Coating, Decorating, Laminating Packaging Format: Rigid, Flexible, Aerosol, Specialty |
| Companies Covered | Showa Aluminum Can Corporation, My Chau Printing & Packaging Corporation, Canpac Vietnam Co., Ltd, Greif, Inc., Metal Printing & Packaging Ltd, Nihon Canpack (Vietnam) Co., Ltd, TBC-Ball Beverage Can VN Ltd, TMB Corporation, Crown Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Metal Packaging Market Evolving Landscape
Active coating chemistry reformulation and digital workflow integration are compressing product development cycles while reshaping quality assurance protocols across Vietnamese metal packaging operations.
Lightweighting technology is modularizing aluminum can design through gauge reduction below 0.25 mm wall thickness without sacrificing burst pressure ratings. Beverage multinationals operating Vietnam bottling plants are specifying these slimmed-down specifications for carbonated soft drink lines. The structural consequence is tiered supplier qualification, where only rolling mills with tight thickness tolerance control capture premium contract volumes.
Vietnam's Ministry of Natural Resources and Environment is enforcing recyclability disclosure mandates under its national circular economy roadmap. Metal packaging producers must now document end-of-life recovery pathways and recycled content percentages in annual environmental reports. The beverage can segment faces the steepest compliance burden, with aluminum suppliers investing in mass-balance certification systems to verify post-consumer scrap integration claims.
Brand-direct specification is consolidating procurement authority previously held by regional distributors. Multinational food manufacturers now issue centralized packaging tenders covering Vietnam, Thailand, and Philippines operations simultaneously. This pattern concentrates order volumes with tier-one decorators capable of matching color consistency across multi-plant supply, squeezing mid-scale domestic converters from multinational supplier lists.
Vietnam Metal Packaging Market Segmentation
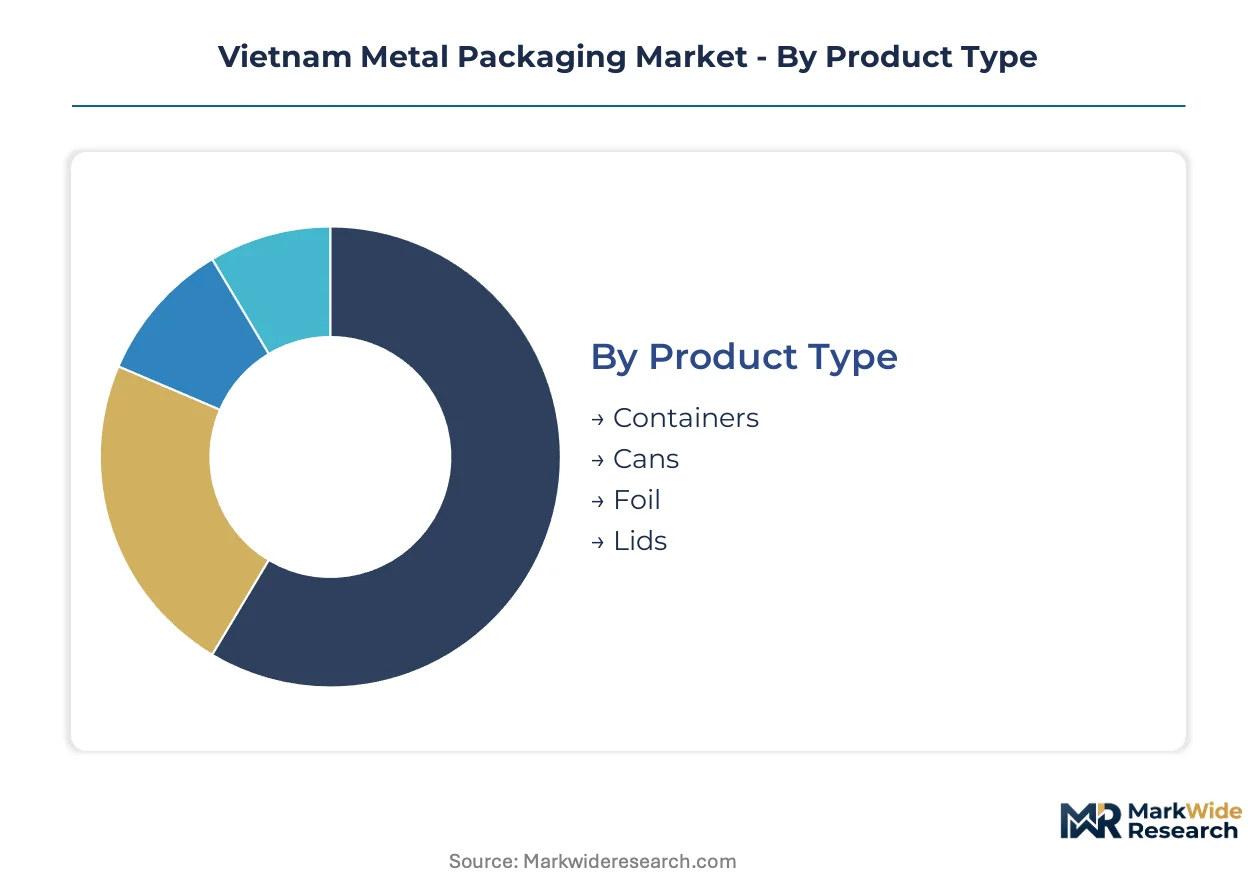
Segmentation reveals how capital deployment, technical capability, and regulatory exposure fragment across distinct production clusters. Manufacturers configure asset bases around substrate thickness tolerances and coating chemistry rather than chasing volume across all formats.
Product Type:
Deep-drawing presses and multi-station welding lines demand the heaviest capital commitments, with tooling amortization schedules stretching across contract cycles.
- Containers:Three-piece steel constructions with soldered or welded side seams serve processed food and industrial lubricant storage. Red River Delta fabricators cluster near Hai Phong steel coil terminals to minimize inbound freight exposure.
- Cans:Two-piece aluminum drawing-and-ironing dominates beverage applications, with wall thickness now pushed below 0.25 mm. Binh Duong plants supply carbonated soft drink and beer bottlers with just-in-time delivery contracts.
- Foil:Thin-gauge aluminum rolling for flexible lamination and household wrap operates at tighter margin pools.
- Lids:Easy-open ends and peelable membrane closures require precision scoring and compound lining equipment.
Cans absorb the bulk of installed capacity; containers are expanding most quickly through processed food export demand.
End User:
Migration from commodity supply toward certified food-contact and pharmaceutical barrier specifications is compressing the qualified supplier base.
- Food & Beverage:Epoxy phenolic and polyester coating systems must pass Ministry of Health migration testing cycles. Beer and carbonated soft drink bottlers in Ho Chi Minh City and Hanoi corridors specify two-piece aluminum for lightweighting and recyclability compliance.
- Pharmaceuticals:Blister foil and tube laminates demand cleanroom conversion lines and batch traceability systems. Domestic generic drug manufacturers source locally while multinationals import higher-barrier specifications.
- Cosmetics:Decorative tinplate and aluminum extrusions for premium fragrance and skincare packaging emphasize offset lithography quality.
- Chemicals:Drum and pail applications tolerate thicker-gauge steel with lower decoration investment.
Food & Beverage commands the dominant share of coating line utilization; Pharmaceuticals is climbing the fastest as domestic drug production scales.
Technology:
Process equipment selection locks manufacturers into specific customer tiers based on color consistency and run-length flexibility.
- Printing:Eight-color offset lithography dominates high-volume beverage can decoration with tight registration tolerances.
- Coating:Food-contact resin application requires solvent recovery systems and emissions controls under Ministry of Natural Resources and Environment protocols.
- Decorating:UV-cured inkjet and digital workflows enable short-run craft beer customization with reduced plate costs.
- Laminating:Extrusion and adhesive bonding for multi-layer foil structures serves pharmaceutical blister and retort pouch applications.
Coating claims the largest share of environmental compliance capital; digital printing is gaining share fastest among mid-scale decorators.
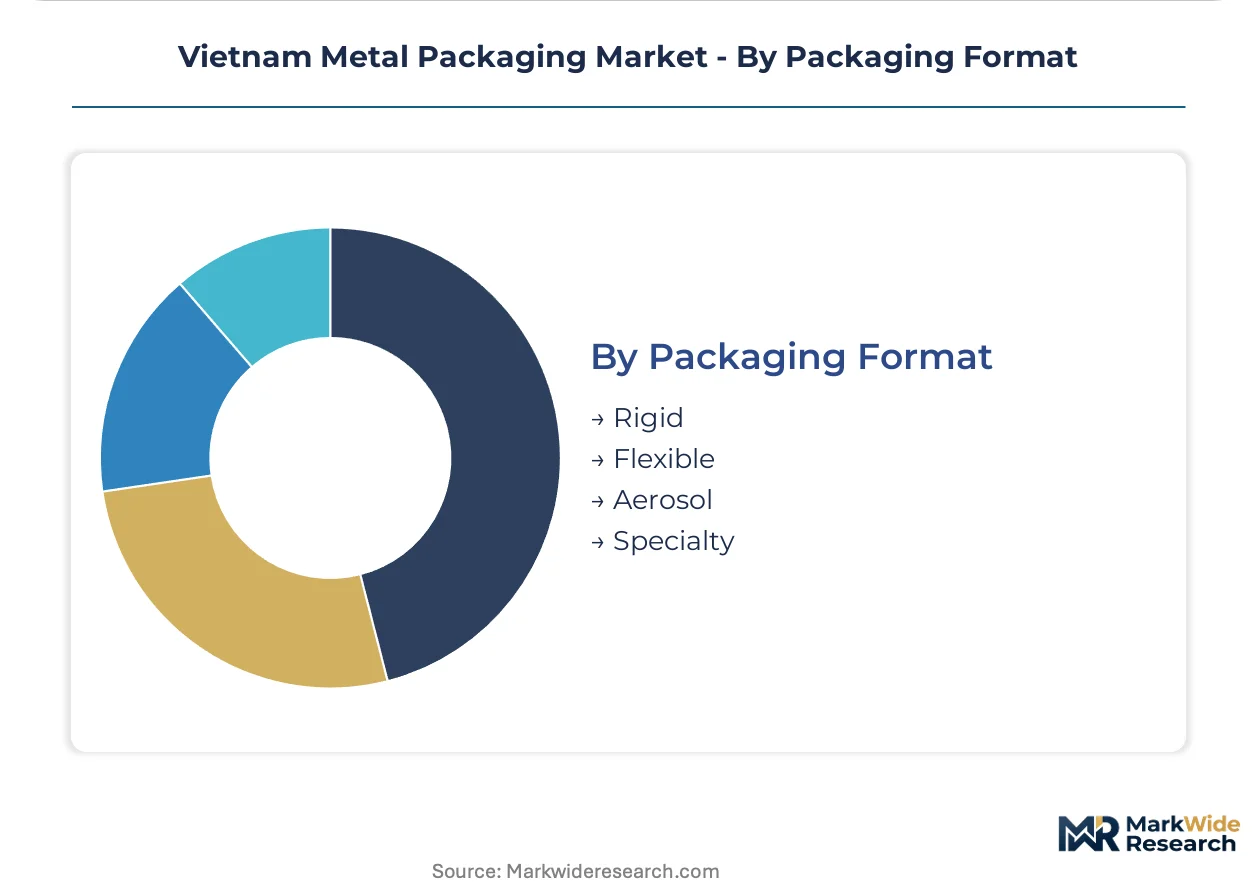
Packaging Format:
Structural rigidity requirements determine substrate mix and downstream handling compatibility across distribution channels.
- Rigid:Steel and aluminum cans, drums, and boxes provide stack strength for palletized distribution. Southeast region warehouses serving Ho Chi Minh City retail chains specify rigid formats for automated handling systems.
- Flexible:Foil laminates and metallized films displace tinplate in sauce and condiment segments through lighter weight and cube efficiency.
- Aerosol:Three-piece tinplate or aluminum cans with internal coating and valve crimping serve personal care and household products.
- Specialty:Shaped containers, gift tins, and promotional formats command premium positioning through unique die geometries.
Rigid formats dominate tonnage throughput; specialty packaging is expanding most quickly through premium brand differentiation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City anchors Vietnam's metal packaging demand through its Binh Duong industrial corridor concentration of two-piece aluminum can plants serving beverage bottlers.
Red River Delta
Hanoi and Hai Phong drive northern steel can demand through processed food exporters targeting ASEAN retail chains. Vietnam's Ministry of Natural Resources and Environment enforces circular economy disclosure mandates that compress design-to-recycle timelines for fabricators. Bac Ninh and Hung Yen provinces host three-piece can welding lines clustered near steel coil terminals.
Southeast Region
Dong Nai and Binh Duong provinces concentrate aluminum drawing-and-ironing capacity for carbonated soft drink and beer packaging. The national standards body mandates food-contact metal safety protocols aligned with ASEAN harmonization. Ho Chi Minh City logistics hubs enable just-in-time delivery contracts with multinational beverage bottlers.
Mekong Delta
Can Tho and An Giang provinces present underpenetrated demand for localized two-piece can supply serving regional beverage distributors. Vietnam's Extended Producer Responsibility framework incentivizes post-consumer scrap collection infrastructure investment. Floating market distribution networks in this region historically relied on imported packaging from Ho Chi Minh City corridors.
Central Coast
Da Nang and Quang Nam provinces process seafood exports requiring corrosion-resistant tinplate containers for international shipment. The Ministry of Health enforces epoxy phenolic coating migration testing cycles that delay new product launches. Chu Lai Economic Zone hosts emerging metal decorating operations targeting central region food processors.
Northeast Highlands
Thai Nguyen and Lang Son provinces supply raw material feedstock through limited aluminum scrap collection and steel distribution nodes. Provincial environmental departments implement national recyclability verification mechanisms with varying enforcement granularity. Border trade corridors with China influence regional material sourcing patterns for smaller fabricators.
Vietnam Metal Packaging Market Competitive Landscape
The competitive structure tilts toward integrated aluminum rolling specialists and diversified domestic converters. Tier-one multinational beverage can manufacturers and mid-scale regional decorators split procurement authority. Three archetypes dominate: integrated upstream suppliers controlling raw material stability, diversified domestic converters spanning multiple substrate formats, and beverage-focused specialists with large-scale two-piece capacity. Capacity expansion and coating technology licensing represent the primary competitive moves reshaping positioning.
Among integrated upstream suppliers, Showa Aluminum Can Corporation exemplifies raw material control through captive rolling capacity. My Chau Printing & Packaging Corporation occupies a position within the diversified domestic converter archetype, spanning container and decorative tin operations. TBC-Ball Beverage Can VN Ltd anchors the beverage specialist tier through large-scale two-piece manufacturing concentration near Binh Duong.
| Leading Market Players |
|---|
| Showa Aluminum Can Corporation |
| My Chau Printing & Packaging Corporation |
| Canpac Vietnam Co., Ltd |
| Greif, Inc. |
| Metal Printing & Packaging Ltd |
| Nihon Canpack (Vietnam) Co., Ltd |
| TBC-Ball Beverage Can VN Ltd |
| TMB Corporation |
| Crown Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
London Metal Exchange aluminum ingot pricing cascades through Vietnamese can manufacturing tiers, compressing margins at converters lacking captive rolling capacity while insulating integrated producers from raw material volatility.
Pricing Analysis
Throughput-based contract pricing anchors beverage can procurement, with multinationals tying unit rates to guaranteed annual volume bands and line efficiency targets. Price differentiation separates premium two-piece aluminum specifications from standard three-piece steel containers through coating certification tiers and thickness tolerance grades. Pricing pressure intensifies in the container segment as flexible pouch substitutes capture sauce and condiment volumes previously held by tinplate. Domestic food processors exhibit highest price sensitivity, while pharmaceutical blister foil buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Australian and Indonesian primary aluminum smelters, forcing Vietnamese can makers to absorb LME price swings without downstream hedging mechanisms. Raw material flows draw from Australian bauxite-to-ingot operations, Indonesian rolling capacity, and regional steel coil terminals at Hai Phong. Supply chain risk centers on tariff exposure from ASEAN-external aluminum sourcing under evolving trade remedy frameworks. Distribution runs through just-in-time delivery contracts linking Binh Duong plants to Ho Chi Minh City beverage bottlers, with northern corridors serving Hanoi-Hai Phong industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's metal packaging sector occupies a process-technology transition phase, with two-piece drawing-and-ironing displacing legacy three-piece welding across beverage applications.
For Market Incumbents: Deepen backward integration into aluminum rolling or secure long-term ingot offtake agreements to neutralize LME volatility exposure. Incumbents must retrofit solvent-based coating lines to water-based alternatives before Ministry of Natural Resources and Environment enforcement tightens, while defending market position through mass-balance certification systems that verify post-consumer scrap integration claims. For New Entrants and Emerging Players: Digital printing workflows on metal substrates offer a technology-first wedge for short-run craft beer customization with reduced plate costs. New entrants should target Mekong Delta underpenetration in Can Tho and An Giang provinces, where floating market distribution networks historically relied on imported packaging from Ho Chi Minh City corridors. A satellite two-piece can plant serving regional beverage distributors represents the most penetrable white-space opportunity. For Investors and Strategic Acquirers: Distressed-cycle entries favor diversified domestic converters with coating line assets in Bac Ninh and Hung Yen provinces, where legacy lacquer retrofit costs strain undercapitalized operators. Long-term viability hinges on circular economy compliance capabilities across the analysis window. Investors should monitor enforcement granularity around recycled content verification mechanisms as the primary inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive ingot-to-sheet capacity insulates Showa Aluminum from LME volatility and secures raw material stability. |
| Water-Based Coating Line Retrofit | Conversion from solvent-based systems ensures Ministry of Natural Resources and Environment compliance ahead of enforcement tightening. |
| Mass-Balance Certification Investment | Verified post-consumer scrap integration unlocks tax credits under Vietnam's Extended Producer Responsibility framework. |
| Digital Printing Workflow Deployment | UV-cured inkjet decoration enables short-run craft beer customization with reduced plate costs and faster turnaround. |
| Mekong Delta Satellite Plant | Localized two-piece can supply in Can Tho captures underpenetrated demand from regional beverage distributors. |
Research Methodology
Trade statistics from Vietnam Customs, ASEAN harmonization protocols, and LME price archives formed the secondary backbone, supplemented by primary interviews with coating line engineers, beverage procurement managers, and Ministry of Health food-contact regulators. Bottom-up and top-down triangulation validated volume estimates across substrate formats and end-use applications.
Bottom-up modeling aggregated plant-level capacity utilization and product mix data, while top-down cross-checks applied macroeconomic consumption coefficients across the projection horizon. Segmentation dimensions included substrate type, end-use vertical, coating chemistry tier, and regional production cluster. CAGRs derived from regression analysis against aluminum price trajectories and beverage bottler capex cycles.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement dates and potential bauxite-to-rolling greenfield investments. Forecasts reflect documented assumptions about circular economy roadmap implementation pace and ASEAN food-contact harmonization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
North America Metal Packaging Market
Metal Packaging
Brass Foils Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
Global Laminated Aluminium Foil Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
Tinplate Packaging Market
Metal Packaging
Novelty Tins Market
Metal Packaging
Asia-Pacific Metal Packaging Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
France Metal Packaging Market
Metal Packaging
Bi-Metal Cans Market
Metal Packaging
Metal Food Cans Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Egypt Metal Packaging Market