
 Japan Plastic Bottles Market | 2026-2036
Japan Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Plastic Bottles Market Insights
JIS S 2053 certification for plastic food contact containers is collapsing the supplier base for beverage-grade PET applications. Toyo Seikan Group Holdings leverages its integrated steel-and-plastics platform to sustain supply security across multiple prefectures. Yoshino Kogyosho anchors Japan's refillable bottle ecosystem through dedicated mold fabrication and closed-loop collection infrastructure. Takemoto Yohki competes by specializing in precision cosmetic bottles with proprietary surface treatment technologies.
Japan plastic bottles are hollow thermoplastic containers, typically blow-molded from polyethylene terephthalate or high-density polyethylene resin, engineered to withstand internal carbonation pressure up to 6 bar and maintain oxygen transmission rates below 0.04 cc per bottle per day. These vessels serve as primary packaging for carbonated soft drinks, functional beverages, liquid pharmaceuticals, and personal care formulations across retail and institutional channels. PET bottles occupy the dominant value position due to their clarity, lightweighting potential, and compatibility with existing Japanese recycling infrastructure. HDPE bottles sustain growth in pharmaceutical and household chemical segments where chemical resistance and moisture barrier properties outweigh optical requirements. The above 1L capacity tier leads volume throughput in beverage applications, while below 250ml formats concentrate margin pools in premium cosmetics and travel-size personal care.
METI's resource circulation roadmap and the Containers and Packaging Recycling Law shape material sourcing obligations, forcing converters to document post-consumer recycled content ratios and meet designated collection targets. PMDA guidelines for pharmaceutical primary packaging impose extractables and leachables testing protocols that extend qualification timelines for new bottle suppliers. The Act on Promotion of Resource Circulation further tightens design-for-recycling standards, compelling molders to eliminate problematic additives and standardize resin grades. Stakeholders must monitor whether upcoming revisions to the Containers and Packaging Recycling Law will mandate minimum recycled content thresholds that reshape procurement economics across the supply base.
Market Dynamics
METI's recycled content mandates under the Act on Promotion of Resource Circulation are restructuring converter procurement economics and forcing rapid qualification of post-consumer PET streams for food-contact applications.
Growth Catalysts
- Pharmaceutical packaging expansion:PMDA extractables and leachables protocols are extending qualification timelines, locking in qualified suppliers and creating durable revenue streams for compliant molders.
- Refillable bottle infrastructure:Dedicated mold fabrication and closed-loop collection systems in Chiba and Tokyo prefectures are reducing virgin resin dependence for beverage applications.
- Kanto industrial corridor concentration:Proximity to Tokyo's retail and institutional channels compresses logistics costs and enables just-in-time replenishment for carbonated soft drink bottlers.
Market Restraints
- rPET feedstock volatility:Post-consumer PET bale quality inconsistency and collection shortfalls inflate purification costs beyond virgin resin parity in some quarters.
- JIS S 2053 certification collapse:The standard's tightening is eliminating marginal suppliers and reducing buyer negotiating leverage for beverage-grade PET contracts.
- Aluminum can substitution:Beverage brands are diversifying into aluminum for premium positioning and extended shelf-life claims, compressing PET volume growth in functional drinks.
Strategic Opportunities
- Osaka-Kobe pharmaceutical cluster:Underpenetrated HDPE demand for liquid pharmaceuticals offers expansion paths beyond Kanto saturation.
- Cosmetic precision bottles:Surface treatment technologies for premium personal care formats command margin premiums above commodity beverage applications.
- Design-for-recycling standardization:METI's elimination mandates for problematic additives create first-mover advantages for converters with clean resin streams.
Industry Challenges
- Blow-mold technician scarcity:Specialized skills for high-speed stretch-blow equipment maintenance are concentrating at legacy converters, inflating wage premiums.
- Legacy mold asset stranding:Existing tooling for additive-heavy resin grades faces accelerated obsolescence under tightened recycling law revisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Plastic Bottles Market |
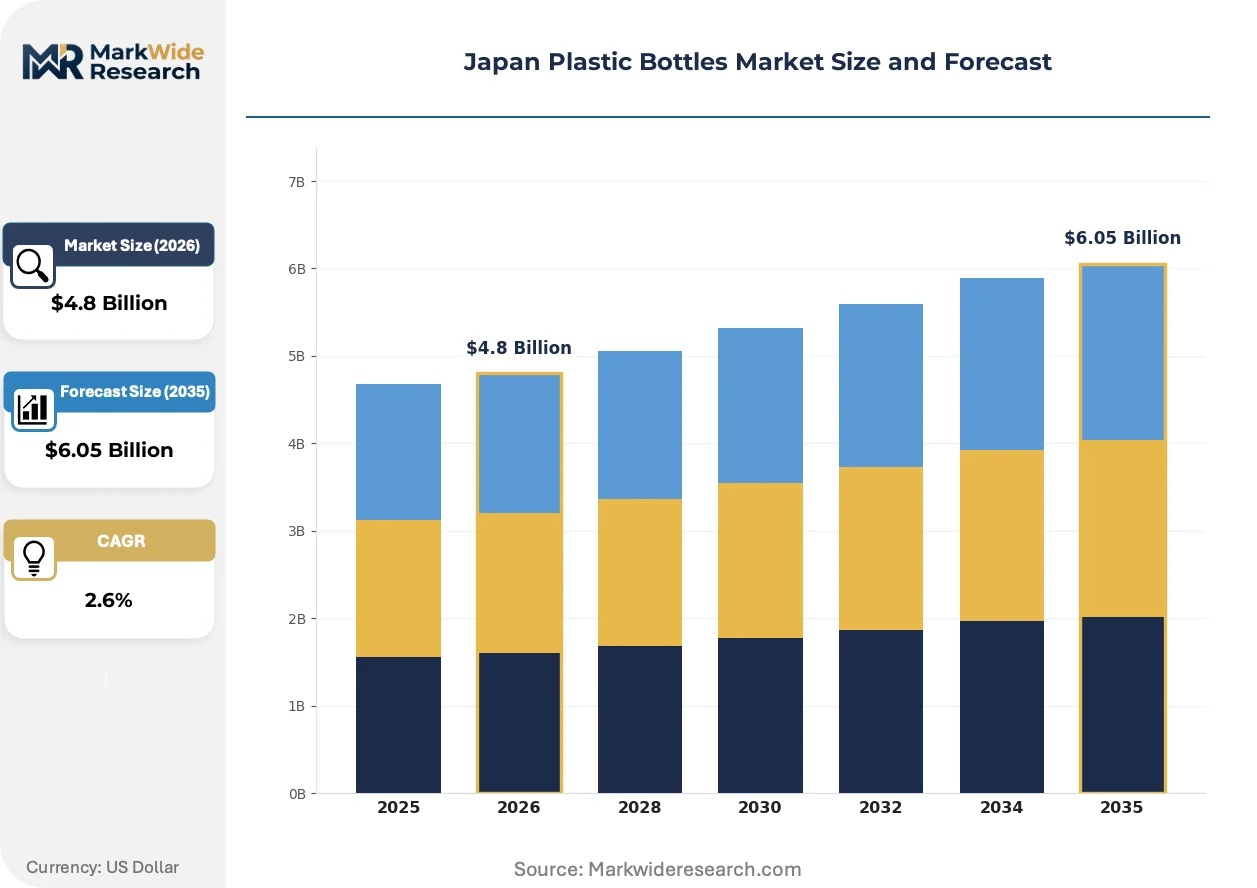
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.05 Billion |
| CAGR (2026 – 2036) | 2.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET Bottles, HDPE Bottles, PVC Bottles, Others End User: Beverage, Personal Care, Household, Pharmaceuticals Capacity: Below 250ml, 250ml-500ml, 500ml-1L, Above 1L Closure Type: Screw Caps, Flip Top Caps, Pump Dispensers, Others |
| Companies Covered | Takemoto Yohki Co., Ltd., Toyo Seikan Group Holdings, Ltd., Kodama Plastics Co., Ltd., Hosokawa Yoko Co., Ltd., Yoshino Kogyosho Co., Ltd., Nihon Yamamura Glass Co., Ltd., TSUKASA PETCO Corporation, Far Eastern Ishizuka Green PET Corporation, Amcor Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Plastic Bottles Market Trends and Innovations
Active barrier technologies and mono-material design protocols are displacing multi-layer constructions as METI tightens sorting compatibility requirements and brands face extended producer responsibility obligations.
Mono-material PET structures with passive oxygen scavenger integration are bifurcating the barrier packaging segment. Pharmaceutical primary packaging buyers are adopting these formats fastest, driven by PMDA leachables documentation burdens. The shift is compressing demand for ethylene vinyl alcohol coextrusion while expanding qualification work for single-resin alternatives.
METI's resource circulation roadmap is mandating documented post-consumer recycled content ratios across all designated packaging categories. Converters must now maintain chain-of-custody records from collection through reprocessing. The beverage segment faces the steepest compliance curves as major retail channels impose verification requirements beyond statutory minimums.
Buyer consolidation among Tokyo-based beverage distributors is compressing supplier counts and extending contract durations. Smaller regional brands are losing shelf access, forcing molders to absorb volume concentration risk or diversify into cosmetic and pharmaceutical channels. Chiba prefecture's logistics hub position is amplifying this consolidation dynamic for carbonated soft drink supply chains.
Japan Plastic Bottles Market Segmentation
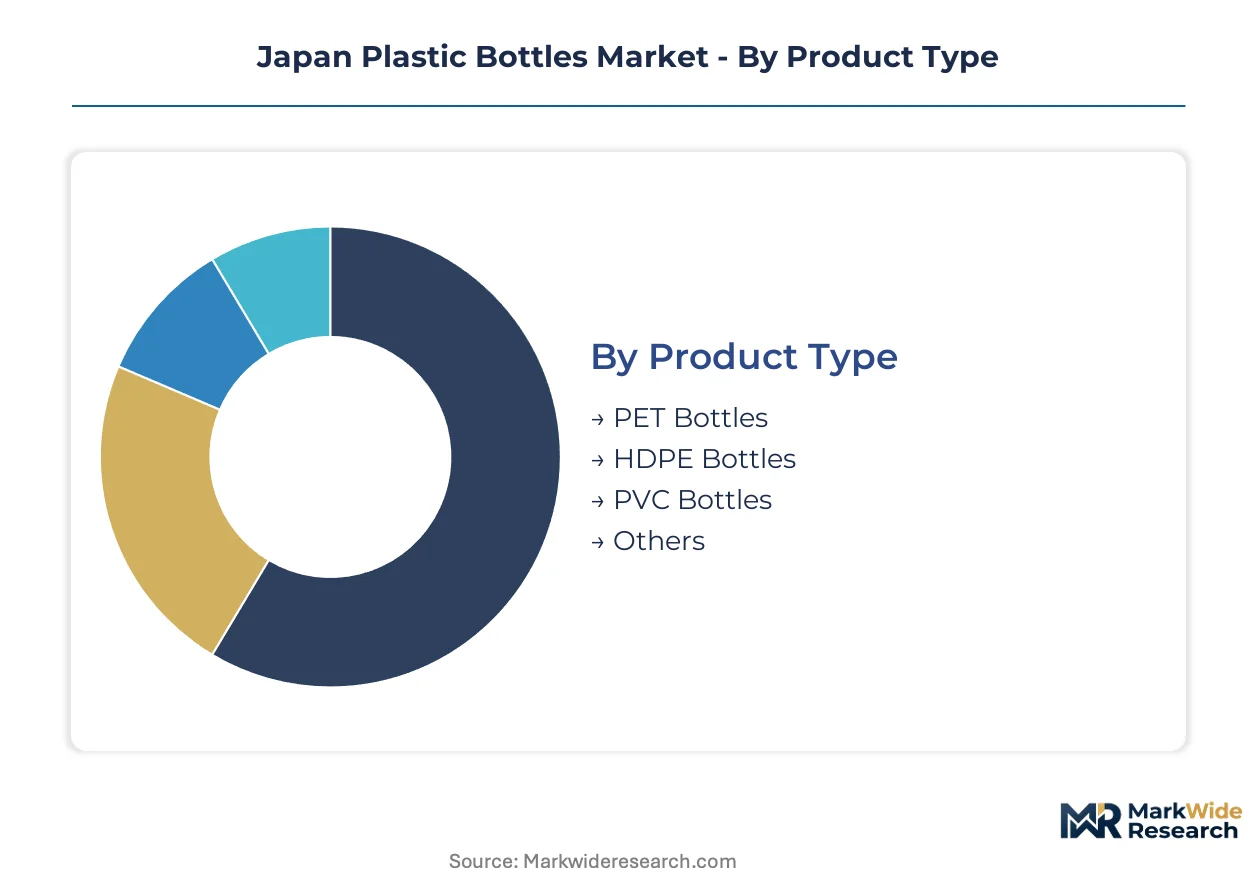
Segmentation reveals how METI regulations and substitution pressures fragment procurement economics across Japan's plastic bottle supply base. Material specifications, capacity tiers, and closure systems each face distinct compliance burdens and competitive threats from alternative packaging formats.
Product Type:
Aluminum can substitution pressure falls unevenly across resin categories, with carbonated beverage applications bearing the heaviest displacement risk while pharmaceutical and chemical resistance segments maintain structural insulation.
- PET Bottles:Blow-molded polyethylene terephthalate structures dominate carbonated soft drink and functional beverage applications through clarity and lightweighting potential. Kanto corridor bottlers concentrate procurement here, though aluminum encroachment in premium functional drinks compresses volume expansion.
- HDPE Bottles:High-density polyethylene resin delivers chemical resistance and moisture barrier properties for pharmaceutical primary packaging and household chemical formulations. PMDA extractables protocols extend qualification timelines, locking in compliant molders around Osaka-Kobe pharmaceutical clusters.
- PVC Bottles:Polyvinyl chloride constructions retain niche positions in specific chemical compatibility applications where plasticizer stability outweighs recycling infrastructure limitations.
- Others:Polypropylene and specialty resin formats serve constrained pharmaceutical and cosmetic segments requiring distinct barrier or sterilization compatibility profiles.
PET bottles anchor the volume base while HDPE bottles gain share at the steepest rate through pharmaceutical packaging expansion.
End User:
Margin tier differentiation separates commodity beverage procurement from precision cosmetic and regulated pharmaceutical applications, with certification burdens and surface treatment requirements stratifying converter economics.
- Beverage:Carbonated soft drinks and functional beverages drive throughput concentration in Chiba and Tokyo prefectures. METI recycled content mandates force rapid rPET stream qualification, while aluminum substitution erodes PET growth in premium positioning segments.
- Pharmaceuticals:Liquid drug primary packaging demands PMDA-compliant extractables and leachables documentation. Mono-material barrier adoption accelerates fastest here as EVOH coextrusion faces sorting compatibility penalties.
- Personal Care:Premium cosmetic bottles command margin premiums through proprietary surface treatment technologies and precision mold fabrication. Travel-size formats below 250ml concentrate margin pools away from commodity beverage economics.
- Household:Cleaning and chemical applications sustain HDPE demand where chemical resistance properties outweigh optical clarity requirements and recycling infrastructure compatibility matters less than functional performance.
Beverage applications anchor the volume base while pharmaceutical packaging gains share at the steepest rate through regulatory qualification barriers.
Capacity:
Volume throughput and margin concentration invert across capacity tiers, with large-format beverage applications running on thin conversion economics while small-format precision segments capture disproportionate value.
- Above 1L:Family-size carbonated soft drink and functional beverage formats dominate unit throughput in Kanto logistics corridors. Lightweighting pressure intensifies as resin cost volatility compresses already-thin conversion margins.
- Below 250ml:Travel-size personal care and premium cosmetic applications concentrate margin extraction through precision mold requirements and surface treatment complexity. Yoshino Kogyosho's refillable infrastructure targets this tier for closed-loop collection economics.
- 500ml-1L:Standard single-serve beverage and household chemical applications balance volume accessibility with logistics efficiency across retail and institutional channels.
- 250ml-500ml:Mid-range formats serve pharmaceutical unit-dose and personal care standard sizes where portability and handling convenience intersect with moderate precision requirements.
Above 1L formats anchor the volume base while below 250ml applications gain share at the steepest rate through premium cosmetic and travel-size personal care expansion.
Closure Type:
Application-specific dispensing requirements and child-resistance mandates fragment closure procurement, with pump and flip-top mechanisms commanding technical premiums over commodity screw formats.
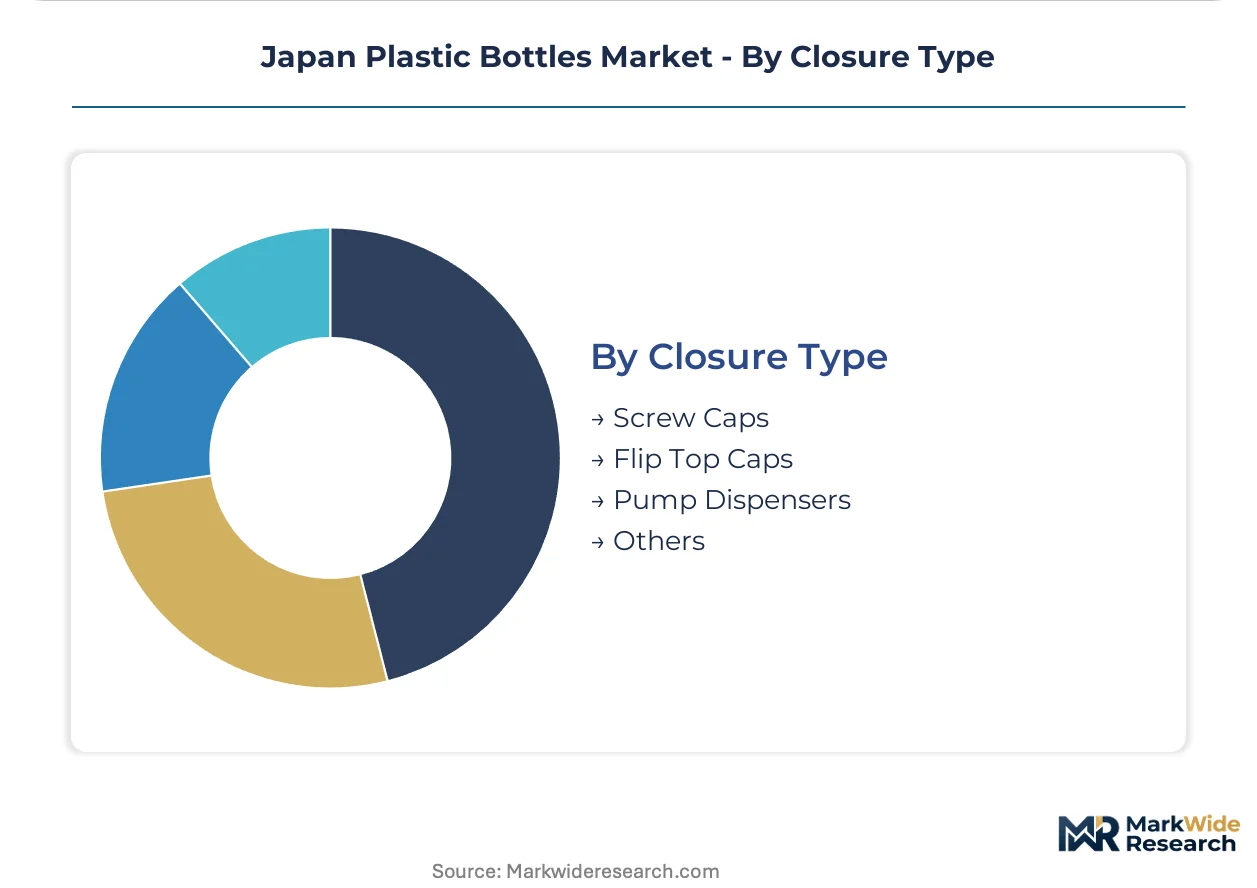
- Screw Caps:Standard threaded closures dominate beverage and basic household applications through cost efficiency and established capping line compatibility. Commoditization pressure intensifies as converter consolidation reduces supplier negotiating leverage.
- Pump Dispensers:Precision actuation mechanisms for personal care and pharmaceutical formulations require specialized mold fabrication and assembly integration. Takemoto Yohki's surface treatment expertise extends into closure compatibility for premium cosmetic positioning.
- Flip Top Caps:Single-handed dispensing convenience drives adoption in functional beverages and travel-size personal care, balancing accessibility with reseal integrity requirements.
- Others:Child-resistant and tamper-evident formats serve pharmaceutical compliance segments where PMDA guidelines impose specific functional certification burdens.
Screw caps anchor the volume base while pump dispensers gain share at the steepest rate through premium personal care and precision pharmaceutical packaging expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's resource circulation roadmap and recycled content mandates are redistributing plastic bottle demand across Japan's industrial corridors, with prefectural compliance capabilities becoming the primary location determinant.
Kanto/Tokyo
Carbonated soft drink bottlers and functional beverage distributors concentrate procurement in Chiba and Tokyo prefectures, drawn by compressed logistics costs and just-in-time replenishment infrastructure. The Containers and Packaging Recycling Law imposes designated collection targets that favor converters with established closed-loop systems. Toyo Seikan Group Holdings leverages integrated steel-and-plastics platforms to sustain supply security across multiple prefectures in this corridor.
Kansai/Osaka
Pharmaceutical primary packaging demand for liquid drugs drives HDPE bottle growth, with PMDA extractables and leachables protocols extending qualification timelines for new suppliers. The Osaka-Kobe pharmaceutical cluster remains underpenetrated relative to Kanto saturation, offering expansion paths for compliant molders. Kodama Plastics Co., Ltd. anchors regional supply capabilities through dedicated fabrication infrastructure.
Chubu/Nagoya
Automotive and industrial chemical applications sustain specialized HDPE demand where chemical resistance outweighs optical clarity requirements. Manufacturing supply chains for household cleaning products concentrate around Nagoya's logistics hub position. Regional converters face less stringent recycled content pressure than beverage-grade suppliers in Kanto.
Kyushu
Food processing and regional beverage brands generate mid-tier PET demand, though smaller scale limits converter investment in high-speed stretch-blow equipment. Collection infrastructure gaps for post-consumer PET bales inflate purification costs beyond virgin resin parity. Local molders compete on flexibility rather than volume throughput.
Hokkaido
Dairy and agricultural packaging applications sustain niche HDPE demand, with extended distribution distances to Honshu markets compressing margin structures. Cold chain requirements for fresh food exports create specialized barrier needs. Regional supply chains remain fragmented with limited rPET stream development.
Japan Plastic Bottles Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with JIS S 2053 compliance collapse eliminating marginal suppliers and reducing buyer negotiating leverage. The market structure concentrates around integrated packaging conglomerates with captive resin processing, mid-scale precision specialists serving pharmaceutical and cosmetic niches, and regional fabricators competing on logistics proximity. Dominant competitive moves include backward integration into mold fabrication and strategic partnerships with retail distributors for closed-loop collection infrastructure.
Within the integrated conglomerate tier, Toyo Seikan Group Holdings exemplifies scale-driven positioning through diversified material platforms, while Yoshino Kogyosho Co., Ltd. occupies a specialist role in refillable bottle ecosystems. Among precision-focused fabricators, Takemoto Yohki Co., Ltd. represents the cosmetic and pharmaceutical packaging archetype with proprietary surface treatment positioning. These three entities collectively illustrate how certification burdens and recycled content mandates stratify competitive capabilities across Japan's plastic bottle supply base.
| Leading Market Players |
|---|
| Takemoto Yohki Co., Ltd. |
| Toyo Seikan Group Holdings, Ltd. |
| Kodama Plastics Co., Ltd. |
| Hosokawa Yoko Co., Ltd. |
| Yoshino Kogyosho Co., Ltd. |
| Nihon Yamamura Glass Co., Ltd. |
| TSUKASA PETCO Corporation |
| Far Eastern Ishizuka Green PET Corporation |
| Amcor Plc |
| Others |
Pricing and Supply Chain Analysis
Aluminum can substitution in premium functional beverages simultaneously compresses PET bottle pricing power in Kanto corridor bottling contracts and accelerates geographic consolidation toward Chiba prefecture's integrated logistics hubs. This displacement dynamic forces converters to absorb margin compression or absorb volume concentration risk from consolidating Tokyo-based beverage distributors.
Pricing Analysis
Certification level under JIS S 2053 and PMDA pharmaceutical compliance creates the primary spread between premium and commodity tiers. Three-tier pricing structure across pharmaceutical-grade, beverage-grade, and industrial-grade resin specifications stratifies converter economics. Cost compression in above-1L beverage formats is intensifying because rPET feedstock volatility inflates purification costs beyond virgin resin parity. Beverage bottlers exhibit highest price sensitivity due to thin conversion margins, while pharmaceutical buyers prioritize qualification security over unit cost.
Supply Chain Analysis
Just-in-time replenishment preferences among Tokyo-based beverage distributors dominate downstream logistics, compressing inventory buffers and amplifying disruption sensitivity. Resin supply concentrates in domestic petrochemical complexes around Chiba and Yokkaichi, with post-consumer PET bale collection feeding regional reprocessing infrastructure. The supply chain rests on purified terephthalic acid and ethylene glycol feedstocks sourced from integrated refining operations. Single-source vulnerability to rPET bale quality inconsistency threatens converter qualification timelines. Distribution runs through dedicated logistics corridors linking Chiba molding facilities to Kanto retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's plastic bottle market requires substitution defense against aluminum can encroachment in premium beverage positioning, compelling strategic repositioning across all stakeholder tiers.
For Market Incumbents: Consolidate mold fabrication capabilities and closed-loop collection infrastructure to defend against rPET feedstock volatility and JIS S 2053 certification collapse. Backward integration into dedicated resin reprocessing secures supply continuity as METI mandates tighten. Lock in pharmaceutical qualification barriers through PMDA extractables documentation investments. For New Entrants and Emerging Players: Lead with precision cosmetic bottles and surface treatment technologies to bypass commodity beverage saturation. The Osaka-Kobe pharmaceutical cluster offers underpenetrated HDPE demand with extended qualification timelines protecting compliant molders. Partner with regional distributors for closed-loop collection infrastructure rather than competing on volume throughput. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision specialists with captive certification capabilities over commodity volume players. Long-term viability hinges on regulatory compliance moats rather than scale economics. Watch for METI revisions to the Containers and Packaging Recycling Law as the inflection signal for minimum recycled content threshold impacts. Revision becomes warranted when aluminum substitution rates in functional beverages cross structural volume thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Stream Qualification Investment | METI mandates force rapid food-contact approval for post-consumer resin sources. |
| Mold Fabrication Backward Integration | Yoshino Kogyosho's captive tooling secures refillable bottle ecosystem control. |
| Osaka-Kobe Pharmaceutical Expansion | PMDA protocols extend qualification timelines, locking in compliant HDPE suppliers. |
| Surface Treatment Technology Acquisition | Takemoto Yohki's proprietary coatings command premium cosmetic positioning. |
| Closed-Loop Collection Partnership | Chiba logistics hubs enable just-in-time replenishment for Kanto bottlers. |
Research Methodology
Initial hypotheses were tested against primary input from blow-mold technicians, beverage procurement managers, pharmaceutical packaging engineers, and METI regulatory officials and refined through secondary validation. Primary fieldwork combined structured interviews with converter operations heads and distributor logistics planners. Secondary sources included JIS standard documentation, PMDA pharmaceutical packaging guidelines, METI resource circulation white papers, and prefectural industrial statistics. Bottom-up volume modeling triangulated against top-down resin consumption data.
Variance decomposition across material type, end-use segment, capacity tier, and closure mechanism isolates growth drivers from substitution effects. Segmentation dimensions modeled include resin grade specifications, pharmaceutical versus beverage versus cosmetic end-use applications, and regional production cluster economics. CAGRs were derived from trend extrapolation of resin consumption patterns and qualification timeline impacts. Industry-specific inputs incorporated PMDA extractables protocol delays and aluminum can substitution elasticity estimates.
Forecasts assume regulatory continuity in METI resource circulation mandates and PMDA pharmaceutical packaging standards; material policy shifts would require re-modeling. Specific risks include accelerated aluminum substitution in functional beverages, rPET bale collection shortfalls, and JIS S 2053 standard revisions eliminating additional suppliers. Revision becomes warranted when aluminum substitution rates or recycled content mandate thresholds cross modeled sensitivity bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
Plastic Corrugated Sheets Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market