
 Disposable Straw Market | 2026-2036
Disposable Straw Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Straw Market Outlook
A capital-intensity divergence between integrated pulp processors and specialty converters is rotating competitive dynamics in the disposable straw sector. Huhtamaki leverages its molded-fiber infrastructure across European beverage packaging lines. Footprint anchors its position through proprietary plant-based polymer chemistry. Transcend Packaging competes from UK-based paper straw manufacturing scaled for quick-service restaurant supply chains.
Disposable straws are single-use tubular implements, typically 6–10 millimeters in diameter and 150–250 millimeters in length, engineered for liquid conveyance in foodservice and consumer settings. Paper material straws lead volume in regions with plastic restriction mandates, while bamboo variants command premium positioning in specialty cafes. Jumbo-size straws sustain margin pools in bubble-tea and smoothie segments where structural integrity requirements exceed standard specifications. Restaurants dominate end-user procurement through contracted distributor relationships.
FDA food-contact substance regulations govern cellulose and biopolymer safety in the US market, while the EU Single-Use Plastics Directive mandates member-state phaseouts of conventional plastic straws. BIS certification requirements in India shape import access for foreign paper straw suppliers. Stakeholders must monitor evolving compostability standards across jurisdictions to align material portfolios with enforcement timelines.
Market Dynamics
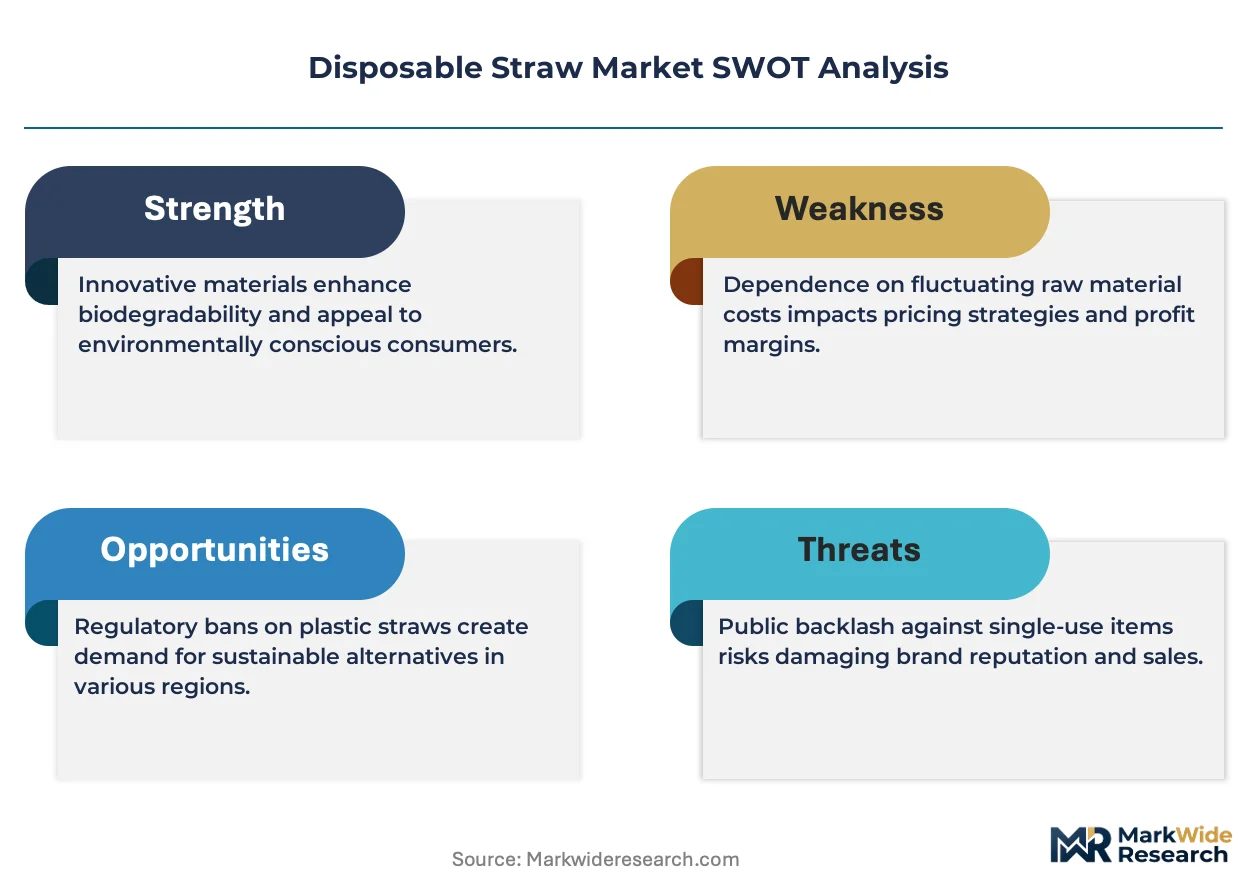
Single-use plastic prohibition mandates across multiple jurisdictions are forcing material substitution at scale, redirecting procurement flows toward cellulose and biopolymer alternatives while compressing polypropylene straw volumes in regulated corridors.
Growth Catalysts
- EU Single-Use Plastics Directive:Member-state phaseout enforcement is mandating foodservice transitions to paper and biopolymer straws, eliminating incumbent plastic supply from quick-service restaurant chains.
- Cellulose fiber processing:Advanced pulping technologies are enabling structural integrity in cold-beverage applications previously dominated by petroleum-based polymers.
- Ho Chi Minh City manufacturing cluster:Export-oriented paper straw production capacity is scaling to serve North American foodservice distributor procurement contracts.
Market Restraints
- Pulp input cost volatility:Bleached kraft fiber prices fluctuate with regional timber harvest cycles, squeezing converter margins during supply tightness.
- Supply concentration in Southeast Asia:Overreliance on Vietnamese and Indonesian contract manufacturers creates geopolitical and logistics risk for North American buyers.
- Structural integrity limitations:Extended immersion in acidic or carbonated beverages degrades uncoated paper straw performance, restricting application scope.
Strategic Opportunities
- India foodservice penetration:BIS certification pathways for imported paper straws remain underdeveloped, creating first-mover positioning for compliant foreign suppliers.
- Compostability certification alignment:Home-compostable biopolymer formulations meeting evolving EU EN 13432 standards command premium placement in sustainability-focused retail channels.
- Bubble-tea segment specialization:Jumbo-diameter structural designs for tapioca pearl beverages represent underserved specification demand in East Asian and North American urban markets.
Industry Challenges
- Composting infrastructure mismatch:Industrial composting facility availability lags biopolymer straw deployment in many municipalities, creating disposal confusion and consumer backlash.
- Coating chemistry compliance:PFAS-free barrier formulations must satisfy FDA food-contact substance regulations while maintaining liquid resistance, extending R&D validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Straw Market |
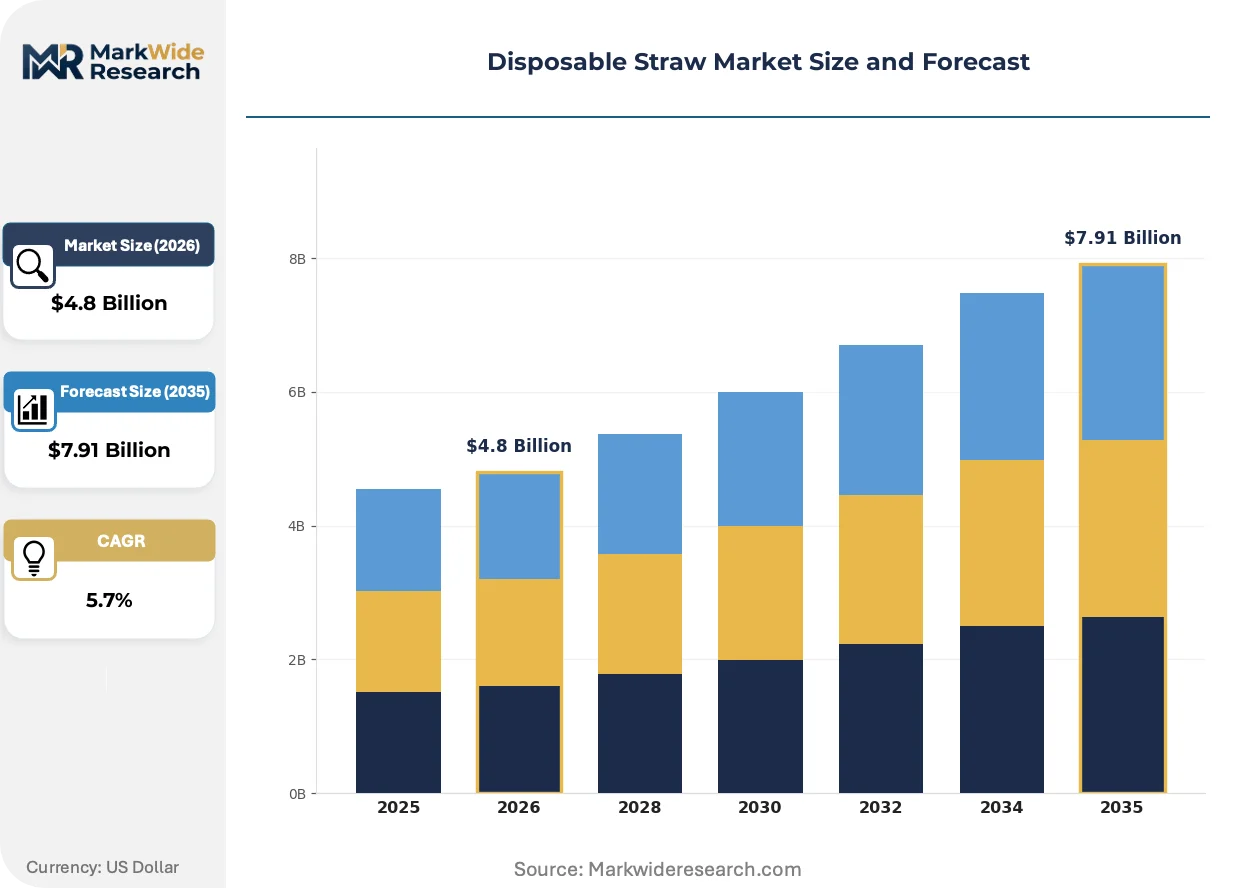
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Bamboo, Metal End User: Restaurants, Cafes, Catering Services, Household Size: Regular, Jumbo, Cocktail, Kids Distribution Channel: Online, Retail Stores, Wholesalers, Supermarkets |
| Companies Covered | Huhtamaki, Aardvark Straws, BioPak, Transcend Packaging, Hoffmaster Group, Footprint, Vegware, Eco-Products, Novolex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Straw Market Strategic Shifts
Material science breakthroughs and enforcement acceleration are converging to reshape competitive positioning, with functionality gaps narrowing between sustainable alternatives and conventional plastics.
Barrier-coated molded-fiber technology is fragmenting the cold-beverage straw category. Quick-service restaurant chains in Germany and France are adopting aqueous-coated cellulose designs for fountain drink applications. The technology is fragmenting incumbent polypropylene market share by eliminating the performance gap that previously justified plastic retention.
REACH chemical restriction expansions are tightening polymer additive scrutiny across European supply chains. Manufacturers face reformulation costs for colorants and slip agents previously grandfathered under legacy registrations. Biopolymer straw producers in the Netherlands and Belgium are accelerating third-party compostability certification to preempt regulatory exclusion.
Direct-procurement platforms are disintermediating traditional foodservice distributors for straw replenishment. Mid-sized restaurant groups in California and New York are contracting specialty converters through digital sourcing channels. This pattern concentrates most visibly in coastal metropolitan markets where sustainability procurement officers hold centralized purchasing authority.
Disposable Straw Market Segmentation
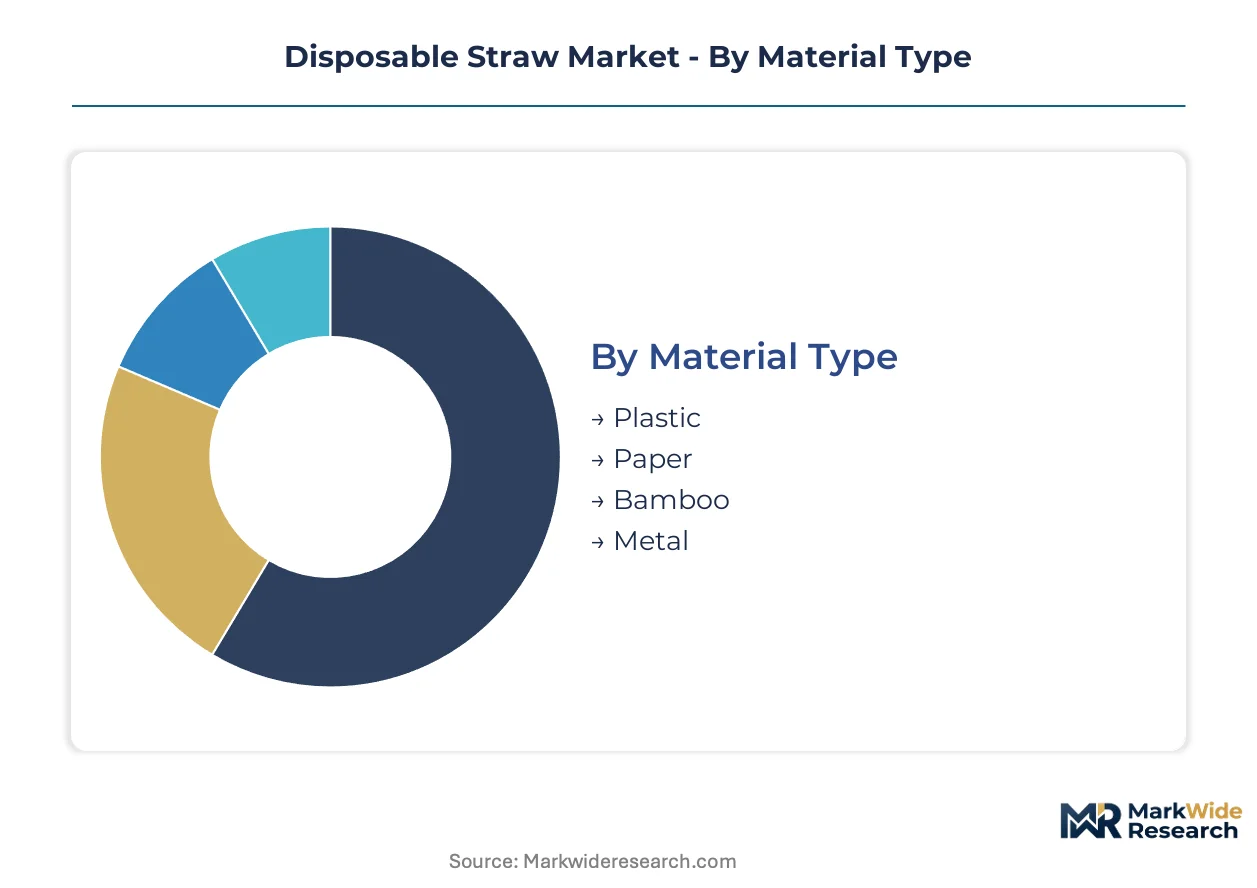
Material composition dictates regulatory compliance pathways and margin structures across the disposable straw sector. End-use concentration and size specifications further fragment procurement patterns by application durability requirements and beverage viscosity.
Material Type:
EU Single-Use Plastics Directive enforcement and FDA food-contact substance regulations create divergent compliance burdens across material categories, reshaping supply chain economics.
- Paper:Bleached kraft fiber construction with aqueous or PLA barrier coatings satisfies EU member-state plastic prohibitions. Demand concentrates in German and French quick-service restaurant chains where fountain drink applications require cold-beverage structural integrity. Pulp input cost volatility from Nordic timber harvest cycles squeezes converter margins during supply tightness.
- Plastic:Polypropylene and polylactic acid formulations retain residual share in jurisdictions without enforcement infrastructure. Procurement persists in US states lacking statewide single-use plastic mandates, though municipal bans in California and New York compress volumes. REACH chemical restriction expansions in Europe tighten additive scrutiny for colorants and slip agents.
- Bamboo:Laminated grass fiber construction commands premium positioning in specialty cafe channels with sustainability procurement officers.
- Metal:Stainless steel and aluminum reusable variants serve counter-service retail with deposit-return schemes in Scandinavian urban markets.
Paper handles the majority of throughput; bamboo is expanding most quickly on share in premium foodservice channels.
End User:
Contracted distributor relationships versus direct-procurement platforms create divergent customer acquisition economics across buyer scale tiers.
- Restaurants:Full-service and quick-service chains procure through national foodservice distributors with sustainability specifications written into master agreements. California and New York metropolitan markets show accelerating direct-converter contracting through digital sourcing channels.
- Cafes:Independent specialty coffee operators prioritize aesthetic differentiation and compostability certification alignment for brand positioning.
- Catering Services:Event-based procurement demands bulk packaging efficiency and rapid replenishment logistics for seasonal volume spikes.
- Household:Retail-packaged straw consumption concentrates in supermarket private-label programs with home-compostable claims.
Restaurants dominate absolute volume; cafes are climbing the fastest on sustainability-premium capture.
Size:
Structural integrity requirements scale non-linearly with diameter, fragmenting manufacturing tooling and coating chemistry investments.
- Jumbo:10–12 millimeter diameter specifications sustain margin pools in bubble-tea and smoothie segments where tapioca pearl conveyance demands superior crush resistance. Ho Chi Minh City manufacturers specialize in reinforced paper constructions for North American East Asian foodservice export.
- Regular:6–8 millimeter standard specifications serve fountain drink and water applications with highest volume throughput.
- Cocktail:Narrow 4–5 millimeter diameters for mixed beverage service require precise cut tolerance for aesthetic consistency.
- Kids:Shortened 120–150 millimeter lengths with flexi-bend designs target child-safety specifications in family restaurant chains.
Regular size commands the steepest volume trajectory; jumbo specifications gain share fastest on margin expansion.
Distribution Channel:
Channel concentration determines working capital intensity and sustainability certification verification burdens for suppliers.
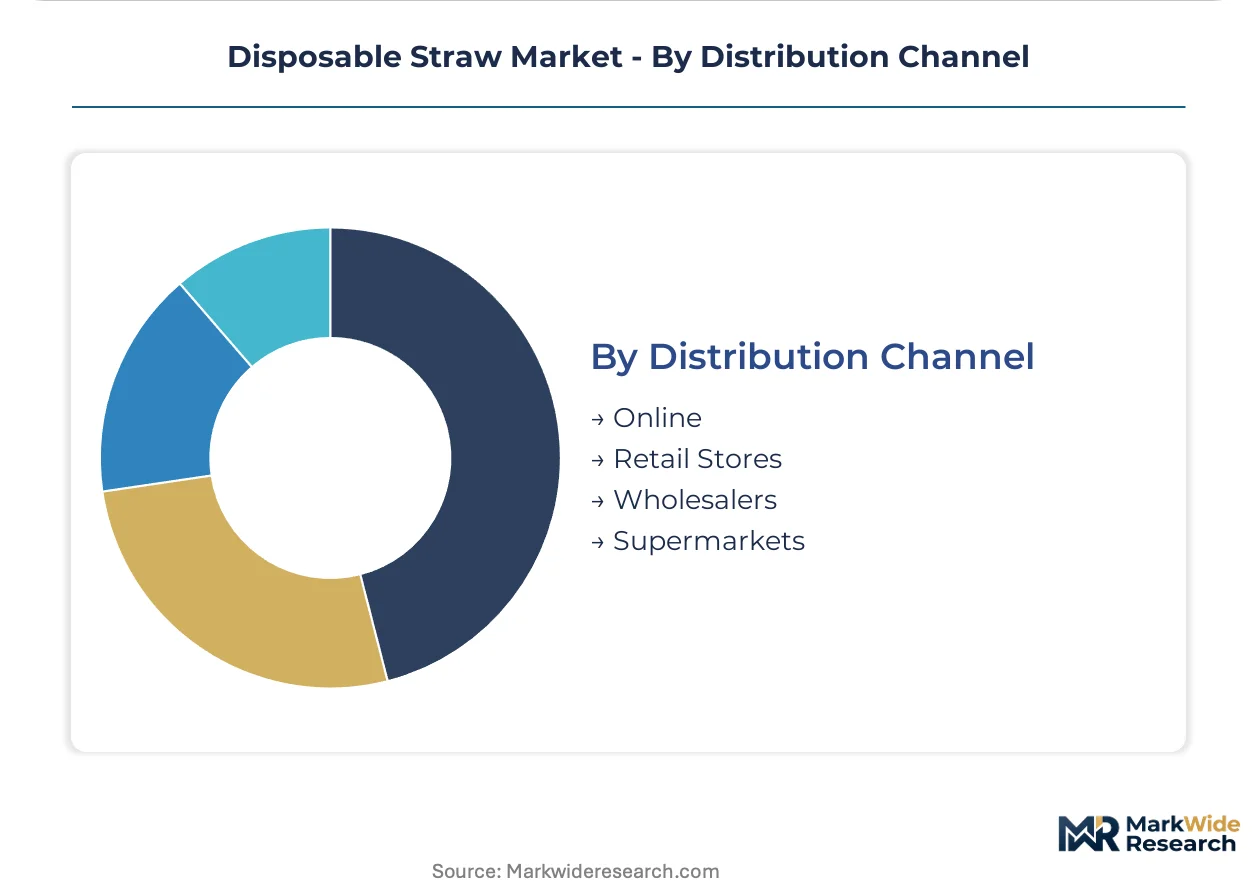
- Wholesalers:Traditional foodservice distributors consolidate procurement for mid-sized restaurant groups with private-label straw programs. Inventory pooling across multiple SKUs reduces per-unit logistics costs for cellulose-based alternatives.
- Online:Direct-procurement platforms disintermediate distributor markups for sustainability-focused buyers with centralized purchasing authority.
- Retail Stores:Convenience and drugstore channels stock impulse-purchase straw packs with minimal sustainability claims.
- Supermarkets:Grocery private-label programs demand third-party compostability certification and bulk packaging efficiency.
Wholesalers retain the dominant throughput position; online channels show the steepest expansion trajectory on disintermediation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese contract manufacturers command pricing leverage over North American foodservice buyers due to concentrated paper straw production capacity, while fragmented EU converter networks absorb pulp cost volatility through regional sourcing diversification.
United States
California and New York municipal bans compress polypropylene straw volumes while quick-service chains accelerate paper procurement through direct-converter digital platforms. FDA food-contact substance regulations govern cellulose and biopolymer safety compliance for interstate commerce. Ho Chi Minh City manufacturers ship reinforced paper constructions to East Asian foodservice distributors serving Los Angeles and New York metropolitan markets.
Germany
Quick-service restaurant chains adopt aqueous-coated cellulose designs for fountain drink applications, fragmenting incumbent plastic market share. EU Single-Use Plastics Directive enforcement mandates member-state phaseouts of conventional plastic straws with binding reduction targets. REACH chemical restriction expansions tighten polymer additive scrutiny for colorants and slip agents across converter supply chains.
France
Specialty cafe channels with sustainability procurement officers drive premium positioning for bamboo and compostable biopolymer variants. ANSM and CNIL frameworks intersect with EU-wide packaging waste directives to shape compliance pathways. Paris metropolitan foodservice clusters source through national distributors with sustainability specifications written into master agreements.
Vietnam
Export-oriented paper straw production scales to serve North American foodservice distributor procurement contracts with cost-competitive bleached kraft fiber construction. BIS certification requirements in neighboring India shape regional export strategy for cross-border market access. Ho Chi Minh City manufacturing corridor concentrates reinforced jumbo-diameter capacity for bubble-tea segment export demand.
India
Foodservice penetration accelerates as BIS certification pathways for imported paper straws remain underdeveloped, creating first-mover positioning opportunities. FSSAI regulations govern food-contact material safety while DGFT import policies shape foreign supplier market access. Maharashtra and Gujarat industrial corridors develop domestic converter capacity to reduce reliance on Southeast Asian contract manufacturing.
Disposable Straw Market Competitive Environment
Concentration sits with integrated pulp processors and specialty converters competing through capital-intensity divergence rather than scale consolidation. The vendor base splits between molded-fiber infrastructure owners, proprietary plant-based polymer chemists, and scaled paper straw manufacturers serving quick-service supply chains. Three archetypes dominate: European biotech innovators, Southeast Asian export-oriented fabricators, and North American sustainability-focused converters. Competitive moves center on compostability certification alignment and direct-procurement platform partnerships to disintermediate traditional distributors.
Among European integrated packaging groups, Huhtamaki leverages molded-fiber infrastructure across beverage packaging lines, representing the capital-intensive processor archetype. Transcend Packaging occupies a position within UK-based paper straw manufacturing scaled for quick-service restaurant supply chains. Footprint anchors the proprietary chemistry tier through plant-based polymer formulation capabilities.
| Leading Market Players |
|---|
| Huhtamaki |
| Aardvark Straws |
| BioPak |
| Transcend Packaging |
| Hoffmaster Group |
| Footprint |
| Vegware |
| Eco-Products |
| Novolex |
| Others |
Value Chain & Pricing Dynamics
Cellulose fiber substitution for polypropylene simultaneously relocates production gravity toward Vietnamese contract manufacturers and compresses margin pools for converters lacking pulp-processing integration. This displacement dynamic concentrates pricing power with integrated pulp processors while fragmenting converter profitability across specialty coating chemistries.
Pricing Analysis
The customization-premium spread between jumbo-diameter bubble-tea specifications and standard fountain-drink straws spans roughly three performance tiers. Pricing stratifies across premium aqueous-coated constructions, standard PLA-barrier designs, and economy uncoated kraft variants. Cost compression in the economy tier is intensifying because Nordic pulp cost volatility squeezes non-integrated converters. Quick-service restaurant chains exhibit lowest price sensitivity through volume-contracted procurement, while independent cafes negotiate hardest on per-unit costs.
Supply Chain Analysis
Inventory-strategy preferences split between just-in-time replenishment for quick-service distributor contracts and strategic stockpiling by North American buyers hedging Southeast Asian logistics risk. Supply concentrates in Vietnam, Indonesia, and India for finished straw fabrication, with bleached kraft pulp feeding from Nordic and Brazilian timber sources. Single-source vulnerability runs through the Ho Chi Minh City manufacturing corridor where export capacity is tethered to containerized shipping lanes. Distribution runs through national foodservice distributors consolidating procurement for mid-sized restaurant groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-procurement platform economics are disintermediating traditional distributor relationships, creating interoperability advantages for converters with digital channel integration and sustainability certification transparency.
For Market Incumbents: Shield market position by deepening backward integration into Nordic pulp supply and accelerating PFAS-free barrier R&D validation. The threat of aqueous-coated molded-fiber technology from European biotech firms compresses polypropylene retention justification. Capacity consolidation in Vietnam's manufacturing corridor provides cost leverage against emerging regional competitors.
For New Entrants and Emerging Players: Lead with BIS certification pathway navigation for India's underdeveloped import compliance infrastructure. The most penetrable white space sits in jumbo-diameter reinforced paper constructions for East Asian bubble-tea export demand. A digital-first go-to-market angle targeting California and New York sustainability procurement officers bypasses incumbent distributor lock-in.
For Investors and Strategic Acquirers: The market sits at a material-substitution acceleration phase that favors integrated pulp processors with compostability certification alignment. Long-term viability over the next decade hinges on regulatory enforcement durability across EU member states and US municipal jurisdictions. Acquisition targets should demonstrate proprietary coating chemistry and direct-procurement platform partnerships. The signal to watch is industrial composting facility buildout velocity in major metropolitan markets.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Barrier R&D Investment | FDA food-contact compliance unlocks quick-service restaurant procurement contracts. |
| Backward Integration into Pulp Supply | Nordic timber sourcing agreements insulate converters from kraft fiber cost volatility. |
| Direct-Procurement Platform Partnership | Digital channel integration disintermediates foodservice distributor markups for sustainability buyers. |
| Home-Compostability Certification Alignment | EU EN 13432 compliance commands premium placement in retail private-label programs. |
| Jumbo-Diameter Capacity Expansion | Reinforced structural designs capture bubble-tea segment margin pools in North American urban markets. |
Study Parameters
A standing panel of foodservice procurement directors, pulp converter operations managers, sustainability certification auditors, and quick-service restaurant supply chain executives provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from EU Single-Use Plastics Directive enforcement tracking, FDA food-contact substance filings, BIS import certification databases, and Nordic timber harvest cycle reports. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Consistency checks validated projection outputs against external benchmarks including customs trade data for bleached kraft fiber movements and foodservice distributor procurement disclosures. The analytical framework segmented across material composition, end-user scale tier, diameter specification, and distribution channel complexity throughout the forecast period. CAGRs derived from regression analysis of substitution elasticity between cellulose and petroleum-based polymers, with pulp cost volatility and regulatory enforcement timelines as key model inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU directive enforcement or accelerated US municipal ban adoption would require recalibration. Forecasts reflect documented assumptions regarding composting infrastructure buildout and coating chemistry validation timelines. Revision becomes warranted when industrial composting facility availability crosses critical mass thresholds in major metropolitan markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
PCR Films Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
South Africa Plastic Bottles Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Egypt Plastic Bottles Market
Plastic Packaging
China Plastic Bottles Market