
 Cast Stretch Films Market | 2026-2036
Cast Stretch Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Stretch Films Market Analysis
ISO 9001 quality management certification is bifurcating the competitive landscape between qualified suppliers and commodity producers. Berry Global Inc leverages vertical integration across resin sourcing and film extrusion to sustain cost leadership in North America. Manuli Stretch anchors its position through specialized machine-grade formulations designed for high-speed automated wrapping lines in European distribution centers.
Cast stretch films are linear low-density polyethylene (LLDPE) or low-density polyethylene (LDPE) films manufactured through flat-die extrusion with subsequent stretching to achieve controlled cling and puncture resistance, primarily employed for unitizing palletized goods during transit and storage. Machine grade films dominate volume consumption in automated logistics hubs where throughput velocity determines operational economics, while specialty films containing metallocene catalyst resins capture premium margin pools in temperature-sensitive pharmaceutical distribution. LLDPE formulations lead material selection due to superior elongation properties, though HDPE blends are penetrating heavy-load industrial segments where puncture strength outweighs cost sensitivity.
REACH substance restrictions in Europe and FDA food-contact notification requirements in the United States govern monomer migration limits and additive compositions, compelling reformulation investments among resin suppliers and film converters. The EU Packaging and Packaging Waste Regulation is accelerating mechanical recycling content mandates, reshaping procurement specifications for retail and food service buyers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between virgin resin optimization or recycled feedstock integration strategies before compliance deadlines crystallize.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing resin suppliers and film converters to reconfigure feedstock strategies ahead of mechanical recycling content mandates, bifurcating procurement specifications between virgin-optimized and recycled-integrated supply chains.
Growth Catalysts
- Automated Warehouse Expansion:Food and beverage distributors across Germany's industrial corridor are standardizing machine-grade film specifications for high-velocity palletization, pulling demand toward puncture-resistant LLDPE formulations.
- REACH Compliance:ECHA substance restrictions on monomer migration limits are compelling material purity investments that qualified suppliers leverage to capture share from commodity producers.
- Metallocene Catalyst Adoption:Temperature-sensitive pharmaceutical distributors are specifying metallocene-based specialty films for cold-chain unitization, opening premium margin pools beyond standard logistics applications.
Market Restraints
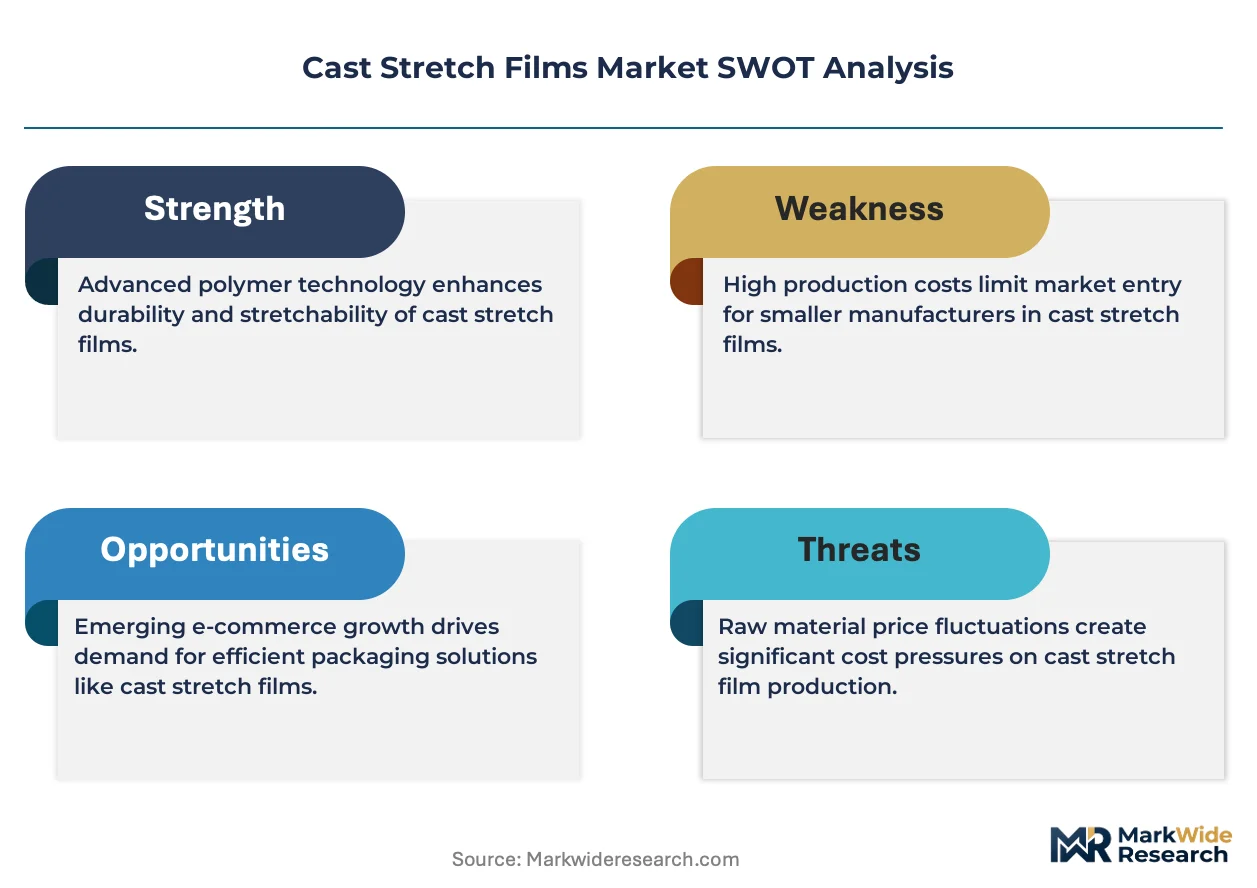
- Ethylene Feedstock Volatility:LLDPE and LDPE resin prices fluctuate with naphtha-cracker economics, compressing converter margins during upstream petrochemical cycles.
- European Supply Concentration:Machine-grade film production clusters along the Rhine-Ruhr corridor, exposing buyers to single-source risk during regional logistics disruptions.
- Technical Load-Cap Limitations:Standard cast films face substitution pressure from HDPE blends in heavy-load industrial segments where puncture strength requirements exceed elongation performance.
Strategic Opportunities
- Recycled Content Integration:The EU Green Deal's circular economy action plan creates procurement advantages for converters achieving 30%+ post-consumer recycled content ahead of 2030 mandates.
- Pharmaceutical Cold-Chain Expansion:Biologics distribution networks in Switzerland and the Netherlands are adopting multi-layer barrier films for temperature-validated pallet unitization.
- Digital Inventory Integration:RFID-enabled stretch films are converging with warehouse management systems, enabling real-time load tracking for automotive just-in-sequence suppliers.
Industry Challenges
- ISO 9001 Certification Timeline:Mid-scale converters face 12-18 month quality management system implementation cycles to qualify for automated logistics hub supplier lists.
- Legacy Extrusion Asset Reconfiguration:Flat-die lines require substantial capital modification to process mechanically recycled feedstock without optical defect generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Stretch Films Market |
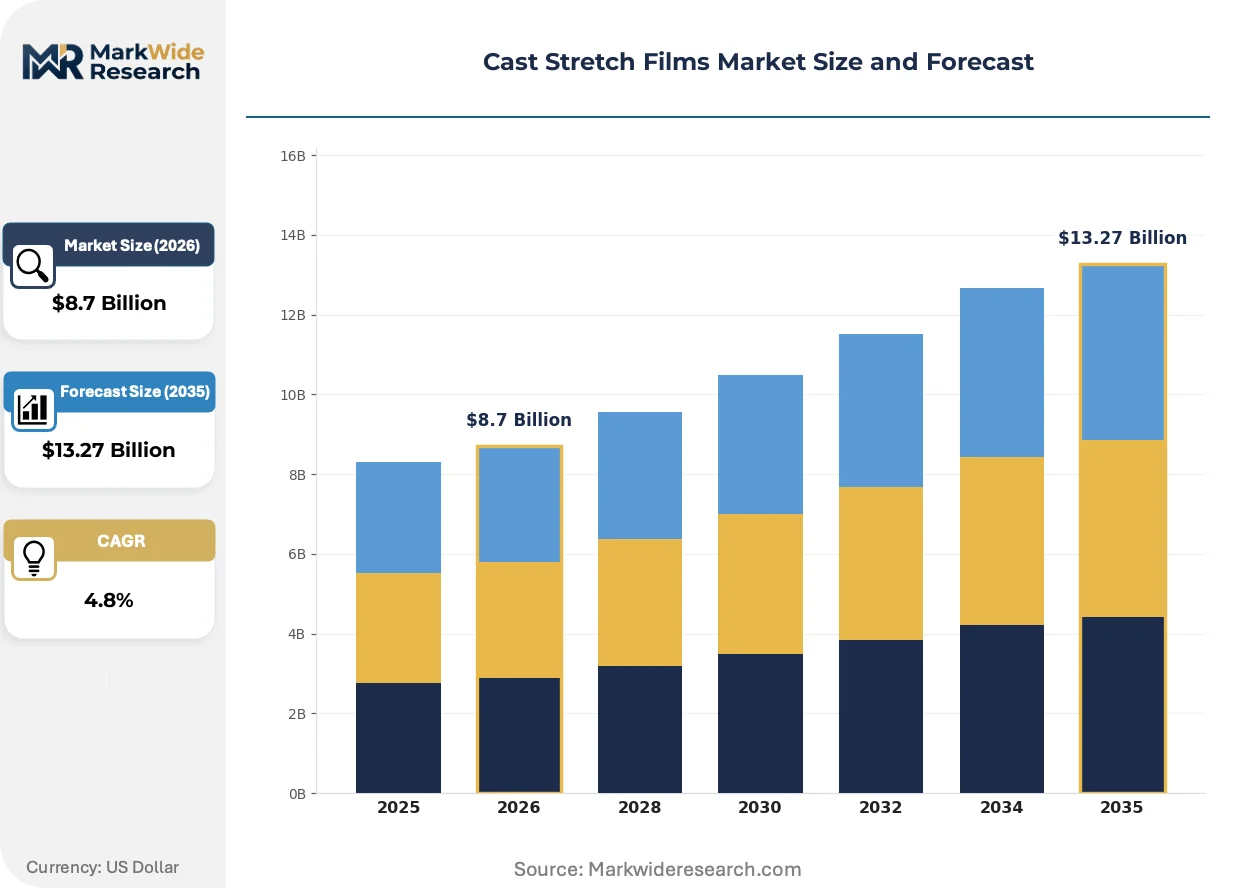
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Grade, Machine Grade, Pre-Stretch, Specialty Material: LDPE, LLDPE, HDPE, PVC End User: Food & Beverage, Retail, Healthcare, Industrial Packaging Type: Roll, Shrink Wrap, Pallet Wrap, Bundling |
| Companies Covered | Berry Global Inc, Sigma Plastics Group, Intertape Polymer Group, AEP Industries, Paragon Films, Manuli Stretch, Amcor Plc, Inteplast Group, Borealis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Stretch Films Market Emerging Trajectories
Material science advances and regulatory compliance pressures are restructuring competitive advantage around feedstock traceability, film functionalization, and integration with automated material handling systems.
Metallocene-grade LLDPE resins are supplanting conventional Ziegler-Natta formulations in temperature-sensitive pharmaceutical distribution. Cold-chain logistics operators in Switzerland and the Netherlands specify these materials for validated thermal performance. The shift is compressing commodity resin margins while rewarding converters with pharmaceutical certification capabilities.
REACH substance restrictions are tightening additive composition limits for cling agents and slip additives. ECHA evaluations of plasticizer migration are compelling reformulation investments among European resin suppliers. Food-contact film converters in Germany and France are accelerating non-phthalate additive qualification programs to maintain FDA and EFSA dual compliance.
Consolidated buying by third-party logistics providers is compressing supplier lists to ISO-certified converters with captive resin supply. Automated distribution centers in the Netherlands now require machine-grade films with ±2% gauge tolerance for high-speed wrapping line compatibility. The specification tightening favors vertically integrated producers over toll-converting specialists.
Cast Stretch Films Market Segmentation
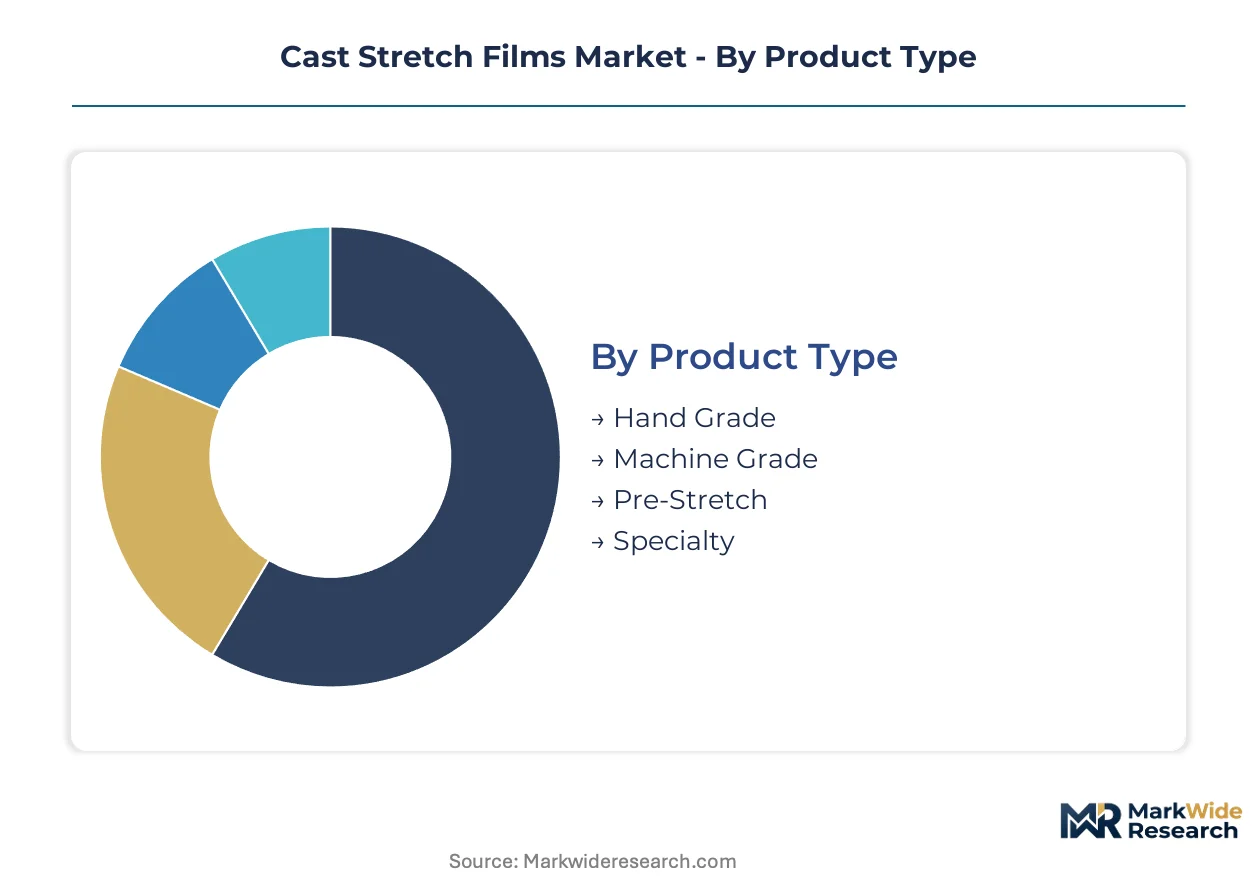
Segmentation in cast stretch films reveals how performance specifications diverge across automation levels, material science capabilities, and end-use compliance requirements. Each dimension carries distinct margin structures and substitution vulnerabilities that reshape supplier positioning.
Product Type:
Machine grade films face intensifying substitution pressure from pre-stretch alternatives as warehouse automation accelerates throughput optimization, while hand grade formulations confront reusable pallet wrap systems in sustainability-focused procurement.
- Machine Grade:High-velocity extrusion produces films with ±2% gauge tolerance for automated wrapping lines. Food and beverage distributors across Germany's industrial corridor specify these for palletization protocols, though capital-intensive line integration limits mid-scale converter participation.
- Hand Grade:Manual application films prioritize ergonomic cling and tear resistance over gauge precision. Small-format retail consolidation in France and Italy sustains volume, yet labor cost inflation is compressing share against semi-automated alternatives.
- Pre-Stretch:Orientation-stabilized films reduce material consumption per pallet load. Swiss pharmaceutical distributors specify these for cold-chain unitization where film yield directly impacts landed cost.
- Specialty:Multi-layer barrier and metallocene-catalyzed formulations serve temperature-validated applications. Biologics networks in the Netherlands drive specification tightening for thermal performance certification.
Machine grade retains volume leadership; specialty holds the steepest expansion curve.
Material:
Cost tier stratification separates commodity resin formulations from performance-engineered alternatives, with feedstock traceability emerging as a procurement differentiator under EU circular economy mandates.
- LLDPE:Linear low-density polyethylene dominates through superior elongation and puncture resistance balance. Automotive just-in-sequence suppliers in Germany standardize on hexene copolymer grades for load containment during multi-modal transit.
- LDPE:Low-density polyethylene offers clarity and processing ease for hand-application films. Italian fresh produce exporters favor these for optical inspection compatibility, though metallocene LLDPE is displacing share in premium segments.
- HDPE:High-density blends penetrate heavy-load industrial segments where puncture strength outweighs elongation performance. Chemical pallet unitization in Belgium specifies these for abrasive load surfaces.
- PVC:Polyvinyl chloride retains niche position in cling film applications. REACH substance restrictions on plasticizer migration are constraining food-contact deployment to non-direct applications.
LLDPE commands the broadest application base; HDPE is gaining share fastest in load-specific industrial specifications.
End User:
Application-driven segmentation concentrates procurement power among logistics consolidators, with compliance requirements fragmenting specifications across temperature sensitivity and migration limit standards.
- Food & Beverage:Palletization protocols demand FDA and EFSA dual-compliant formulations. German retail consolidation centers specify machine-grade LLDPE with non-phthalate cling additives for high-velocity throughput.
- Industrial:Heavy-load chemical and automotive components require puncture-optimized films. Rhine-Ruhr corridor exporters prioritize HDPE blends for automated warehouse compatibility.
- Healthcare:Pharmaceutical distribution networks specify metallocene-based barrier films. Swiss and Dutch cold-chain operators validate thermal performance for biologics unitization.
- Retail:Store-level consolidation and back-of-house operations sustain hand-grade consumption. French hypermarket chains are piloting pre-stretch systems to reduce material intensity.
Food and beverage anchors volume demand; healthcare is expanding most quickly on cold-chain infrastructure investment.
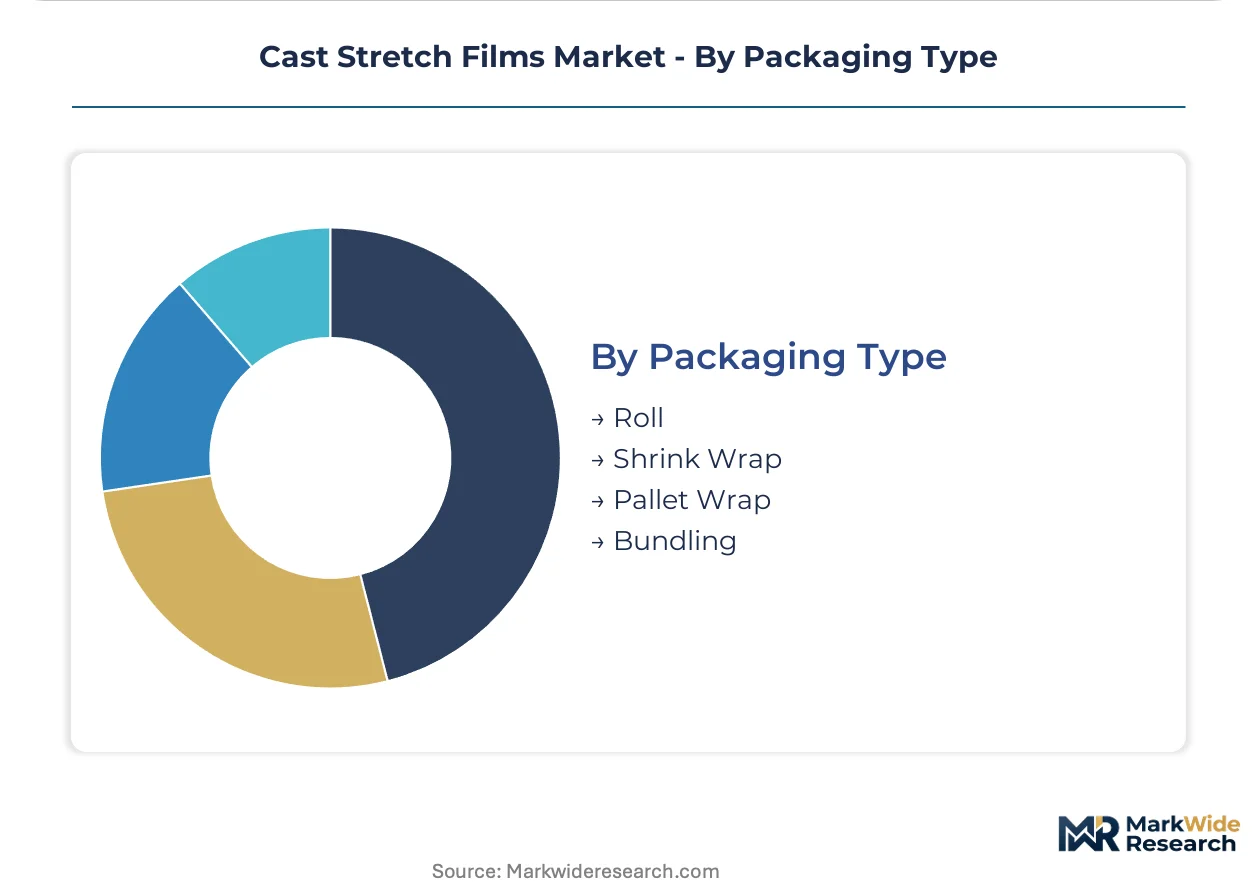
Packaging Type:
Customer type stratification separates pallet-scale unitization from item-level protection, with format selection determining converter equipment configuration and margin capture.
- Pallet Wrap:Primary revenue pool for machine-grade film consumption. Automated distribution centers in the Netherlands require RFID-enabled variants for warehouse management system integration.
- Roll:Standard supply format for converter and distributor inventory. German industrial corridor procurement concentrates on 20-micron to 23-micron gauge specifications for compatibility across wrapping line vintages.
- Shrink Wrap:Heat-activated films for item bundling and display protection. Italian consumer goods exporters specify these for retail-ready pallet presentation.
- Bundling:Narrow-width films for multi-pack collation. Beverage sector demand in Belgium and France sustains specialized extrusion line utilization.
Pallet wrap dominates value capture; bundling maintains stable niche positioning against alternative collation technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Third-party logistics consolidators concentrate procurement power in Germany, the United States, and the Netherlands, while pharmaceutical cold-chain operators in Switzerland and food-contact converters in France drive specification divergence.
Germany
Automotive just-in-sequence suppliers and chemical exporters along the Rhine-Ruhr corridor standardize machine-grade LLDPE films for automated palletization. REACH substance restrictions on monomer migration compel resin reformulation investments. Berry Global Inc leverages vertical integration across resin sourcing and film extrusion to sustain cost leadership in North America.
United States
Food and beverage distributors expand palletization protocols across Midwest distribution hubs, pulling demand toward puncture-resistant formulations. FDA food-contact notification requirements govern additive compositions for cling agents. Chicago-area automated logistics centers specify films with ±2% gauge tolerance for high-speed wrapping line compatibility.
Switzerland
Biologics distribution networks specify metallocene-based barrier films for temperature-validated pallet unitization. Swissmedic pharmaceutical certification requirements drive specification tightening beyond standard logistics applications. Basel-region cold-chain operators validate thermal performance for specialty film procurement.
Netherlands
Rotterdam-port distribution centers consolidate buying power among ISO-certified converters with captive resin supply. EU Packaging and Packaging Waste Regulation mandates accelerate mechanical recycling content integration. Eindhoven-area automated warehouses require RFID-enabled variants for warehouse management system integration.
France
Fresh produce exporters in the Provence-Alpes-Côte d'Azur region favor LDPE films for optical inspection compatibility. EFSA food-contact compliance programs accelerate non-phthalate additive qualification. Lyon-area retail consolidation centers pilot pre-stretch systems to reduce material intensity.
Cast Stretch Films Market Vendor Landscape
Player mix skews toward vertically integrated resin-to-film producers and specialized machine-grade formulators. The competitive structure bifurcates between commodity converters serving price-sensitive hand-grade segments and qualified suppliers capturing automated logistics hub contracts. Two strategic archetypes dominate: resin-integrated volume leaders and certification-focused specialty producers. Capacity expansion along the Rhine-Ruhr corridor and strategic partnerships for recycled feedstock sourcing represent the dominant competitive moves.
Within the vertically integrated tier, Berry Global Inc and Borealis AG exemplify upstream control over resin supply and film extrusion operations. Manuli Stretch occupies a position among European specialists in machine-grade formulations designed for high-velocity automated wrapping lines. Sigma Plastics Group and Intertape Polymer Group represent North American fabricators with scale-driven positions in standard logistics applications. These anchors illustrate how geographic concentration and feedstock strategy determine competitive positioning.
| Leading Market Players |
|---|
| Berry Global Inc |
| Sigma Plastics Group |
| Intertape Polymer Group |
| AEP Industries |
| Paragon Films |
| Manuli Stretch |
| Amcor Plc |
| Inteplast Group |
| Borealis AG |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with naphtha-indexed pricing lock in resin supply visibility for German and Dutch converters while insulating machine-grade film producers from spot ethylene volatility. These arrangements concentrate procurement power among vertically integrated suppliers with captive cracker access, compressing margins for toll-converting specialists dependent on spot resin markets.
Pricing Analysis
Cost-plus contracts indexed to ICIS ethylene benchmarks dominate machine-grade film procurement between Rhine-Ruhr corridor producers and automated logistics operators. Price differentiation rests on ISO 9001 certification tier and gauge tolerance precision, with ±2% tolerance films commanding premium positioning over commodity alternatives. Pricing pressure stems from HDPE blend substitution in heavy-load chemical palletization, where puncture strength requirements exceed standard LLDPE performance. Hand-grade segments exhibit highest price sensitivity due to labor cost inflation driving semi-automated conversion, while pharmaceutical cold-chain specifications show lowest sensitivity given thermal validation requirements.
Supply Chain Analysis
Inventory cycles stretching 6-8 weeks from resin procurement to film delivery expose converters to ethylene price swing absorption. Supply concentrates in Germany, the Netherlands, and Belgium, with flat-die extrusion lines clustering along the Rhine-Ruhr corridor and Rotterdam port hinterland. Raw material dependencies center on hexene and butene comonomer LLDPE resins, metallocene catalyst systems, and non-phthalate cling additives. Single-source vulnerability runs through concentrated European cracker operations serving film-grade polyethylene. Distribution runs through third-party logistics consolidators with direct line-feed arrangements to automated warehouse operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EU Packaging and Packaging Waste Regulation mandates bifurcate procurement between virgin-optimized and recycled-integrated supply chains, creating specialized niches for compliant converters ahead of mechanical recycling content deadlines.
For Market Incumbents: Compound certification advantages by accelerating ISO 9001 qualification timelines for mid-scale competitors before automated logistics hub supplier lists crystallize. Prioritize backward integration into mechanically recycled feedstock processing to defend margin position against resin suppliers forward-integrating into film extrusion. Threat of HDPE blend substitution in heavy-load industrial segments demands puncture-optimized formulation R&D investment. For New Entrants and Emerging Players: Lead with recycled content integration capabilities targeting 30% post-consumer mechanical recycling thresholds ahead of EU mandate crystallization. White-space opportunity concentrates in Swiss and Dutch pharmaceutical cold-chain distribution, where metallocene-based barrier film certification remains underpenetrated relative to standard logistics applications. Go-to-market angle should emphasize thermal validation documentation for biologics unitization protocols. For Investors and Strategic Acquirers: ISO-certified machine-grade specialists with captive resin supply and pharmaceutical certification capabilities represent the most defensible acquisition archetype for long-term viability across the 5-10 year window. Signal to monitor: ECHA substance restriction expansions beyond current phthalate additive limits, which would trigger reformulation investment cycles favoring pre-qualified converters with R&D scale.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Content Integration | EU Packaging and Packaging Waste Regulation mandates reshape procurement specifications for retail buyers. |
| Metallocene Catalyst Formulation Expansion | Swissmedic certification requirements drive premium positioning in pharmaceutical cold-chain distribution. |
| RFID-Enabled Film Development | Rotterdam-port logistics consolidators require real-time load tracking for warehouse management integration. |
| Backward Integration into Resin Sourcing | Captive hexene comonomer supply insulates margin compression from naphtha-cracker cycle volatility. |
| ISO 9001 Certification Acceleration | Automated distribution centers in the Netherlands restrict supplier lists to quality-system-qualified converters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory submission databases through structured interviews with film extrusion plant managers, procurement leads at third-party logistics operators, distribution channel partners, and technical R&D directors at resin suppliers. Bottom-up volume estimates derived from production capacity utilization and grade-mix assumptions triangulate against top-down demand segmentation from end-use industry consumption patterns.
Segmentation dimensions modeled span product type tier, material formulation grade, end-use industry vertical, and packaging format across the projection horizon. CAGRs emerge from elasticity-adjusted demand curves incorporating automation penetration rates and regulatory compliance cost pass-through assumptions. Industry-specific inputs include ethylene feedstock price trajectories, REACH substance restriction implementation timelines, and mechanical recycling infrastructure deployment schedules.
Forecasts assume regulatory continuity in EU REACH and FDA food-contact notification regimes; material policy shifts would require re-modeling of additive composition limits and migration threshold compliance costs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Blow Molded Plastics Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Europe Blow Molded Plastic Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Mexico Plastic Packaging Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
PET Preforms Market