
 Mexico Plastic Packaging Market | 2026-2036
Mexico Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Plastic Packaging Market Foresight
Food and beverage end-use demand is shifting toward lighter-weight formats that cut transport costs while preserving barrier performance. Grupo Phoenix anchors its position through captive blow-molding capacity serving domestic dairy and juice accounts. Berry Global leverages multi-site manufacturing across central Mexico to sustain just-in-time supply relationships with multinational CPG brands. ALPLA-Werke Alwin Lehner GmbH & Co KG differentiates through in-house preform and closure production that tightens quality control for carbonated soft drink bottlers.
Mexico plastic packaging encompasses thermoformed, extruded, and molded polymer structures engineered to contain, protect, and present consumer and industrial goods, with typical wall thicknesses ranging from 0.2 mm for flexible films to 2.5 mm for rigid industrial containers. PET bottles lead volume due to their clarity, recyclability, and compatibility with Mexico's established bottle-to-bottle recycling infrastructure led by PetStar. Flexible pouches represent the fastest-expanding form category as snack and sauce brands seek format differentiation and reduced material intensity. Polyethylene dominates material tonnage because of its cost position and versatility across both film and rigid applications, though rPET content requirements are elevating PET's strategic importance in beverage packaging.
COFEPRIS enforces food-contact safety standards that dictate migration limits and additive approvals for packaging destined for edible products, while SEMARNAT implements extended producer responsibility provisions that push converters toward post-consumer recycled feedstocks. PROFECO's labeling and consumer protection rules shape how packaging communicates content claims and recycling instructions to Mexican households. Stakeholders must monitor how pending state-level waste management regulations and energy cost fluctuations alter the economics of domestic resin conversion versus imported finished packaging.
Market Dynamics
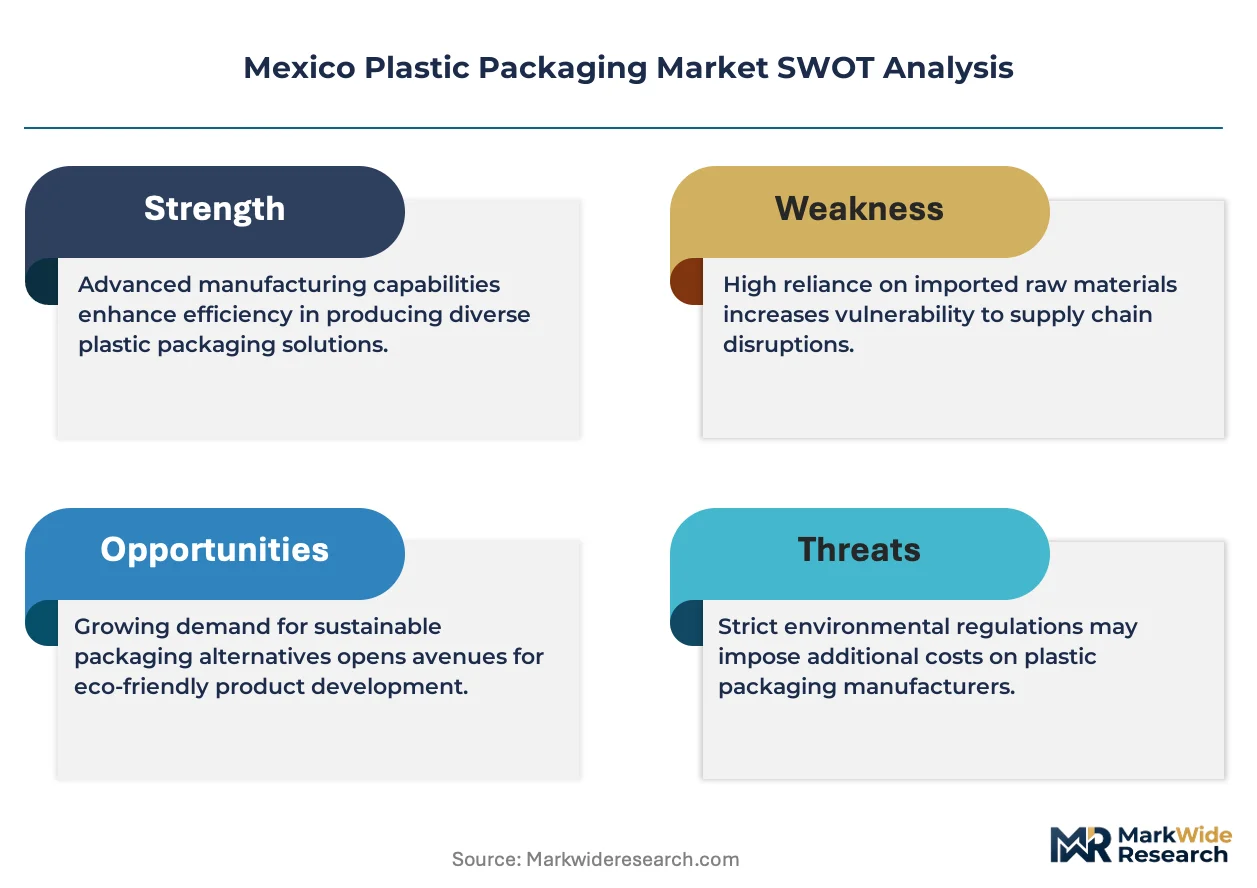
SEMARNAT's extended producer responsibility framework is forcing converters to reconfigure resin sourcing around post-consumer recycled feedstocks, compressing margins for processors lacking backward integration into recycling infrastructure.
Growth Catalysts
- Bajío Industrial Corridor Concentration:Major bottling and processed food operations cluster in Guanajuato and Querétaro, creating dense demand nodes that justify dedicated converter capacity investments.
- rPET Mandates:Circular economy content requirements elevate demand for food-grade recycled PET, pulling investment toward bottle-to-bottle recycling infrastructure.
- Flexible Pouch Migration:Snack and sauce brands accelerate format shifts from rigid containers to laminated pouches, cutting material intensity and logistics cube.
Market Restraints
- Resin Price Volatility:Polyethylene and PET feedstock costs track naphtha and paraxylene indices, exposing converters to margin compression when energy markets spike.
- Recycling Infrastructure Gaps:Collection rates for flexible multilayer films lag rigid containers, limiting feedstock availability for circular content targets.
- COFEPRIS Migration Limits:Food-contact safety standards restrict additive packages and recycled content ratios in edible-product packaging, constraining formulation flexibility.
Strategic Opportunities
- Yucatán Peninsula Expansion:Underpenetrated beverage and personal care markets in southeastern Mexico offer first-mover advantages for regional converter capacity.
- Monomaterial Flexible Films:PE-based pouch structures compatible with existing store-dropoff recycling streams unlock sustainability claims without multilayer complexity.
- PROFECO Label Alignment:Clear recycling instruction mandates create differentiation for brands investing in consumer-education packaging design.
Industry Challenges
- Recycling Technician Shortage:Sortation and wash-line operation expertise lags capacity expansion, constraining output quality at mechanical recycling facilities.
- Legacy Extruder Retrofitting:Converting existing lines to handle higher rPET flake percentages requires screw and die modifications that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Plastic Packaging Market |
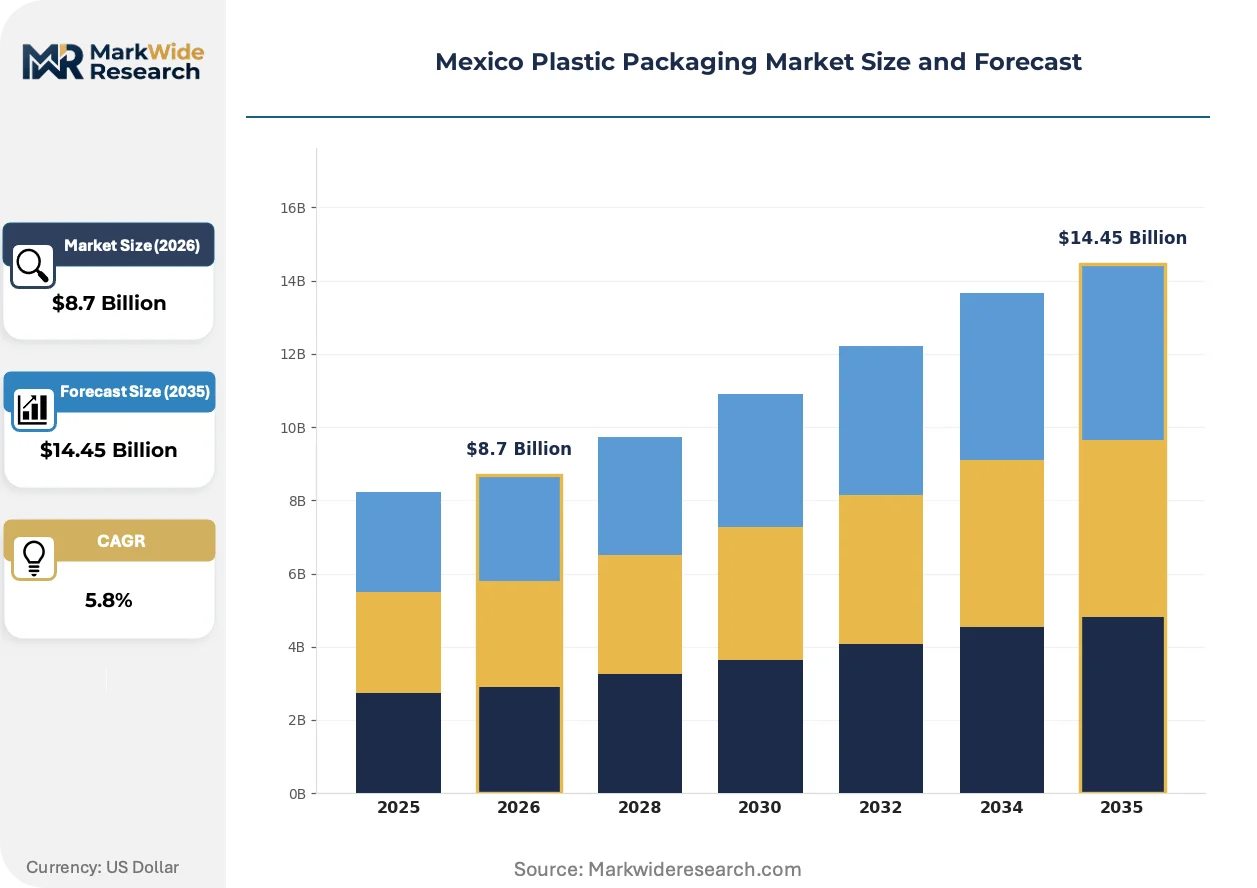
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Pouches, Containers, Films Material: Polyethylene, Polypropylene, PET, PVC End User: Food, Beverage, Personal Care, Pharmaceuticals Form: Rigid, Flexible, Semi-Rigid, Multi-Layer |
| Companies Covered | Amcor plc, ALPLA-Werke Alwin Lehner GmbH & Co KG, Mondi plc, Sonoco Products Company, Berry Global, Greif, Inc., Grupo Phoenix, Envases Universales, PetStar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Plastic Packaging Market Shifts & Advancements
Digital printing and automation technologies are compressing minimum order quantities and lead times, enabling converters to serve fragmented brand portfolios without sacrificing asset utilization.
Digital flexographic printing is automating plateless changeover workflows that previously required 45-minute makeready cycles. Mid-tier snack brands in Jalisco and Estado de México are adopting this technology to support SKU proliferation for regional flavor variants. The compression of order economics is automating the viability of sub-5,000-unit production runs that were previously uneconomical.
SEMARNAT's updated extended producer responsibility provisions tighten post-consumer recycled content thresholds for rigid containers. Processors must now document chain-of-custody from collection through reprocessing to claim compliance credits. Beverage bottlers in the Mexico City metropolitan area are responding by anchoring supply agreements with PetStar and independent recyclers.
Brand procurement teams are consolidating supplier panels around converters offering integrated design-to-delivery services. Multinational CPG accounts now require simulation-validated barrier performance before awarding volume contracts. This specification tightening is most visible in dairy and juice segments, where shelf-life extension directly competes with cold-chain infrastructure gaps.
Mexico Plastic Packaging Market Segmentation
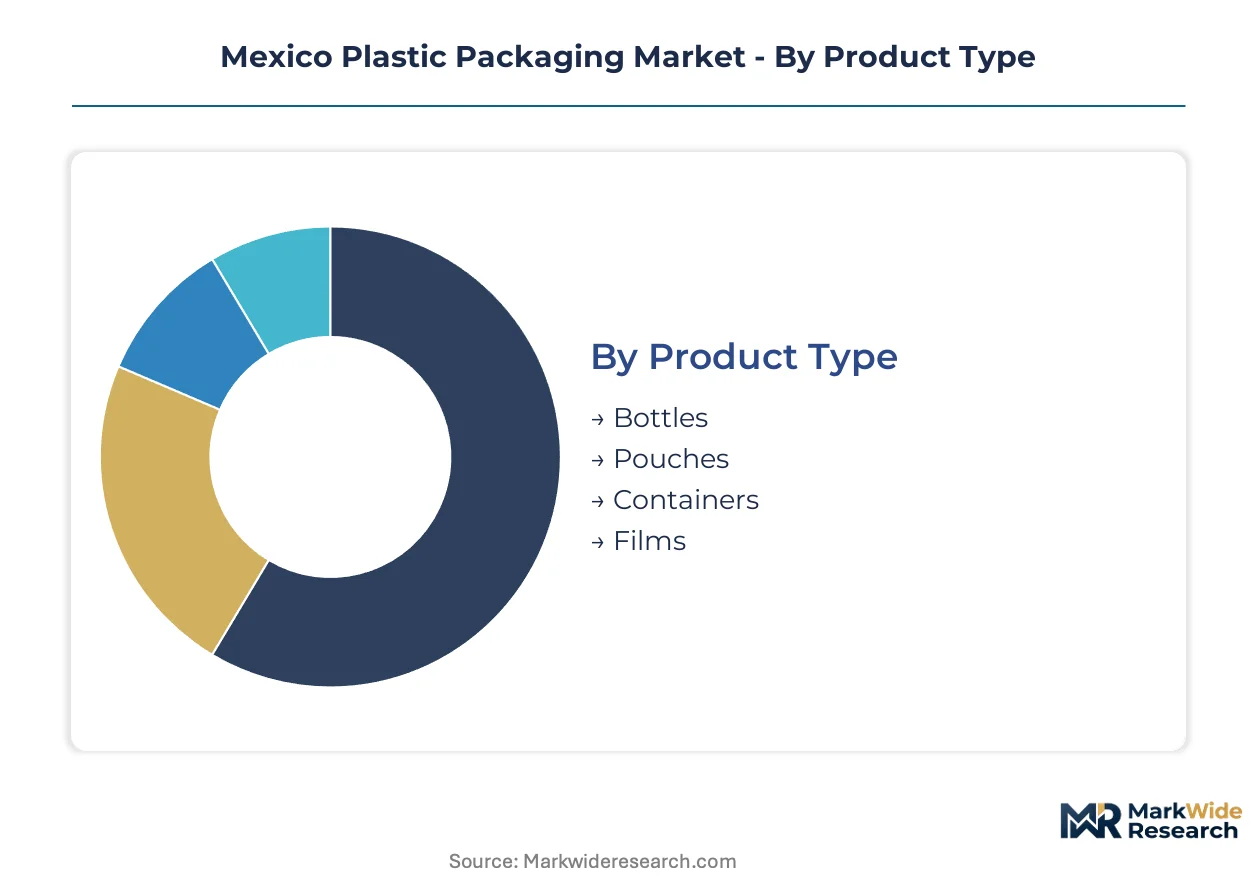
Segmentation reveals how Mexican converters align capacity investments with diverging performance requirements across beverage bottlers, processed food manufacturers, and personal care formulators. Understanding these splits exposes where resin sourcing flexibility and recycling compliance obligations concentrate.
Product Type:
Customization intensity varies from commodity bottles to engineered multi-layer pouches, with standardization dominant at high-volume end-uses and bespoke specifications governing niche barrier applications.
- Bottles:Blow-molded PET and HDPE structures dominate carbonated soft drink and dairy applications. Demand clusters around the Bajío corridor where Grupo Phoenix and ALPLA maintain captive preform operations. COFEPRIS migration limits constrain recycled content ratios in edible-product bottles.
- Pouches:Laminated flexible formats with oxygen and moisture barriers are displacing rigid containers in snack and sauce segments. Jalisco-based brands adopt digital flexographic printing to support SKU proliferation for regional flavor variants.
- Containers:Injection-molded tubs and trays serve prepared meals and dairy spreads. Specifications center on freezer-to-microwave thermal stability.
- Films:Cast and blown polyethylene structures wrap palletized goods and form primary food-contact layers. Thickness tolerances tighten for automated packaging lines.
Most installed capacity flows through Bottles. Expansion is steepest in Pouches.
Material:
Cost positioning separates commodity thermoplastics from performance polymers, with circular economy mandates now reordering strategic priority regardless of base resin economics.
- Polyethylene:LDPE and HDPE grades anchor flexible film and rigid container production due to melt processability and seal performance. Tonnage concentrates in central Mexico extrusion corridors serving tortilla and bakery packaging.
- PET:Clarity and established bottle-to-bottle recycling infrastructure elevate strategic importance despite higher base cost. PetStar's recycling complex supplies food-grade rPET to Mexico City metropolitan bottlers meeting SEMARNAT content thresholds.
- Polypropylene:High melt strength supports thermoformed cups and microwaveable containers. Random copolymer grades compete with PET in hot-fill juice applications.
- PVC:Cling film and blister pack applications persist in pharmaceutical and fresh produce wrapping. Regulatory pressure on plasticizer migration limits expansion in food-contact uses.
Polyethylene commands the largest installed base. PET is gaining share fastest on recycled content mandates.
End User:
Volume scale and specification stringency diverge sharply, with beverage and food accounts driving asset utilization while pharmaceutical and personal care segments command premium pricing for compliance-intensive formats.
- Food:Processed meat, dairy, and bakery applications require oxygen scavenging and modified atmosphere compatibility. Shelf-life extension competes with cold-chain infrastructure gaps in southeastern distribution.
- Beverage:Carbonated soft drink and bottled water volumes anchor PET preform demand. Just-in-time supply relationships with multinational CPG brands require multi-site manufacturing coverage across central Mexico.
- Personal Care:Shampoo and conditioner bottles prioritize aesthetic differentiation through color and texture effects. Smaller lot sizes favor digital printing adoption.
- Pharmaceuticals:Blister packs and vials demand COFEPRIS-validated barrier performance and child-resistant closure integration. Migration testing protocols extend qualification timelines.
Food and Beverage absorb the majority of resin throughput. Pharmaceuticals is expanding most quickly on compliance-driven format upgrades.
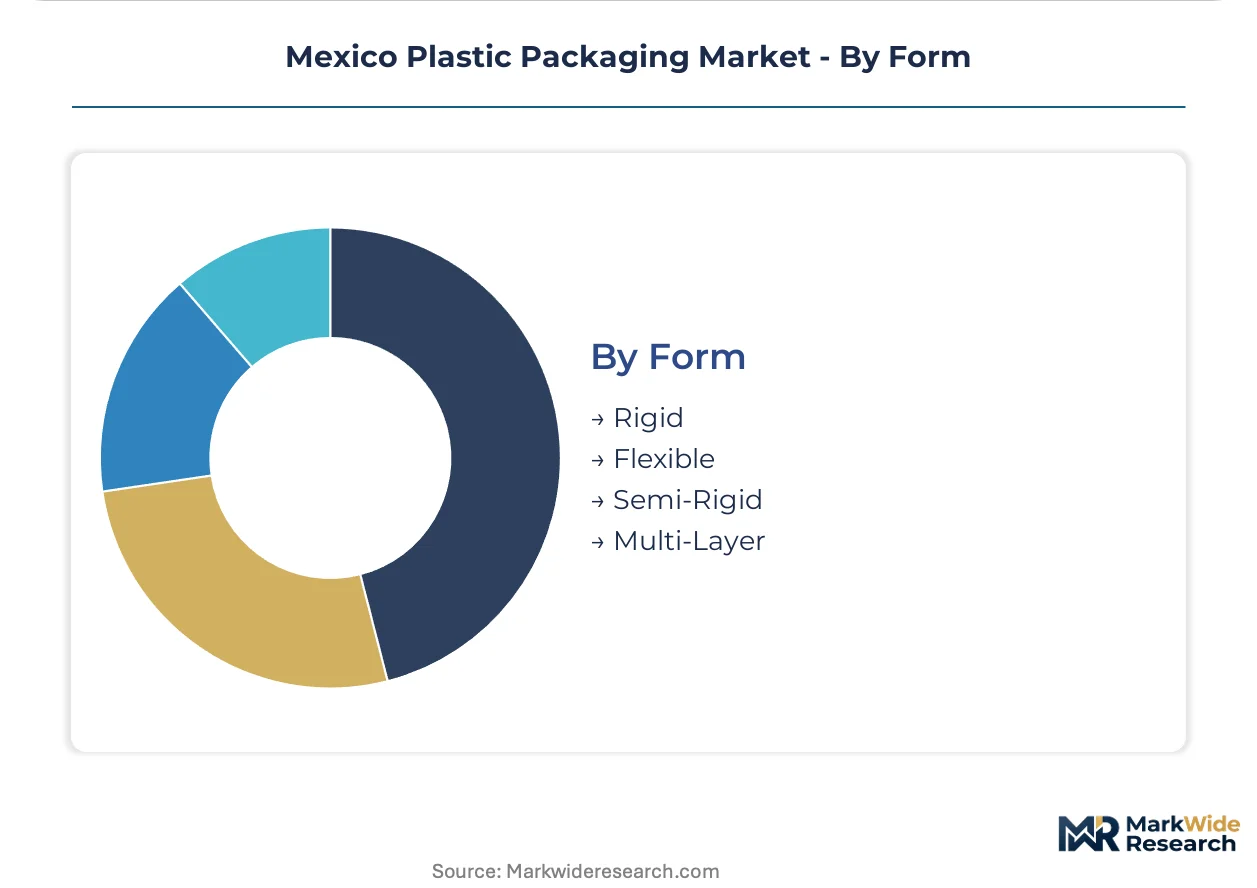
Form:
Structural mechanics and recycling pathway compatibility define competitive positioning, with rigid formats leveraging existing mechanical recycling infrastructure and flexible structures pursuing monomaterial redesign for circular claims.
- Rigid:Bottles, jars, and trays maintain dimensional stability for stacking and retail presentation. Collection and sortation infrastructure supports post-consumer recycled feedstock integration.
- Flexible:Pouches and films reduce material intensity and logistics cube. Multi-layer barrier constructions face recycling infrastructure gaps that SEMARNAT extended producer responsibility provisions aim to address.
- Semi-Rigid:Thermoformed tubs and trays bridge protection and lightweighting for dairy and prepared meals. Wall thickness optimization balances rigidity with resin minimization.
- Multi-Layer:Coextruded and laminated structures combine incompatible polymers for barrier performance. Delamination requirements complicate mechanical recycling pathways.
Rigid formats dominate current recycling streams. Flexible structures are climbing the fastest on snack and sauce brand migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between Mexican states are redirecting converter investments toward jurisdictions with lighter compliance burdens and cheaper energy inputs.
Bajío Region
Carbonated soft drink and dairy bottlers concentrate in Guanajuato and Querétaro, driving captive preform demand from Grupo Phoenix and ALPLA operations. SEMARNAT's extended producer responsibility provisions apply uniformly, though local energy subsidies reduce processing costs versus Mexico City. The León-Silao industrial corridor hosts dense blow-molding capacity serving Coca-Cola FEMSA and Grupo Lala accounts.
Mexico City Metropolitan Area
Multinational CPG brands demand just-in-time supply coverage, pulling Berry Global and Envases Universales into multi-site manufacturing configurations. COFEPRIS enforcement intensity peaks here, extending migration testing timelines for food-contact packaging. Toluca and Cuautitlán Izcalli anchor extrusion corridors supplying tortilla and bakery film to domestic retail chains.
Nuevo León
Monterrey's manufacturing base supports automotive and industrial chemical packaging with HDPE drum and intermediate bulk container production. CFE industrial electricity rates in the state undercut central Mexico by 12-15%, attracting resin conversion capacity from polyethylene importers. García and Apodaca host thermoforming operations for prepared meal trays.
Jalisco
Snack brands in Guadalajara accelerate flexible pouch adoption, with digital flexographic printing enabling regional flavor variant proliferation. PROFECO labeling enforcement creates compliance costs that favor larger converters with in-house legal teams. The El Salto industrial park concentrates cast film extrusion for primary food-contact layers.
Yucatán Peninsula
Underpenetrated beverage and personal care markets in Mérida and Cancún offer first-mover positioning for regional converter capacity. SEDUMA state environmental permits process faster than SEMARNAT federal timelines, compressing project commissioning. Logistics costs from central Mexico currently disadvantage imported finished packaging.
Mexico Plastic Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational CPG accounts consolidating supplier panels around integrated design-to-delivery capabilities. The vendor base organizes into three tiers: global converters with multi-country manufacturing footprints, regional Mexican groups with captive recycling integration, and specialized flexible film processors serving fragmented snack brands. Capacity expansion and backward integration into recycling infrastructure represent the dominant competitive vectors as SEMARNAT content mandates tighten.
Among Austria-based rigid packaging specialists, ALPLA-Werke Alwin Lehner GmbH & Co KG exemplifies the preform-and-closure integration archetype that tightens quality control for carbonated soft drink bottlers. Berry Global, operating as a US-incorporated multinational, occupies a position emphasizing multi-site manufacturing coverage across central Mexico to sustain just-in-time relationships. Grupo Phoenix, identifiable as a Mexican corporate entity, anchors the regional captive blow-molding tier serving domestic dairy and juice accounts with localized production.
| Leading Market Players |
|---|
| Amcor plc |
| ALPLA-Werke Alwin Lehner GmbH & Co KG |
| Mondi plc |
| Sonoco Products Company |
| Berry Global |
| Greif, Inc. |
| Grupo Phoenix |
| Envases Universales |
| PetStar |
| Others |
Supply & Pricing Matrix
Digital flexographic printing adoption across Jalisco and Estado de México snack converters compresses makeready economics while redistributing pricing power toward equipment-integrated suppliers capable of sub-5,000-unit production runs.
Pricing Analysis
Distributor margins on imported resin shipments compress converter profitability, particularly for polyethylene-dependent extrusion operations in central Mexico. Three-tier pricing structure across premium, standard, and economy levels separates food-grade rPET from virgin PET and industrial-grade regrind. Pricing pressure stems from naphtha-indexed polyethylene volatility and SEMARNAT compliance documentation costs. Small-format snack brands exhibit highest price sensitivity, while multinational CPG accounts prioritize barrier validation over per-unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Coca-Cola FEMSA and Grupo Lala force preform converters to qualify multiple resin suppliers across US Gulf Coast, Mexican petrochemical corridors, and Asian import channels. Raw material dependencies center on paraxylene for PET, ethylene feedstock for polyethylene grades, and adhesion promoters for multilayer laminates. Tariff exposure on US-origin resin creates margin vulnerability during trade policy shifts. Distribution runs through captive blow-molding networks for beverage accounts and third-party logistics for fragmented food brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
rPET mandate compliance costs concentrate margin expansion opportunity with backward-integrated recyclers and digital-printing converters serving SKU-proliferating snack brands.
For Market Incumbents: Deploy captive recycling infrastructure to capture SEMARNAT compliance credits before independent recyclers scale food-grade flake output. Berry Global and Grupo Phoenix should anchor preform supply agreements with documented chain-of-custody from PetStar collection through reprocessing. Defensive positioning requires retrofitting legacy extruders for higher rPET percentages before technician scarcity extends commissioning timelines. For New Entrants and Emerging Players: Regional bottlers in Mérida and Cancún represent the most penetrable demand node, with logistics costs currently disadvantaging central Mexico converters. Flexible pouch specialists should target Jalisco snack brands adopting digital flexographic printing for regional flavor variants. Go-to-market positioning centers on monomaterial PE structures compatible with existing store-dropoff recycling streams. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap flexible film processors lacking rPET integration but possessing digital printing assets convertible to monomaterial pouch production. Long-term viability favors converters with SEDUMA permitting relationships in Yucatán and captive supply agreements with multinational CPG accounts. Watch PetStar expansion timelines as inflection indicator for food-grade rPET feedstock availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captures SEMARNAT compliance credits and secures food-grade rPET supply for beverage bottlers. |
| Digital Printing Adoption | Enables sub-5,000-unit economics for Jalisco snack brands proliferating regional flavor SKUs. |
| Monomaterial Flexible Film Development | Unlocks sustainability claims for pouch converters navigating multilayer recycling infrastructure gaps. |
| Yucatán Regional Capacity Expansion | Exploits SEDUMA permitting speed and underpenetrated beverage demand in Mérida-Cancún corridor. |
| Chain-of-Custody Documentation Systems | Satisfies SEMARNAT audit requirements for post-consumer recycled content claims in rigid containers. |
Research Methodology
Direct dialogue with blow-molding plant managers, resin procurement leads at multinational CPG brands, SEMARNAT compliance officers, and PetStar recycling operations directors grounded qualitative findings. Secondary validation drew from COFEPRIS food-contact safety filings, SEC 10-K disclosures by packaging multinationals, Mexican customs resin import data, and PROFECO labeling enforcement records. Bottom-up capacity assessments across Bajío corridor converters triangulated against top-down demand estimates from beverage bottler volume reports.
Bottom-up modeling aggregated installed extrusion and blow-molding capacity by product type, material, and end-use segment across the analysis window. Top-down verification cross-referenced resin consumption patterns against SEMARNAT extended producer responsibility compliance thresholds. Segmentation dimensions included form factor, polymer chemistry, and geographic production cluster. CAGRs derived from regression analysis of historical volume trends and projected mandate-driven rPET adoption curves, with sensitivity testing for energy cost fluctuations and collection rate assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PetStar capacity expansion, CFE industrial electricity rate revisions, and COFEPRIS migration limit adjustments. Deviation in naphtha-to-polyethylene spread or US-Mexico trade policy on resin tariffs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
Brazil Plastic Bottles Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
Europe Plastic Packaging Market
Plastic Packaging
Plastic Liners Market
Plastic Packaging
Reusable Plastic Water Bottles Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Plastic Vials Market