
 Asia Pacific Plastic Bottles Market | 2026-2036
Asia Pacific Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Plastic Bottles Market Insights
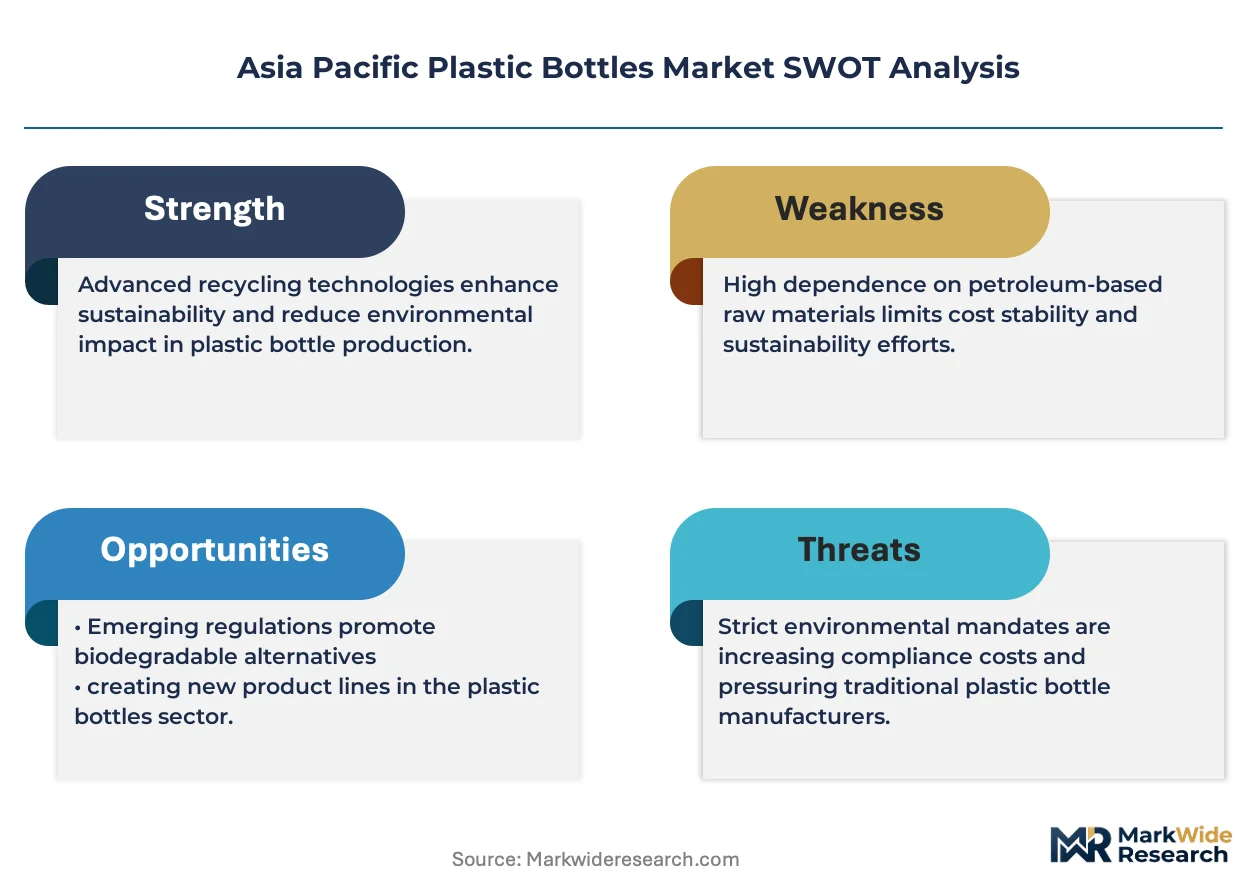
Lightweight design services and refill-subscription programs is repositioning how packaging value gets captured in the Asia Pacific plastic bottles landscape. Amcor plc leverages its preform engineering network to dominate thin-wall PET development for beverage clients. Manjushree Technopack Limited anchors South Asian supply through its Bengaluru and Guwahati plants, specializing in pharmaceutical-grade bottles. Berry Global Inc. competes on multi-layer barrier technology for sensitive personal care formulations.
Asia Pacific plastic bottles are hollow containers formed through extrusion blow molding, injection blow molding, or stretch blow molding, typically ranging from 50 milliliters to 20 liters in capacity and constructed from thermoplastic polymers with specified wall thickness and neck finish tolerances. They serve primarily as liquid containment and distribution vessels across food, beverage, pharmaceutical, and chemical supply chains. PET bottles lead volume due to established recycling infrastructure and clarity requirements in the beverage industry, while HDPE bottles command margin pools in household products where chemical resistance and post-consumer recyclate integration carry specification premiums. Multi-layer feature categories are expanding fastest as oxygen and UV barrier demands intensify in pharmaceutical and juice packaging segments.
China's SAMR enforces GB standards for food-contact plastics that restrict additive migration and mandate testing protocols, while India's BIS operates compulsory registration schemes for PET and HDPE containers used in packaged drinking water. Japan's METI promotes container recycling through its Design for Environment guidelines, shaping material choices for brands exporting across Northeast Asian trade corridors. Stakeholders must monitor how these frameworks evolve around recycled content mandates and extended producer responsibility schemes to align capacity investments with compliance timelines.
Market Dynamics
India's BIS certification tightening and China's GB standards enforcement are compressing supplier margins while accelerating consolidation among preform manufacturers across Maharashtra and Gujarat clusters.
Growth Catalysts
- India's BIS compulsory registration scheme:Mandates for PET and HDPE containers in packaged drinking water are phasing out subscale converters and redirecting volume toward certified blow-molding facilities in western states.
- Carbonated beverage line expansions:Southeast Asian bottlers are commissioning stretch blow-molding capacity for PET at scale, pulling demand for lightweight preform designs.
- Pharmaceutical barrier specifications:Multi-layer co-injection technology adoption is accelerating as oxygen and UV protection requirements intensify for sensitive drug formulations across the region.
Market Restraints
- Feedstock volatility:Purified terephthalic acid and ethylene glycol price swings compress margins for converters locked into annual beverage supply contracts.
- Preform supply concentration:Western India's Maharashtra-Gujarat corridor controls critical blow-molding infrastructure, creating geographic vulnerability for brands sourcing from distant Southeast Asian plants.
- Mechanical recycling contamination limits:Existing reprocessing infrastructure cannot handle multi-layer barrier structures, constraining circularity claims for pharmaceutical and juice packaging segments.
Strategic Opportunities
- Indonesia's underdeveloped refill infrastructure:Subscription-based reuse programs for household chemicals remain nascent, offering first-mover positioning for platform operators.
- Japan's METI Design for Environment guidelines:Container recycling incentives are reshaping material specifications for brands exporting across Northeast Asian trade corridors.
- Digital printing convergence with blow molding:In-mold labeling integration enables batch-level traceability for pharmaceutical serialization requirements without secondary operations.
Industry Challenges
- Multi-layer co-injection technician scarcity:Barrier layer thickness calibration and defect detection require specialized mold-flow expertise that regional vocational programs have not scaled.
- BIS certification timeline compression:Laboratory testing queues for migration and heavy metal protocols are extending product launch windows for converters serving India's packaged water segment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Plastic Bottles Market |
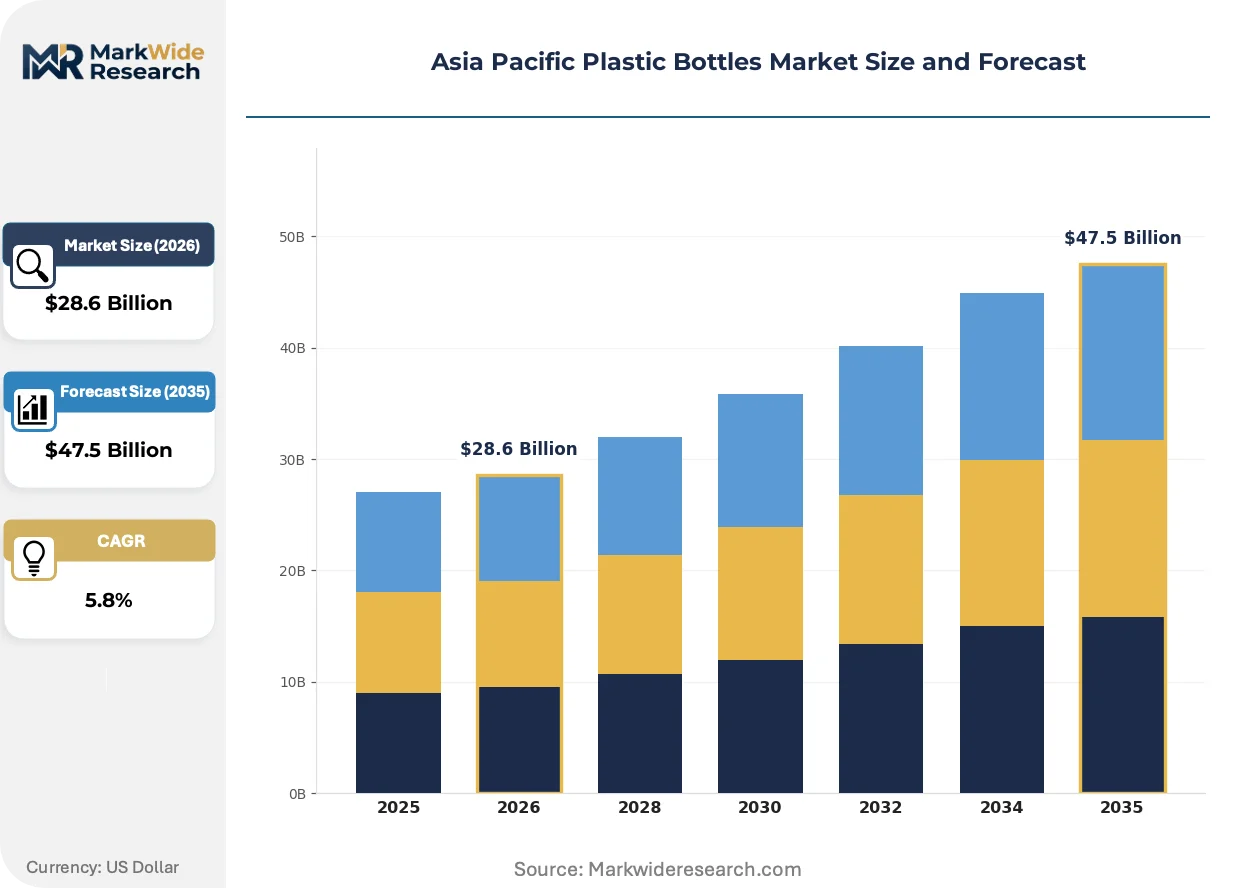
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pet Bottles, HDPE Bottles, PVC Bottles, LDPE Bottles End User: Beverage Industry, Personal Care, Household Products, Pharmaceuticals Feature: Recyclable, Biodegradable, Multi-layer, Lightweight Packaging Type: Bottled Water, Soft Drinks, Juices, Cleaning Products |
| Companies Covered | Amcor plc, Gerresheimer AG, Berry Global Inc., ALPLA Group, Pact Group Holdings Limited, Silgan Holdings Inc., Huhtamaki Oyj, Sealed Air Corporation, Manjushree Technopack Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Plastic Bottles Market Trends and Innovations
Active and intelligent packaging integration is compressing traditional commodity positioning across Asia Pacific plastic bottles, with functional additives and connected features commanding specification premiums in regulated end-uses.
Mono-material barrier structures are unifying oxygen protection and recyclability in a single PET stream. Pharmaceutical and juice packagers in Japan and South Korea are specifying these designs to meet METI recycling guidelines while maintaining shelf-life performance. This unifying architecture is compressing demand for legacy multi-layer HDPE constructions that require separation before reprocessing.
China's SAMR enforcement of GB standards for food-contact plastics is mandating additive migration testing protocols that disqualify legacy masterbatch formulations. Converters serving export markets are reformulating to comply with both domestic GB limits and destination-country requirements. The beverage segment is responding fastest, with carbonated brands accelerating preform requalification to avoid shipment detention at customs.
Direct-to-retail procurement consolidation is compressing distributor tiers in Southeast Asia. Large-format retailers in Thailand and Vietnam are specifying bottle designs at headquarters and sourcing preforms directly from Gujarat and Maharashtra converters, bypassing regional trading houses. This pattern is most visible in private-label bottled water, where volume concentration enables custom lightweighting programs.
Asia Pacific Plastic Bottles Market Segmentation
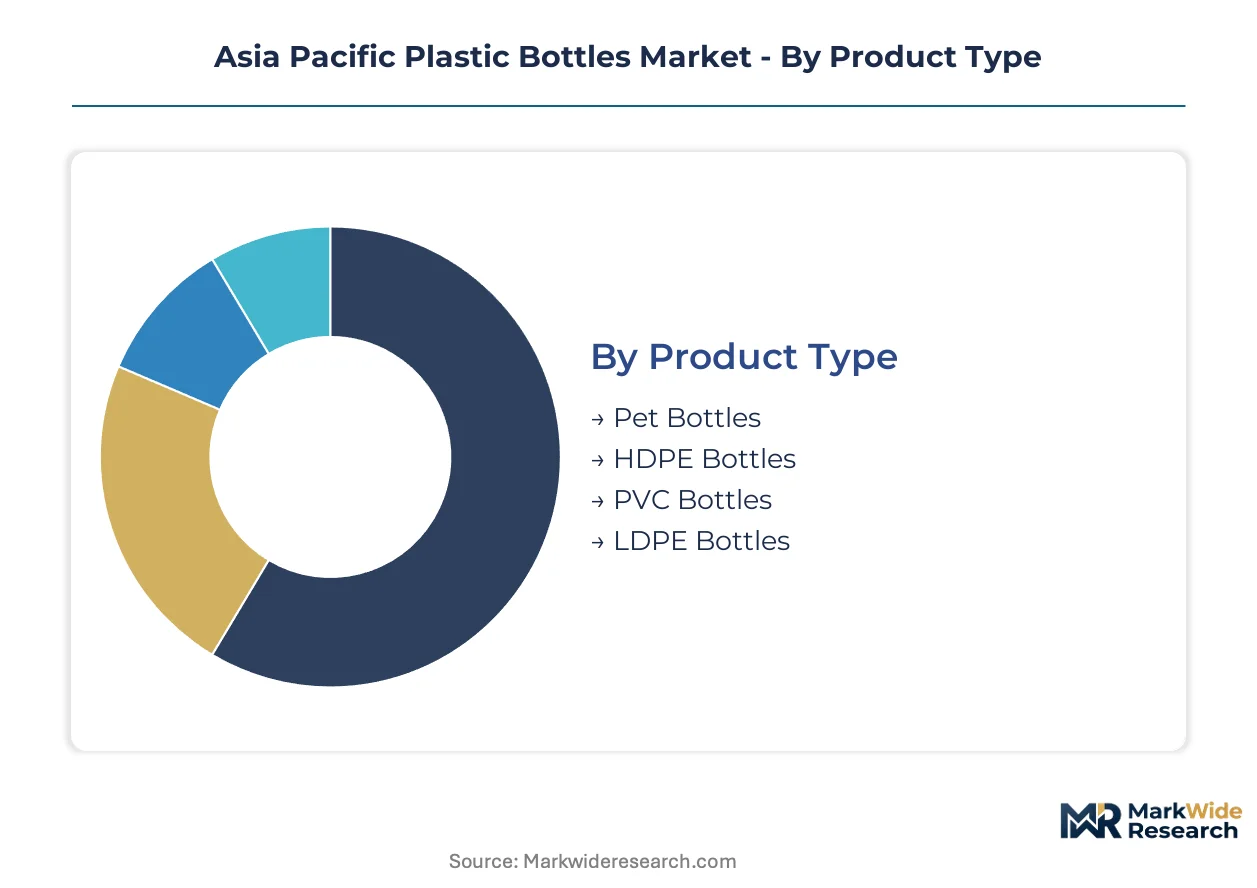
Segmentation in the Asia Pacific plastic bottles market reveals how material specifications, end-use requirements, and sustainability mandates create distinct competitive arenas. Each category channels investment toward different capability clusters across the region's manufacturing bases.
Product Type:
Replacement cycles for bottle materials accelerate as regulatory thresholds for recycled content and migration limits tighten across India, China, and Japan.
- PET Bottles:Thermoplastic polyester formed through stretch blow molding delivers clarity and established mechanical recycling pathways. Demand concentrates in Southeast Asian carbonated beverage lines where lightweight preform designs reduce resin intensity per unit.
- HDPE Bottles:High-density polyethylene extrusion blow molding yields chemical resistance and post-consumer recyclate integration. Maharashtra and Gujarat converters command margin pools in household product supply chains where BIS certification mandates filter subscale competitors.
- PVC Bottles:Polyvinyl chloride construction persists in niche pharmaceutical blister and chemical containment applications with specific barrier requirements.
- LDPE Bottles:Low-density polyethylene squeeze bottles serve personal care dispensing formats where flexibility and cost minimization dominate procurement criteria.
PET bottles sit at the top of the volume ranking, with multi-layer feature categories climbing the fastest as barrier specifications intensify.
End User:
Cost tier differentiation separates commodity converters from specification-driven suppliers serving regulated segments with mandatory certification protocols.
- Beverage Industry:Carbonated soft drink and bottled water brands commission stretch blow-molding capacity at scale across Thailand, Vietnam, and Indonesia. Procurement consolidation enables direct preform sourcing from western Indian manufacturing clusters.
- Pharmaceuticals:Oxygen and UV barrier demands for sensitive drug formulations drive multi-layer co-injection technology adoption. Japan's METI Design for Environment guidelines reshape material specifications for brands exporting across Northeast Asian trade corridors.
- Personal Care:HDPE and LDPE formats dominate shampoo, lotion, and cosmetic dispensing applications where chemical resistance and squeezability carry specification weight.
- Household Products:Cleaning chemical containment requires chemical-resistant constructions with child-resistant closure compatibility, concentrating supply among established blow-molding networks.
Beverage applications command the dominant volume position, with pharmaceutical packaging expanding most quickly on barrier technology premiums.
Feature:
Customer type segmentation distinguishes between brand-owners seeking compliance certification and retailers optimizing for private-label cost structures.
- Multi-layer:Co-injection barrier structures integrate oxygen and UV protection for pharmaceutical and juice packaging segments. Technician scarcity for mold-flow calibration and defect detection constrains regional supply expansion.
- Recyclable:Mono-material PET streams unify barrier performance with mechanical recycling compatibility, displacing legacy multi-layer HDPE constructions in Japan and South Korea.
- Lightweight:Thin-wall preform engineering reduces resin intensity per bottle, capturing value through freight efficiency and material cost reduction in high-volume beverage applications.
- Biodegradable:Bio-based polymer formulations remain commercially limited, constrained by cost premiums and absence of industrial composting infrastructure across the region.
Recyclable features anchor current procurement specifications, with multi-layer constructions gaining share fastest on pharmaceutical barrier requirements.
Packaging Type:
Supply concentration in western India's blow-molding corridor shapes fulfillment patterns for distinct liquid containment categories.
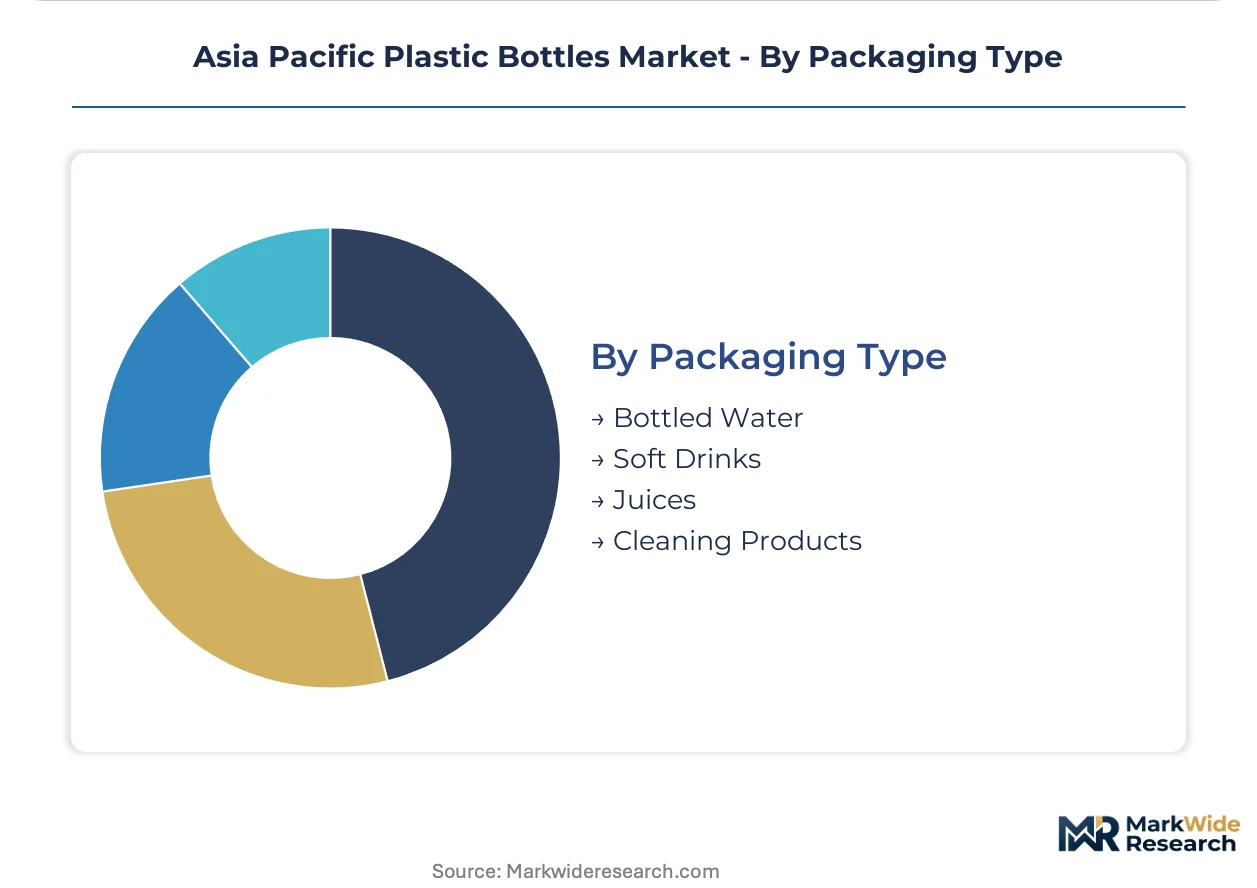
- Bottled Water:India's BIS compulsory registration scheme for PET and HDPE containers phases out uncertified converters, redirecting volume toward Maharashtra and Gujarat facilities with laboratory testing capabilities.
- Soft Drinks:Carbonated beverage carbonation pressure requirements drive stretch blow-molding specifications and preform lightweighting programs across Southeast Asian bottling networks.
- Juices:Oxygen-sensitive formulations require barrier protection, creating specification overlap with pharmaceutical packaging demands for multi-layer technology.
- Cleaning Products:Chemical resistance and dispensing functionality concentrate procurement among HDPE converters with established household product supply relationships.
Bottled water holds the volume lead, with juice packaging ascending fastest on barrier specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters migrate capacity toward jurisdictions with harmonized standards and established testing infrastructure, arbitraging compliance cost gaps between mature certification regimes and emerging registration schemes.
India
Maharashtra and Gujarat host dense clusters of blow-molding and preform manufacturing facilities serving domestic beverage brands and Southeast Asian exporters. BIS compulsory registration schemes for PET and HDPE containers are phasing out subscale converters and redirecting volume toward certified facilities with laboratory testing capabilities.
China
Stretch blow-molding capacity expansion for carbonated drinks and bottled water anchors demand in the Yangtze River Delta and Pearl River Delta manufacturing belts. SAMR enforcement of GB standards for food-contact plastics mandates additive migration testing protocols that disqualify legacy masterbatch formulations.
Japan
Pharmaceutical and juice packagers in Kanto and Kansai regions specify mono-material PET barrier structures to meet METI Design for Environment guidelines while maintaining shelf-life performance. Container recycling incentives are reshaping material specifications for brands exporting across Northeast Asian trade corridors.
Thailand
Large-format retailers commission stretch blow-molding capacity for private-label bottled water, sourcing preforms directly from western Indian converters and bypassing regional trading houses. Procurement consolidation enables custom lightweighting programs at volume scale.
Vietnam
Beverage bottlers expand PET packaging lines for carbonated drinks, pulling demand for lightweight preform designs from established supply networks. Direct-to-retail procurement patterns concentrate distributor tiers as headquarters-level specification authority displaces regional intermediaries.
Asia Pacific Plastic Bottles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with beverage procurement favoring scale-driven preform suppliers while pharmaceutical packaging rewards barrier technology specialists. The vendor base organizes around three strategic archetypes: integrated resin-to-preform operators, multi-layer co-injection specialists, and regional blow-molding converters serving private-label retailers. Dominant competitive moves include backward integration into resin compounding and geographic expansion through manufacturing joint ventures in underpenetrated Southeast Asian markets.
Among Asia-Pacific headquartered converters, Manjushree Technopack Limited anchors South Asian supply through its Bengaluru and Guwahati manufacturing positions, while Amcor plc leverages its preform engineering network to occupy a scale-driven position in thin-wall PET development. Berry Global Inc. sits within the multi-layer barrier technology tier, competing on specification premiums for sensitive personal care and pharmaceutical formulations where oxygen and UV protection requirements intensify.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Berry Global Inc. |
| ALPLA Group |
| Pact Group Holdings Limited |
| Silgan Holdings Inc. |
| Huhtamaki Oyj |
| Sealed Air Corporation |
| Manjushree Technopack Limited |
| Others |
Pricing and Supply Chain Analysis
Purified terephthalic acid and ethylene glycol feedstock costs cascade through PET preform manufacturing tiers, compressing margins at converter levels while concentrating pricing power among Maharashtra and Gujarat blow-molding clusters with captive resin sourcing.
Pricing Analysis
Distributor margin compression distinguishes beverage procurement from pharmaceutical packaging tiers. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified pharmaceutical-grade bottles from uncertified commodity water containers. Price differentiation hinges on migration testing compliance and lightweight preform engineering sophistication. Pricing pressure stems from annual supply contract lock-ins that prevent pass-through of ethylene glycol volatility. Private-label bottled water buyers exhibit highest price sensitivity, while pharmaceutical barrier specification buyers tolerate premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale beverage demand from Thailand and Vietnam retailers sourcing preforms directly from western Indian converters. Geographic supply concentrates in India, China, and Thailand, with raw material dependencies on purified terephthalic acid, ethylene glycol, and high-density polyethylene resin. Distribution runs through consolidated distributor tiers bypassed by headquarters-level procurement at large-format retailers. Single-source vulnerability characterizes the Maharashtra-Gujarat corridor, where preform supply concentration creates geographic risk for Southeast Asian bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge as BIS certification timelines extend product launch windows in India while China's SAMR enforcement accelerates masterbatch reformulation costs, creating cost differentials between compliant and non-compliant supply bases.
For Market Incumbents: Lock in barrier technology specialists through acquisition or exclusive supply arrangements before technician scarcity intensifies. Defend position by deepening backward integration into resin compounding to neutralize ethylene glycol volatility exposure. Prioritize certification investment in Maharashtra and Gujarat laboratory testing capabilities to capture volume redirected by BIS compulsory registration schemes.
For New Entrants and Emerging Players: Capture Indonesia's nascent refill-subscription infrastructure for household chemicals before platform economics solidify. Target pharmaceutical multi-layer co-injection segments where technician scarcity constrains incumbent expansion. Lead with digital printing convergence offerings that enable batch-level traceability without secondary operations.
For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification mandates phase out subscale converters and redirect volume toward certified facilities. Five-to-ten year viability favors integrated resin-to-preform operators with geographic diversification beyond western India. Monitor BIS laboratory testing queue lengths as inflection indicator for certification bottleneck severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive PTA and ethylene glycol sourcing neutralizes feedstock volatility for Maharashtra-Gujarat converters. |
| Multi-Layer Co-Injection Capacity Expansion | Oxygen and UV barrier specifications from Japan's METI guidelines drive pharmaceutical packaging premiums. |
| Digital Printing Convergence with Blow Molding | In-mold labeling integration satisfies pharmaceutical serialization requirements without secondary label operations. |
| Geographic Manufacturing Joint Ventures | Thailand and Vietnam bottler partnerships reduce logistics exposure from western India supply concentration. |
| Lightweight Preform Engineering Programs | Thin-wall PET designs reduce resin intensity per unit for Southeast Asian carbonated beverage lines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with blow-molding plant managers, beverage brand procurement leads, pharmaceutical packaging specification directors, and BIS certification laboratory heads informed demand-side validation. Secondary sources included customs trade databases, BIS registration records, SAMR GB standard filings, and METI Design for Environment guideline documents. Bottom-up preform volume estimates and top-down polymer consumption figures underwent iterative reconciliation.
Comparable-period anchoring linked forward projections to historical PET resin intensity trends and preform lightweighting adoption curves. Segmentation modeling spanned material type, end-use application, barrier feature category, and regional regulatory cluster. CAGRs derived from slope-consistency checks against carbonated beverage line expansion announcements and pharmaceutical packaging capacity commissioning patterns. Forecast inputs incorporated BIS certification timeline distributions and SAMR enforcement intensity assumptions.
Feedstock price volatility, regulatory timeline compression, and mechanical recycling infrastructure gaps are the dominant revision risks. Forecasts reflect documented assumptions about certification scheme phase-in schedules and preform engineering adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Post-Consumer Recycled Plastic Packaging Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
China Plastic Packaging Market
Plastic Packaging
Vacuum Forming Plastic Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market