
 Disposable Underwear Market | 2026-2036
Disposable Underwear Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Underwear Market Insights
Aging-care workforce shortages across developed economies is unwinding traditional reusable garment protocols in hospitals and long-term care facilities. Kimberly Clark Corporation leverages its institutional distribution networks to sustain North American supply contracts for absorbent hygiene products. Essity AB anchors European market presence through specialized medical-grade disposable underwear lines. Ontex Group competes on manufacturing scale, operating high-throughput facilities that serve private-label pharmacy chains across multiple continents.
Disposable underwear denotes single-use absorbent garments engineered with superabsorbent polymer cores, breathable non-woven top sheets, and elasticized leg gathers to contain moisture and protect skin integrity in clinical, travel, and incontinence applications. The product category serves infection control protocols, mobility-limited patient dignity, and temporary hygiene needs where laundering infrastructure proves impractical. Non-woven material formulations dominate production volumes due to cost-efficient meltblown and spunbond manufacturing, though biodegradable substrates represent the fastest-growing material segment as procurement policies harden against petroleum-derived synthetics. Healthcare end users command the largest demand share through hospital group purchasing organizations, while hospitality and travel channels expand through amenity-kit distributors serving airlines and cruise operators.
FDA medical device classifications govern absorbent garment claims in the United States, requiring clinical substantiation for skin-safety and fluid-retention performance. The EU Green Deal and REACH chemical restrictions are accelerating biodegradable material investments among manufacturers seeking CE-marked access. Stakeholders must monitor evolving compostability certification standards and institutional procurement carbon-accounting requirements to anticipate which material platforms will secure long-term contract eligibility.
Market Dynamics
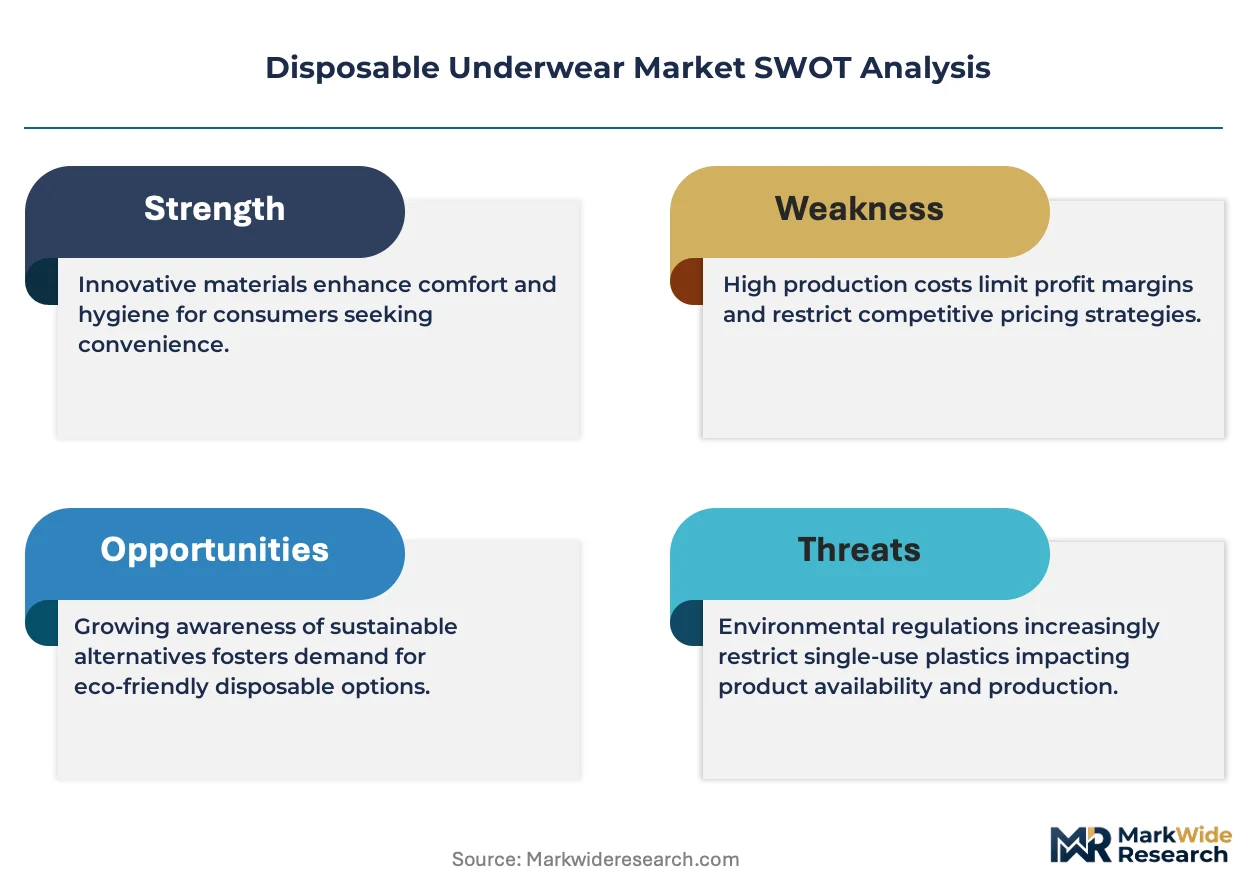
The EU's Single-Use Plastics Directive is forcing material transitions across the disposable underwear supply chain, compelling manufacturers to abandon petroleum-derived synthetics for certified biodegradable substrates or lose institutional contract eligibility in European healthcare systems.
Growth Catalysts
- Aging-care workforce shortages:Hospitals and long-term care facilities in Japan, Germany, and the United States are abandoning reusable garment protocols. Labor cost pressures drive adoption of single-use alternatives that eliminate laundering infrastructure and reduce infection control staffing demands.
- REACH chemical restrictions:ECHA's tightening limits on residual monomers in superabsorbent polymers are accelerating R&D investments in bio-based alternatives. Manufacturers securing early compliance capture preferential sourcing status from EU hospital group purchasing organizations.
- Superabsorbent polymer core advances:Next-generation sodium polyacrylate formulations with enhanced fluid retention rates are expanding addressable applications. Post-surgical and maternity segments adopt premium disposable underwear where reusable options previously dominated.
Market Restraints
- Fluff pulp price volatility:Scandinavian pulp mill supply disruptions and energy cost spikes in 2023-2024 compressed margins for manufacturers dependent on conventional absorbent cores. Input cost pass-through remains incomplete in fixed-price institutional contracts.
- Compostability certification fragmentation:Competing standards from TÜV Austria, BPI, and DIN CERTCO create compliance complexity. Manufacturers face redundant testing costs to maintain multi-jurisdiction market access.
- Reusable garment substitution in home care:Washable incontinence products with antimicrobial textile treatments are gaining traction among cost-conscious family caregivers outside institutional settings.
Strategic Opportunities
- India's hospital infrastructure expansion:Ayushman Bharat health insurance coverage expansion is creating demand for single-use hygiene products in tier-2 and tier-3 cities. Domestic manufacturing under PLI scheme incentives offers cost-competitive export positioning.
- Cruise line amenity-kit channels:Premium disposable underwear integration into passenger wellness programs represents untapped hospitality revenue. Direct sourcing relationships with Carnival, Royal Caribbean, and MSC bypass traditional distributor markups.
- EU Green Deal procurement mandates:Mandatory carbon-accounting requirements in public healthcare tenders favor suppliers with verified biodegradable supply chains. Early movers secure multi-year framework agreements before compliance becomes universal.
Industry Challenges
- Biodegradable polymer processing expertise:PLA and PHA substrate conversion requires extrusion and thermal bonding capabilities distinct from conventional polypropylene operations. Technical talent scarcity in bio-based non-woven engineering constrains capacity expansion timelines.
- FDA 510(k) substantiation timelines:Medical device claims for skin-safety and fluid-retention performance require clinical documentation averaging 18-24 months. Pipeline products face revenue recognition delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Underwear Market |
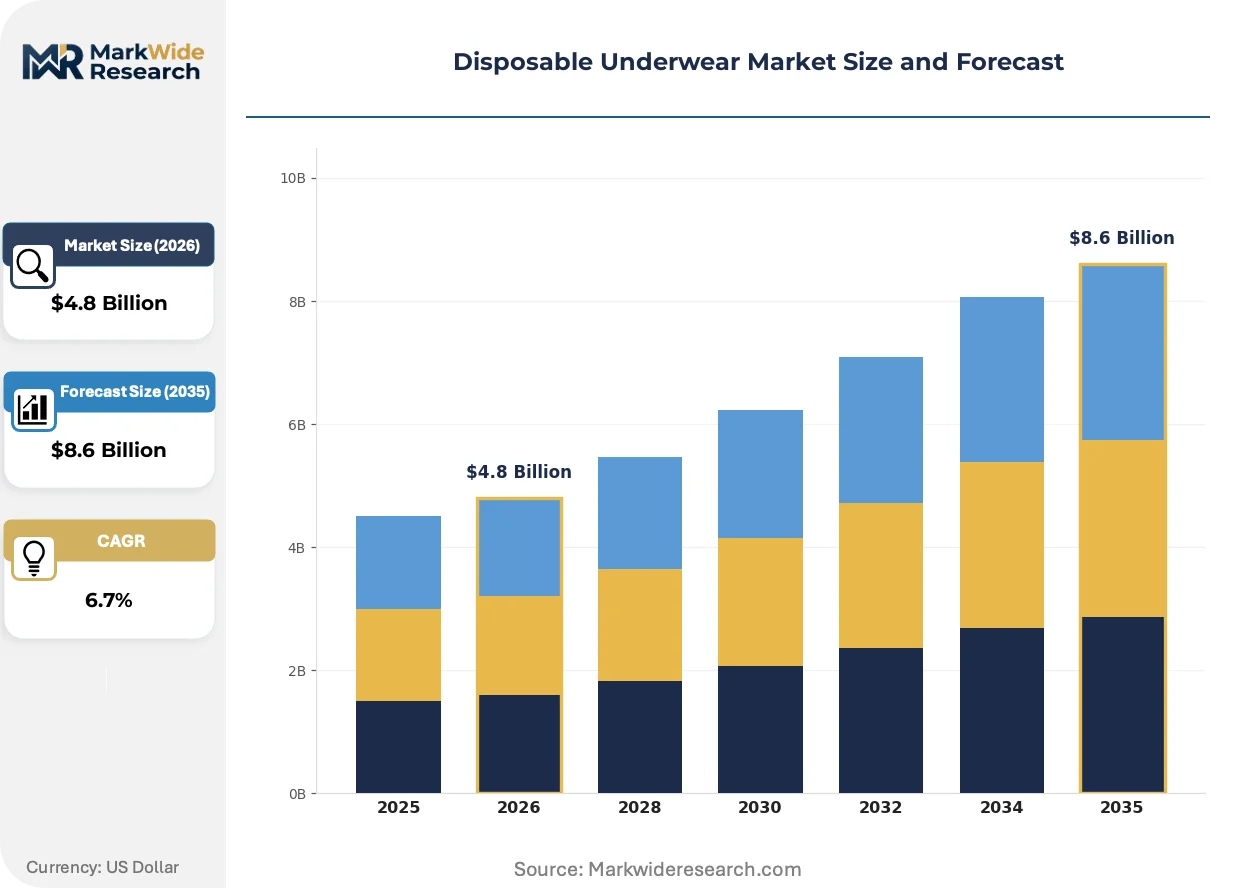
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Men's, Women's, Unisex, Children's Material: Non-Woven, Cotton, Biodegradable, Synthetic Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores End User: Healthcare, Hospitality, Travel, Personal Care |
| Companies Covered | Kao Corporation, Ontex Group, Kimberly Clark Corporation, Hengan International Group, Paul Hartmann AG, Essity AB, First Quality Enterprises, Medline Industries, Unicharm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Underwear Market Trends and Innovations
Material science breakthroughs and regulatory compliance architectures are reshaping competitive positioning in disposable underwear manufacturing, with biodegradability certification and supply chain transparency emerging as primary differentiation vectors.
Superabsorbent polymer core technology is miniaturizing through precision-engineered gradient-density layering that maintains fluid retention capacity while reducing overall garment bulk. Post-acute care facilities and ambulatory surgical centers are adopting these slim-profile designs to improve patient mobility and dignity. The structural compression of core thickness is enabling discrete product formats that expand addressable demand beyond traditional incontinence applications into travel and wellness segments.
REACH chemical restrictions are eliminating conventional acrylic-based superabsorbent polymers from EU-bound production lines, forcing substrate reformulation investments. Manufacturers are retrofitting meltblown lines to process polylactic acid and starch-based alternatives at commercial scale. Medical-grade disposable underwear lines targeting CE-marked access face the steepest compliance cost burdens, with smaller private-label competitors exiting the European market entirely.
Hospital group purchasing organizations are consolidating supplier rosters around carbon-accounting transparency requirements. Three-year framework agreements now mandate third-party lifecycle assessment documentation for all product categories. German procurement coalitions led by University Hospital Cologne and Charité Berlin are establishing the template specifications that diffuse across Austrian and Swiss institutional buyers within 18-24 month adoption cycles.
Disposable Underwear Market Segmentation
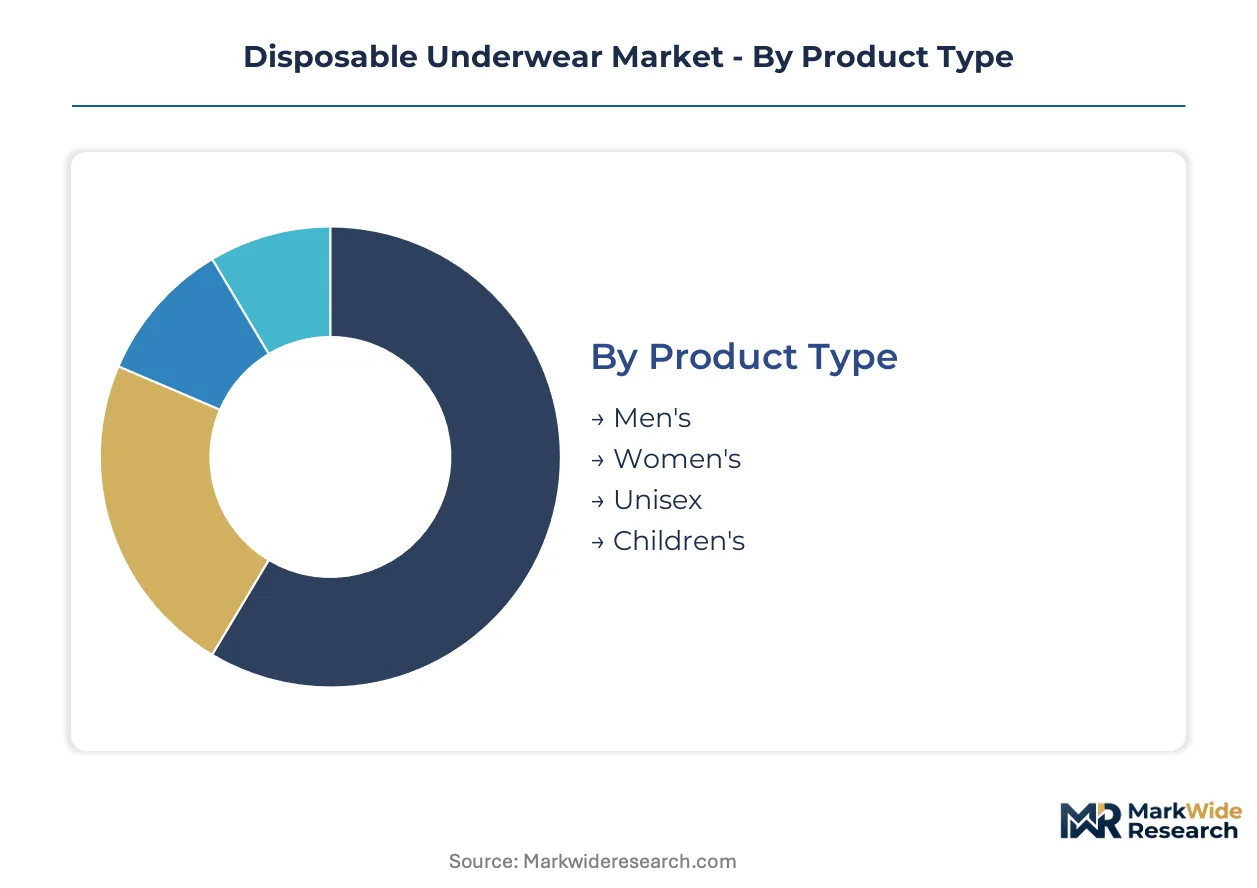
Disposable underwear manufacturers must navigate divergent channel economics and regulatory requirements across product configurations. Material choices and distribution pathways determine contract eligibility in institutional procurement while shaping margin profiles in consumer-direct segments.
Product Type:
Channel mix varies sharply by gendered and age-based segments, with institutional buyers consolidating volume around unisex specifications while retail channels fragment across specialized fits.
- Men's:Anatomical pouch designs with targeted absorbency zones address post-prostate surgery and mobility-limited demographics. German hospital procurement coalitions specify men's lines for urology wards, driving premium pricing for medical-grade certifications.
- Women's:Contoured waistbands and wider rear coverage accommodate maternity and post-surgical recovery applications. Demand concentrates in ambulatory surgical centers across Japan and the United States where patient dignity protocols favor discrete disposable options over reusable alternatives.
- Unisex:Standardized fits dominate bulk institutional contracts through group purchasing organizations, sacrificing customization for inventory efficiency and volume pricing leverage.
- Children's:Smaller-scale production runs serve pediatric specialty distributors and family travel segments with lower per-unit margins offset by brand loyalty development.
By volume, Unisex leads through hospital procurement consolidation. By growth pace, Women's is climbing the fastest as post-acute care facilities expand.
Material:
Cost tier stratification separates commodity petroleum-based substrates from premium biodegradable alternatives, with regulatory compliance costs widening the pricing spread.
- Non-Woven:Spunbond-meltblown-spunbond polypropylene laminates deliver cost-efficient fluid management at scale. Mass-market pharmacy chains across India and Brazil anchor volume demand for standard incontinence applications where price sensitivity dominates.
- Biodegradable:Polylactic acid and starch-based alternatives command 40-60% price premiums over conventional substrates. EU Green Deal procurement mandates in Germany, France, and the Netherlands are accelerating hospital tender specifications toward certified compostable materials.
- Cotton:Natural fiber blends target skin-sensitive demographics in premium personal care segments, limited by higher unit costs and laundering-equipment substitution in home care settings.
- Synthetic:Petroleum-derived alternatives retain residual share in price-pressured emerging markets where regulatory enforcement of single-use plastics restrictions remains uneven.
By volume, Non-Woven dominates manufacturing throughput. By margin expansion trajectory, Biodegradable is gaining share fastest as procurement policies harden.
Distribution Channel:
Customer type determines channel selection, with institutional buyers bypassing retail markup structures while convenience-seeking consumers fragment across digital and physical touchpoints.
- Online:Direct-to-consumer subscriptions and discrete delivery address stigma-sensitive incontinence purchasers. Amazon and specialized medical supply platforms capture recurring revenue through auto-replenishment algorithms.
- Supermarkets:Mass-market visibility drives impulse purchases in travel and light incontinence segments, though shelf space competition from established absorbent hygiene brands constrains new entrant access.
- Pharmacies:Pharmacist consultation influence shapes premium product selection for post-surgical and maternity applications, with private-label expansion pressuring branded margins.
- Specialty Stores:Medical equipment dealers and surgical supply distributors serve long-term care facilities with bulk fulfillment and reimbursement documentation support.
By transaction volume, Pharmacies lead through insurance-reimbursed institutional flows. By channel growth, Online is expanding most quickly as subscription models reduce customer acquisition costs.
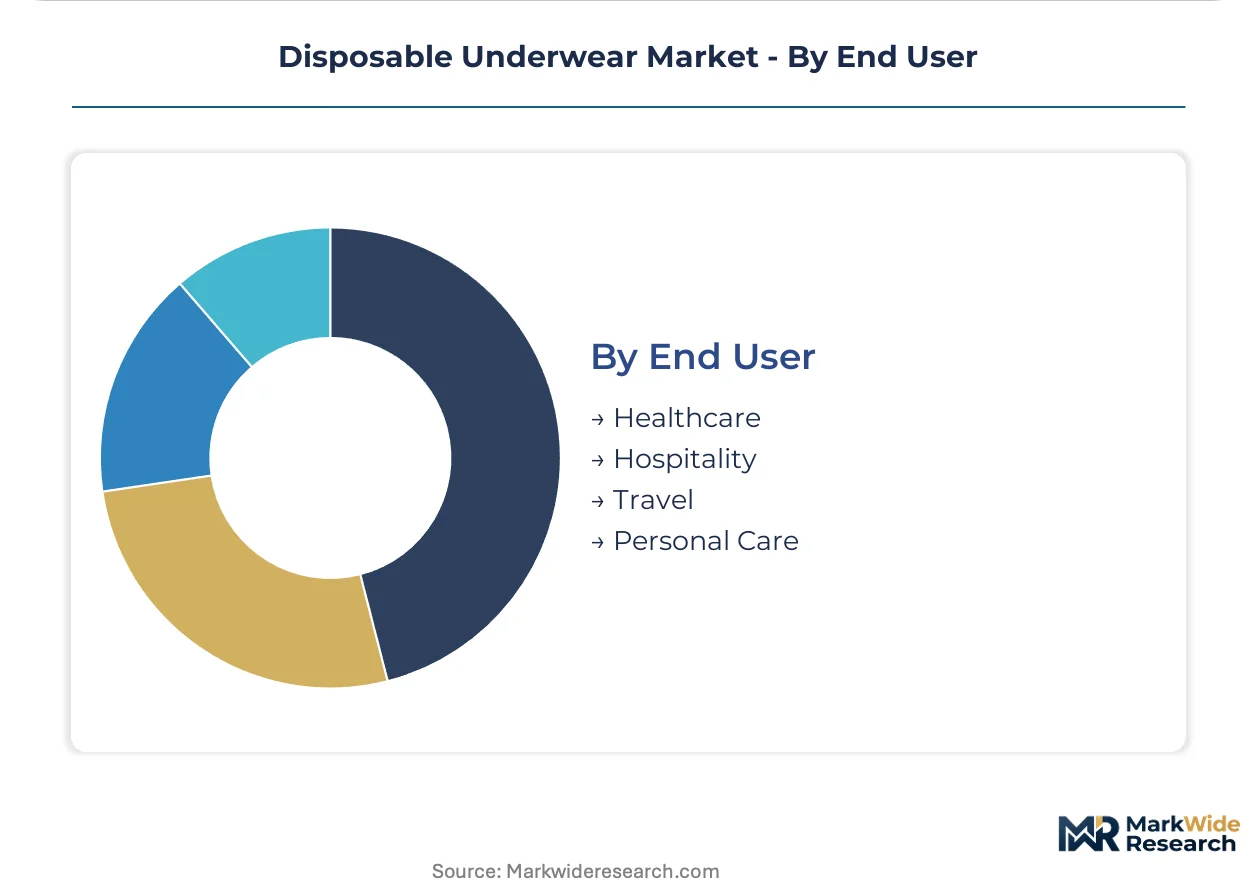
End User:
Application maturity varies across clinical, hospitality, and personal use cases, with regulatory intensity and procurement sophistication shaping competitive dynamics.
- Healthcare:Infection control protocols and laundering cost elimination drive hospital and nursing facility adoption. FDA medical device classifications and ECHA REACH compliance requirements create dual-jurisdiction certification burdens for multinational suppliers.
- Hospitality:Cruise line and airline amenity integration represents nascent premium positioning, with Carnival and Royal Caribbean piloting wellness-program inclusion for passenger convenience.
- Travel:Compact disposable formats target backpackers and business travelers through airport retail and adventure gear distributors, seasonal demand patterns complicating inventory planning.
- Personal Care:Home-based incontinence management competes with reusable textile alternatives, cost-conscious family caregivers driving private-label pharmacy preference over premium branded offerings.
By revenue concentration, Healthcare leads through durable institutional contracts. By application expansion, Hospitality is climbing the fastest as experiential travel operators differentiate passenger service tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital procurement coalitions consume disposable underwear under stricter biodegradability mandates than Japanese facilities, where workforce shortages accelerate adoption regardless of substrate composition. This consumption-mix differential fragments supplier strategies across regulatory jurisdictions.
Germany
University Hospital Cologne and Charité Berlin anchor institutional demand through carbon-accounting procurement frameworks. The EU Green Deal mandates lifecycle assessment documentation for all public healthcare tenders. Manufacturing clusters in North Rhine-Westphalia retrofit meltblown lines to process polylactic acid alternatives at commercial scale.
United States
Post-acute care facilities and ambulatory surgical centers drive premium adoption as patient dignity protocols displace reusable garments. FDA 510(k) medical device classifications govern absorbent garment claims requiring clinical substantiation. Distribution concentrates through group purchasing organizations serving hospital networks across the Midwest and Southeast corridors.
Japan
Aging-care workforce shortages unwind traditional laundering protocols in nursing facilities faster than any developed economy. METI guidelines on infection control staffing ratios institutionalize single-use alternatives. Osaka-based medical supply distributors consolidate volume through keiretsu procurement relationships with metropolitan hospital systems.
India
Ayushman Bharat health insurance expansion creates demand in tier-2 and tier-3 cities lacking laundry infrastructure. The PLI scheme incentivizes domestic manufacturing of absorbent hygiene products. Gujarat and Maharashtra host emerging production clusters targeting cost-competitive export positioning toward Middle Eastern markets.
China
Hospital infrastructure modernization in provincial capitals absorbs volume from standardized unisex product lines. NMPA medical device registrations align with international quality benchmarks for export-oriented manufacturers. Yangtze River Delta production hubs serve both domestic institutional procurement and private-label contracts for Southeast Asian distributors.
Disposable Underwear Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding institutional distribution networks and the latter competing on manufacturing scale or regional cost positioning. The upper tier secures multi-year framework agreements through carbon-accounting transparency and biodegradability certification. Three archetypes populate the competitive map: integrated hygiene conglomerates with captive polymer research, private-label manufacturers operating high-throughput facilities across multiple continents, and regional specialists leveraging domestic regulatory familiarity. Dominant competitive moves include backward integration into bio-based substrate supply chains and strategic partnerships with hospital group purchasing organizations to secure tender eligibility.
Among the integrated tier, Kimberly Clark Corporation and Essity AB exemplify divergent geographic anchoring strategies, with the former leveraging North American institutional networks and the latter securing CE-marked access through specialized medical-grade lines. Ontex Group occupies a position within the scale-driven private-label segment, operating facilities that serve pharmacy chains across multiple jurisdictions. These three entities represent the competitive spectrum from premium certification-heavy positioning to volume-oriented cost leadership.
| Leading Market Players |
|---|
| Kao Corporation |
| Ontex Group |
| Kimberly Clark Corporation |
| Hengan International Group |
| Paul Hartmann AG |
| Essity AB |
| First Quality Enterprises |
| Medline Industries |
| Unicharm Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at high-throughput meltblown facilities in Germany and China establishes cost floors that smaller competitors cannot match, concentrating supply-side power among integrated manufacturers while forcing price discipline across biodegradable and conventional substrate tiers.
Pricing Analysis
Long-term offtake agreements dominate institutional procurement, with hospital group purchasing organizations locking in three-year framework contracts that specify carbon-accounting documentation and compostability certification tiers. Price differentiation hinges on biodegradability grade and FDA 510(k) medical device classification, with certified premium lines commanding substantial markups over private-label pharmacy alternatives. Cost compression in standard non-woven tiers is intensifying because of Scandinavian fluff pulp supply volatility and energy input spikes. Family caregivers in home care settings exhibit the highest price sensitivity, while German hospital procurement coalitions prioritize compliance transparency over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among institutional distributors serving acute care facilities, though strategic stockpiling of superabsorbent polymer feedstocks buffers against Scandinavian pulp mill disruptions. Manufacturing concentrates in Germany, China, and India, with North Rhine-Westphalia clusters retrofitting lines for polylactic acid processing and Yangtze River Delta hubs serving export markets. Raw material dependencies center on sodium polyacrylate formulations, spunbond polypropylene resins, and certified biodegradable substrates. Single-source vulnerability in bio-based polymer engineering talent constrains capacity expansion timelines. Distribution runs through group purchasing organizations and specialized medical supply distributors with keiretsu relationships in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of extrusion engineers capable of processing polylactic acid and starch-based alternatives at commercial scale is constraining which manufacturers can capture EU Green Deal procurement mandates, creating a capability moat around early movers with retrofit production lines.
For Market Incumbents: Consolidate backward integration into bio-based substrate supply chains before REACH chemical restrictions eliminate conventional polymer options from European production lines. Secure multi-year framework agreements with German hospital procurement coalitions by embedding third-party lifecycle assessment documentation into standard contract terms. Capacity expansion in Gujarat and Maharashtra under India's PLI scheme offers cost-competitive positioning for Middle Eastern export markets. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships opens institutional access faster than FDA 510(k) timelines, particularly for post-surgical and maternity applications in ambulatory surgical centers. Target India's tier-2 and tier-3 hospital infrastructure expansion where laundry infrastructure gaps create immediate demand for single-use alternatives. Direct sourcing relationships with cruise line operators bypass established distributor markups in the hospitality channel. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with captive bio-based substrate research and established meltblown retrofit capabilities over pure-brand consumer plays. Long-term viability rests on securing compostability certification across multiple jurisdictions before standards fragment further. Acquisition targets should demonstrate verified supply chain transparency and carbon-accounting documentation. Monitor ECHA's tightening residual monomer limits as the inflection indicator for superabsorbent polymer formulation obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Substrates | Captive polylactic acid supply secures EU Green Deal tender eligibility before compliance becomes universal. |
| CE Marking Fast-Track Investment | Accelerated notified body partnerships unlock German hospital procurement coalitions ahead of FDA timelines. |
| Hospital System Partnership | Direct GPO relationships with University Hospital Cologne and Charité Berlin anchor multi-year volume commitments. |
| Sustainability Repositioning | TÜV Austria and DIN CERTCO certification expansion insulates against compostability standard fragmentation. |
| Geographic Manufacturing Footprint | Gujarat and Maharashtra facilities under PLI incentives target cost-competitive Middle Eastern export positioning. |
Research Methodology
The analysis maps biodegradable substrate transitions, superabsorbent polymer core advances, and institutional procurement pattern shifts, each validated through hospital purchasing committee interviews, biomedical engineering consultations, and GPO contracts managers across Germany, the United States, and Japan. Primary fieldwork with meltblown line operators and bio-based polymer R&D directors combined with secondary validation from ECHA regulatory filings, FDA 510(k) submission databases, and EU tender documentation. Bottom-up production capacity modeling and top-down procurement spend analysis were triangulated against trade flow data and hospital infrastructure investment disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled dimensions spanning material substrate tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs were derived from segmented demand elasticity analysis and input cost trajectory assumptions. Forecast inputs incorporated fluff pulp price volatility patterns, REACH chemical restriction implementation timelines, and workforce shortage severity indices in aging-care economies.
Underlying assumptions cover sustained EU Green Deal procurement mandate enforcement, biodegradability certification standard convergence, and superabsorbent polymer formulation transition feasibility, with deviation risk concentrated in ECHA regulatory timeline acceleration and bio-based substrate processing talent availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Asia Health Check-Ups Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Parents-In-Waiting: Global Prenatal Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market
Personal Health
Menstrual Cup Market
Personal Health
Foot Insole Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Tongue Scraper Market
Personal Health
Reusable Face Mask Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Jet Lag Therapy Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Global Health and Wellness Market
Personal Health
Biohacking Market
Personal Health
Global on Site Preventive Care Market
Personal Health
Patient Health Management Market