
 Keratoprosthesis (Kpro) Market | 2026-2036
Keratoprosthesis (Kpro) Market Size, Share, and Industry Trends Forecast 2026-2036
Keratoprosthesis (Kpro) Market Foresight
Collagen-mimetic biocompatible coatings is tilting Kpro manufacturing toward surfaces that reduce postoperative stromal melting and device extrusion. CorneaGen Inc. anchors North American distribution through its corneal tissue network and synthetic graft portfolio. EyeYon Medical specializes in endothelial therapeutic adjuncts that complement Kpro implantation workflows. Aurolab dominates cost-sensitive segments with PMMA-based devices engineered for high-volume ophthalmic camps.
Keratoprosthesis constitutes an artificial corneal substitute, typically fabricated from polymethyl methacrylate (PMMA) or silicone with titanium or polymethyl methacrylate backplates, designed to restore optical clarity when human donor corneal transplantation fails or is contraindicated. The device creates a permanent optical pathway through an opaque or vascularized cornea while maintaining intraocular pressure integrity. Boston Kpro devices command the largest installed base among product types due to decades of surgical familiarity and published outcomes data. Hospitals represent the dominant end-user channel, though ophthalmic clinics are capturing faster growth as outpatient Kpro procedures expand under ambulatory surgery center protocols.
FDA PMA requirements enforce rigorous clinical evidence standards for novel Kpro designs, while EU MDR and CE marking obligations extend post-market surveillance mandates across European markets. The analysis indicates that stakeholders must track evolving reimbursement codes for Kpro procedures alongside biocompatibility testing protocols, as regulatory stringency directly shapes which device platforms achieve commercial scalability.
Market Dynamics
Collagen-mimetic surface engineering is compressing postoperative complication timelines and forcing device manufacturers to abandon legacy PMMA-only architectures in favor of hybrid biocompatible platforms.
Growth Catalysts
- EU MDR post-market surveillance mandates:Stricter clinical follow-up requirements under the Medical Device Regulation are accelerating evidence-generation investments among manufacturers, creating competitive moats for compliant device platforms.
- Ambulatory surgery center protocols:Outpatient Kpro procedures are expanding rapidly as ophthalmic clinics adopt same-day discharge standards, shifting procedure volume away from inpatient hospital settings.
- Corneal donor shortages in Japan:Persistent tissue scarcity is driving surgical familiarity with synthetic alternatives, expanding the addressable patient pool beyond repeat graft failures.
Market Restraints
- PMMA input cost volatility:Petrochemical feedstock fluctuations create margin pressure for manufacturers of traditional polymethyl methacrylate devices, particularly in cost-sensitive segments.
- Supply concentration in Boston Kpro installed base:Decades of published outcomes data have locked surgical training and institutional purchasing around a single dominant design, creating switching friction for novel platforms.
- FDA PMA evidentiary thresholds:Rigorous clinical evidence requirements for novel Kpro designs extend development timelines and capital requirements, filtering out undercapitalized entrants.
Strategic Opportunities
- Underpenetrated German tertiary centers:Regional disparities in Kpro surgical volume present expansion potential for device manufacturers with dedicated training infrastructure.
- Endothelial therapeutic adjunct convergence:Combination workflows integrating Kpro implantation with cell-based therapies are opening new reimbursement pathways and premium pricing tiers.
- CE marking acceleration under notified body specialization:Concentrated ophthalmic device expertise among select EU notified bodies is compressing regulatory timelines for MDR-compliant submissions.
Industry Challenges
- Keratoprosthesis surgical skill scarcity:The specialized training required for complex anterior segment reconstruction limits addressable surgeon pools and constrains procedure volume growth.
- Biocompatibility certification timelines:Extended ISO 10993 testing protocols for novel coating chemistries delay product launches and tie up R&D capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keratoprosthesis (Kpro) Market |
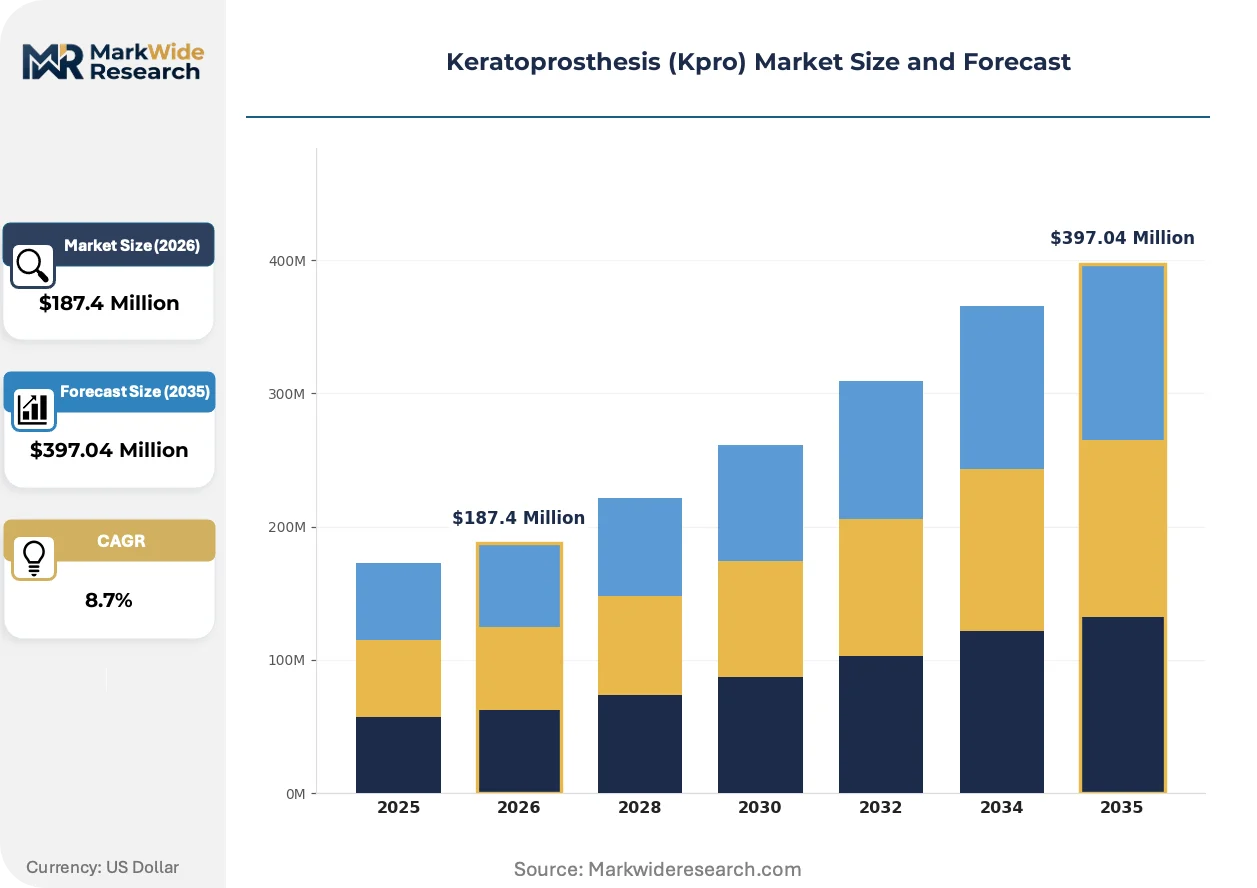
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boston Kpro, Alpha Kpro, Osteo Ocular, Other Options End User: Hospitals, Ophthalmic Clinics, Research Institutes, Specialty Centers Material: Polycarbonate, Silicone, PMMA, Biocompatible Coatings Application: Corneal Blindness, Trauma, Chemical Burns, Severe Anterior Segment Disease |
| Companies Covered | CorneaGen Inc., EyeYon Medical, Aurolab, Boston Keratoprosthesis (Massachusetts Eye and Ear), DIOPTEX GmbH, Addition Technology, Inc., LinkoCare Life Sciences AB, FCI Ophthalmics, Inc., KeraMed, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keratoprosthesis (Kpro) Market Shifts & Advancements
Surface chemistry innovation is displacing material-centric competition in Kpro manufacturing, with biocompatibility performance now outweighing optical clarity as the primary design axis.
Collagen-mimetic biocompatible coatings are digitizing manufacturing quality control through real-time surface characterization protocols. Device fabricators are adopting atomic force microscopy and spectroscopic ellipsometry for coating uniformity verification. Tertiary ophthalmic centers are digitizing their supply chain qualification processes, compressing vendor onboarding from months to weeks.
EU MDR Article 10 post-market clinical follow-up requirements are extending surveillance obligations across European markets. Manufacturers must now commit to multi-year patient registries as a condition of CE marking renewal. Boston Kpro and novel device platforms face equivalent documentation burdens, leveling competitive dynamics for emerging entrants.
After-sales service unbundling is fragmenting traditional device-vendor relationships in the United States. Hospitals are separating Kpro procurement from surgical training contracts, forcing manufacturers to price training modules independently. This shift is most visible in high-volume ophthalmic centers where procurement committees now negotiate device and education spend through distinct vendor evaluation tracks.
Keratoprosthesis (Kpro) Market Segmentation
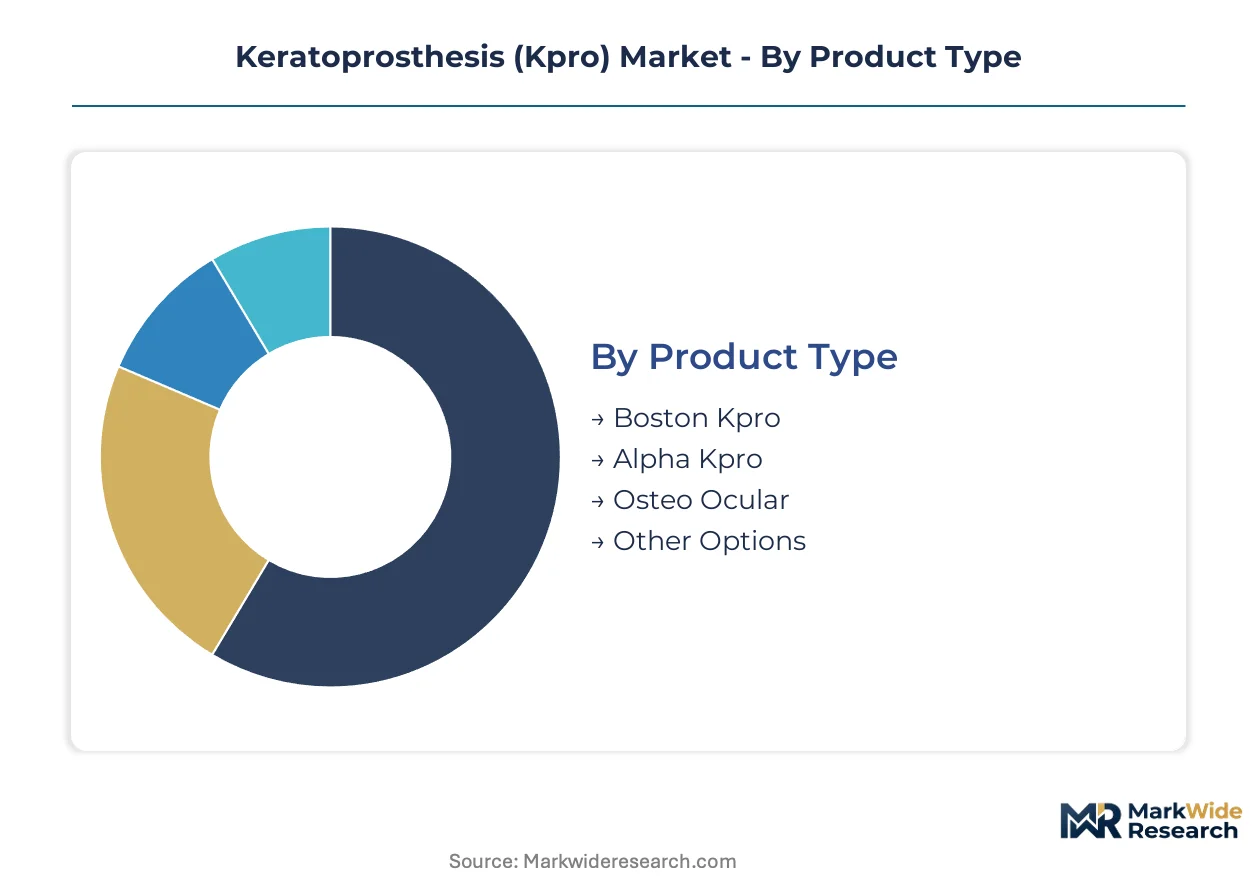
Keratoprosthesis segmentation reveals how device architecture, clinical setting, and patient pathology intersect to determine commercial viability. Manufacturers must align platform specifications with reimbursement pathways and surgical workflow constraints across each dimension.
Product Type:
Cost tier stratification separates established platforms with decades of outcomes data from emerging designs competing on biocompatibility performance.
- Boston Kpro:The titanium backplate and polymethyl methacrylate optical cylinder design has accumulated the largest surgical outcomes database. Tertiary ophthalmic centers in the United States and Germany anchor procurement volume due to training infrastructure familiarity and institutional purchasing agreements.
- Alpha Kpro:This PMMA-based platform incorporates a flexible skirt design intended to reduce stromal melting complications. Demand clusters in cost-sensitive markets where device procurement budgets constrain platform selection, particularly high-volume ophthalmic camps in South Asia.
- Osteo Ocular:Titanium-integrated architecture targets patients with severe autoimmune ocular surface disease. The design addresses extrusion risk in repeat graft failure populations.
- Other Options:Emerging platforms include custom-fabricated devices and experimental biointegrative designs under early clinical evaluation.
Boston Kpro holds installed capacity. Alpha Kpro is rotating up the share rankings.
End User:
Customer type determines reimbursement coding complexity and capital equipment requirements for device implantation workflows.
- Hospitals:Inpatient surgical suites manage complex anterior segment reconstructions requiring anesthesia support and overnight observation. These facilities capture high-acuity cases with concurrent ocular comorbidities.
- Ophthalmic Clinics:Ambulatory surgery center protocols enable same-day discharge for uncomplicated Kpro procedures. This channel is expanding fastest as outpatient reimbursement codes mature and surgical efficiency improves.
- Research Institutes:Academic medical centers conduct post-market clinical follow-up registries mandated by EU MDR Article 10 requirements. These institutions generate evidence for CE marking renewals and FDA PMA supplements.
- Specialty Centers:Dedicated corneal service lines concentrate surgical volume and maintain dedicated Kpro nursing protocols. Centers in Japan leverage this model to address persistent donor tissue scarcity.
Hospitals retain the dominant share position. Ophthalmic clinics are climbing the fastest.
Material:
Supply concentration and biocompatibility certification timelines differentiate material selection for manufacturers.
- PMMA:Polymethyl methacrylate dominates legacy device fabrication due to optical clarity and established machining protocols. Petrochemical feedstock volatility creates margin pressure for manufacturers dependent on this material.
- Biocompatible Coatings:Collagen-mimetic surface chemistries are displacing bare PMMA architectures as the primary design axis. ISO 10993 testing protocols extend development timelines but reduce postoperative complication rates.
- Silicone:Flexible optical materials enable specific design geometries for complex anterior segment anatomies. Applications remain niche due to manufacturing complexity.
- Polycarbonate:High-impact resistance properties suit trauma reconstruction scenarios. Limited adoption reflects optical performance trade-offs against PMMA alternatives.
PMMA holds installed capacity. Biocompatible coatings are rotating up the share rankings.
Application:
Patient pathology severity determines device selection criteria and postoperative surveillance intensity.
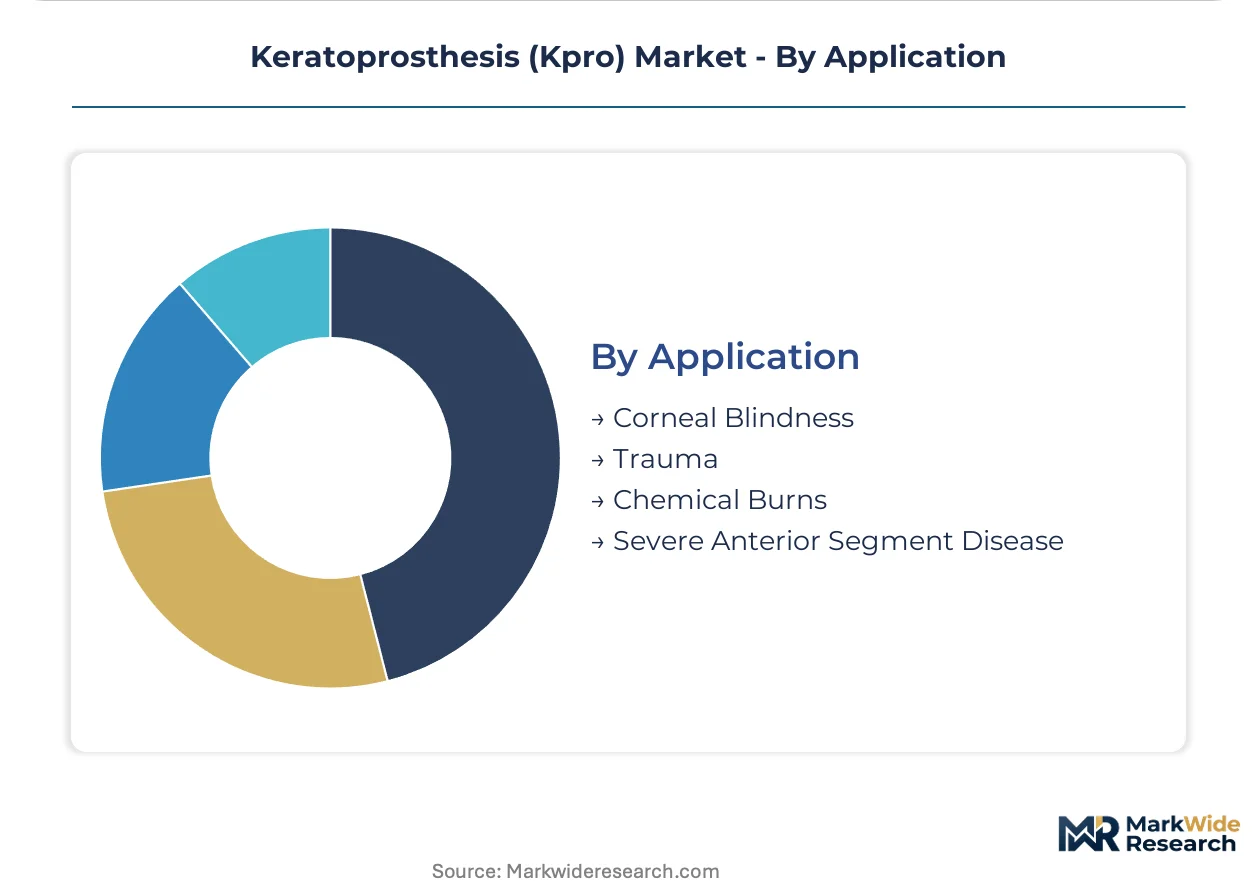
- Corneal Blindness:End-stage corneal opacification from multiple graft failures represents the core indication. Boston Kpro outcomes data specifically supports reimbursement in this population.
- Chemical Burns:Acute alkali or acid exposure creates limbal stem cell deficiency and conjunctival cicatrization. These cases require staged reconstruction with Kpro implantation following ocular surface stabilization.
- Trauma:Penetrating injury with corneal tissue loss may proceed directly to Kpro when donor tissue is unavailable or contraindicated. Military and industrial accident populations drive demand.
- Severe Anterior Segment Disease:Autoimmune conditions including Stevens-Johnson syndrome and ocular cicatricial pemphigoid present extrusion risks that influence device platform selection.
Corneal blindness holds installed capacity. Chemical burns are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tertiary ophthalmic centers in the United States, Germany, and Japan concentrate procurement volume for keratoprosthesis devices, with each market shaped by distinct regulatory pathways and corneal donor availability constraints.
United States
FDA PMA pathways enforce rigorous clinical evidence standards for novel Kpro designs, extending development timelines for emerging platforms. Boston Keratoprosthesis devices anchor the installed base through decades of surgical familiarity and published outcomes data. Massachusetts Eye and Ear maintains concentrated training infrastructure in Greater Boston, reinforcing institutional purchasing patterns among high-volume corneal service lines.
Germany
EU MDR post-market surveillance mandates under Article 10 requirements accelerate evidence-generation investments among manufacturers seeking CE marking renewal. Regional disparities in Kpro surgical volume persist across tertiary centers, with underpenetrated facilities in North Rhine-Westphalia presenting expansion potential for device manufacturers with dedicated training infrastructure. Notified body specialization in ophthalmic devices compresses regulatory timelines for MDR-compliant submissions.
Japan
Persistent corneal donor tissue scarcity drives surgical familiarity with synthetic alternatives, expanding the addressable patient pool beyond repeat graft failures. METI oversight of medical device quality management systems shapes manufacturer compliance investments. Tokyo and Osaka metropolitan areas concentrate specialized corneal service lines that leverage dedicated Kpro nursing protocols to address tissue scarcity.
India
CDSCO medical device registration requirements under the Medical Device Rules govern import and manufacturing compliance for Kpro platforms. Aurolab dominates cost-sensitive segments with PMMA-based devices engineered for high-volume ophthalmic camps across South Asia. Tamil Nadu and Karnataka host concentrated manufacturing and distribution infrastructure for synthetic corneal substitutes serving price-constrained markets.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while operating independent conformity assessment procedures. NHS specialized commissioning frameworks determine reimbursement access for Kpro procedures in tertiary ophthalmic centers. London and Manchester anchor clinical trial activity for novel device platforms seeking European market entry.
Keratoprosthesis (Kpro) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the keratoprosthesis market, with procurement concentration in tertiary ophthalmic centers creating tiered access dynamics. The installed base around Boston Kpro devices locks surgical training and institutional purchasing around a single dominant design, generating switching friction for novel platforms. Two strategic archetypes dominate: established platforms with decades of outcomes data and emerging biocompatible coating specialists. Competitive moves center on regulatory evidence generation for PMA and CE marking pathways, alongside unbundling of surgical training contracts from device procurement.
Among North American fabricators, CorneaGen Inc. and Addition Technology, Inc. occupy positions within the distribution and manufacturing tier. EyeYon Medical exemplifies the therapeutic adjunct specialist archetype, while DIOPTEX GmbH represents European precision manufacturing capabilities. LinkoCare Life Sciences AB anchors Nordic-based device development, and Aurolab sits within the cost-engineered manufacturing segment serving high-volume ophthalmic camps.
| Leading Market Players |
|---|
| CorneaGen Inc. |
| EyeYon Medical |
| Aurolab |
| Boston Keratoprosthesis (Massachusetts Eye and Ear) |
| DIOPTEX GmbH |
| Addition Technology, Inc. |
| LinkoCare Life Sciences AB |
| FCI Ophthalmics, Inc. |
| KeraMed, Inc. |
| Others |
Supply & Pricing Matrix
Tamil Nadu manufacturing clusters anchor PMMA device fabrication for cost-sensitive ophthalmic camps, concentrating procurement leverage among high-volume buyers who negotiate multi-year supply agreements. This geographic concentration feeds downstream pricing power toward tertiary centers in Germany and Japan, where device qualification timelines and biocompatibility certification costs create natural margin buffers against commodity-tier competition.
Pricing Analysis
Cost-plus contracts indexed to petrochemical feedstock benchmarks govern PMMA-based device procurement, with price adjustments triggered quarterly. Three-tier pricing structure across premium biocoated, standard titanium-backplate, and economy PMMA-only levels differentiates Boston Kpro, Alpha Kpro, and Aurolab offerings respectively. Pricing pressure stems from ophthalmic clinic procurement committees unbundling surgical training from device contracts, forcing standalone module pricing. Cost-sensitive segments in South Asia exhibit highest price elasticity, while Japanese tertiary centers prioritize outcomes data over acquisition cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Tamil Nadu fabricators enable inventory-light distribution models for European and North American distributors. PMMA optical cylinders, titanium backplates, and collagen-mimetic coating chemistries draw from India, Germany, and specialized chemical suppliers in the United States. Single-source vulnerability concentrates in ISO 10993-certified coating substrate providers, where biocompatibility testing bottlenecks create allocation risk. Distribution runs through corneal tissue networks and dedicated ophthalmic device distributors serving hospital purchasing committees and ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement committee consolidation across United States hospital systems and German hospital networks is shifting bargaining power toward institutional buyers who demand unbundled pricing transparency. This buyer-side concentration rewards manufacturers with modular service architectures and penalizes bundled legacy contracts.
For Market Incumbents: Harden regulatory evidence moats through accelerated EU MDR Article 10 registry commitments and FDA PMA supplement filings for biocoated platform extensions. Deepen backward integration into collagen-mimetic substrate production to offset coating chemistry supply concentration. Defend against emerging biointegrative device entrants by locking exclusive training contracts with Massachusetts Eye and Ear and comparable tertiary centers before procurement unbundling completes. For New Entrants and Emerging Players: Underpenetrated North Rhine-Westphalia tertiary centers represent the most penetrable entry point for novel biocoated platforms with dedicated surgical training infrastructure. Chemical burn indication expansion in Japanese metropolitan areas offers secondary white-space with established reimbursement codes and documented tissue scarcity. Pursue GPO contract qualification pathways alongside individual hospital pilot programs to bypass Boston Kpro purchasing lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biocompatibility coating specialists with ISO 10993 certification completion and notified body relationships already established. Long-term viability hinges on convergence with endothelial therapeutic adjunct workflows rather than standalone device replacement. Acquisition targets should demonstrate CE marking renewal readiness under MDR and active post-market clinical follow-up registry enrollment. Monitor FDA breakthrough device designation petitions as inflection signals for platform validation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Notified body specialization in ophthalmic devices compresses MDR compliance timelines for novel coatings. |
| Hospital System Partnership | GPO contract qualification with United States purchasing committees secures volume commitments against procurement unbundling. |
| Backward Integration into Coating Substrates | In-house collagen-mimetic chemistry production reduces ISO 10993 testing queue dependency and margin volatility. |
| Software Companion Development | Digital surgical planning tools for anterior segment reconstruction differentiate training offerings from commodity device vendors. |
| Reimbursement Strategy | Outpatient procedure code expansion with CMS and German statutory insurers enables ambulatory surgery center volume capture. |
Research Methodology
Desk research of FDA PMA filings, EMA CE marking databases, and hospital procurement contract disclosures preceded structured interviews with corneal surgeons, biomedical engineers, GPO contracts managers, and ophthalmic device distributors. Primary fieldwork across tertiary centers in Boston, Tokyo, and Düsseldorf validated secondary estimates of surgical volume and training infrastructure concentration. Bottom-up device shipment modeling triangulated against top-down tertiary center capacity assessments.
Forecasts assume stable EU MDR enforcement intensity, continued corneal donor tissue scarcity in Japan, and unbundling of surgical training from device procurement in United States hospital systems. Segmentation modeling incorporated product type, end-user channel, material architecture, and patient pathology severity across the projection horizon. CAGRs derived from procedure volume growth rates, device replacement cycles, and pricing trajectory assumptions for biocoated versus legacy PMMA platforms.
Practitioners should monitor FDA breakthrough device designation petitions, EU MDR notified body capacity constraints, and ophthalmic clinic same-day discharge protocol adoption for early signals of competitive inflection. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hearing Aids Market
Medical Devices
Non-Invasive Brain Stimulation System Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Absorbable PGLA Surgical Sutures Market
Medical Devices
Versatile Cryosurgical Devices Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Urology Guidewires Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Capnography Devices Market
Medical Devices
Organ Care Market
Medical Devices
Ventilation Devices Market