
 Bandage Contact Lenses Market | 2026-2036
Bandage Contact Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Bandage Contact Lenses Market Outlook
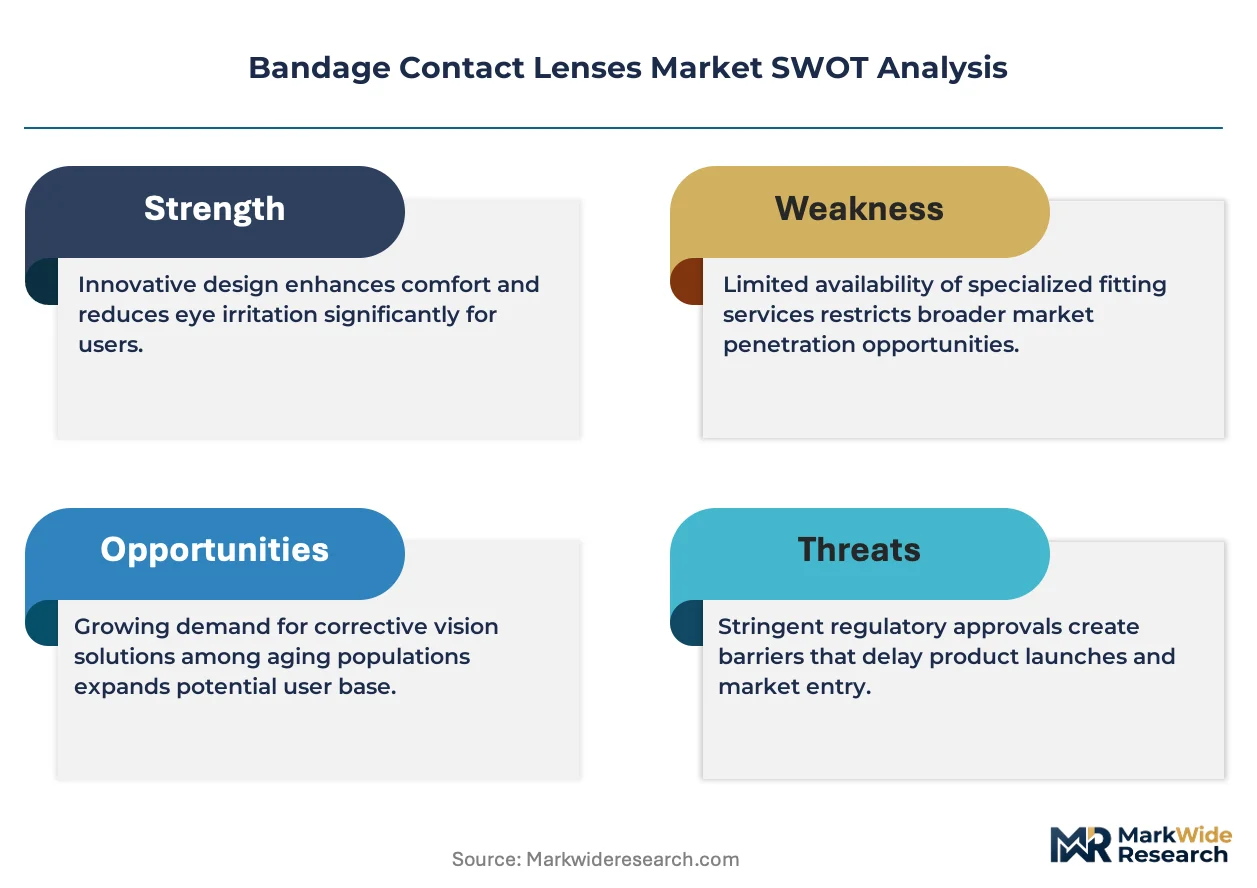
Consolidation among ophthalmology clinic chains is repositioning procurement leverage toward larger buyer networks. Alcon Inc. leverages its surgical suite relationships to sustain bandage lens placement post-procedure. Johnson & Johnson Vision Care anchors its position through retail optical store partnerships that extend therapeutic lens access. CooperVision competes on silicone hydrogel technology leadership, differentiating its portfolio with extended-wear oxygen permeability specifications.
Bandage contact lenses are medical devices designed for corneal protection and healing support, typically manufactured from silicone hydrogel or rigid gas permeable materials with oxygen transmissibility values exceeding 80 Dk/t to prevent hypoxic complications during extended wear. Their primary commercial purpose centers on post-surgical care and ocular surface disorder management, where the lens acts as a protective barrier promoting epithelial regeneration. Silicone hydrogel dominates the product type landscape due to superior oxygen delivery and reduced corneal staining risk compared to conventional hydrogel alternatives. Post-surgical care represents the most structurally entrenched application segment, while dry eye syndrome indications are gaining fastest clinical traction as meibomian gland dysfunction diagnoses expand. The end user base tilts toward ophthalmology clinics, where procedure volume concentration creates concentrated margin pools for manufacturers with direct sales forces.
FDA 510(k) clearance requirements and ISO 13485 quality management standards govern bandage lens commercialization, with the FDA's ophthalmic device division scrutinizing biocompatibility and sterility assurance testing protocols. The EU MDR framework imposes additional clinical evidence demands on manufacturers seeking CE marking for therapeutic indications, reshaping market access timelines and documentation burdens. Stakeholders must monitor evolving reimbursement coding for therapeutic lens indications, as payor coverage decisions will determine whether home care adoption can match institutional utilization rates.
Market Dynamics
Silicone hydrogel material breakthroughs are compressing oxygen permeability thresholds while FDA 510(k) clearance pathways for therapeutic indications accelerate clinical validation cycles, fundamentally restructuring how manufacturers compete on extended-wear specifications.
Growth Catalysts
- Post-surgical care protocols:Ambulatory surgical centers are expanding bandage lens deployment following refractive and corneal procedures, creating concentrated demand pools tied to procedure volume growth.
- FDA clearance pathways:Streamlined 510(k) review processes for therapeutic indications are reducing time-to-market for silicone hydrogel innovations with enhanced biocompatibility profiles.
- Corneal specialist density:United States metropolitan clusters with high ophthalmologist concentration support elevated utilization rates through established reimbursement infrastructure.
Market Restraints
- Raw material concentration:Silicone hydrogel polymer supply chains concentrate among specialty chemical producers in Germany and Japan, exposing manufacturers to input cost volatility.
- EU MDR documentation burdens:Clinical evidence requirements for CE marking under the Medical Device Regulation are extending market access timelines by 12-18 months for therapeutic indications.
- Conventional hydrogel substitution:Lower-cost hydrogel alternatives persist in price-sensitive institutional procurement, limiting premium silicone hydrogel penetration in developing markets.
Strategic Opportunities
- Dry eye syndrome expansion:Meibomian gland dysfunction diagnosis growth is opening therapeutic lens applications beyond post-surgical care into chronic ocular surface management.
- Home care reimbursement codes:Emerging payor coverage decisions for therapeutic lens home use could unlock patient-direct channels currently blocked by institutional billing requirements.
- Retail optical partnerships:Extended-wear silicone hydrogel specifications are enabling therapeutic lens placement through optometry chains with in-house corneal specialists.
Industry Challenges
- ISO 13485 compliance timelines:Quality management system certification for sterile device manufacturing requires 18-24 month validation cycles that constrain product line expansion.
- Biocompatibility testing bottlenecks:Cytotoxicity and sensitization assay backlogs at contracted laboratories are delaying FDA submission packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bandage Contact Lenses Market |
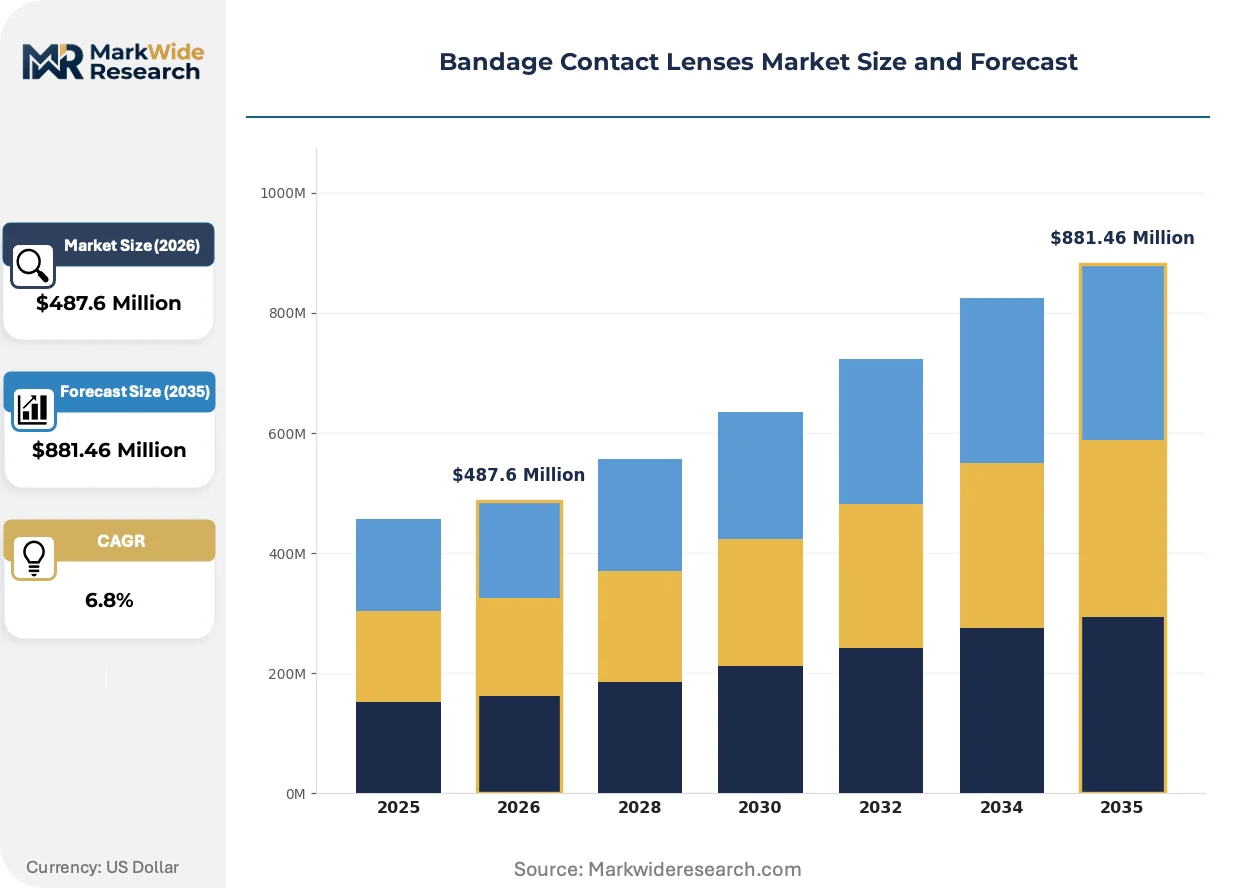
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Hydrogel, Rigid Gas Permeable, Soft Lenses, Therapeutic Lenses Application: Ocular Surface Disorders, Post-Surgical Care, Corneal Abrasions, Dry Eye Syndrome End User: Ophthalmology Clinics, Hospitals, Retail Optical Stores, Home Care Distribution Channel: Online Pharmacy, Retail Pharmacy, Direct Sales, Optical Stores |
| Companies Covered | Alcon Inc., Bausch & Lomb, CooperVision, Johnson & Johnson Vision Care, Advanced Vision Technologies, CLEARLAB SG PTE LTD, Excellent Hi-Care Pvt. Ltd., Metro Optics, UltraVision CLPL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bandage Contact Lenses Market Strategic Shifts
Material science advances and regulatory framework evolution are converging to reshape competitive differentiation around oxygen delivery performance and wear-duration claims.
Silicone hydrogel formulations with Dk/t values exceeding 150 are modularizing the traditional trade-off between extended wear duration and corneal health outcomes. Refractive surgery centers in the United States are adopting these specifications for 7-30 day continuous wear protocols. This modularization is compressing the addressable market for conventional hydrogel alternatives in premium therapeutic segments.
EU MDR clinical evidence requirements are forcing manufacturers to generate prospective safety data for CE marking renewal. The regulation demands post-market surveillance systems that track adverse events across distributed patient populations. Silicone hydrogel portfolios with existing FDA 510(k) clearances are leveraging US trial data to satisfy European notified body expectations.
Buying committees at ophthalmology clinic chains are consolidating procurement decisions across multi-site networks. Direct sales forces from established manufacturers are displacing independent distributor relationships in the United States. This concentration is most visible in California and Texas, where private equity-backed clinic roll-ups command volume pricing leverage.
Bandage Contact Lenses Market Segmentation
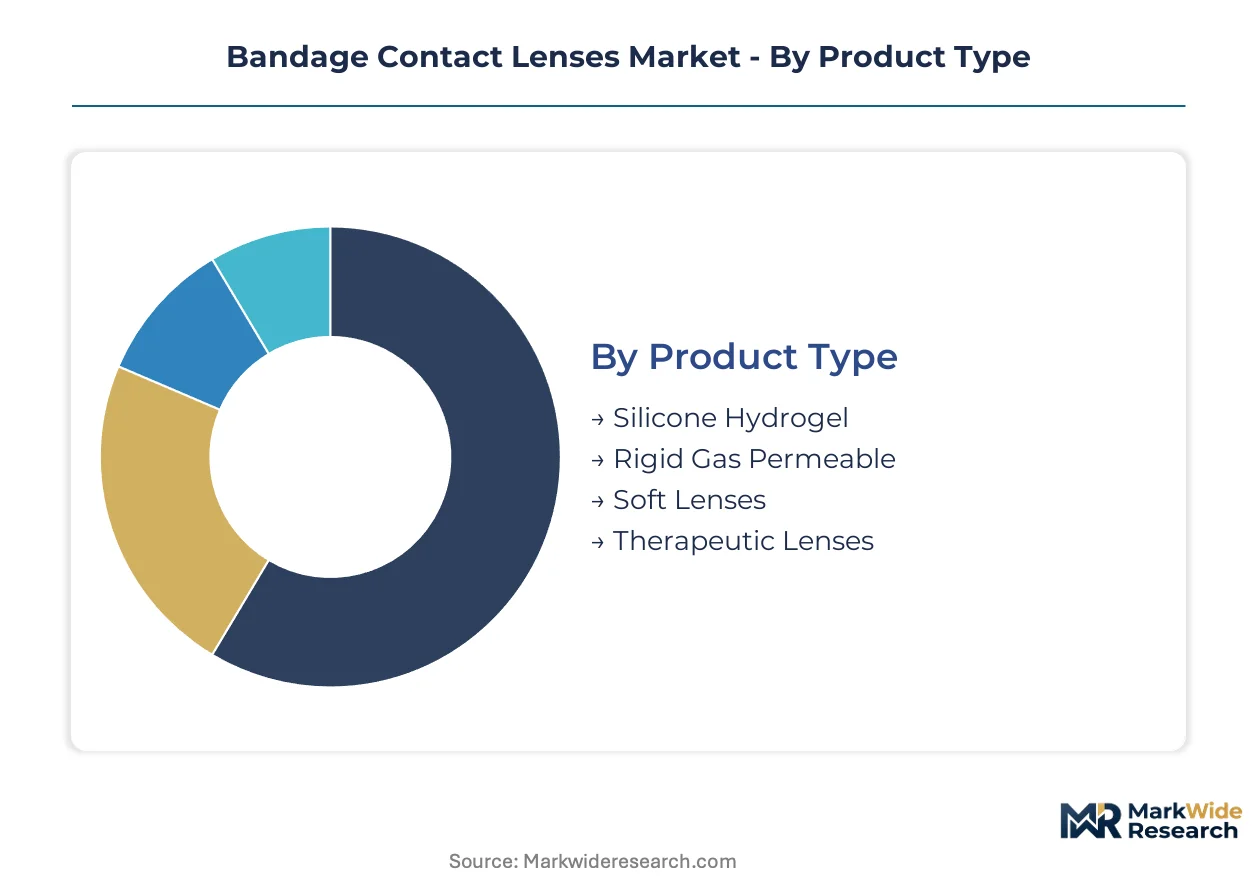
Bandage contact lens manufacturers align product portfolios with distinct certification pathways and reimbursement codes. Segment-specific FDA 510(k) requirements and EU MDR clinical evidence demands create divergent commercialization timelines across material platforms and therapeutic indications.
Product Type:
FDA 510(k) clearance intensity varies by material chemistry, with silicone hydrogel formulations facing enhanced biocompatility scrutiny compared to conventional alternatives.
- Silicone Hydrogel:Delivers oxygen transmissibility values exceeding 150 Dk/t through silicone-integrated polymer matrices. Demand concentrates in United States refractive surgery centers adopting 7-30 day continuous wear protocols following LASIK and corneal cross-linking procedures.
- Rigid Gas Permeable:Manufactured from fluorosilicone acrylate or silicone acrylate copolymers with superior optical clarity for irregular corneal surfaces. Post-keratoplasty care in German and Japanese tertiary eye hospitals sustains niche utilization despite fitting complexity.
- Soft Lenses:Conventional hydrogel materials with lower oxygen permeability serve price-sensitive institutional procurement in developing markets.
- Therapeutic Lenses:Purpose-designed devices for drug delivery integration and sustained-release applications require FDA premarket notification with enhanced sterility assurance testing.
Leading the category by volume: Silicone Hydrogel. Expanding most quickly: Therapeutic Lenses.
Application:
Reimbursement coding density determines addressable market size, with post-surgical indications commanding established CPT codes while emerging therapeutic uses navigate prior authorization requirements.
- Post-Surgical Care:Dominant revenue pool tied to ambulatory surgical center procedure volumes. United States refractive surgery chains standardize bandage lens protocols across multi-site networks, creating concentrated procurement leverage.
- Dry Eye Syndrome:Meibomian gland dysfunction diagnosis expansion drives fastest clinical uptake. Japanese and South Korean ophthalmology clinics pioneer therapeutic lens protocols for chronic ocular surface management.
- Ocular Surface Disorders:Recurrent corneal erosion and neurotrophic keratitis indications require specialist fitting expertise.
- Corneal Abrasions:Emergency department and urgent care deployment faces generic substitution pressure from lower-cost protective alternatives.
Post-Surgical Care generates the largest revenue base. Dry Eye Syndrome claims the steepest expansion trajectory.
End User:
Procurement authority is shifting toward consolidated buyer networks as private equity-backed clinic roll-ups displace independent practice purchasing patterns.
- Ophthalmology Clinics:Procedure volume concentration creates margin pools for manufacturers with direct sales forces. California and Texas clinic chains command volume pricing through centralized buying committees.
- Hospitals:Inpatient and emergency department utilization tied to trauma and chemical injury protocols.
- Retail Optical Stores:Extended-wear silicone hydrogel specifications enable therapeutic placement through optometry chains with in-house corneal specialists.
- Home Care:Emerging payor coverage decisions for therapeutic lens home use could unlock patient-direct channels currently blocked by institutional billing requirements.
Ophthalmology Clinics dominate procurement volume. Home Care presents the most significant channel expansion opportunity.
Distribution Channel:
Channel economics reflect inventory carrying costs and regulatory compliance burdens, with sterile device handling requirements favoring specialized distribution infrastructure.
- Direct Sales:Manufacturer field forces serve high-volume ophthalmology clinic chains with just-in-time delivery and technical fitting support.
- Optical Stores:Therapeutic lens placement requires optometrist credentialing and in-house corneal specialist availability.
- Retail Pharmacy:Limited penetration due to sterile storage requirements and prescription verification complexity.
- Online Pharmacy:Home care reimbursement code expansion could enable direct-to-patient fulfillment for established therapeutic indications.
Direct Sales commands the highest value per transaction. Online Pharmacy is gaining share fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese specialty chemical producers anchor silicone hydrogel polymer supply chains for bandage lens manufacturing. FDA 510(k) clearance pathways in the United States and EU MDR frameworks in Europe create divergent market access timelines across major demand centers.
United States
Refractive surgery chains in California and Texas standardize bandage lens protocols across multi-site networks. FDA ophthalmic device division scrutiny of biocompatibility testing shapes submission requirements. Dallas-Fort Worth and Los Angeles metropolitan clusters concentrate ambulatory surgical center procedure volumes.
Germany
Tertiary eye hospitals in Berlin and Munich sustain rigid gas permeable lens utilization for post-keratoplasty care. EU MDR clinical evidence demands extend CE marking timelines for therapeutic indications. The Rhine-Ruhr industrial corridor hosts specialty polymer producers supplying silicone hydrogel raw materials.
Japan
Ophthalmology clinics in Tokyo and Osaka pioneer therapeutic lens protocols for chronic dry eye management. PMDA consultation procedures guide premarket submission strategies for extended-wear devices. The Keihin industrial zone concentrates contact lens manufacturing infrastructure.
South Korea
Seoul-based ophthalmology chains drive meibomian gland dysfunction diagnosis expansion. MFDS medical device review pathways accommodate silicone hydrogel innovations with enhanced oxygen permeability. The Gyeonggi-do province clusters optical device manufacturing facilities.
India
Price-sensitive institutional procurement in Maharashtra and Karnataka sustains conventional hydrogel demand. CDSCO medical device rules govern import licensing for therapeutic lens categories. The Mumbai-Pune corridor concentrates ophthalmology clinic chains with centralized procurement authority.
Bandage Contact Lenses Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized therapeutic applications and regional distribution partnerships. The vendor base stratifies across multinational ophthalmic device manufacturers with surgical suite relationships and mid-scale specialists competing on material specifications. Three archetypes dominate: integrated surgical device-lens portfolios, retail optical channel anchors, and silicone hydrogel technology specialists. Consolidation among ophthalmology clinic chains and direct sales force expansion represent the dominant competitive moves reshaping procurement leverage.
Within the integrated portfolio tier, Alcon Inc. and Johnson & Johnson Vision Care occupy positions that leverage surgical device relationships into post-procedure lens placement. CooperVision exemplifies the material-specialist archetype, anchoring competitive differentiation on extended-wear oxygen permeability specifications. These three manufacturers collectively represent the concentration of direct sales infrastructure serving high-volume clinic chains in the United States and European markets.
| Leading Market Players |
|---|
| Alcon Inc. |
| Bausch & Lomb |
| CooperVision |
| Johnson & Johnson Vision Care |
| Advanced Vision Technologies |
| CLEARLAB SG PTE LTD |
| Excellent Hi-Care Pvt. Ltd. |
| Metro Optics |
| UltraVision CLPL |
| Others |
Value Chain & Pricing Dynamics
Silicone hydrogel polymer formulation advances are compressing unit economics while simultaneously concentrating procurement leverage among German and Japanese specialty chemical producers. This dual compression reshapes how manufacturers balance extended-wear performance claims against raw material cost exposure.
Pricing Analysis
Technical fitting support and just-in-time delivery bundling separate premium silicone hydrogel offerings from unbundled conventional hydrogel alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects oxygen permeability specifications and ISO 13485 certification status. Pricing pressure stems from conventional hydrogel substitution in Indian and Southeast Asian institutional procurement. Ambulatory surgical centers in the United States exhibit lowest price sensitivity due to reimbursement infrastructure, while Maharashtra clinic chains in India drive hardest bargain negotiations.
Supply Chain Analysis
Sterile device air freight and cold-chain handling requirements add 15-20% landed cost premiums for cross-border shipments from German and Japanese polymer plants. Silicone hydrogel production draws from fluorosilicone acrylate monomers, platinum catalyst systems, and precision molding equipment. Single-source vulnerability concentrates in the Rhine-Ruhr corridor's specialty chemical producers. Distribution runs through manufacturer direct sales forces serving high-volume ophthalmology clinic chains with field-based technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bandage contact lens market is becoming a vertical-integration race, with manufacturers pursuing backward control over silicone hydrogel polymer supply to defend margin structures against raw material volatility.
For Market Incumbents: Cement surgical suite relationships through extended-wear specification leadership and direct sales force expansion into California and Texas clinic chains. Alcon and Johnson & Johnson Vision Care should deepen captive supply arrangements with German polymer producers to offset input cost pressure. ISO 13485 certification investments create switching costs against emerging silicone hydrogel specialists. For New Entrants and Emerging Players: Telehealth-enabled prescription verification and direct-to-patient fulfillment routes unlock home care reimbursement expansion before established manufacturers adapt billing infrastructure. Target dry eye syndrome protocols in Japanese and South Korean ophthalmology clinics where meibomian gland dysfunction diagnosis growth outpaces incumbent coverage. Partner with retail optical chains possessing in-house corneal specialists to bypass direct sales force requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated ophthalmic device portfolios seeking surgical-lens placement synergies. Five-to-ten year viability hinges on FDA 510(k) clearance velocity and EU MDR adaptation timelines. Watch for home care reimbursement code finalization as inflection signal for patient-direct channel economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined therapeutic indication pathways reduce time-to-market for silicone hydrogel innovations. |
| EU MDR Clinical Evidence Buildout | Post-market surveillance systems satisfy notified body demands for extended-wear CE marking. |
| Hospital System Partnership Expansion | Multi-site ophthalmology clinic chains concentrate procurement decisions through centralized buying committees. |
| Silicone Hydrogel Polymer Backward Integration | Captive supply from German and Japanese specialty chemical producers insulates against input cost volatility. |
| Home Care Reimbursement Strategy | Payor coverage decisions for therapeutic lens home use unlock patient-direct channels beyond institutional billing. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, and ISO 13485 certification records, complemented by interviews with corneal specialists, ophthalmology clinic procurement managers, GPO contracts administrators, and silicone hydrogel polymer chemists. Secondary sources included CMS Medicare reimbursement databases, hospital procurement records, and customs trade data for silicone hydrogel raw material flows. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market size validation.
Cross-referencing historical silicone hydrogel adoption curves against expert panel input shaped the projection framework across the analysis window. Segmentation dimensions modeled included material chemistry platform, therapeutic indication, end-user facility type, and regional regulatory cluster. CAGRs derived from weighted average of procedure volume growth and pricing trajectory assumptions. Industry-specific inputs incorporated ambulatory surgical center expansion rates and meibomian gland dysfunction diagnosis prevalence curves.
Inputs from FDA ophthalmic device division guidance documents and PMDA consultation procedures were available through the study window; gaps in real-time EU MDR notified body processing timelines introduce uncertainty bands around European market access assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Memory Implants Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Antimicrobial Coated Medical Devices Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Global Cryotherapy Market
Medical Devices
North America Organ-On-Chip Market
Medical Devices
Global Hyperbaric Oxygen Therapy (HBOT) Devices Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Bionic Devices Market
Medical Devices
Laryngeal Airway Mask Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Global Artificial Limbs Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Ultrasonic Dissection Devices Market