
 Blood and Blood Components Market | 2026-2036
Blood and Blood Components Market Size, Share, and Industry Trends Forecast 2026-2036
Blood and Blood Components Market Analysis
CE marking under the EU Medical Device Regulation is reorganizing competitive access for plasma fractionators seeking European market entry. CSL Behring leverages vertically integrated plasma collection networks across multiple geographies to sustain supply security. Grifols S.A. anchors its position through specialized immunoglobulin manufacturing capabilities. Fresenius Kabi AG competes in the hospital transfusion systems segment with automated blood handling technologies.
Blood and blood components comprise cellular elements—erythrocytes, leukocytes, platelets—and acellular plasma proteins collected through apheresis or whole-blood donation, then processed under controlled temperature and anticoagulant conditions to maintain viability for therapeutic transfusion. Plasma fractionation yields albumin, clotting factors, and immunoglobulins for inherited deficiency disorders, trauma resuscitation, and autoimmune conditions. Red blood cell concentrates dominate hospital transfusion volumes due to chronic anemia and surgical demand, while platelet segments carry premium positioning given short shelf life and specialized storage requirements. Oncology therapy areas generate concentrated platelet and plasma consumption patterns tied to myelosuppressive treatment protocols.
The FDA enforces Current Good Manufacturing Practice standards for blood establishments, while the EMA's Blood Products Working Party harmonizes pathogen safety criteria across European member states. Health Canada and the TGA maintain parallel vigilance frameworks that shape export eligibility for plasma-derived products. Stakeholders must monitor evolving donor screening criteria and nucleic acid testing mandates as these standards determine which collection networks qualify for international supply contracts.
Market Dynamics
Pathogen reduction technologies are compressing the viability window for traditional cold-chain-dependent blood components while nucleic acid testing mandates expand collection network qualification thresholds.
Growth Catalysts
- EU Medical Device Regulation CE marking:The MDR framework is consolidating plasma fractionator access routes, favoring collection networks with established quality management systems.
- Aging surgical populations:Japan, Germany, and the United States sustain transfusion volumes through orthopedic and cardiovascular procedure growth in patients over 65.
- Oncology therapy expansion:Myelosuppressive treatment protocols concentrate platelet and plasma consumption at tertiary cancer centers.
Market Restraints
- Plasma collection concentration:United States-based collection networks supply over half of global source plasma, creating geopolitical and pandemic-disruption exposure.
- Albumin price volatility:Fractionation yield sensitivity to plasma protein concentration compresses margin predictability for albumin manufacturers.
- Donor deferral policy friction:FDA individual risk-based assessment revisions lag implementation timelines, constraining eligible donor pool expansion.
Strategic Opportunities
- Pathogen reduction technology adoption:INTERCEPT and Mirasol systems qualify collection networks for premium supply contracts with European hospital systems.
- Sub-Saharan Africa cold-chain infrastructure:Modular solar-powered storage units enable plasma and red cell concentrate distribution beyond capital cities.
- Recombinant factor VIII convergence:Biosynthetic clotting factor manufacturing is reducing plasma dependency for hemophilia A treatment protocols.
Industry Challenges
- Apheresis technician certification timelines:Specialized donor collection training programs create 18-24 month workforce pipeline constraints.
- Legacy blood bank information system integration:Automated component tracking platforms require capital-intensive interoperability with hospital electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood and Blood Components Market |
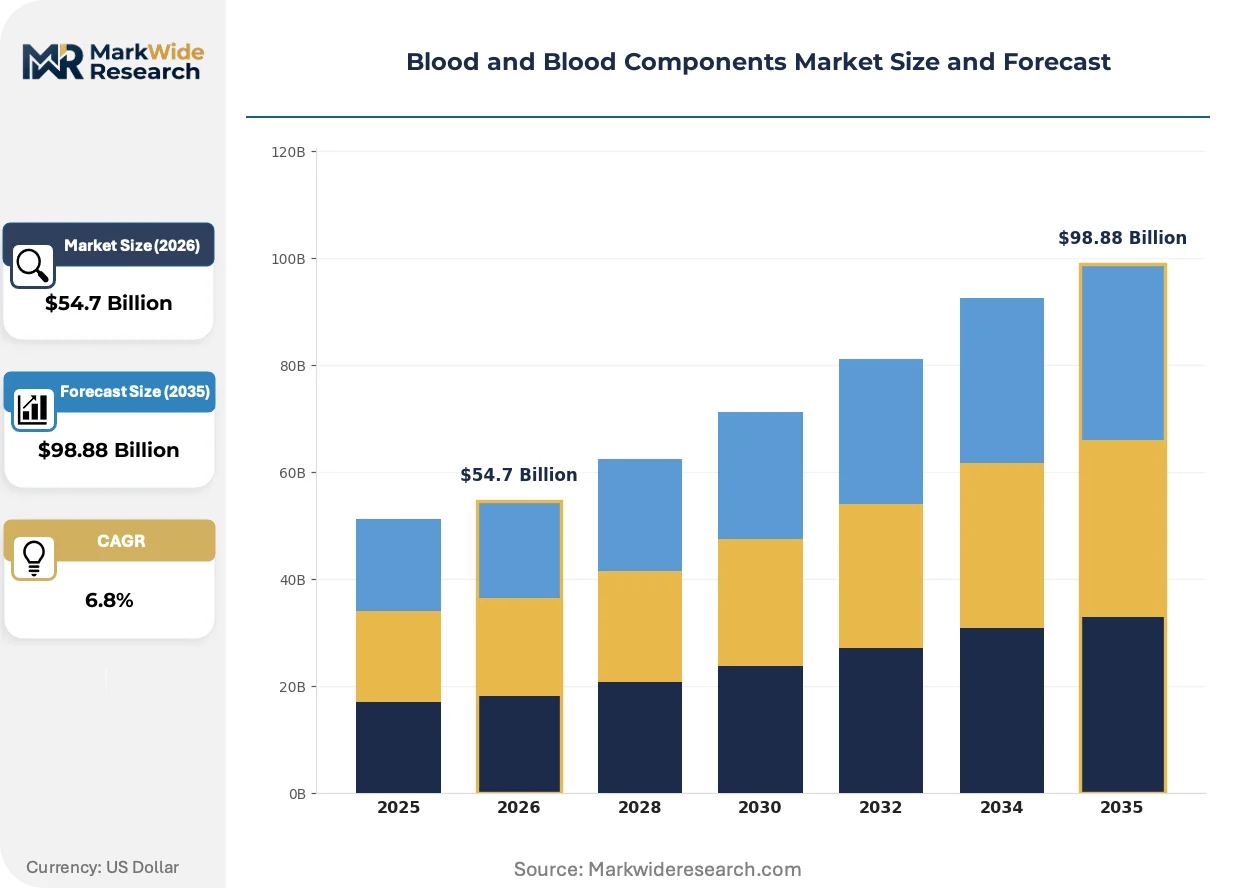
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $98.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Blood, Red Blood Cells, Platelets, Plasma Therapy Area: Oncology, Trauma Care, Cardiovascular, Hematology End User: Hospitals, Blood Banks, Clinics, Emergency Services Delivery Mode: Transfusion, Transport, Collection, Storage |
| Companies Covered | Grifols S.A., CSL Behring, Becton, Dickinson and Company, Terumo Corporation, Fresenius Kabi AG, Haemonetics Corporation, Takeda Pharmaceutical Company Limited, Octapharma AG, Kedrion S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood and Blood Components Market Emerging Trajectories
Digital traceability platforms and synthetic biology approaches are bifurcating competitive investment between incremental cold-chain optimization and fundamental plasma substitution research.
Pathogen reduction technology is decomposing the traditional trade-off between transfusion safety and component shelf life. Hospital blood banks in Germany and Japan are adopting amotosalen/UVA and riboflavin/UV systems for platelet and plasma units. This compression of viral safety risk is enabling extended dating for irradiated components and reducing emergency inventory write-offs.
EMA Blood Products Working Party guidance on nucleic acid testing harmonization is forcing collection network consolidation across European member states. Fractionators without captive plasma supply face qualification barriers under the updated Common Technical Document requirements. Central and Eastern European hospital systems are prioritizing contracts with vertically integrated suppliers holding EMA-certified collection sites.
Hospital purchasing consortia are aggregating transfusion service procurement across multi-site health systems. Group purchasing organizations in the United States now negotiate blood component contracts covering 40-60 hospital beds simultaneously, compressing price points for standard red cell concentrates. This buyer concentration is most visible in California and Texas, where Catholic health systems and academic medical center networks dominate regional transfusion volumes.
Blood and Blood Components Market Segmentation
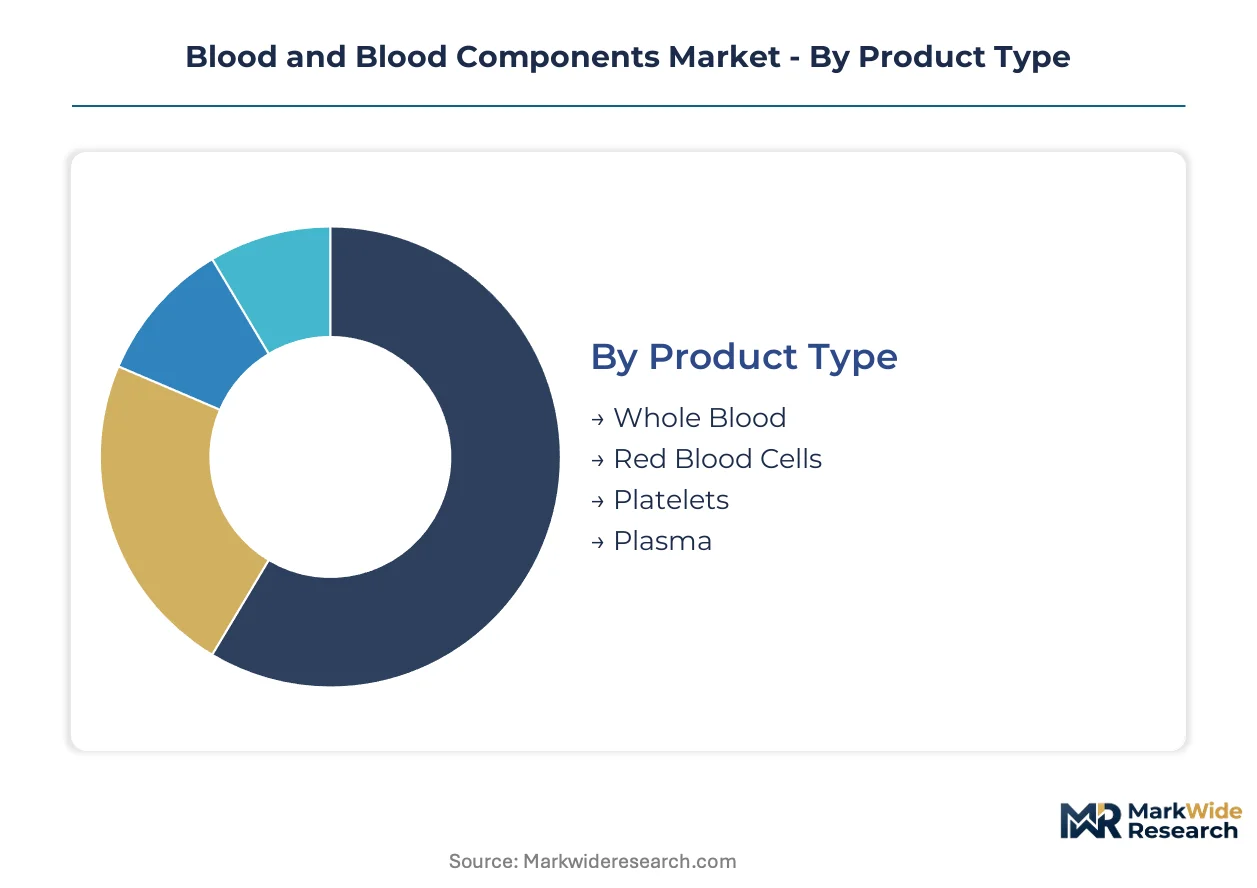
Blood and blood components segment along therapeutic function, supply chain position, and clinical application. Each dimension carries distinct regulatory pathways, margin structures, and substitution pressures from recombinant alternatives or synthetic biology approaches.
Product Type:
Recombinant factor concentrates and synthetic platelet substitutes are compressing demand for plasma-derived and cellular components at divergent rates.
- Whole Blood:Unfractionated blood containing all cellular and plasma elements, typically reserved for massive transfusion protocols in military and rural emergency settings. Trauma centers in the United States maintain limited inventories for hemorrhagic shock resuscitation, constrained by short shelf life and type-specific matching requirements.
- Red Blood Cells:Concentrated erythrocyte units depleted of plasma and buffy coat, stabilized in additive solutions for extended storage. Chronic anemia management in German tertiary hospitals and Japanese cardiovascular surgical programs sustains transfusion volumes, though patient blood management initiatives are moderating per-procedure utilization.
- Platelets:Apheresis-derived or pooled random-donor units requiring controlled agitation and temperature maintenance.
- Plasma:Source material for fractionation into albumin, immunoglobulins, and clotting factors.
Red Blood Cells retains volume leadership; Platelets holds the steepest expansion curve.
Therapy Area:
Clinical application determines component specification, processing intensity, and reimbursement tier across hospital payment systems.
- Oncology:Myelosuppressive chemotherapy regimens generate concentrated platelet and plasma consumption at tertiary cancer centers. Memorial Sloan Kettering and MD Anderson maintain dedicated apheresis collection partnerships to secure irradiated, CMV-negative platelet inventories for stem cell transplant protocols.
- Trauma Care:Massive transfusion protocols deploy balanced ratios of red cells, plasma, and platelets for hemorrhage control. Level I trauma centers in Texas and California coordinate with regional blood suppliers for thawed plasma and emergency release O-negative red cell reserves.
- Cardiovascular:Cardiopulmonary bypass and ventricular assist device implantation drive plasma and red cell utilization.
- Hematology:Inherited coagulation disorders and bone marrow failure syndromes require specialized component modifications.
Oncology commands premium pricing; Trauma Care shows the fastest volume acceleration.
End User:
Institutional scale and clinical complexity determine procurement patterns, inventory management systems, and supplier relationship structures.
- Hospitals:Acute care facilities with embedded transfusion services manage the majority of component utilization. Academic medical centers in Japan and Germany operate sophisticated blood banks with irradiation capabilities, leukoreduction, and extended antigen matching for alloimmunized patients.
- Blood Banks:Collection and processing centers serve as intermediate nodes between donors and clinical consumers.
- Clinics:Outpatient transfusion facilities for chronic anemia and hemophilia prophylaxis.
- Emergency Services:Pre-hospital transfusion programs in air medical services and ground ambulances.
Hospitals dominate procurement volume; Emergency Services is expanding most quickly.
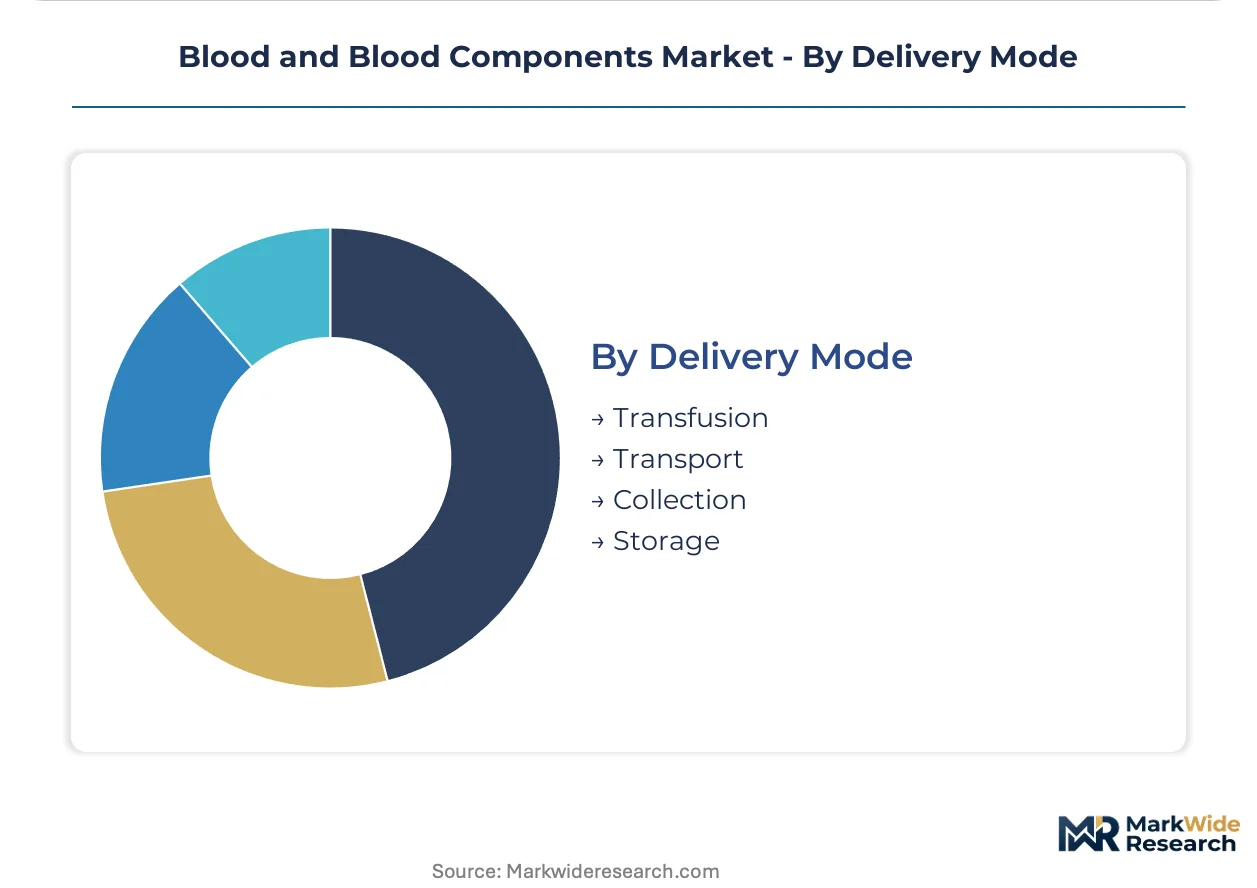
Delivery Mode:
Supply chain position determines capital intensity, regulatory jurisdiction, and margin capture across the value chain.
- Transfusion:Clinical administration of blood components at the point of care, encompassing bedside compatibility testing, infusion monitoring, and adverse event management. Hospital transfusion committees in the United States enforce utilization review protocols under Joint Commission standards.
- Transport:Temperature-controlled logistics for time-sensitive cellular components.
- Collection:Donor recruitment, phlebotomy, and initial processing operations.
- Storage:Inventory maintenance under FDA and EMA stability requirements.
Transfusion captures the value apex; Transport is gaining share fastest through specialized cold-chain providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA blood donor deferral policy revisions and EMA CE marking under the EU Medical Device Regulation are reshaping collection network qualification thresholds across major markets. National regulators in Japan, Germany, and the United States enforce divergent pathogen safety standards that determine plasma fractionator market access.
United States
Trauma care units in Texas and California sustain massive transfusion protocol volumes for hemorrhagic shock resuscitation. The FDA enforces Current Good Manufacturing Practice standards for blood establishments while revising individual risk-based donor assessment criteria. CSL Behring operates vertically integrated plasma collection networks across multiple geographies from its headquarters region.
Germany
Chronic anemia management in tertiary hospitals and cardiovascular surgical programs drive red blood cell concentrate utilization. EMA Blood Products Working Party guidance harmonizes nucleic acid testing mandates across member states. Hospital blood banks in Bavaria and North Rhine-Westphalia deploy automated blood handling technologies with irradiation capabilities.
Japan
Aging populations over 65 sustain orthopedic and cardiovascular procedure growth requiring transfusion support. The PMDA maintains parallel vigilance frameworks that shape export eligibility for plasma-derived products. Academic medical centers in Tokyo and Osaka operate sophisticated blood banks with extended antigen matching for alloimmunized patients.
China
Oncology therapy expansion at tertiary cancer centers concentrates platelet and plasma consumption for myelosuppressive treatment protocols. The NMPA regulates blood establishment licensing under national pharmaceutical standards. Hospital systems in Beijing and Shanghai are adopting pathogen reduction technologies for imported plasma components.
Australia
The TGA maintains vigilance frameworks determining qualification for international plasma supply contracts. Pathogen reduction technology adoption is enabling extended dating for irradiated components in Sydney and Melbourne hospital systems. Collection networks are consolidating under Commonwealth blood service procurement arrangements.
Blood and Blood Components Market Vendor Landscape
Player mix skews toward plasma fractionators with captive collection networks and automated transfusion technology suppliers. Market structure concentrates around vertically integrated plasma processors and hospital systems specialists. Two strategic archetypes dominate: fractionators controlling upstream plasma supply and technology vendors delivering automated blood handling platforms. Competitive moves center on collection network consolidation and pathogen reduction technology licensing.
Within the fractionator tier, Grifols S.A. and CSL Behring exemplify vertically integrated models with established quality management systems. Fresenius Kabi AG occupies a position among automated transfusion technology suppliers. These three anchors represent the dominant competitive configurations: Spanish and Australian-domiciled fractionators with global collection footprints, and German-based hospital systems specialists.
| Leading Market Players |
|---|
| Grifols S.A. |
| CSL Behring |
| Becton, Dickinson and Company |
| Terumo Corporation |
| Fresenius Kabi AG |
| Haemonetics Corporation |
| Takeda Pharmaceutical Company Limited |
| Octapharma AG |
| Kedrion S.p.A. |
| Others |
Supply Flow & Price Mechanics
Five-day platelet inventory cycles compress margin buffers for hospital blood banks while amplifying pricing power for collection networks with pathogen reduction certification. This tight synchronization between perishable supply and procurement contracts concentrates negotiating leverage among vertically integrated plasma fractionators.
Pricing Analysis
Certification level (FDA-grade, CE-marked, or standard collection) creates the primary spread between premium and economy tiers in blood component contracting. Per-unit transactional pricing dominates hospital procurement, with pathogen-reduced platelets and irradiated components commanding substantial premiums over standard units. Cost compression in red cell concentrates is intensifying because group purchasing organizations aggregate demand across multi-site health systems. Academic medical centers show the least price sensitivity due to specialized inventory requirements, while rural hospitals face acute budget constraints.
Supply Chain Analysis
The United States supplies over half of global source plasma, Germany anchors European fractionation capacity, and Japan maintains stringent self-sufficiency protocols for domestic transfusion needs. Plasma collection draws from specialized apheresis centers, donor recruitment infrastructure, and nucleic acid testing laboratories. Single-source vulnerability concentrates in US-based collection networks exposed to pandemic disruption and geopolitical friction. Distribution runs through temperature-controlled logistics providers, hospital blood banks, and emergency service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat story where FDA and EMA certification requirements create prohibitive switching costs for hospital customers. Pathogen safety mandates entrench established collection networks against new competition.
For Market Incumbents: Consolidate captive plasma supply through collection network expansion in Central and Eastern European member states. Deepen backward integration into specialized apheresis equipment manufacturing to offset technician certification bottlenecks. Recombinant factor VIII convergence threatens plasma dependency for hemophilia A protocols.
For New Entrants and Emerging Players: CE marking fast-track under the EU Medical Device Regulation offers the most penetrable entry pathway for modular pathogen reduction technology vendors. Target Sub-Saharan African cold-chain infrastructure gaps with solar-powered storage solutions. Partner with regional hospital consortia for pilot deployment contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting non-core blood fractionation assets. Long-term viability hinges on nucleic acid testing harmonization and pathogen reduction technology licensing revenue streams. Monitor FDA individual risk-based donor assessment implementation timelines as inflection indicators for collection network capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance unlocks European hospital system procurement contracts for plasma fractionators. |
| Pathogen Reduction Technology Licensing | INTERCEPT and Mirasol system adoption qualifies suppliers for premium supply agreements in Germany and Japan. |
| Hospital System Partnership | Academic medical center alliances secure dedicated apheresis collection for stem cell transplant protocols. |
| Backward Integration into Collection Networks | Captive plasma supply insulates margin predictability against albumin price volatility. |
| Reimbursement Strategy | Medicare and commercial payer alignment determines transfusion service revenue stability for hospital blood banks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blood bank directors, apheresis collection managers, hospital transfusion committee chairs, plasma fractionation executives, and regulatory affairs specialists. Secondary validation drew from FDA guidance documents, EMA Blood Products Working Party submissions, hospital procurement databases, and GPO contract disclosures. Bottom-up component volume modeling and top-down plasma fractionation revenue analysis were triangulated for convergence.
Across the analysis window, forecasts were derived from segmented modeling across product type (whole blood, red cells, platelets, plasma), therapy area (oncology, trauma, cardiovascular, hematology), and end-user institution scale. CAGRs were computed from historical transfusion volume trends, surgical procedure growth patterns, and myelosuppressive therapy expansion rates. Pathogen reduction technology adoption curves and donor deferral policy revisions served as key forecast sensitivity inputs.
Underlying assumptions cover stable nucleic acid testing mandates and gradual FDA donor screening liberalization, with deviation risk concentrated in pandemic-related collection disruptions and recombinant factor substitution acceleration. Recalibration cycles align with material shifts in regulatory guidance and pathogen safety technology validation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Incontinence Products Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Dementia Care Products Market
Healthcare Products
Hospital Privacy Screens Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Medical Products Market
Healthcare Products
Birth Tissue Products Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Australia Hair Transplant Market