
 Estonia Pharmaceutical Market | 2026-2036
Estonia Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Estonia Pharmaceutical Market Insights
Biologic drug substances derived from mammalian cell cultures are replacing small-molecule synthetics in oncology pipelines, which is realigning manufacturing investment toward cold-chain infrastructure. AstraZeneca plc leverages its biologics specialization to anchor hospital tender participation across the Baltic states. Bayer AG sustains cardiovascular portfolio dominance through established primary care channels. Teva Pharmaceutical Industries competes on generic injectable volumes, particularly in institutional procurement cycles.
Estonia Pharmaceutical encompasses chemically synthesized and biologically produced medicinal products formulated for disease prevention, diagnosis, or treatment, with active pharmaceutical ingredients typically requiring purity thresholds exceeding 99.5% and stability validation across specified temperature ranges. Prescription drugs occupy the largest value share due to chronic disease reimbursement pools, while biologics represent the fastest-expanding category as hospital formularies widen access to monoclonal antibody therapies. Oncology within the therapy area dimension commands premium pricing and concentrated specialist prescribing, whereas generic medications face margin compression from centralized procurement auctions.
The State Agency of Medicines enforces EU MDR-aligned pharmacovigilance and clinical trial standards, while the Health Insurance Fund's reimbursement lists directly determine product accessibility and manufacturer revenue predictability. Estonia's adoption of EU F-Gas Regulation constrains inhalation product propellant formulations, pushing reformulation toward dry-powder alternatives. Stakeholders must monitor whether the national digital health infrastructure's real-world evidence capabilities will reshape post-market authorization requirements and pricing negotiations.
Market Dynamics
Biologics manufacturing is electrifying Estonia's pharmaceutical infrastructure as hospital procurement pivots toward temperature-sensitive monoclonal antibody therapies, forcing wholesale reconfiguration of cold-chain logistics and reimbursement frameworks.
Growth Catalysts
- Estonia's Health Insurance Fund reimbursement expansion:The national fund is widening hospital formulary access to biologic therapies, creating predictable revenue streams for manufacturers investing in local cold-chain capabilities.
- Synthetic biology platforms:Microbial cell factories and precision fermentation are compressing active pharmaceutical ingredient production timelines and cost structures for generic manufacturers.
- Tartu biotechnology corridor concentration:University-linked research clusters are generating specialized talent pipelines and preclinical service capabilities that attract contract development investment.
Market Restraints
- EU F-Gas Regulation compliance costs:The phasedown of hydrofluorocarbon propellants is forcing metered-dose inhaler reformulation toward dry-powder alternatives, requiring capital-intensive R&D retooling.
- Single-source API dependencies:Estonia's manufacturers remain tethered to concentrated Asian supply bases for key starting materials, exposing margins to freight volatility and customs delays.
- Cold-chain infrastructure gaps:Rural pharmacy networks outside Tallinn lack validated storage for biologics requiring 2-8°C stability, limiting patient access expansion.
Strategic Opportunities
- Real-world evidence integration:Estonia's digital health infrastructure enables post-market surveillance that could reshape Health Insurance Fund pricing negotiations for innovative therapies.
- Contract manufacturing for Baltic neighbors:Underpenetrated Latvia and Lithuania markets present white-space demand for Estonia's emerging biologics fill-finish capacity.
- Green chemistry incentives:EU Green Deal alignment is creating preferential tender scoring for manufacturers adopting enzymatic synthesis and solvent reduction protocols.
Industry Challenges
- Bioprocessing skill scarcity:Mammalian cell culture expertise remains concentrated in Tallinn's university hospital network, constraining workforce scaling for commercial manufacturing.
- MDR transition timelines:EU Medical Device Regulation convergence is extending conformity assessment durations for combination products, compressing launch windows.
- Legacy ERP integration:Hospital procurement digitization demands API connectivity that smaller generic manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estonia Pharmaceutical Market |
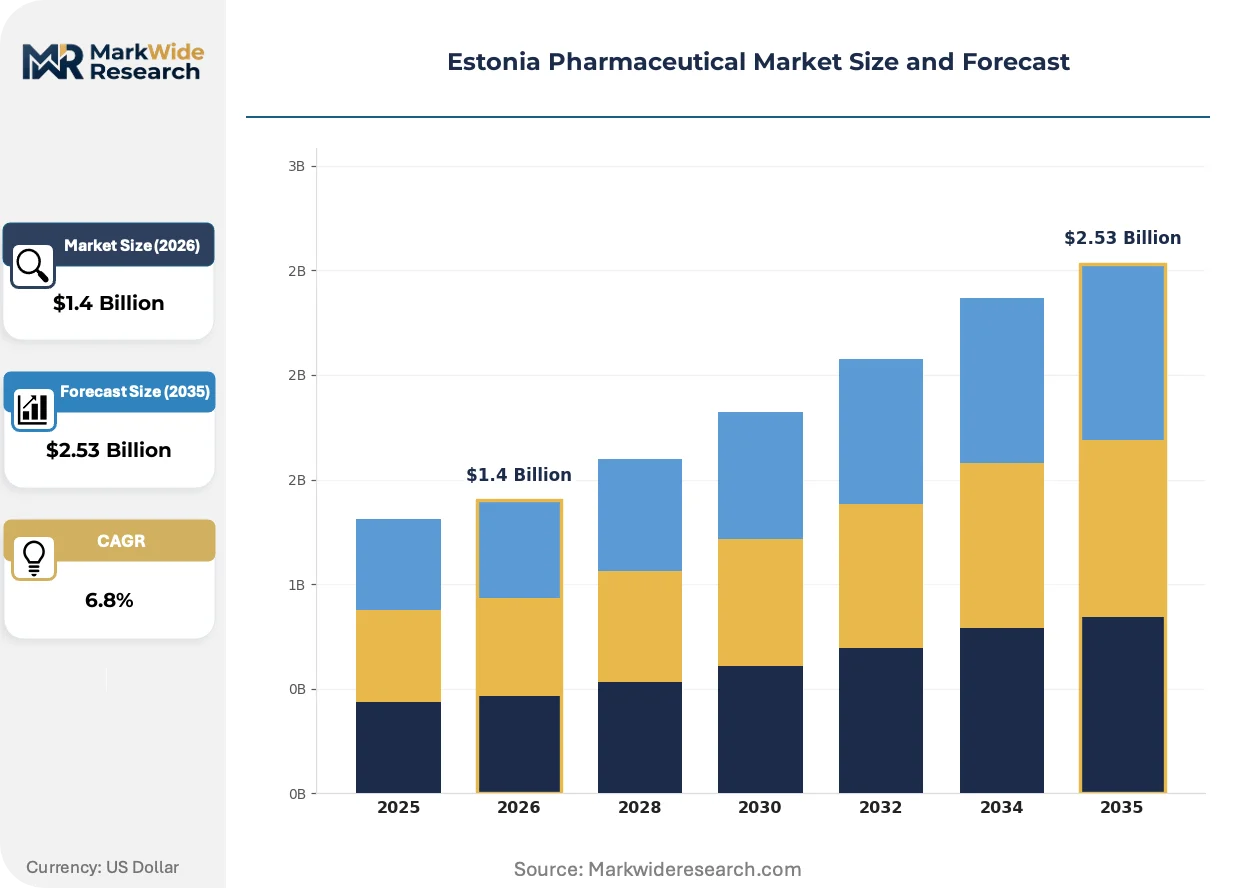
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Biologics, Generic Medications Therapy Area: Oncology, Cardiovascular, Infectious Diseases, Vaccines End User: Hospitals, Pharmacies, Clinics, Research Institutions Delivery Mode: Injectable, Oral, Topical, Inhalation |
| Companies Covered | AbbVie Inc., AstraZeneca plc, Bayer AG, C.H. Boehringer Sohn AG & Ko. KG, GlaxoSmithKline plc, Teva Pharmaceutical Industries, ROCS Trading, PPC Pharma, NorVita, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estonia Pharmaceutical Market Trends and Innovations
Continuous processing and digital twin technologies are compressing pharmaceutical development cycles while regulatory frameworks accelerate sustainability mandates across manufacturing footprints.
Single-use bioreactor systems are electrifying Estonia's contract manufacturing landscape. Tartu-based development facilities are adopting disposable stirred-tank technologies to reduce cross-contamination risk between monoclonal antibody campaigns. The shift is enabling multi-product flexibility that attracts early-stage biotech outsourcing from Nordic sponsors.
EMA's tightening pharmacovigilance requirements for biologics are extending post-authorization safety study obligations. Estonian manufacturers must now maintain dedicated signal detection teams and periodic safety update report cadences that small-molecule portfolios never demanded. Hospital pharmacies are responding by consolidating biologic dispensing to specialist centers with adverse event reporting capabilities.
Centralized procurement auctions are compressing generic medication margins while concentrating volume with manufacturers offering integrated logistics services. Estonia's Health Insurance Fund tendering platform now weights supply reliability and temperature documentation more heavily than unit price alone. Tallinn's hospital network has become the proving ground for vendor-managed inventory contracts that shift stockholding risk to manufacturers.
Estonia Pharmaceutical Market Segmentation
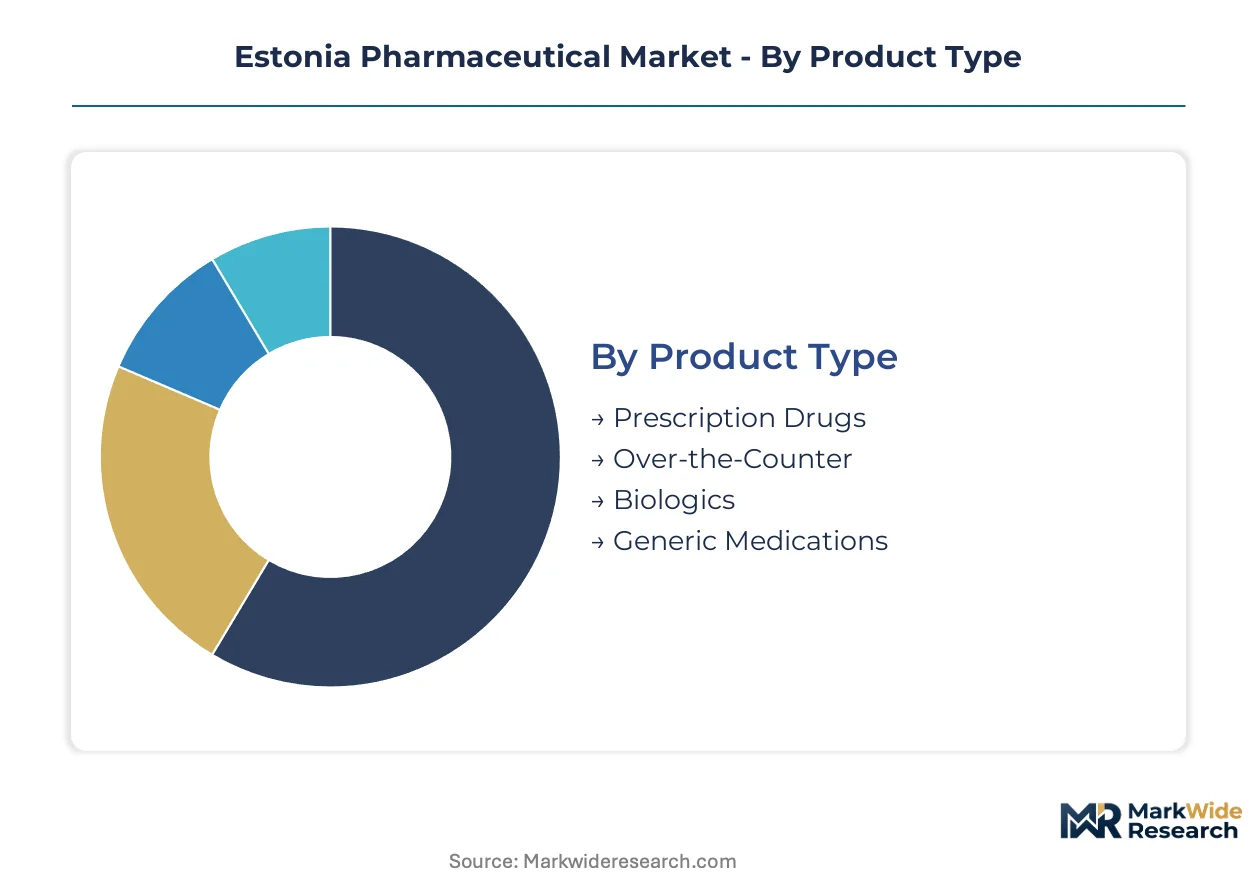
Estonia's pharmaceutical segmentation reveals how reimbursement policy and procurement concentration reshape competitive positioning across product categories. Supply-side capabilities cluster unevenly across these dimensions, creating distinct margin profiles and investment requirements for manufacturers.
Product Type:
Manufacturing infrastructure concentrates around temperature stability requirements and regulatory complexity tiers, with capital deployment favoring segments that align with Health Insurance Fund procurement priorities.
- Prescription Drugs:Chronic disease formulations requiring specialist prescribing dominate Health Insurance Fund reimbursement pools. Tallinn's university hospital network anchors demand for cardiovascular and metabolic therapies with established formulary placement.
- Biologics:Mammalian cell culture-derived monoclonal antibodies demand validated 2-8°C cold-chain infrastructure. Hospital procurement expansion is redirecting investment toward Tartu biotechnology corridor fill-finish capacity.
- Over-the-Counter:Self-medication categories face pharmacy network consolidation pressures with margin compression from centralized retail procurement.
- Generic Medications:Small-molecule synthetics compete on tender pricing with API cost volatility compressing margins for non-integrated manufacturers.
Prescription drugs absorb the bulk of installed capacity; biologics is expanding most quickly.
Therapy Area:
Clinical trial infrastructure and specialist physician concentration determine where development investment flows, with reimbursement generosity directly shaping manufacturer portfolio priorities.
- Oncology:Immuno-oncology biologics command premium pricing through concentrated specialist prescribing at Tallinn's national cancer center. Health Insurance Fund oncology budgets are expanding fastest among therapy categories.
- Cardiovascular:Established primary care channels sustain volume for antihypertensive and anticoagulant portfolios with predictable tender participation.
- Infectious Diseases:Antimicrobial stewardship programs are narrowing hospital formulary access while resistance surveillance demands narrow-spectrum development.
- Vaccines:National immunization program procurement concentrates volume with cold-chain logistics providers serving the Health Insurance Fund's centralized purchasing.
Oncology captures the steepest pricing premiums; vaccines follow the most rigid procurement calendars.
End User:
Procurement digitization maturity varies sharply across customer types, with API connectivity and vendor-managed inventory capabilities becoming decisive tender criteria.
- Hospitals:National cancer center and university hospital network procurement dominates biologic volumes with temperature documentation requirements excluding smaller suppliers.
- Pharmacies:Retail consolidation is concentrating generic dispensing with chain networks demanding integrated logistics services beyond unit price competition.
- Clinics:Outpatient specialist centers are gaining biologic dispensing consolidation as EMA pharmacovigilance requirements extend post-authorization obligations.
- Research Institutions:Tartu University-linked preclinical service capabilities attract contract development investment from Nordic biotech sponsors.
Hospitals command the deepest procurement sophistication; clinics are digitizing fastest.
Delivery Mode:
Formulation technology and device combination requirements create distinct manufacturing entry barriers with regulatory pathway complexity determining competitive density.
- Injectable:Fill-finish capacity for monoclonal antibodies requires sterile manufacturing infrastructure that Estonia's emerging biologics sector is constructing around Tartu development facilities.
- Oral:Solid dose manufacturing for chronic disease maintenance therapies faces margin compression from centralized generic procurement auctions.
- Topical:Dermatology and transdermal categories serve dispersed primary care demand with less concentration in hospital procurement.
- Inhalation:EU F-Gas Regulation phasedown is forcing metered-dose reformulation toward dry-powder alternatives with capital-intensive device development.
Injectable formats attract the newest manufacturing investment; inhalation faces the steepest regulatory retooling burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentration in Tallinn and Tartu drives Estonia's pharmaceutical demand geography, with reimbursement policy creating distinct investment corridors across the country's urban hierarchy.
Harju County
Tallinn's university hospital network anchors biologic dispensing volumes and cold-chain infrastructure investment. The Health Insurance Fund's centralized tendering platform operates from the capital, creating procurement sophistication that favors manufacturers with validated temperature documentation. Tallinn's logistics providers are constructing regional distribution hubs to serve Latvia and Lithuania markets.
Tartu County
The biotechnology corridor generates specialized workforce pipelines and contract development opportunities from Nordic sponsors. Tartu University-linked research clusters attract precision fermentation and microbial cell factory investment. Local development facilities are adopting single-use bioreactor systems to reduce cross-contamination risk between monoclonal antibody campaigns.
Ida-Viru County
Industrial chemistry heritage from oil shale processing creates latent capacity for active pharmaceutical ingredient synthesis. The region's technical workforce faces retraining requirements to transition from bulk chemicals to GMP-compliant pharmaceutical manufacturing. Eastern border proximity exposes supply chains to freight volatility from concentrated Asian API sources.
Pärnu County
Seasonal population fluctuations create demand volatility for retail pharmacy networks and over-the-counter categories. The coastal location lacks validated cold-chain infrastructure for biologics requiring 2-8°C stability, limiting patient access expansion. Summer tourism generates temporary demand spikes that strain inventory planning systems.
Lääne-Viru County
Rural pharmacy consolidation pressures generic medication dispensing margins outside major procurement centers. Distance from Tallinn's hospital networks limits specialist prescribing access for oncology and immunology therapies. Digital health infrastructure penetration enables remote consultation models that partially offset geographic disadvantage.
Estonia Pharmaceutical Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers align with Health Insurance Fund procurement digitization requirements. The vendor base clusters around three tiers: multinational biologics specialists with cold-chain capabilities, mid-scale generic manufacturers competing on tender pricing, and regional distributors integrating logistics services. Portfolio diversification toward biologics and backward integration into API sourcing represent the prevailing competitive moves.
Among multinational biologics specialists, AstraZeneca plc and AbbVie Inc. exemplify the premium-tier archetype with established hospital formulary placement. Bayer AG occupies a position within the cardiovascular-focused mid-tier, while Teva Pharmaceutical Industries represents the generic injectable volume strategy. Estonian market presence for these entities flows through Baltic regional structures rather than dedicated national subsidiaries.
| Leading Market Players |
|---|
| AbbVie Inc. |
| AstraZeneca plc |
| Bayer AG |
| C.H. Boehringer Sohn AG & Ko. KG |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries |
| ROCS Trading |
| PPC Pharma |
| NorVita |
| Others |
Pricing and Supply Chain Analysis
Health Insurance Fund tendering platform digitization is compressing generic medication margins while rewarding manufacturers with validated cold-chain documentation, forcing supply chain investment toward temperature-controlled logistics capabilities that reshape cost structures across product tiers.
Pricing Analysis
Volume concentrates in generic injectables where tender pricing erodes manufacturer returns, while biologics sustain premium positioning through specialist hospital formulary access. Price differentiation hinges on Health Insurance Fund reimbursement tier placement and cold-chain certification status. Pricing pressure intensifies in small-molecule categories as centralized procurement auctions weight supply reliability above unit cost. Retail pharmacy chains exhibit highest price sensitivity; oncology biologics at Tallinn's national cancer center show lowest.
Supply Chain Analysis
Regional distribution centers in Tallinn anchor hub-and-spoke patterns serving hospital networks across Harju and Tartu counties. Active pharmaceutical ingredient sourcing draws from India, China, and selected European synthesis facilities. Key starting materials for generic manufacturing include hydrofluorocarbon propellants, mammalian cell culture media, and sterile fill-finish components. Single-source API dependencies from concentrated Asian supply bases expose margins to freight volatility and customs processing delays. Distribution runs through temperature-validated logistics providers with Health Insurance Fund vendor-managed inventory contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Estonia's pharmaceutical landscape is consolidating around procurement digitization capabilities that marginalize smaller generic manufacturers lacking API connectivity and cold-chain infrastructure investment.
For Market Incumbents: Anticipate Health Insurance Fund tendering platform evolution toward real-world evidence integration by building signal detection teams and periodic safety update report capabilities for biologics portfolios. Defensive positioning demands backward integration into API sourcing to reduce Asian supply base exposure, alongside capacity expansion in Tartu biotechnology corridor fill-finish facilities. Cold-chain infrastructure gaps in rural pharmacy networks present acquisition targets for integrated logistics service extension. For New Entrants and Emerging Players: The mid-tier pricing gap between AstraZeneca plc biologic premiums and Teva Pharmaceutical Industries generic volumes offers white-space positioning for precision fermentation-derived biosimilars. Target contract development opportunities from Nordic biotech sponsors seeking Tartu University-linked preclinical services. Entry angle centers on single-use bioreactor adoption for multi-product flexibility with reduced cross-contamination risk between monoclonal antibody campaigns. For Investors and Strategic Acquirers: The window for entry favors mid-scale manufacturers with GMP-compliant API synthesis capabilities and established Health Insurance Fund tender participation records. Long-term viability hinges on portfolio diversification toward biologics and green chemistry alignment with EU Green Deal procurement scoring. Watch Health Insurance Fund reimbursement list expansion for monoclonal antibody therapies as inflection signal for cold-chain infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Buildout | Validates 2-8°C storage capabilities required for Health Insurance Fund biologic tender eligibility. |
| Precision Fermentation Platform Adoption | Compresses active pharmaceutical ingredient production timelines for generic manufacturers in Tartu corridor. |
| Real-World Evidence Integration | Enables post-market surveillance capabilities that reshape Health Insurance Fund pricing negotiations. |
| Backward API Integration | Reduces single-source dependencies on concentrated Asian supply bases for key starting materials. |
| Green Chemistry Certification | Secures preferential tender scoring under EU Green Deal alignment for enzymatic synthesis protocols. |
Research Methodology
EMA submission databases, Health Insurance Fund reimbursement lists, and ClinicalTrials.gov records formed the secondary backbone, supplemented by customs trade data on active pharmaceutical ingredient flows. Primary fieldwork encompassed interviews with drug development executives at Tartu biotechnology corridor facilities, regulatory affairs leads navigating EU MDR transition timelines, formulary directors at Tallinn's university hospital network, and hospital procurement managers operating the national tendering platform. Bottom-up and top-down triangulation validated volume estimates across product type and therapy area segmentation dimensions.
Bottom-up modeling anchored patient population estimates to Health Insurance Fund reimbursement pool data, while top-down cross-checks referenced Baltic regional pharmaceutical consumption patterns. Segmentation dimensions encompassed product type, therapy area, end user, and delivery mode, with dosage form and regional regulatory cluster as additional analytical lenses. CAGRs were derived from trend extrapolation of reimbursement expansion rates and manufacturing capacity buildout timelines across the projection horizon. Forecast inputs included biologics formulary access expansion trajectories and EU F-Gas Regulation compliance cost assumptions.
Inputs from EMA pharmacovigilance reporting systems and Health Insurance Fund procurement databases were available through the study window; gaps in real-world evidence integration timelines and MDR transition completion schedules introduce uncertainty bands around biologics growth assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Oral Vaccines Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Global Acyclovir Market