
 IV Fluid Monitoring Device Market | 2026-2036
IV Fluid Monitoring Device Market Size, Share, and Industry Trends Forecast 2026-2036
IV Fluid Monitoring Device Market Insights
Equipment leasing and pay-per-use financing is fragmenting the competitive landscape for IV fluid monitoring hardware. Baxter International Inc. leverages its installed base of infusion pumps to secure long-term service contracts. B. Braun Melsungen AG anchors its position through backward integration into disposable set manufacturing. Fresenius Kabi AG competes by bundling monitoring devices with its parenteral nutrition and fluid therapy portfolios.
An IV fluid monitoring device is an electromechanical or sensor-based system that measures infusion rate, volume delivered, and occlusion pressure in real time, typically operating with accuracy thresholds of plus or minus five percent to prevent medication errors. Its primary purpose is to automate the detection of flow irregularities and integrate alarm data into central nursing station displays. Smart pumps currently dominate the device type category due to their embedded drug libraries and dose error reduction software, while flow sensors represent the fastest-growing segment as manufacturers miniaturize ultrasonic and thermal detection elements for disposable set integration. Hospitals command the largest end-user share given their capital budgets and regulatory compliance obligations, though home care connectivity solutions are expanding as reimbursement frameworks evolve for remote patient monitoring.
FDA 510(k) premarket notification requirements enforce substantial equivalence standards for new infusion pump submissions, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE-marked smart pumps entering European care settings. HIPAA interoperability rules in the United States further shape product roadmaps by requiring encrypted data transmission between bedside monitors and enterprise health record architectures. Stakeholders must evaluate whether to build proprietary connectivity stacks or adopt open interoperability frameworks as health system procurement criteria harden around cybersecurity and data portability specifications.
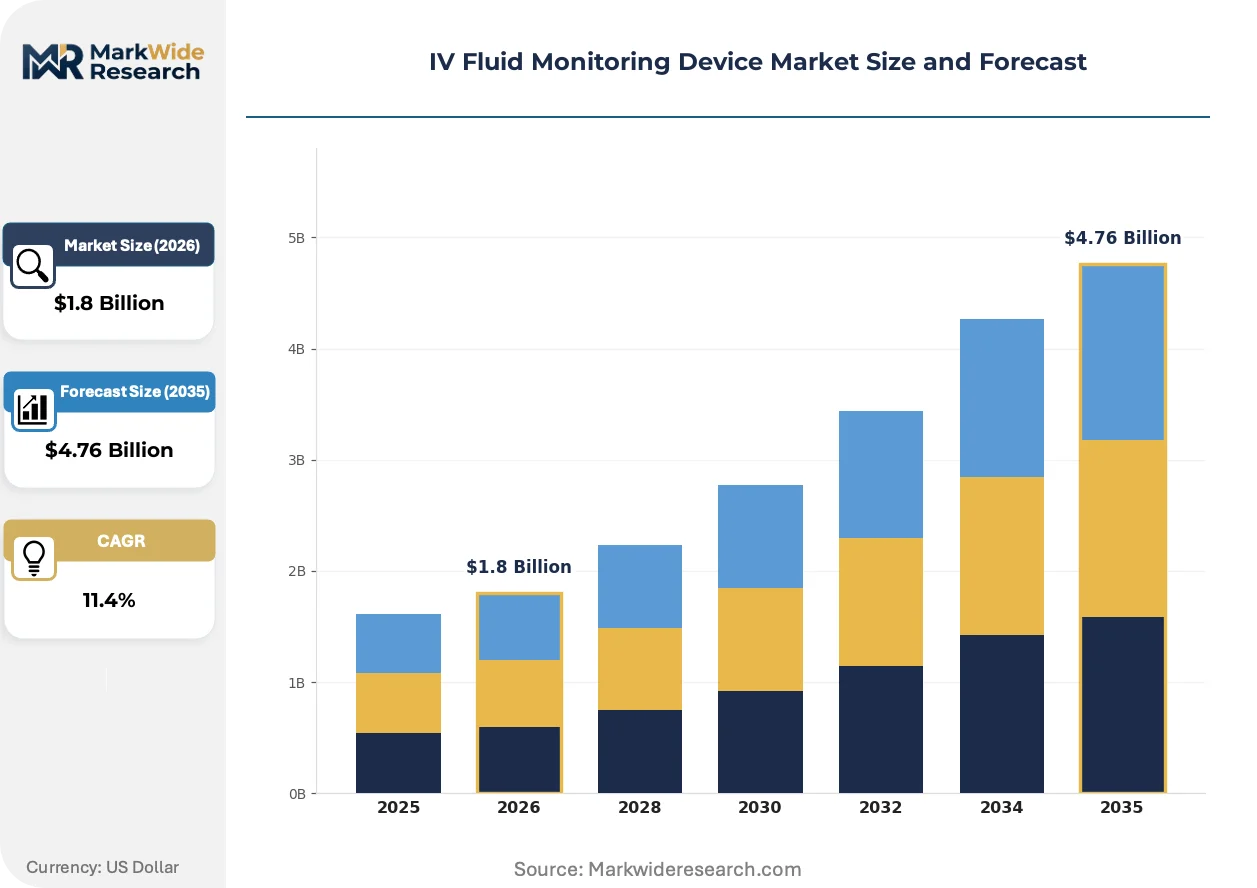
Market Dynamics
Hospital medication safety mandates are compressing replacement cycles for legacy infusion pumps as health systems prioritize dose error reduction software and wireless connectivity upgrades to meet interoperability requirements.
Growth Catalysts
- FDA 510(k) Pre-market Notification:Substantial equivalence standards for smart pump submissions are accelerating hospital infrastructure modernization programs across acute care settings.
- Home Care Connectivity:Remote patient monitoring reimbursement frameworks are expanding addressable demand beyond traditional hospital boundaries into ambulatory infusion services.
- Ultrasonic Flow Sensing:Miniaturized thermal and acoustic detection elements are enabling disposable set integration that reduces per-procedure capital intensity.
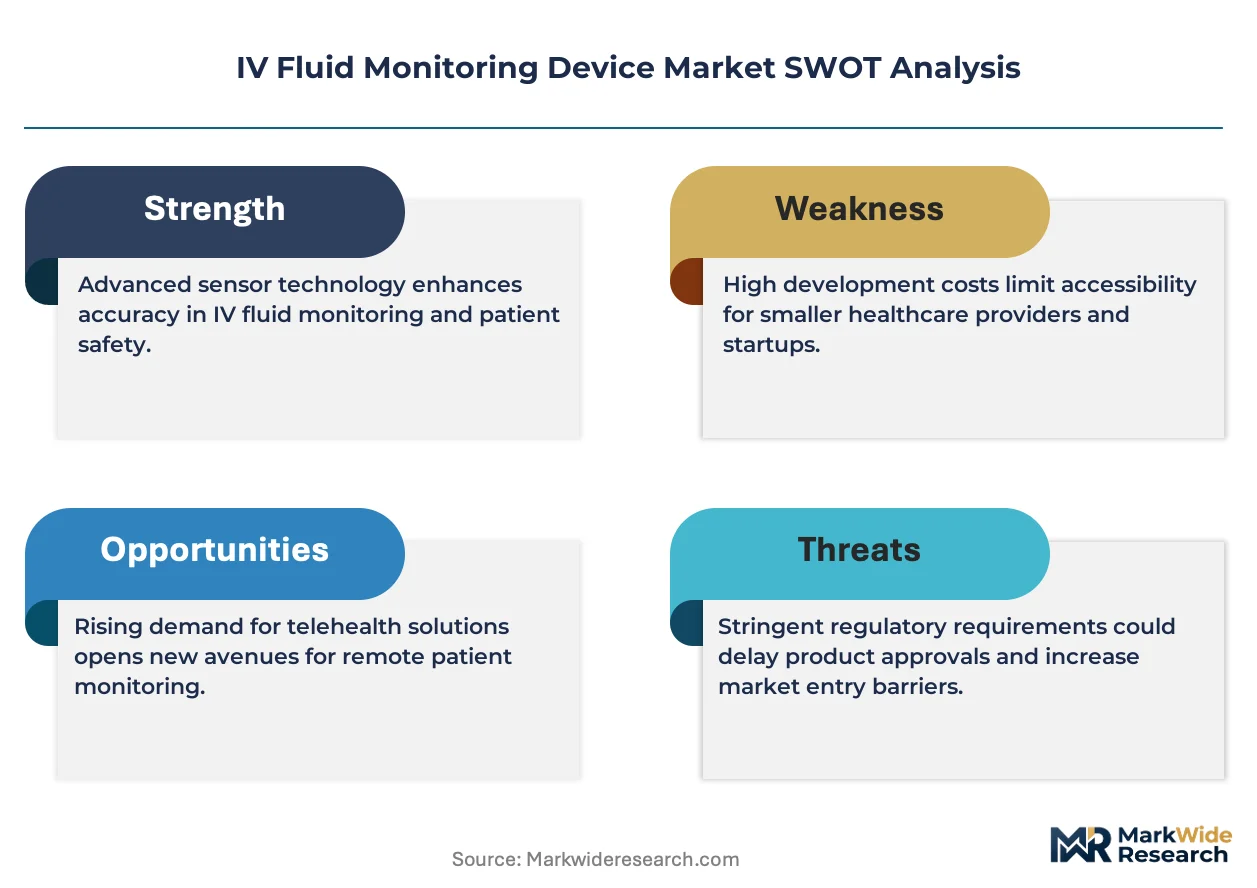
Market Restraints
- Silicon Chip Supply Concentration:Taiwan and South Korean semiconductor foundries create vulnerability in sensor component availability for disposable manufacturing.
- EU MDR Clinical Evidence Burden:Post-market surveillance mandates for CE-marked devices extend validation timelines and compress development budgets.
- Manual Gravity Infusion Substitution:Low-cost alternatives persist in resource-constrained settings where capital equipment procurement faces budgetary freezes.
Strategic Opportunities
- India's CDSCO Fast-Track Pathway:Accelerated approval mechanisms for Class B and C medical devices are opening private hospital procurement channels in tier-1 cities.
- AI-Enhanced Predictive Occlusion:Machine learning algorithms layered on pressure sensor data are creating differentiation in high-acuity ICU segments.
- Pay-per-Use Financing:Equipment-as-a-service models are converting capital expenditure barriers into recurring revenue streams for mid-size hospital networks.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Health systems face acute shortages of technicians qualified to maintain wireless-enabled smart pump fleets and troubleshoot interoperability failures.
- Legacy EHR Integration Complexity:Proprietary data formats from incumbent pump manufacturers create friction when connecting to heterogeneous hospital information architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Fluid Monitoring Device Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart Pump, Infusion Set, Flow Sensor, Monitor End User: Hospitals, Home Care, Ambulatory Surgical Centers, Clinics Connectivity: Bluetooth, Wi-Fi, Wired, Cellular Application: Oncology, Critical Care, Pain Management, Hydration |
| Companies Covered | Baxter International Inc., B. Braun Melsungen AG, Becton Dickinson and Company, Medtronic plc, ICU Medical Inc., Fresenius Kabi AG, Cardinal Health Inc., Johnson & Johnson Services Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Fluid Monitoring Device Market Trends and Innovations
Digital twin architectures are redefining how infusion data flows through clinical workflows, compressing the gap between bedside sensing and enterprise decision support. Three developments merit particular attention.
Cloud-native pump management software is virtualizing the traditional architecture of standalone bedside units into distributed sensor networks with centralized control planes. Large academic medical centers in the United States are piloting these systems to consolidate drug library updates across multi-hospital networks. This virtualization is compressing hardware refresh cycles while shifting value capture toward recurring software licenses.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate post-market performance data for smart pump interoperability claims. Device firms must now maintain systematic literature reviews and PMCF studies to sustain CE marking. European notified bodies are prioritizing submissions with pre-validated cybersecurity documentation, advantaging early movers with ISO 27001-certified development pipelines.
Consolidated procurement consortia are displacing individual hospital purchasing decisions across integrated delivery networks in the United States. Group purchasing organizations now mandate open HL7 FHIR connectivity as a threshold qualification for infusion pump contracts. This specification tightening is filtering vendor pools and accelerating consolidation among mid-tier device manufacturers unable to fund certification investments.
IV Fluid Monitoring Device Market Segmentation
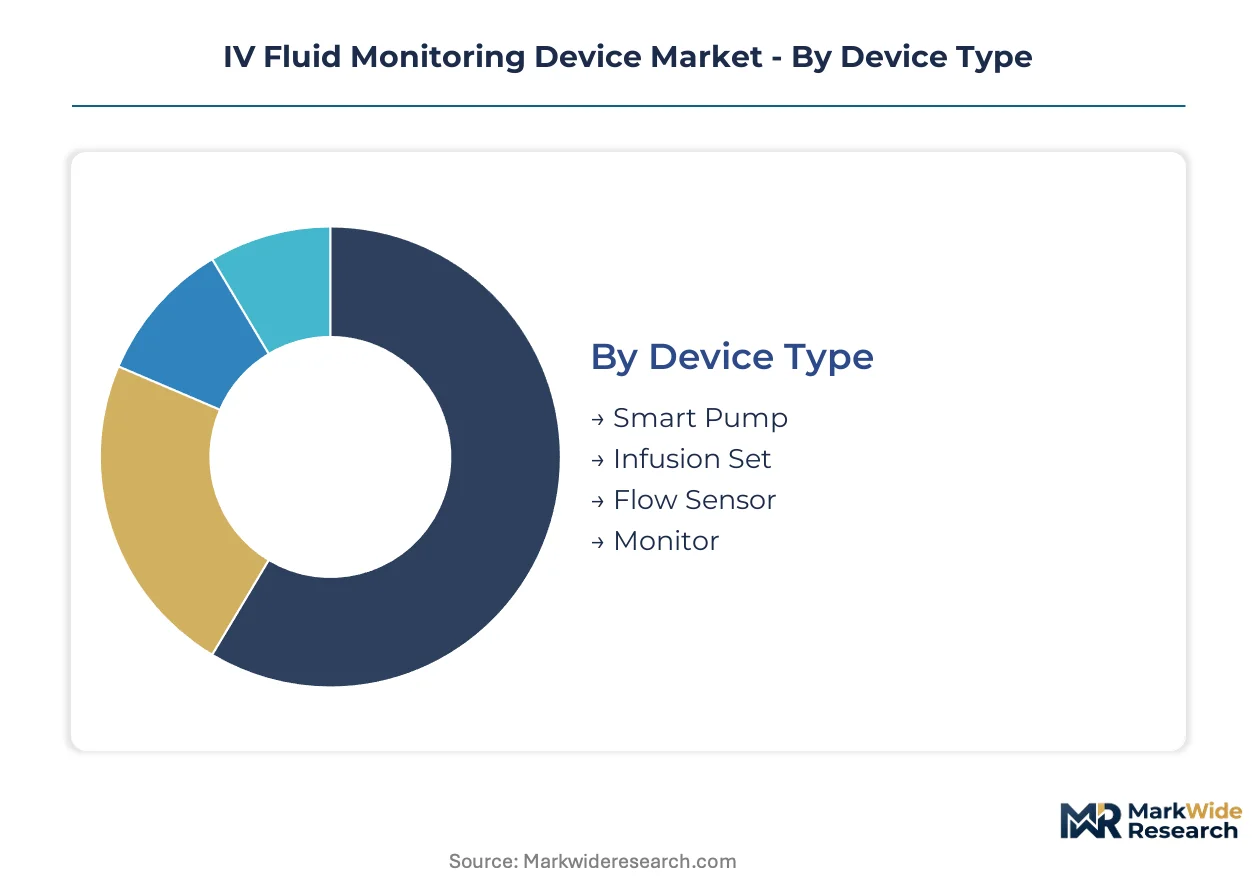
IV fluid monitoring devices fragment across four distinct category axes that shape procurement priorities and technology roadmaps differently. Device type determines capital intensity and replacement cadence. End-user concentration dictates connectivity requirements and regulatory compliance burden. Application specificity drives drug library configurations and alarm parameter customization.
Device Type:
Mature electromechanical platforms coexist with emerging sensor miniaturization, creating divergent margin profiles across hardware categories.
- Smart Pump:These programmable volumetric or syringe pumps embed dose error reduction software and wireless drug libraries with accuracy thresholds of plus or minus five percent. United States hospital networks concentrate procurement here as FDA 510(k) interoperability mandates accelerate replacement of legacy units without wireless connectivity.
- Flow Sensor:Miniaturized ultrasonic and thermal detection elements integrate into disposable infusion sets, eliminating per-procedure capital equipment requirements. Ambulatory surgical centers in Germany and France are adopting these for short-duration infusions where smart pump overhead proves economically unjustified.
- Infusion Set:Disposable tubing assemblies with integrated pressure sensing membranes connect pumps to vascular access devices.
- Monitor:Standalone display units aggregate data from multiple bedside sensors into centralized nursing station dashboards.
Smart Pump handles the majority of throughput; Flow Sensor is the fastest mover on share.
End User:
Customer type stratification reflects reimbursement framework maturity and capital budget accessibility across care settings.
- Hospitals:Acute care facilities command procurement volume through centralized biomedical engineering departments and group purchasing organization contracts. United States integrated delivery networks now mandate HL7 FHIR connectivity as a threshold qualification, filtering vendor pools to established manufacturers with certified interoperability stacks.
- Home Care:Remote patient monitoring reimbursement expansion is opening ambulatory infusion channels for oncology and parenteral nutrition therapies. Medicare reimbursement codes in the United States now cover connected infusion pumps for qualifying patients, shifting device economics toward recurring service revenue.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize disposable flow sensors over capital-intensive smart pumps.
- Clinics:Outpatient infusion suites balance equipment utilization rates against per-chair capital deployment.
Hospitals dominate absolute unit deployment; Home Care is expanding most quickly as reimbursement frameworks mature.
Connectivity:
Wireless protocol selection hinges on hospital information architecture heterogeneity and cybersecurity posture.
- Wi-Fi:Enterprise-grade wireless enables real-time data transmission to electronic health record systems and centralized alarm management platforms. Large academic medical centers in the United States pilot cloud-native pump management architectures that virtualize bedside units into distributed sensor networks with centralized control planes.
- Bluetooth:Low-energy protocols support patient-worn ambulatory pumps with smartphone companion applications for home care monitoring. EU MDR Article 10 clinical evaluation requirements now mandate post-market cybersecurity documentation for wireless-enabled devices, advantaging early movers with ISO 27001-certified development pipelines.
- Wired:Ethernet-connected pumps persist in high-acuity ICU segments where wireless interference risks are clinically unacceptable.
- Cellular:LTE and 5G modems enable rural home care connectivity where broadband infrastructure remains underdeveloped.
Wi-Fi carries the highest throughput volume; Bluetooth is climbing the fastest as home care reimbursement expands.
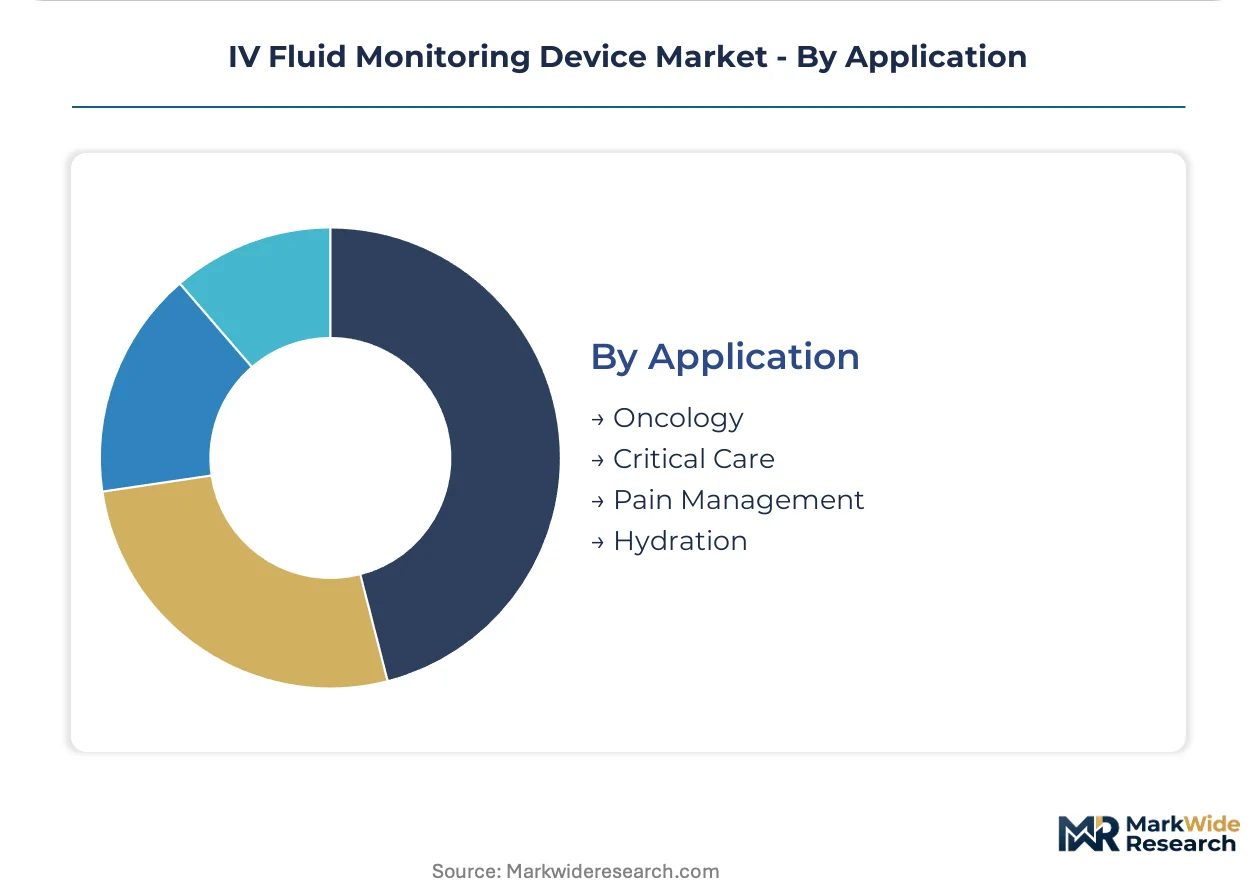
Application:
Therapeutic use case determines alarm sensitivity thresholds, drug library complexity, and regulatory scrutiny intensity.
- Critical Care:ICU infusion protocols demand high-precision volumetric control for vasoactive medications with narrow therapeutic indices. AI-enhanced predictive occlusion algorithms layered on pressure sensor data are creating vendor differentiation in this high-acuity segment.
- Oncology:Chemotherapy infusion requires specialized drug libraries with programmable dose limits and vesicant extravasation detection. India's CDSCO fast-track pathway for Class C medical devices is accelerating private hospital procurement of oncology-specific smart pumps in Mumbai and Delhi tier-1 facilities.
- Pain Management:Patient-controlled analgesia pumps incorporate demand-dose lockout intervals and respiratory depression monitoring.
- Hydration:Maintenance fluid therapy utilizes simplified gravity-fed or basic pump configurations with minimal drug library requirements.
Critical Care absorbs the highest equipment value per bed; Oncology is gaining share fastest as ambulatory infusion centers proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement expansions for connected home infusion pumps are reshaping procurement patterns across mature healthcare markets. FDA 510(k) interoperability mandates in the United States and EU MDR clinical evidence requirements in Europe are accelerating replacement cycles for legacy equipment. India's CDSCO fast-track pathway is opening private hospital procurement channels for Class C medical devices.
United States
Integrated delivery networks concentrate demand through group purchasing organization contracts that mandate HL7 FHIR connectivity as a threshold qualification. HIPAA interoperability rules require encrypted data transmission between bedside monitors and enterprise health record architectures. Large academic medical centers in Boston and the San Francisco Bay Area pilot cloud-native pump management systems that virtualize bedside units into distributed sensor networks.
Germany
Ambulatory surgical centers in Bavaria and Baden-Württemberg adopt disposable flow sensors for short-duration infusions where smart pump overhead proves economically unjustified. EU MDR Article 10 clinical evaluation requirements enforce post-market surveillance mandates for CE-marked smart pumps entering European care settings. Notified bodies prioritize submissions with pre-validated ISO 27001-certified cybersecurity documentation from manufacturers.
India
Private hospital procurement channels in Mumbai and Delhi tier-1 facilities drive oncology-specific smart pump adoption through accelerated CDSCO approval mechanisms for Class B and C medical devices. The country's national pharmaceutical regulator fast-tracks submissions with pre-validated clinical evidence packages. Medical device clusters in Gujarat and Karnataka host contract manufacturing operations for disposable infusion set components.
Japan
PMDA regulatory frameworks emphasize post-market safety surveillance for wireless-enabled infusion devices entering acute care settings. METI industrial policy supports domestic production of miniaturized sensor components for disposable set integration. Tokyo and Osaka metropolitan hospital networks concentrate procurement of high-precision volumetric pumps for critical care applications.
United Kingdom
NHS procurement frameworks prioritize dose error reduction software and wireless connectivity upgrades in centralized tender processes for acute trust medication delivery infrastructure. MHRA post-market vigilance requirements align with EU MDR transitional provisions for legacy device certifications. London and Manchester integrated care systems consolidate smart pump fleets across multi-site hospital networks.
IV Fluid Monitoring Device Market Competitive Landscape
On the supply side, the industry is consolidating around established infusion therapy conglomerates with captive disposable manufacturing capabilities and certified interoperability stacks. Three archetypes dominate: diversified medical technology conglomerates with full-stack infusion portfolios, specialized pump manufacturers with deep drug library expertise, and disposable set suppliers backward integrated into sensor miniaturization. Competitive intensity centers on M&A activity targeting connectivity software assets and strategic partnerships with group purchasing organizations to secure multi-hospital network contracts.
Within the diversified conglomerate tier, Baxter International Inc., B. Braun Melsungen AG, and Fresenius Kabi AG exemplify positioning through installed base leverage and vertical control over disposable supply chains. These entities represent archetypes of service-contract monetization, backward integration into consumables manufacturing, and therapeutic portfolio bundling respectively. Their collective presence anchors competitive dynamics in hospital procurement channels where long-term maintenance agreements and drug library update subscriptions convert capital sales into recurring revenue streams.
| Leading Market Players |
|---|
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Becton Dickinson and Company |
| Medtronic plc |
| ICU Medical Inc. |
| Fresenius Kabi AG |
| Cardinal Health Inc. |
| Johnson & Johnson Services Inc. |
| Terumo Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwanese semiconductor foundry concentration creates vulnerability in sensor component availability that simultaneously widens pricing spreads between premium FDA-validated systems and economy-tier alternatives while compressing margins for disposable set manufacturers dependent on single-source chip supply. This single-source dependency forces tiered pricing structures that separate ISO 27001-certified smart pump ecosystems from basic gravity-fed alternatives, with procurement committees absorbing risk premiums into long-term service contracts.
Pricing Analysis
Certification level creates the primary spread across the IV fluid monitoring device landscape, with FDA 510(k)-cleared and CE-marked MDR-compliant systems commanding substantial premiums over non-validated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differential cybersecurity documentation, drug library sophistication, and wireless interoperability stack maturity. Cost compression in the economy tier is intensifying because manual gravity infusion substitutes persist in budget-constrained procurement channels. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure capital intensity concerns, while integrated delivery networks prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Contract manufacturing for disposable infusion sets concentrates in Gujarat and Karnataka medical device clusters, with sensor miniaturization feeding from Taiwan and South Korean semiconductor foundries. Raw material dependencies center on medical-grade polymers, piezoelectric ceramics for ultrasonic elements, and precision-molded pressure membranes. Single-source vulnerability in Taiwan-based chip supply creates exposure to geopolitical disruption and allocation constraints during demand surges. Distribution runs through group purchasing organization contracts that consolidate hospital network procurement into multi-year agreements with embedded service obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IV fluid monitoring device market sits at an early-cycle expansion phase where home care reimbursement tailwinds and AI-enhanced predictive occlusion capabilities are opening white-space beyond traditional hospital boundaries.
For Market Incumbents: Build installed base moats through captive disposable set manufacturing and backward integration into sensor component supply. Secure multi-hospital network contracts via GPO partnerships that mandate HL7 FHIR connectivity as threshold qualification. Defend against flow sensor miniaturization threats by embedding drug library subscriptions into hardware lease structures that convert capital sales to recurring revenue. For New Entrants and Emerging Players: Establish a beachhead in India's tier-1 private hospital channels where CDSCO fast-track pathways for Class C devices accelerate approval timelines compared to mature markets. Target oncology-specific smart pump segments with localized drug libraries for chemotherapy protocols. Pursue pay-per-use financing models that eliminate capital expenditure barriers for mid-size hospital networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that targets connectivity software assets and ISO 27001-certified development pipelines. Long-term viability over the next decade hinges on cloud-native pump management virtualization and AI-enhanced predictive maintenance capabilities. Monitor FDA 510(k) interoperability mandate enforcement intensity as the signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Interoperability Submission | Premarket notification for wireless drug library integration accelerates hospital infrastructure modernization programs. |
| CE Marking Pathway under EU MDR | Article 10 clinical evidence requirements filter vendor pools to manufacturers with systematic PMCF study capabilities. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement across multi-site networks with embedded service obligations. |
| Software Companion Development | Cloud-native pump management virtualizes bedside units into distributed sensor networks with centralized control planes. |
| Reimbursement Strategy | Medicare coverage expansion for connected home infusion pumps shifts device economics toward recurring service revenue. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and infusion therapy clinicians and refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR Article 10 clinical evaluation submissions, hospital procurement contract repositories, and CMS Medicare reimbursement code filings. Bottom-up segment sizing triangulated against top-down macro healthcare infrastructure spending patterns.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation dimensions spanning device type, end-user concentration, wireless protocol selection, and therapeutic application specificity. CAGRs were derived from replacement cycle modeling, reimbursement framework evolution, and technology adoption S-curve analysis. Industry-specific forecast inputs included drug library update subscription attach rates and disposable set per-procedure utilization coefficients.
Stress conditions across semiconductor supply allocation, EU MDR transition timeline extensions, and home care reimbursement code expansion velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of FDA 510(k) clearance backlogs, CDSCO fast-track approval volumes, and GPO contract specification tightening is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Brazil Minimally Invasive Surgery Devices Market
Medical Devices
Digital Impression System Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Anti-Decubitus Dynamic Mattress Market
Medical Devices
Global Surgical Navigation System Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Asia-Pacific Medical Device Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Breast Pump Flange Market