
 Smart Mask Market | 2026-2036
Smart Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Mask Market Analysis
Healthcare professionals are rotating toward AI-driven monitoring masks while general consumers retreat from pandemic-era stockpiling. L'Oréal Groupe leverages its beauty-tech R&D infrastructure to sustain premium positioning in consumer-facing LED therapy masks. Qure specializes in app-connected acne treatment devices that anchor its direct-to-consumer channel control. Therabody competes through recovery-focused wellness positioning that extends its brand equity from percussion into facial technology.
A smart mask integrates microelectronics, biosensors, and filtration media into wearable respiratory or dermatological devices, typically incorporating Bluetooth connectivity for real-time data transmission to companion applications. These devices serve medical monitoring, occupational safety, or cosmetic treatment purposes through programmable light arrays, particle sensors, or voice amplification modules. Advanced filtration masks and UV sterilizing variants occupy the highest margin pools where healthcare procurement justifies premium pricing for validated pathogen protection. Sensor technology leads functional differentiation while AI-driven monitoring represents the fastest-expanding capability layer as algorithms improve respiratory pattern recognition.
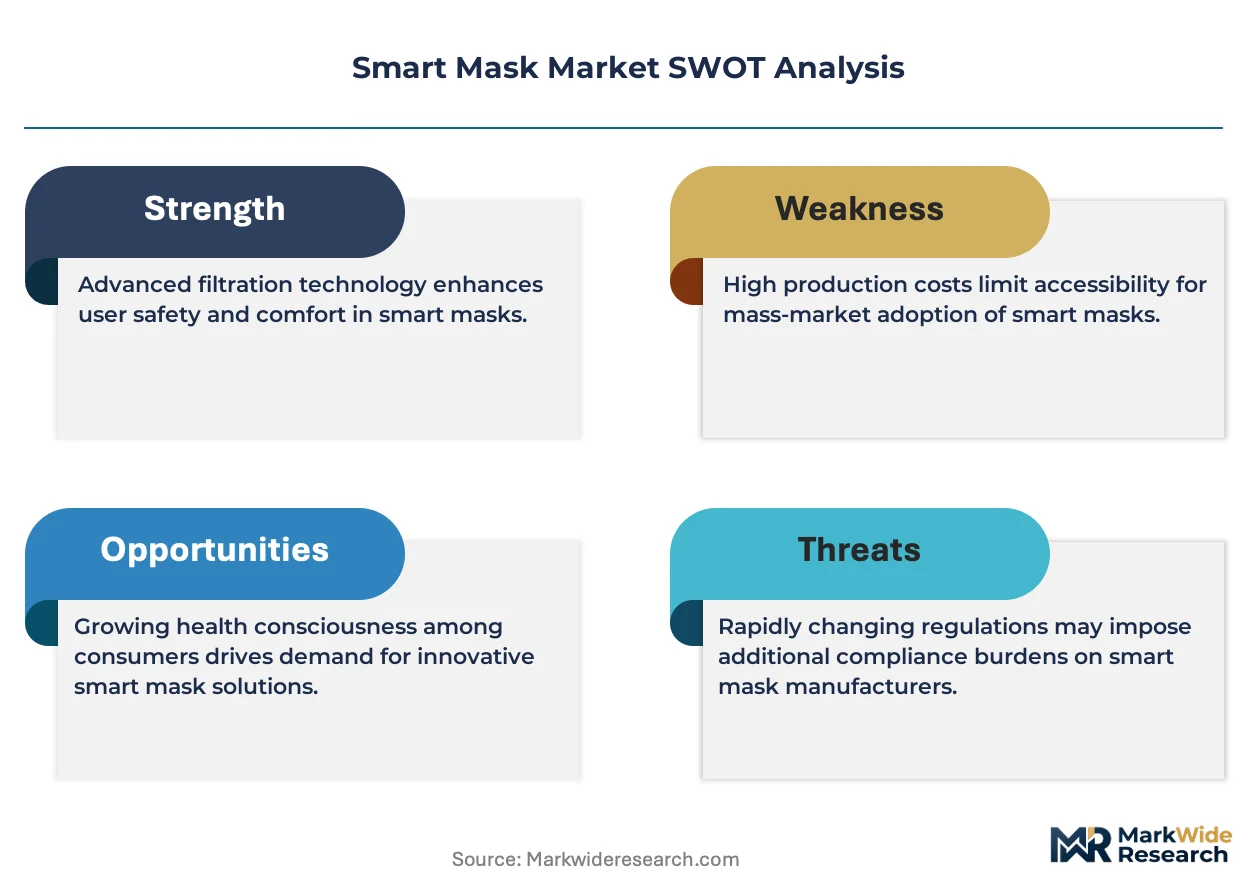
FDA clearance requirements for wearable medical devices shape product development timelines and clinical validation investments in the United States. EPA filtration standards and OSHA respiratory protection regulations further constrain industrial segment entry for manufacturers lacking certified testing infrastructure. Stakeholders must monitor evolving FDA software-as-medical-device guidance to determine whether algorithm updates trigger new premarket submissions.
Market Dynamics
Hospital procurement networks are consolidating vendor relationships around FDA-cleared connected respiratory devices, compressing purchasing timelines while elevating clinical validation requirements for wearable mask manufacturers.
Growth Catalysts
- OSHA Respiratory Protection Standards:Industrial employers in the United States face mandates to upgrade from disposable N95s to reusable elastomeric respirators with fit-testing documentation. Smart masks with real-time seal monitoring satisfy compliance while reducing fit-test labor costs.
- Biosensor miniaturization:CMOS-based gas sensors and photoplethysmography modules now integrate into mask form factors without compromising breathability. Medical-grade pulse oximetry and CO2 monitoring drive adoption in post-acute care settings.
- South Korea:MFDS fast-track approval pathways for AI-enabled medical devices accelerate commercialization timelines for algorithm-driven respiratory pattern recognition masks targeting sleep apnea management.
Market Restraints
- Lithium-polymer battery supply concentration:Cell production concentrates in Chinese manufacturing hubs, exposing mask makers to raw material cost volatility and export control risks for wearable power systems.
- FDA 510(k) clearance timelines:Software-as-medical-device guidance creates uncertainty whether AI algorithm updates trigger new premarket submissions, freezing development roadmaps for adaptive monitoring features.
- Reusable elastomeric respirators:Industrial buyers increasingly favor cartridge-based systems with decade-long service life over disposable smart masks, compressing replacement revenue streams in occupational safety segments.
Strategic Opportunities
- Germany:The EU Medical Device Regulation (MDR) creates first-mover advantages for manufacturers achieving notified body certification before 2027 compliance deadlines, locking out late entrants from hospital procurement networks.
- Voice amplification modules:Convergence of bone conduction audio and noise-canceling microphones enables clear communication in high-decibel industrial environments, opening construction and mining applications beyond healthcare.
- Direct-to-patient subscription models:Dermatology-focused LED therapy masks bypass retail markup through app-connected recurring revenue, capturing lifetime value from acne and anti-aging treatment protocols.
Industry Challenges
- Clinical validation capacity:Wearable medical device trials require specialized respiratory physiology expertise and IRB coordination, creating bottlenecks for startups without established clinical affairs teams.
- Interoperability with EHR systems:HL7 FHIR integration demands divert engineering resources from core sensor development, delaying product launches for hospital-connected monitoring masks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Mask Market |
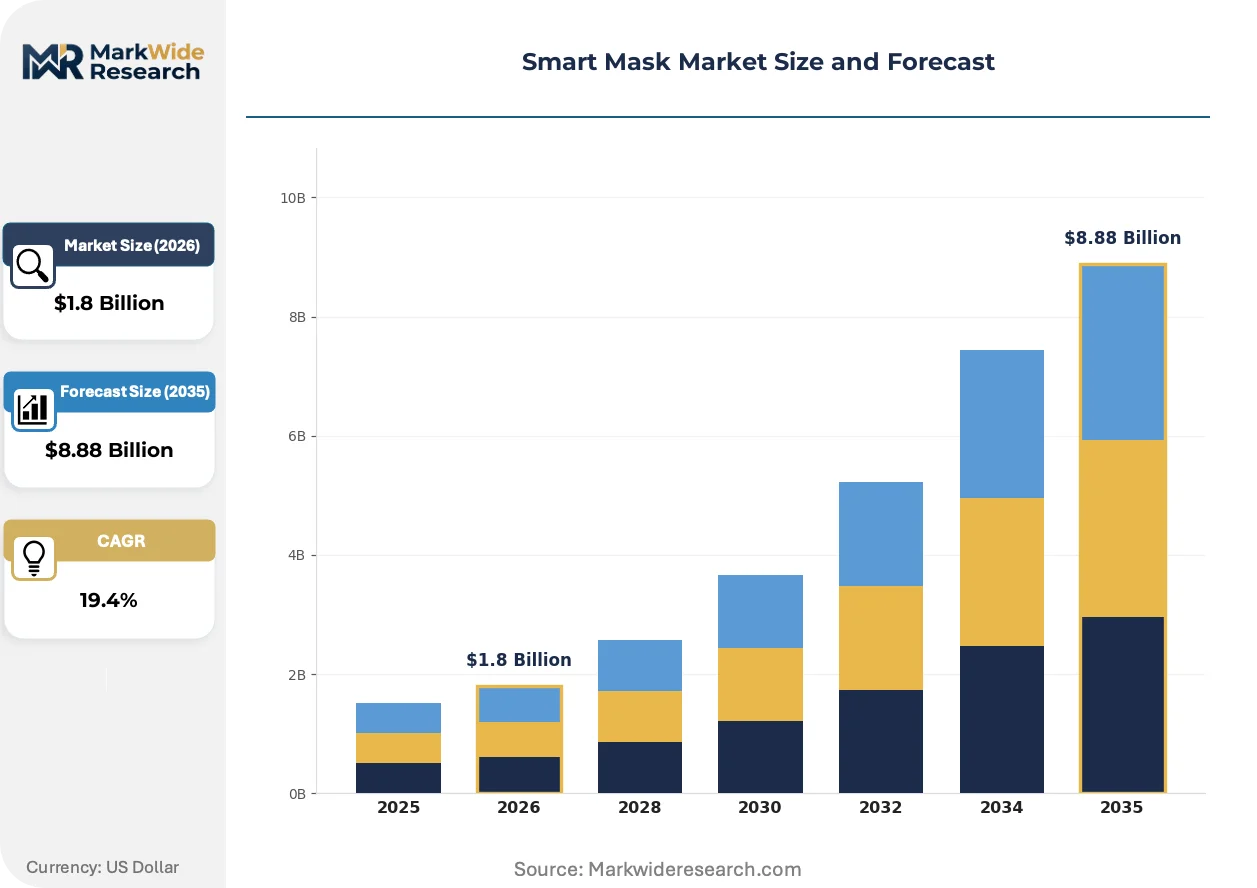
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Smart Masks, Advanced Filtration Masks, Voice-Enabled Masks, UV Sterilizing Masks End User: Healthcare Professionals, General Consumers, Industrial Workers, First Responders Technology: Bluetooth Connectivity, IoT Integration, Sensor Technology, AI-Driven Monitoring Sales Channel: Online Retail, Pharmacy Chains, Direct Sales, Distributors |
| Companies Covered | Therabody, Renpho, L'Oréal Groupe, MZ Skin, Qure, I-Smart Developments, Silk'n, Taiki, SharkNinja, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Mask Market Emerging Trajectories
Algorithmic respiratory analysis is displacing simple threshold alerts, while material science breakthroughs enable sustained wear comfort previously incompatible with embedded electronics.
Photobiomodulation arrays using dual-wavelength LEDs are bifurcating the cosmetic mask segment into medical-grade dermatological devices and consumer wellness accessories. Dermatology clinics in the United States prescribe 633nm red and 415nm blue light protocols for inflammatory acne, while wellness retailers market identical hardware without clinical dosing controls. This divergence is compressing margin pools at the mid-market tier as premium positioning requires FDA 510(k) clearance investment.
The EU AI Act risk classification framework is reshaping development priorities for algorithm-enabled masks. High-risk categorization for respiratory monitoring systems mandates conformity assessment by notified bodies, extending commercialization timelines by 12-18 months. German and French manufacturers are responding by segregating AI features into optional software modules, preserving hardware sales while navigating regulatory uncertainty.
Hospital procurement departments are consolidating vendor contracts around integrated device-and-data platforms, displacing standalone mask sales. GPOs in the United States now require Bluetooth connectivity with cloud dashboard compatibility, bundling respiratory protection with compliance analytics. This behavior is most visible in California and Texas health systems, where value-based care contracts incentivize preventable readmission reduction through continuous remote monitoring.
Smart Mask Market Segmentation
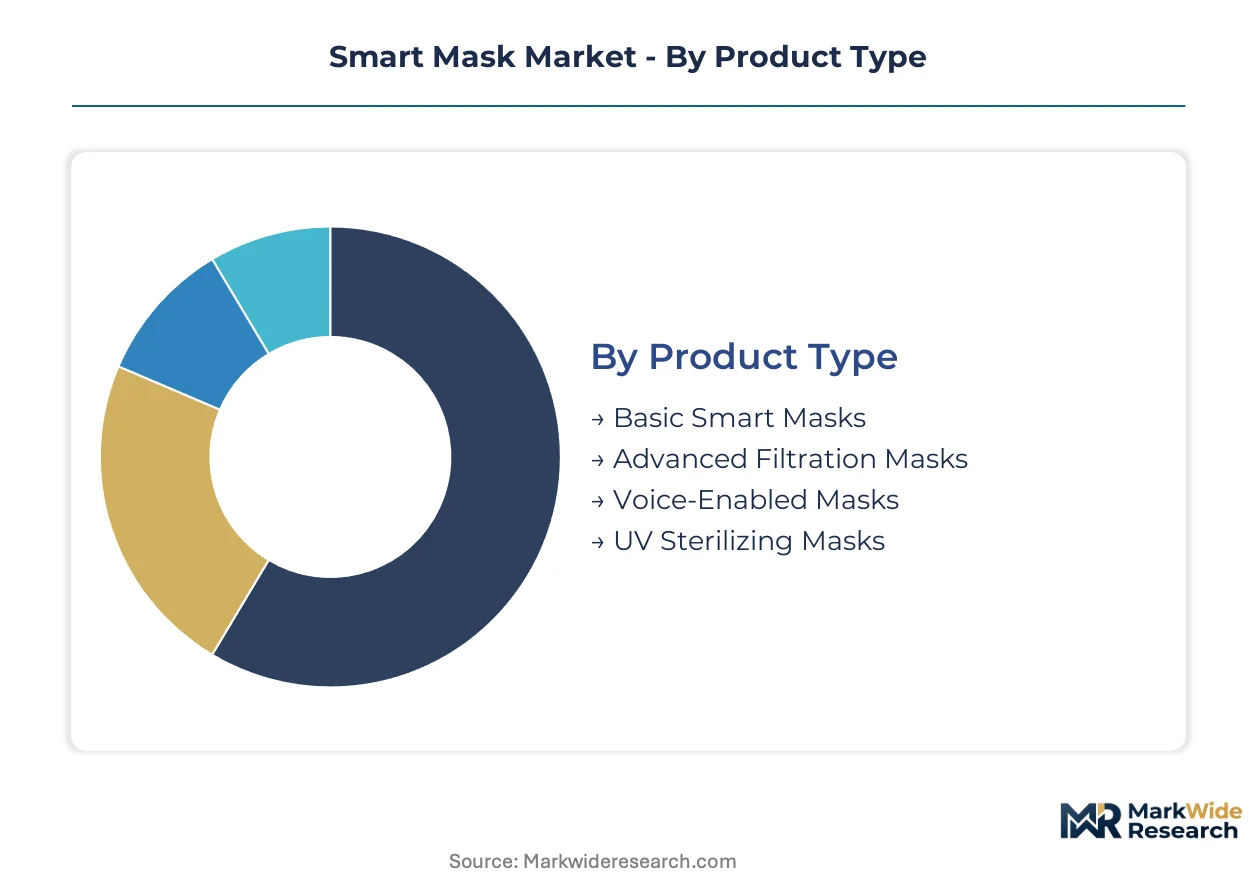
Product differentiation in smart masks hinges on regulatory clearance tier and sensor sophistication, with reimbursement pathways and procurement specifications fragmenting addressable markets across medical, industrial, and consumer domains.
Product Type:
Disposable N95 alternatives and basic PPE commoditization exert substitution pressure on entry-level smart masks, while validated filtration systems command defensive positioning.
- Basic Smart Masks:Entry-tier devices incorporate Bluetooth pairing for filter-life tracking without clinical-grade sensors. Pharmacy chains in the United States stock these for consumer wellness positioning, though margin compression from unconnected respirators limits shelf space allocation.
- Advanced Filtration Masks:Elastomeric platforms with NIOSH-certified cartridges and real-time seal monitoring satisfy OSHA respiratory protection mandates for industrial employers. Hospital procurement networks prioritize these for high-risk aerosol-generating procedures, bundling fit-test documentation with connected compliance dashboards.
- Voice-Enabled Masks:Bone conduction audio modules enable clear communication in high-decibel environments. Construction and mining supervisors specify these for crew coordination, extending adoption beyond healthcare into occupational safety segments.
- UV Sterilizing Masks:Integrated ultraviolet-C LEDs provide on-mask pathogen inactivation between uses. Premium positioning targets first responder units and field medical teams with limited sterilization infrastructure.
Advanced filtration masks retain volume leadership; UV sterilizing variants hold the steepest expansion curve.
End User:
Procurement centralization in healthcare systems concentrates purchasing power, while fragmented industrial buyer bases sustain distributor intermediation.
- Healthcare Professionals:FDA-cleared connected respiratory devices anchor hospital GPO contracts in California and Texas health systems. Value-based care incentives for preventable readmission reduction drive continuous remote monitoring adoption in post-acute care settings.
- General Consumers:LED therapy masks for dermatological treatment dominate direct-to-consumer channels, with app-connected acne protocols capturing recurring subscription revenue. L'Oréal Groupe and Qure compete through beauty-tech R&D infrastructure versus specialized device positioning.
- Industrial Workers:OSHA mandates for fit-test documentation propel demand for seal-monitoring elastomeric respirators. Manufacturing and chemical processing facilities in the United States consolidate vendor relationships around reusable cartridge systems with decade-long service life.
- First Responders:Fire departments and emergency medical services prioritize voice amplification and integrated communication modules. Federal procurement programs in the United States specify interoperability with existing radio systems.
Healthcare professionals command pricing power; general consumers exhibit the most volatile demand patterns.
Technology:
Algorithm-enabled capabilities face regulatory uncertainty under FDA software-as-medical-device guidance, freezing development roadmaps for adaptive features.
- Bluetooth Connectivity:Standard wireless protocol for companion app pairing and cloud dashboard integration. Hospital procurement departments now require this as table stakes for vendor contract consolidation.
- IoT Integration:Enterprise fleet management platforms enable centralized compliance tracking across distributed workforces. Industrial employers in the United States deploy these for OSHA audit documentation and predictive filter replacement scheduling.
- Sensor Technology:CMOS-based gas sensors and photoplethysmography modules integrate pulse oximetry and CO2 monitoring into mask form factors. Post-acute care settings in South Korea adopt these for sleep apnea management under MFDS fast-track pathways.
- AI-Driven Monitoring:Respiratory pattern recognition algorithms displace simple threshold alerts, though EU AI Act high-risk classification extends commercialization timelines by 12-18 months for notified body conformity assessment.
Sensor technology anchors current revenue; AI-driven monitoring faces the longest regulatory runway.
Sales Channel:
Channel control determines margin capture, with direct relationships insulating manufacturers from retail markup compression.
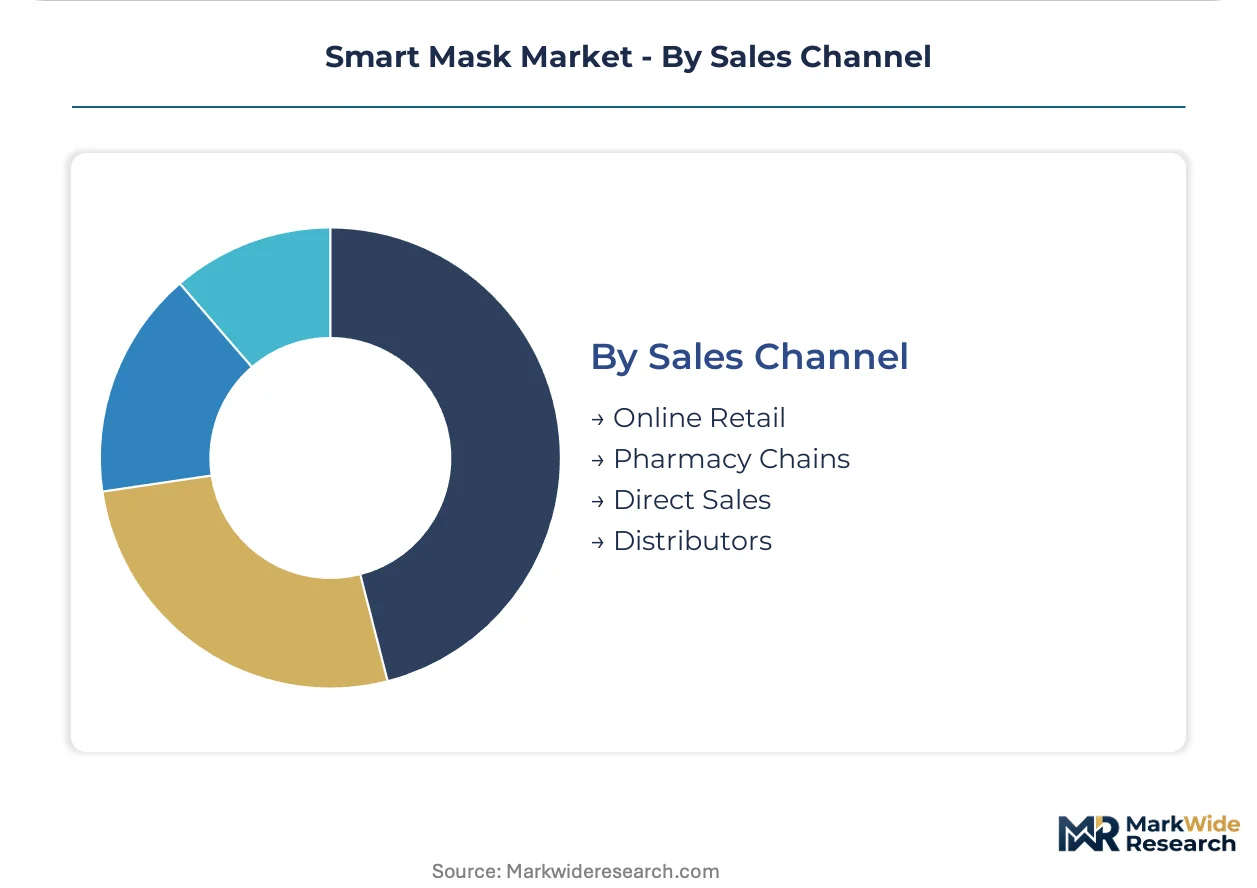
- Online Retail:E-commerce platforms dominate consumer-facing LED therapy mask distribution, with subscription models bypassing traditional retail intermediation. Dermatology-focused brands leverage app connectivity for lifetime value capture.
- Pharmacy Chains:CVS and Walgreens stock basic smart masks for wellness positioning, though clinical-grade devices require specialized medical device distribution partnerships.
- Direct Sales:Hospital procurement networks and industrial safety managers negotiate enterprise contracts directly with manufacturers. GPO consolidation in the United States compresses purchasing timelines while elevating clinical validation requirements.
- Distributors:Regional industrial supply houses maintain relationships with small and mid-sized manufacturing facilities. These intermediaries provide fit-testing services and technical support that mask manufacturers lack scale to deliver directly.
Direct sales capture the highest margins per unit; online retail scales most quickly in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific electronics flows that feed smart mask component supply chains. German rail corridors distribute medical device certifications across the EU single market. South Korean port infrastructure accelerates MFDS-cleared wearable exports to Asian healthcare networks.
United States
Hospital procurement networks in California and Texas consolidate vendor contracts around FDA-cleared connected respiratory devices. OSHA mandates for fit-test documentation propel industrial demand for seal-monitoring elastomeric respirators. The Boston medical device cluster concentrates clinical validation expertise for wearable mask trials.
Germany
The EU Medical Device Regulation creates first-mover advantages for manufacturers achieving notified body certification before 2027 deadlines. Industrial employers in the Ruhr region upgrade to reusable cartridge systems with decade-long service life. The Baden-Württemberg precision engineering corridor supplies sensor miniaturization components.
South Korea
MFDS fast-track approval pathways accelerate commercialization timelines for AI-enabled respiratory monitoring masks. Seoul Capital Area dermatology clinics prescribe LED therapy protocols for inflammatory acne treatment. The Busan-Ulsan manufacturing belt produces CMOS-based gas sensors for mask integration.
China
Lithium-polymer battery production concentrates in Shenzhen and Dongguan manufacturing hubs. NMPA regulatory frameworks shape clinical validation requirements for wearable medical devices targeting domestic hospitals. The Yangtze River Delta electronics corridor supplies Bluetooth modules and photoplethysmography sensors.
Japan
METI industrial standards guide interoperability specifications for IoT-enabled respiratory protection devices. Osaka-based precision manufacturers develop voice amplification modules for high-decibel industrial environments. The Tokyo healthcare procurement system prioritizes continuous remote monitoring for post-acute care settings.
Smart Mask Market Vendor Landscape
Listed leaders compete with private specialists across regulatory clearance tiers, creating a bifurcated structure where FDA-cleared medical devices command premium positioning against consumer wellness accessories. Beauty conglomerates leverage R&D infrastructure for dermatological mask segments while dedicated device manufacturers anchor occupational safety applications. Strategic archetypes include beauty-tech hybrids, medical-grade specialists, and diversified wellness brands. Competitive moves concentrate on clinical validation investments and direct-to-consumer channel control.
Within the beauty-tech tier, L'Oréal Groupe and Qure exemplify divergent approaches to consumer-facing LED therapy positioning. Therabody occupies a position extending wellness brand equity from recovery into facial technology. Among these archetypes, SharkNinja represents the scale-driven appliance manufacturer seeking entry through distribution infrastructure rather than clinical certification.
| Leading Market Players |
|---|
| Therabody |
| Renpho |
| L'Oréal Groupe |
| MZ Skin |
| Qure |
| I-Smart Developments |
| Silk'n |
| Taiki |
| SharkNinja |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with Shenzhen-based lithium-polymer cell manufacturers lock in supply access for smart mask producers while anchoring price visibility against raw material volatility. Hospital procurement networks in the United States leverage multi-year GPO agreements to compress per-unit costs for FDA-cleared connected respiratory devices.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital contracts from direct-to-consumer subscriptions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance grade and sensor sophistication, with NIOSH-certified elastomeric respirators commanding the highest tier. Cost compression in entry-level Bluetooth-enabled masks is intensifying because pharmacy chains limit shelf space for unconnected alternatives. Industrial buyers exhibit the least price sensitivity due to OSHA compliance mandates, while general consumers demonstrate acute sensitivity to subscription renewal rates.
Supply Chain Analysis
Port congestion along the Shanghai-Los Angeles trade lane elevates inbound logistics costs for CMOS sensor modules and photoplethysmography components. Manufacturing concentration in China, South Korea, and Germany draws from lithium-polymer battery production, precision sensor fabrication, and notified body certification infrastructure respectively. Single-source vulnerability in Chinese cell production exposes mask makers to export control risks for wearable power systems. Distribution runs through hospital GPOs and industrial supply houses rather than retail intermediation for clinical-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart mask hardware margins are compressing while app-connected subscription revenue for dermatological treatment protocols expands faster than device sales. Recurring revenue layers now determine lifetime value capture in consumer-facing LED therapy segments.
For Market Incumbents: Consolidate vendor relationships with hospital procurement networks in California and Texas health systems before EU MDR 2027 compliance deadlines lock out late entrants. Backward integration into CMOS sensor production reduces exposure to single-source semiconductor supply from the Yangtze River Delta. FDA software-as-medical-device guidance uncertainty threatens adaptive AI monitoring roadmaps, requiring segregated hardware-software architectures to preserve base device sales. For New Entrants and Emerging Players: Post-acute care remote monitoring for sleep apnea management represents a service-layer gap where incumbents under-serve algorithm-driven respiratory pattern recognition. MFDS fast-track pathways in South Korea offer the most penetrable regulatory entry point for AI-enabled medical devices. Direct-to-patient subscription models for dermatology-focused LED therapy bypass retail markup and capture recurring protocol adherence revenue. For Investors and Strategic Acquirers: Clinical-stage wearable device specialists with established IRB coordination and respiratory physiology expertise present acquisition targets that circumvent validation bottlenecks. Long-term viability hinges on regulatory clearance tier rather than consumer wellness positioning, with FDA 510(k) cleared platforms demonstrating durable pricing power. Watch for EU AI Act high-risk classification enforcement as an inflection indicator that would extend commercialization timelines for algorithm-dependent entrants.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Validates clinical-grade respiratory monitoring for hospital GPO contract eligibility. |
| CE Marking under EU MDR | Locks in first-mover positioning before 2027 notified body capacity constraints. |
| Hospital System Partnership | Secures integrated device-and-data platform contracts displacing standalone mask sales. |
| Software Companion Development | Enables subscription revenue capture from treatment protocol adherence tracking. |
| Reimbursement Strategy | Aligns with value-based care incentives for preventable readmission reduction. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and dermatology clinic operators; and secondary validation through FDA 510(k) filings, MFDS approval databases, hospital procurement contracts, and CMS Medicare reimbursement data. Bottom-up triangulation across sensor component supply chains and top-down validation from healthcare expenditure flows anchored market sizing.
Across the analysis window, forecasts modeled product type segmentation by regulatory clearance tier, end-user segmentation by procurement centralization level, technology segmentation by algorithmic capability layer, and sales channel segmentation by margin capture structure. CAGRs derived from elasticity-adjusted adoption curves for connected respiratory protection and dermatological treatment protocols. Industry-specific inputs included OSHA fit-test mandate compliance rates and MFDS fast-track approval velocity.
Forecasts assume regulatory continuity in FDA software-as-medical-device guidance and EU MDR notified body capacity; material policy shifts would require re-modeling. Algorithm classification risk under the EU AI Act and lithium-polymer export control restrictions represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Infusion Pump Market
Medical Devices
North America Pen Needles Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Portable OT Light Market
Medical Devices
Venous Device Market
Medical Devices
Global Stone Retrieval Basket Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Global Abutment Implants Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Bone Cement Mixers Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Aortic Cannula Systems Market