
 Freeze Drying Masks Market | 2026-2036
Freeze Drying Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Drying Masks Market Insights
Pharmaceutical-grade lyophilization standards are reorganizing competitive tiers in freeze-dried facial masks. L'Oréal S.A. leverages its dermatological research infrastructure to anchor premium positioning in European pharmacy channels. BLOOMAGE BIOTECHNOLOGY dominates domestic supply chains through captive biotech fermentation of active peptides. Estée Lauder Companies, Inc. extends its clinical credibility by specializing in freeze-dried formats for professional treatment settings.
Freeze drying masks are lyophilized sheet masks produced by sublimating frozen aqueous formulations under vacuum, preserving heat-sensitive actives such as epidermal growth factors and stabilized vitamin C at sub-zero temperatures without denaturation. The process yields dry, porous matrices that rehydrate upon contact with aqueous or serum-based activators, extending shelf stability while eliminating preservative load. Hydrating masks lead volume due to universal consumer familiarity and lower formulation complexity, though anti-aging masks command superior margin pools through peptide-dense lyophilized cocktails. Collagen and hyaluronic acid ingredient segments capture the fastest growth as biotech-derived variants replace animal-sourced alternatives, with dermatologist and esthetician end-user channels expanding faster than direct-to-consumer retail.
China's SAMR enforces cosmetic ingredient registration and safety assessment protocols that directly determine market access for imported freeze-dried masks. South Korea's MFDS maintains Good Manufacturing Practice standards for lyophilized cosmetic products that shape domestic export competitiveness. Japan's PMDA oversight of quasi-drug claims restricts functional marketing while elevating clinical evidence requirements for anti-aging positioning. Stakeholders must monitor evolving preservative-free certification standards and professional channel credentialing as dual levers for premium pricing authority.
Market Dynamics
Pharmaceutical-grade lyophilization equipment is concentrating production capacity among biotech-certified manufacturers, forcing mid-tier cosmetic brands to outsource freeze-dried mask production or exit the premium segment entirely. This equipment barrier is reshaping competitive tiers faster than formulation innovation can offset capital disadvantages.
Growth Catalysts
- China's SAMR cosmetic registration protocols:Mandatory safety assessments for preservative-free claims are accelerating demand for lyophilized formats that meet documentation requirements without chemical stabilizers.
- Professional spa channel expansion:South Korean dermatology clinics are standardizing freeze-dried masks as post-procedure protocols, creating institutional procurement pull.
- Biotech-derived peptide fermentation:Advances in recombinant collagen production are lowering raw material costs for anti-aging mask formulations while improving batch consistency.
Market Restraints
- Cold-chain manufacturing infrastructure:Lyophilization requires sub-zero processing facilities that concentrate in South Korea and eastern China, limiting geographic diversification of supply.
- Japan's PMDA quasi-drug evidentiary barriers:Functional anti-aging claims require clinical trial documentation that extends product development timelines by 18-24 months versus cosmetic-only positioning.
- Preservative-free substitution limitations:Conventional hydrogel masks with novel encapsulation technologies compete on convenience for consumers unwilling to activate dry matrices.
Strategic Opportunities
- India's clinical aesthetic sector:Dermatology chains in Mumbai and Delhi are adopting Korean treatment protocols, creating first-mover positioning for freeze-dried mask suppliers with CDSCO documentation.
- At-home activation device convergence:Pairing lyophilized masks with ultrasonic or iontophoresis delivery systems opens premium direct-to-consumer subscription models.
- EU Green Deal chemical reduction mandates:REACH-aligned preservative restrictions are creating regulatory tailwinds for waterless cosmetic formats in German and French pharmacy channels.
Industry Challenges
- Lyophilization technician scarcity:Pharmaceutical-grade vacuum sublimation expertise concentrates in contract manufacturers, forcing brands to rely on toll production with limited quality control visibility.
- ISO 13485 medical device certification timelines:Brands seeking professional channel credibility face 12-18 month audit cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Drying Masks Market |
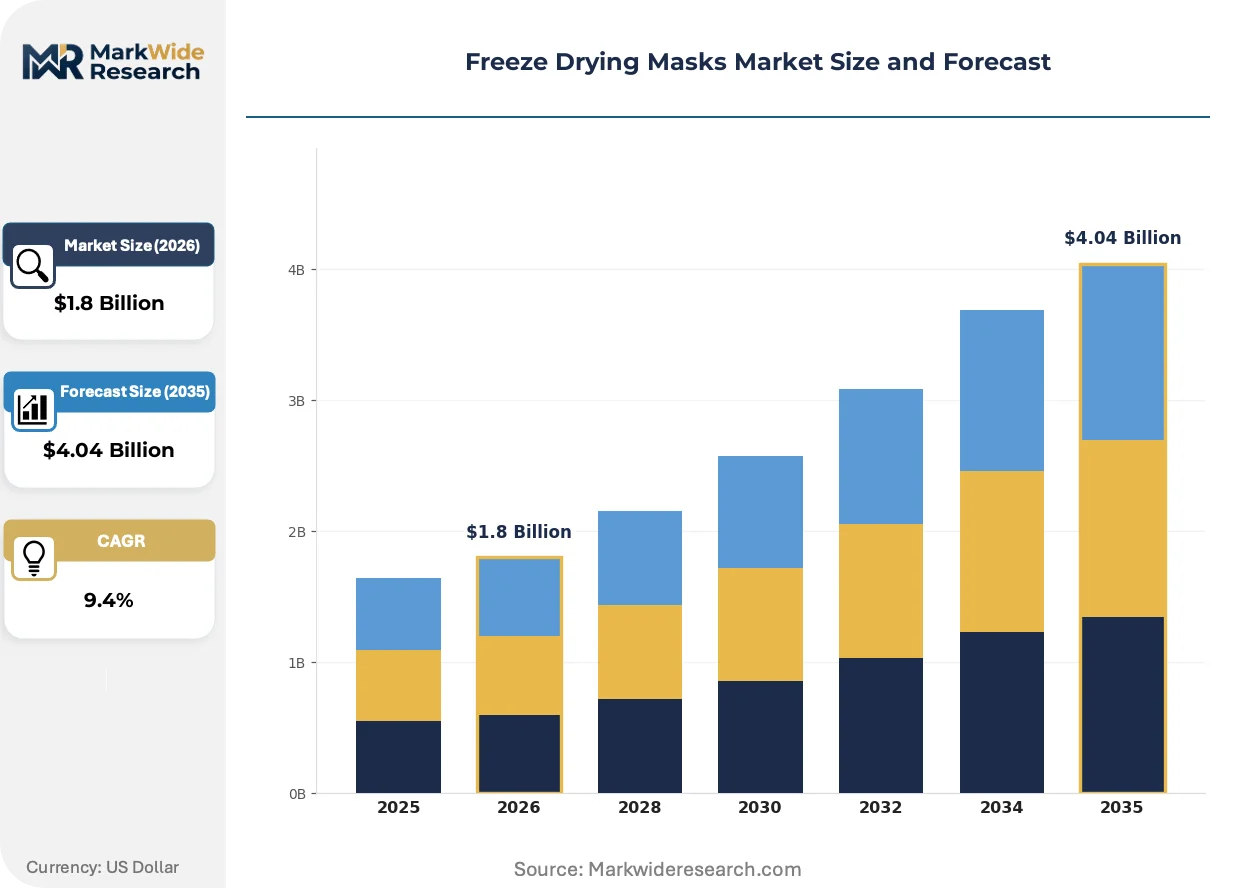
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating Masks, Purifying Masks, Anti-Aging Masks, Brightening Masks Ingredient Type: Collagen, Hyaluronic Acid, Vitamin C, Peptides End User: Consumers, Dermatologists, Estheticians, Spa Professionals Distribution Channel: Online Retail, Specialty Stores, Department Stores, Pharmacies |
| Companies Covered | Herborist, BLOOMAGE BIOTECHNOLOGY, INOHERB, WINONA, exthemax, Maskingdom, Phytomer, L'Oréal S.A., Estée Lauder Companies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Drying Masks Market Trends and Innovations
Lyophilization hardware is miniaturizing while maintaining pharmaceutical-grade vacuum precision, enabling distributed production models that bypass geographic concentration risks. Three converging developments are reshaping how freeze-dried masks reach end users.
Benchtop lyophilization units with sub-50 liter chamber capacity are miniaturizing production economics for regional cosmetic manufacturers. Mid-tier brands in Thailand and Vietnam are adopting these systems to serve domestic pharmacy chains without importing finished masks from Korean contract manufacturers. This distributed production is compressing lead times from 8-12 weeks to under 14 days for localized SKUs.
South Korea's MFDS updated Good Manufacturing Practice standards for lyophilized cosmetics in 2024, mandating real-time moisture monitoring during sublimation cycles. Domestic exporters must retrofit existing vacuum lines or lose MFDS certification required for professional channel sales. The regulation most affects mid-cap manufacturers without capital reserves for sensor infrastructure upgrades.
Japanese consumers are fragmenting purchases across single-use pharmacy formats and subscription-based professional treatments, compressing brand loyalty cycles. Aesthetic clinics in Osaka and Tokyo are responding with membership models that bundle freeze-dried mask protocols with device-based delivery. This channel evolution is most visible in Japan's clinical aesthetic sector, where treatment adherence rates exceed direct-to-consumer retail repurchase frequency.
Freeze Drying Masks Market Segmentation
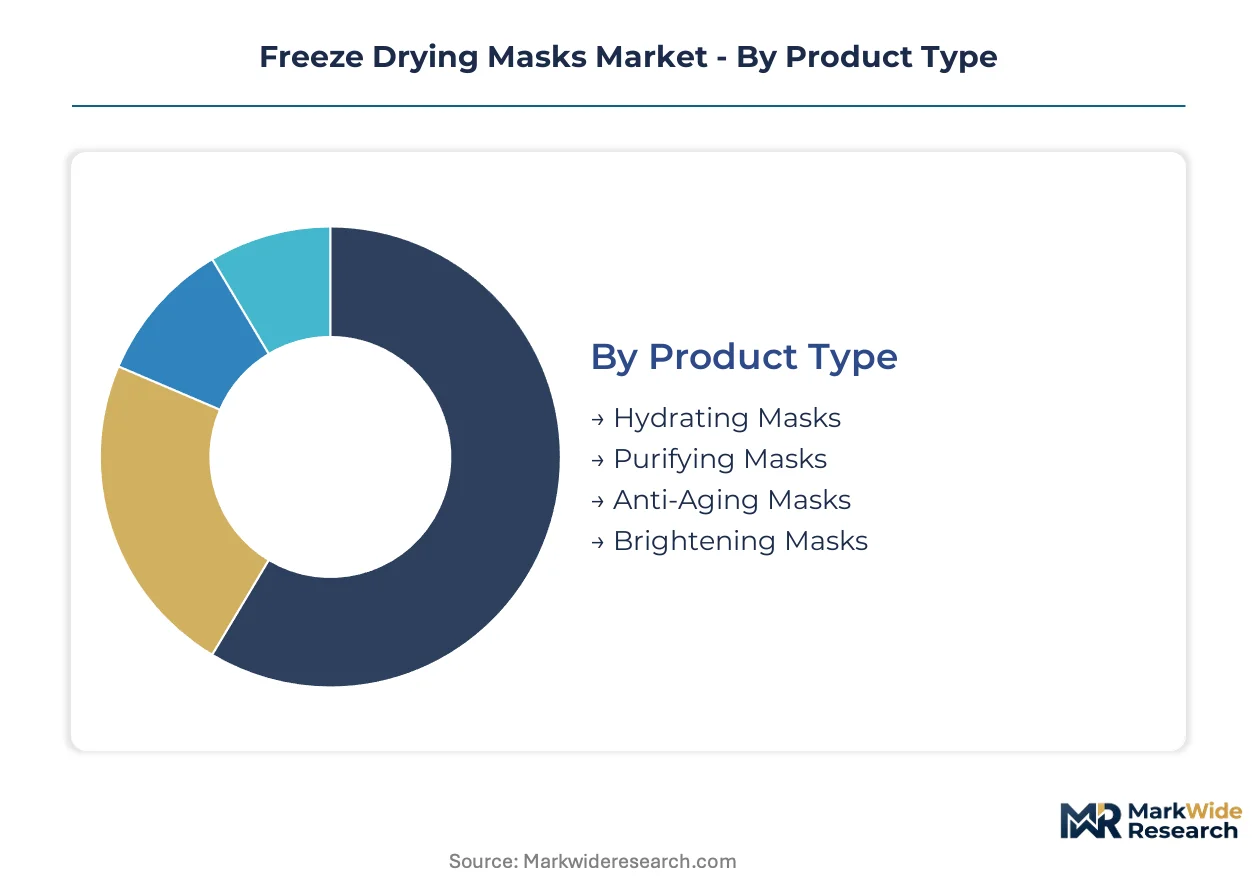
Freeze-dried mask segmentation reveals divergent margin profiles across product types and channel configurations. Pharmaceutical-grade lyophilization requirements concentrate production among certified manufacturers, forcing brands to align portfolio depth with technical capabilities and regulatory documentation.
Product Type:
Domestic consumption in South Korea and Japan favors clinical-grade formats, while export volumes concentrate in universal-use categories with lower activation complexity.
- Hydrating Masks:Lyophilized matrices incorporate hyaluronic acid and trehalose in porous structures that rehydrate with water-based activators. Japanese pharmacy chains in Osaka and Tokyo stock these as entry-level SKUs for first-time freeze-dried mask purchasers. The category benefits from minimal consumer education requirements.
- Anti-Aging Masks:Peptide-dense lyophilized cocktails preserve epidermal growth factors and signal peptides at sub-zero temperatures without denaturation. Seoul dermatology clinics procure these for post-laser treatment protocols, creating institutional demand with recurring purchase cycles. SAMR registration requirements for functional claims limit import competition.
- Purifying Masks:Activated charcoal and tea tree extract formulations target pore refinement in Southeast Asian humid climates.
- Brightening Masks:Stabilized vitamin C and arbutin matrices address hyperpigmentation concerns in East Asian consumer bases.
Hydrating masks command the established base. The steepest expansion runs through anti-aging formats.
Ingredient Type:
Raw material sourcing bifurcates between biotech fermentation facilities in eastern China and marine collagen extraction operations in South Korea.
- Collagen:Recombinant human collagen produced via microbial fermentation in Shandong bioreactors is displacing porcine and bovine alternatives. CDSCO documentation requirements in India favor biotech-derived variants for import approval. Batch consistency improvements are compressing quality control costs.
- Hyaluronic Acid:Low-molecular-weight fractions penetrate dermal layers more effectively than standard cosmetic grades. Chinese manufacturers in Jinan and Weifang dominate global supply, with MFDS-certified exporters capturing Korean professional channel share. Molecular weight specification determines pricing tier placement.
- Vitamin C:Ascorbic acid stabilization through lyophilization avoids oxidation pathways that degrade conventional serum formulations.
- Peptides:Signal peptides and copper tripeptides require pharmaceutical-grade vacuum precision to prevent thermal degradation during processing.
Collagen anchors current formulation volumes. Hyaluronic acid is climbing the fastest as molecular weight customization expands addressable indications.
End User:
Professional channel credentialing requirements in Japan and South Korea segment demand between institutional procurement and direct-to-consumer retail.
- Dermatologists:Clinical settings require ISO 13485-adjacent documentation and post-procedure efficacy data that extends development timelines. PMDA quasi-drug pathways in Japan restrict marketing claims while elevating reimbursement potential for documented outcomes.
- Consumers:At-home activation with bottled activators or device-paired delivery systems dominates volume in Chinese e-commerce channels. Convenience trade-offs against pre-hydrated hydrogel alternatives limit penetration among time-sensitive demographics.
- Estheticians:Korean beauty clinics in Gangnam and Apgujeong standardize freeze-dried protocols for facial treatment add-ons.
- Spa Professionals:Luxury hotel spas in Shanghai and Beijing incorporate lyophilized masks into premium service menus.
Dermatologists anchor premium pricing authority. Consumer channels are expanding most quickly through Tmall and JD.com flagship stores.
Distribution Channel:
Cold-chain integrity requirements concentrate freeze-dried mask distribution through controlled logistics networks in East Asia.
- Pharmacies:German and French pharmacy chains stock preservative-free lyophilized formats under EU Green Deal chemical reduction alignment. Pharmacist consultation requirements educate consumers on activation protocols that direct-to-consumer channels cannot replicate.
- Online Retail:Cross-border e-commerce through Korean and Chinese platforms reaches Southeast Asian consumers without local cold-chain infrastructure. Live-streaming commerce in Douyin and Xiaohongshu demonstrates activation procedures to reduce return rates.
- Specialty Stores:Sephora and equivalent beauty retailers in urban China dedicate shelf space to K-beauty lyophilized brands.
- Department Stores:Premium counters in Tokyo's Ginza and Seoul's Myeongdong emphasize professional-grade positioning.
Pharmacies anchor credibility-driven positioning. Online retail is gaining share fastest through subscription-based replenishment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from South Korean contract manufacturers dominate international supply, while Chinese domestic brands capture accelerating local demand through SAMR-registered formulations. Import dependency concentrates in Southeast Asian markets lacking lyophilization infrastructure.
China
Jinan and Weifang bioreactors supply recombinant hyaluronic acid to domestic mask formulators. SAMR cosmetic ingredient registration protocols mandate preservative-free documentation that favors lyophilized formats. Shanghai dermatology clinics standardize freeze-dried protocols for post-laser recovery.
South Korea
MFDS-certified exporters supply professional channel demand across East Asia. Updated GMP standards in 2024 require real-time moisture monitoring during sublimation cycles. Gangnam aesthetic clinics in Seoul anchor institutional procurement for anti-aging peptide formulations.
Japan
PMDA quasi-drug pathways restrict functional anti-aging marketing while elevating clinical evidence requirements. Osaka and Tokyo aesthetic clinics fragment purchases across single-use pharmacy formats and subscription-based professional treatments. Kanto region manufacturers concentrate pharmaceutical-grade lyophilization capacity.
India
Mumbai and Delhi dermatology chains adopt Korean treatment protocols, creating first-mover positioning for suppliers with CDSCO documentation. Biotech-derived collagen variants satisfy import approval requirements that exclude animal-sourced alternatives. Clinical aesthetic sector expansion outpaces retail channel development.
Germany
EU Green Deal chemical reduction mandates through REACH-aligned preservative restrictions create regulatory tailwinds for waterless formats. Pharmacy chains in Berlin and Munich stock lyophilized masks under pharmacist consultation requirements. Domestic manufacturers lack lyophilization scale, forcing import reliance on Korean suppliers.
Freeze Drying Masks Market Competitive Landscape
Listed leaders compete with private specialists across capital access and production agility. L'Oréal S.A. and Estée Lauder Companies, Inc. leverage dermatological research infrastructure against biotech-anchored private operators. Three archetypes dominate: multinational beauty conglomerates with clinical credibility, captive biotech fermenters controlling peptide supply, and regional contract manufacturers serving toll production demand. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with equipment barriers forcing mid-tier brands toward outsourcing relationships.
Among the multinational tier, L'Oréal S.A. and Estée Lauder Companies, Inc. exemplify dermatology-channel positioning through professional-grade documentation. BLOOMAGE BIOTECHNOLOGY occupies a distinct archetype as a domestic Chinese operator with captive fermentation infrastructure. These three anchors represent the competitive tension between clinical credibility, supply chain control, and geographic market access that defines tier placement in freeze-dried mask procurement.
| Leading Market Players |
|---|
| Herborist |
| BLOOMAGE BIOTECHNOLOGY |
| INOHERB |
| WINONA |
| exthemax |
| Maskingdom |
| Phytomer |
| L'Oréal S.A. |
| Estée Lauder Companies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Seoul-based contract manufacturers and Japanese dermatology chains lock in both lyophilization capacity access and three-year price visibility for peptide-dense anti-aging formats. These arrangements insulate premium tier procurement from spot-market volatility in biotech-derived collagen while binding mid-tier brands to toll-production queues with limited negotiating leverage.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in freeze-dried mask procurement. Premium tiers command certification-grade premiums through MFDS and PMDA documentation, while economy positioning competes on unit cost against novel encapsulation hydrogels. Pricing pressure stems from biotech fermentation scale-up in Shandong bioreactors compressing recombinant collagen costs. Consumer direct-to-channel segments exhibit highest price sensitivity; professional dermatology clinics demonstrate lowest sensitivity due to protocol standardization requirements.
Supply Chain Analysis
South Korea and eastern China anchor pharmaceutical-grade lyophilization capacity for freeze-dried facial masks. Production draws from recombinant peptide fermentation facilities in Jinan, vacuum sublimation equipment clusters near Seoul, and specialized moisture-barrier packaging operations in Osaka. Single-source vulnerability concentrates in MFDS-certified contract manufacturers serving cross-border demand. Distribution runs through cold-chain logistics networks linking Gangnam aesthetic clinics to pharmacy chains in Tokyo and cross-border e-commerce fulfillment centers in Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade vacuum sublimation expertise concentrates in a handful of contract manufacturers, creating acute capability scarcity that shapes competitive access and M&A targeting across the forecast window.
For Market Incumbents: Compound defensive positioning through captive biotech fermentation of signal peptides and backward integration into lyophilization equipment partnerships. Capacity reservation agreements with Seoul-based contract manufacturers neutralize queue-jumping threats from emerging K-beauty brands. ISO 13485 certification maintenance preserves professional channel credentialing against regulatory escalation in Japan. For New Entrants and Emerging Players: Post-procedure protocol standardization in Indian dermatology chains represents a service-layer gap where incumbents under-serve CDSCO documentation requirements. Target Mumbai and Delhi clinical aesthetic sectors through Korean treatment protocol licensing partnerships. Device-paired activation systems open premium direct-to-consumer subscription models with recurring revenue mechanics absent from conventional retail. For Investors and Strategic Acquirers: Biotech-anchored mid-cap formulators with SAMR-registered preservative-free portfolios represent the most defensible acquisition target archetype. Long-term viability hinges on regulatory tailwinds from EU Green Deal chemical reduction mandates and REACH-aligned preservative restrictions. Watch for MFDS GMP enforcement actions that force sub-scale manufacturers into distressed sale scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation Agreements | Secures lyophilization queue priority with Seoul contract manufacturers against competitor access. |
| Biotech Fermentation Scale-Up | Captive recombinant collagen production in Shandong bioreactors compresses raw material cost variability. |
| ISO 13485 Certification Investment | Unlocks professional dermatology channel procurement in Japan and South Korea with documented quality systems. |
| Device-Paired Activation Launch | Ultrasonic delivery system bundling creates subscription revenue models with treatment adherence tracking. |
| CDSCO Documentation Pathway | Enables first-mover positioning in Mumbai and Delhi clinical aesthetic sectors adopting Korean protocols. |
Research Methodology
Operator-level perspectives from lyophilization equipment technicians, dermatology clinic procurement managers, biotech fermentation facility directors, and pharmacy chain category buyers anchored the qualitative base. Primary interview findings triangulated against SAMR cosmetic registration databases, MFDS GMP certification records, PMDA quasi-drug filing documentation, and customs trade flow data for freeze-dried cosmetic imports. Bottom-up SKU-level volume estimates reconciled with top-down market sizing across product type, ingredient category, end-user channel, and distribution format dimensions.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity, biotech fermentation yield improvement trajectories, and professional channel adoption curves. The analytical framework modeled hydration, anti-aging, purifying, and brightening product types; collagen, hyaluronic acid, vitamin C, and peptide ingredient segments; dermatologist, esthetician, spa professional, and consumer end-user channels; and pharmacy, online retail, specialty store, and department store distribution pathways. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and channel penetration assumptions.
Forecasts assume regulatory continuity in SAMR cosmetic safety protocols, MFDS lyophilized GMP standards, and PMDA quasi-drug evidentiary requirements; material policy shifts would require re-modeling. Supply concentration in Korean contract manufacturing and Shandong bioreactor clusters, plus cold-chain logistics cost volatility, constitute primary revision triggers. Recalibration cycles align with material shifts in preservative-free certification standards and professional channel credentialing evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
Medical Gas Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Serological Pipettes Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Intravenous (IV) Fluid Bags Market
Medical Supplies
Foley Trays Market
Medical Supplies
Pressure Relief Mattress Market