
 Physiological Saline Market | 2026-2036
Physiological Saline Market Size, Share, and Industry Trends Forecast 2026-2036
Physiological Saline Market Intelligence
The consolidation of purchasing through Group Purchasing Organizations is rewriting the competitive landscape for suppliers. Baxter International Inc. leverages its extensive manufacturing scale and established hospital relationships to secure large volume contracts. Fresenius Kabi AG specializes in infusion therapy and clinical nutrition, giving it a focused advantage in this core segment. B. Braun Melsungen AG competes through a broad portfolio of medical devices and pharmaceutical products, including saline solutions.
Physiological saline is a sterile solution of sodium chloride (NaCl) in water, typically at a 0.9% concentration to match the osmolarity of human bodily fluids. Its primary purpose is to serve as an intravenous fluid for rehydration, a vehicle for drug delivery, and a solution for wound irrigation. Isotonic saline commands the largest share due to its wide use in IV fluid applications, while demand for flexible bags is displacing traditional glass bottles. Hospitals remain the dominant end-user segment, procuring saline for a multitude of procedures from dialysis to wound cleaning.
Product manufacturing and quality are strictly governed by pharmaceutical regulations, including standards set by the US FDA and the European Medicines Agency (EMA). Market access in key geographies like China requires adherence to specifications from the NMPA, impacting supply chain and labeling. Navigating manufacturing capacity constraints during public health emergencies remains a critical challenge for all suppliers.
Market Dynamics
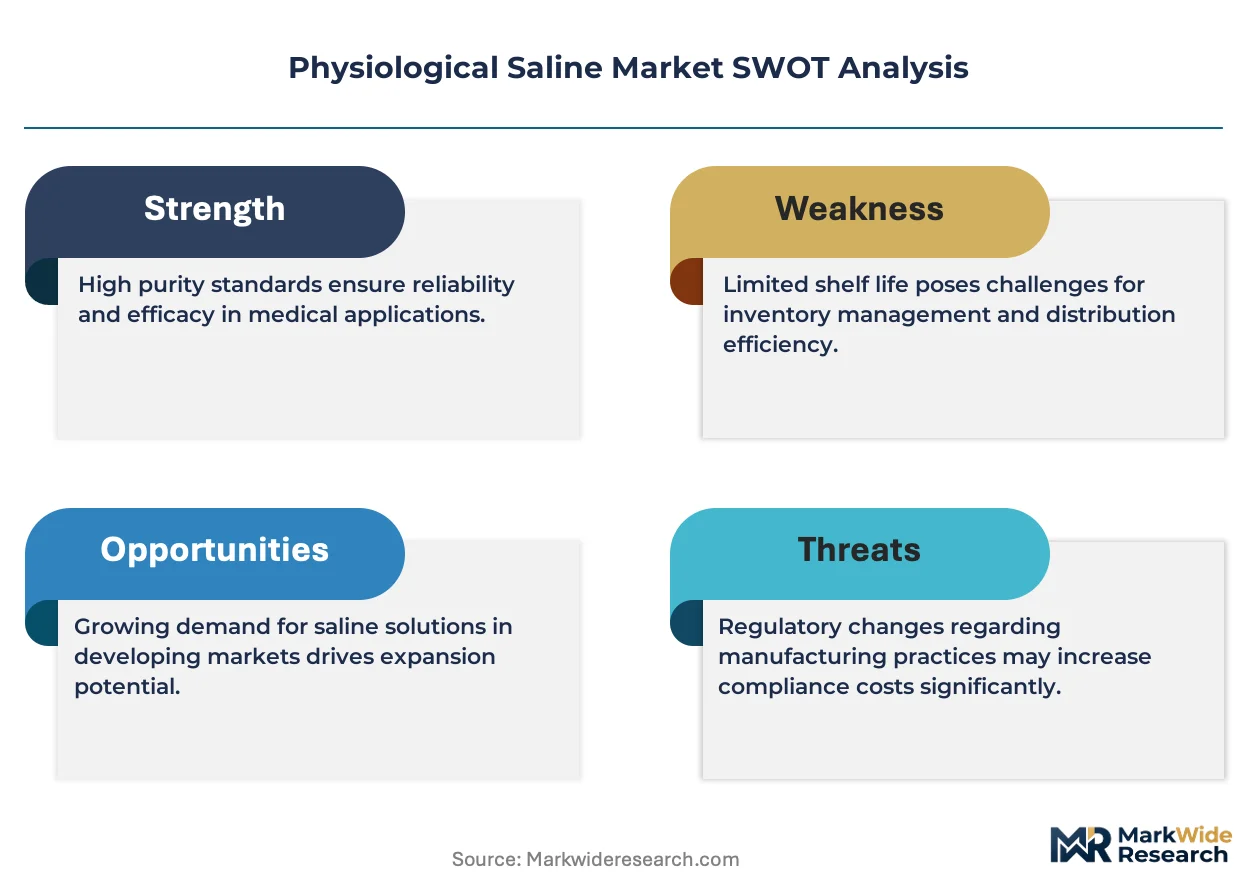
The physiological saline market is shaped by the fundamental tension between its commodity status, driven by high-volume hospital contracts, and the non-negotiable regulatory demands for sterility and quality, which intensify during public health emergencies and supply chain disruptions.
Growth Catalysts
- Public Health Investment:Government-led initiatives in countries like China to expand and modernize public hospital infrastructure directly increase the foundational demand for intravenous solutions for patient care and emergency preparedness.
- Chronic Disease Management:The rising prevalence of conditions requiring regular treatment, such as end-stage renal disease for dialysis and certain cancers for chemotherapy hydration, creates a consistent, long-term demand stream from specialized clinics and hospitals.
- Packaging Innovation:The clinical shift from glass bottles to sterile, single-use flexible bags made from materials like PVC or non-PVC polymers reduces the risk of contamination and handling errors, supporting adoption in critical care settings.
Market Restraints
- Raw Material Volatility:Price fluctuations in USP-grade sodium chloride and, more critically, water for injection (WFI) systems and their high energy costs can compress manufacturer margins, as saline itself is a low-price, high-volume product.
- Manufacturing Concentration:The global supply is dominated by a small number of large-scale producers, creating significant vulnerabilities and potential for widespread shortages during sudden demand spikes or if a major facility goes offline.
- Regulatory Compliance Burden:Gaining and maintaining facility certification from bodies like the US FDA and EMA involves substantial capital investment and lengthy validation processes, acting as a high barrier to entry for new competitors.
Strategic Opportunities
- Emerging Market Penetration:Supplying basic healthcare systems in under-resourced regions of Africa and Southeast Asia represents a significant volume opportunity, especially where local sterile manufacturing capabilities are limited or non-existent.
- Bioprocessing Applications:Saline's use as a stable, isotonic buffer and rinsing agent in cell and gene therapy manufacturing presents a high-value niche, moving it beyond patient care into advanced biopharmaceutical production.
- Home Healthcare Channels:Developing pre-packaged kits for home infusion therapy for patients with chronic conditions creates a new distribution channel that bypasses the competitive GPO-dominated hospital segment for specific indications.
Industry Challenges
- Capital-Intensive Production:Building and maintaining sterile manufacturing lines that meet current Good Manufacturing Practices (cGMP) requires significant upfront capital investment in automation, cleanroom environments, and quality control systems.
- Supply Chain Resilience:Ensuring a validated and redundant supply of critical components, such as polymer films for bags and sterile ports, is a persistent operational challenge, especially when faced with geopolitical or logistical disruptions.
- Pharmacopeia Harmonization:Adhering to evolving and sometimes conflicting standards for labeling, packaging, and purity across different regional pharmacopeias (e.g., USP, EP, JP) complicates global distribution and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physiological Saline Market |
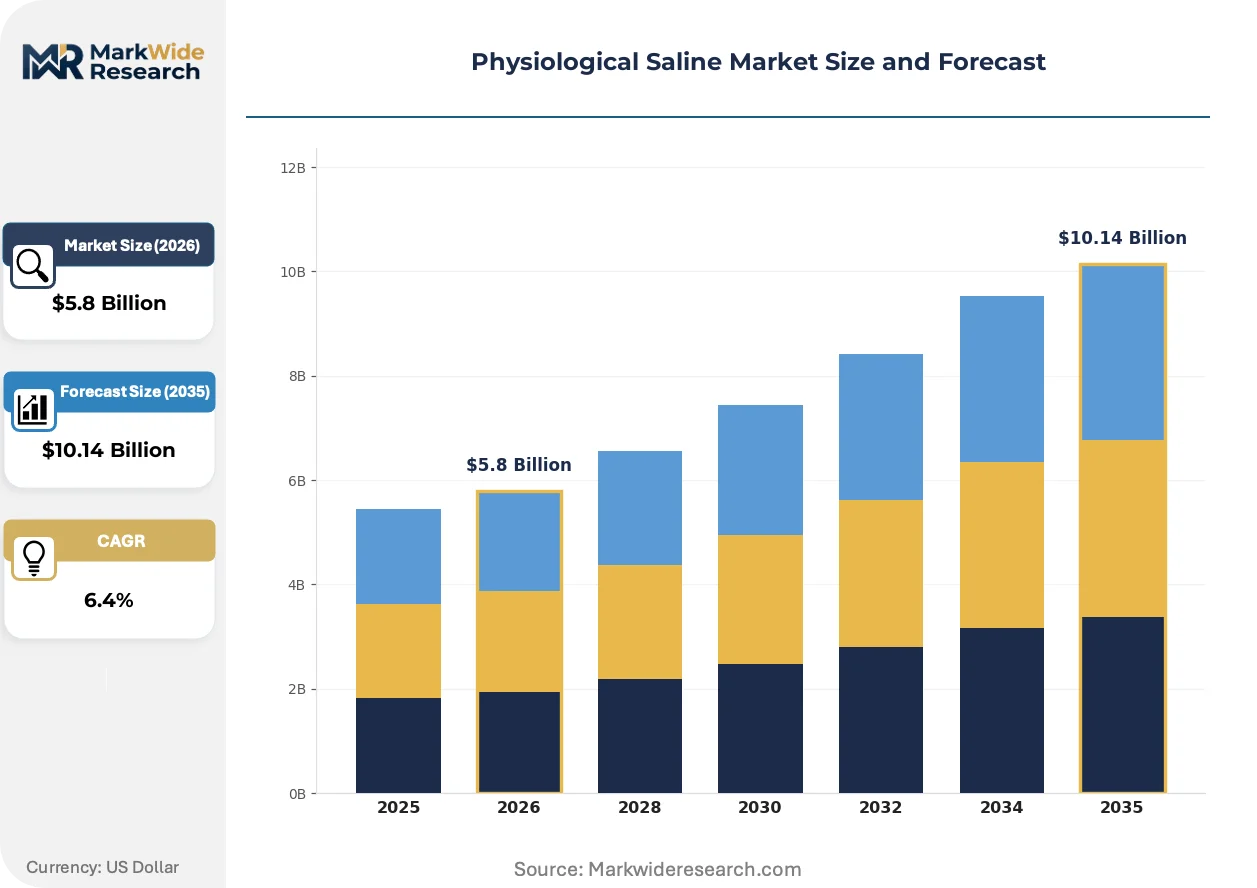
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isotonic Saline, Hypertonic Saline, Hypotonic Saline, Buffer Solutions End User: Hospitals, Clinics, Home Care, Laboratories Packaging Type: Bottles, Ampoules, Pouches, Flexible Bags Application: IV Fluids, Wound Cleaning, Dialysis, Laboratory Studies |
| Companies Covered | Baxter International Inc, B. Braun Melsungen AG, Fresenius Kabi AG, ICU Medical Inc, Otsuka Pharmaceutical Co Ltd, Pfizer Inc, Grifols SA, Medline Industries LP, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physiological Saline Market Strategic Shifts & Innovations
Product and packaging advancements are transforming physiological saline from a basic commodity into a more integrated component of safe and efficient clinical practice. This evolution is driven by a convergence of technological capability, stricter regulatory oversight, and changing institutional procurement behaviors.
Single-use, pre-filled flexible bags featuring integrated sterile connection ports represent a key product evolution. Hospitals and emergency medical services are adopting these systems to improve workflow efficiency and patient safety. This adoption is collapsing the time and infection risk associated with manual preparation from vials or glass bottles, directly reducing the potential for medication errors and hospital-acquired infections.
Heightened regulatory focus from the US FDA and European Medicines Agency (EMA) is driving stricter quality standards for parenteral drug manufacturing. This mandates significant investment in advanced aseptic processing, automated visual inspection systems, and enhanced testing for impurities and endotoxins. The hospital end-user segment is most impacted, as its procurement criteria increasingly favor suppliers who can provide robust documentation of compliance with global pharmacopeia standards.
Consolidation of purchasing power through Group Purchasing Organizations (GPOs) is altering supplier relationships. These entities are moving beyond simple price negotiations to demand verifiable supply chain resilience and guaranteed availability as core components of large-volume contracts. This dynamic is most pronounced in the United States and parts of Europe, where GPOs heavily influence hospital procurement decisions and create a challenging environment for smaller suppliers.
Physiological Saline Market Segmentation
The physiological saline market exhibits distinct segmentation across product types, end-users, packaging formats, and applications. Understanding these segments helps suppliers align product offerings with specific clinical needs and procurement preferences across diverse healthcare environments.
Product Type:
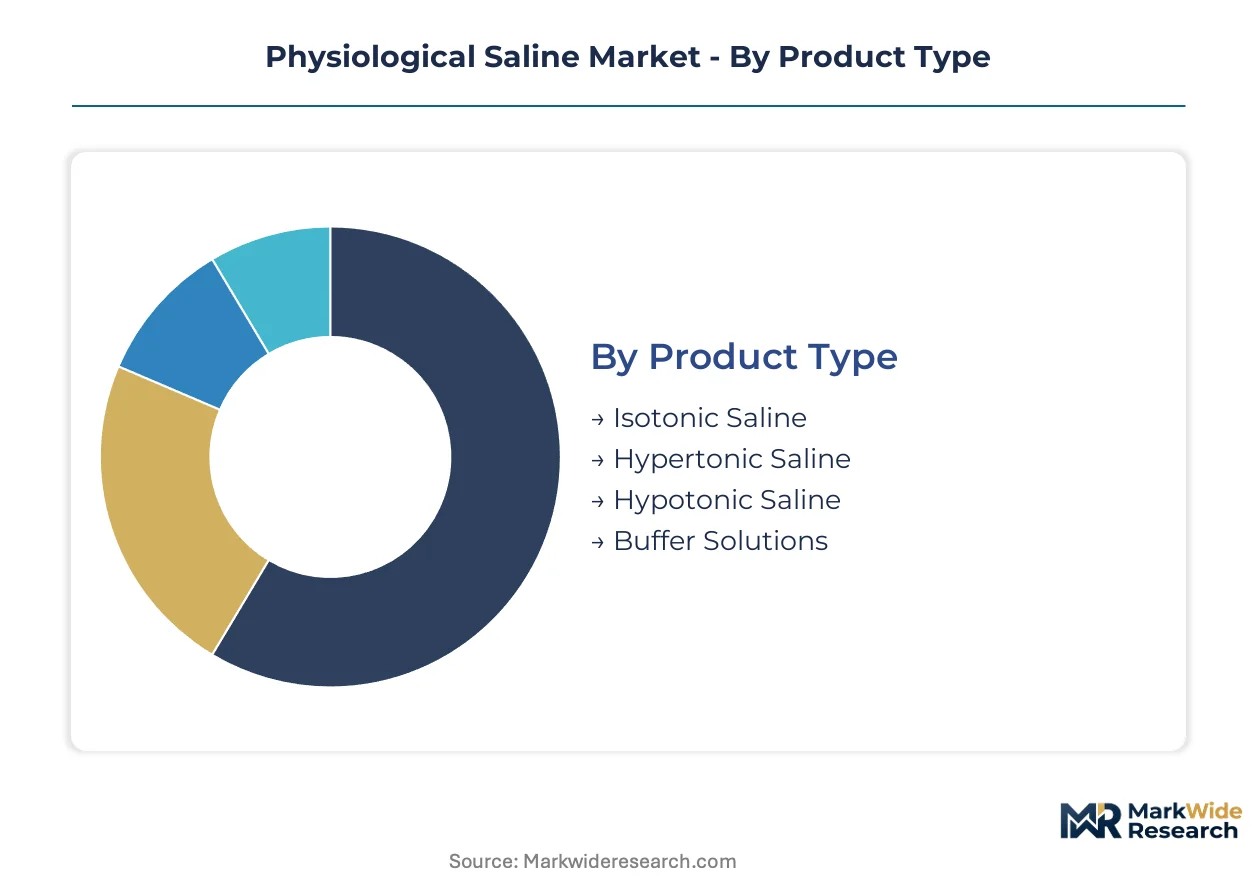
The osmolarity of saline solutions defines the product type dimension, influencing their physiological utility.
- Isotonic Saline:A 0.9% sodium chloride solution, matching human blood osmolarity. It serves as the standard intravenous fluid for rehydration and drug delivery in hospitals.
- Hypertonic Saline:Solutions with a higher solute concentration than bodily fluids, typically 3% or 7% NaCl. Demand concentrates in critical care for cerebral edema management and severe hyponatremia.
- Hypotonic Saline:Solutions with lower solute concentration, like 0.45% NaCl. These are used for cellular rehydration in specific clinical conditions.
- Buffer Solutions:Specialized saline formulations containing buffering agents to maintain pH. These are critical for maintaining cell viability in laboratory studies.
Isotonic Saline holds installed capacity. Hypertonic Saline is rotating up the share rankings.
End User:
Customer type dictates the volume and specific requirements for physiological saline procurement.
- Hospitals:Large-scale healthcare facilities requiring vast volumes of saline for IV administration, surgical procedures, and emergency care. Demand is concentrated in major urban centers due to patient density and complex medical needs.
- Home Care:Provision of medical services in a patient's residence, including home infusion therapy for chronic conditions. This segment is expanding due to an aging population and preference for at-home treatment.
- Clinics:Outpatient facilities using saline for minor procedures, diagnostic imaging, and basic rehydration.
- Laboratories:Research and diagnostic facilities utilizing saline as a diluent, rinsing agent, and cell culture medium.
Hospitals represent the primary demand driver within this segment. Home Care exhibits strong expansion.
Packaging Type:
Supply concentration in packaging types reflects the shift towards enhanced sterility and user convenience.
- Flexible Bags:Single-use containers made from PVC or non-PVC polymers, featuring integrated sterile ports. Their demand is concentrating in critical care settings due to reduced contamination risk and improved workflow efficiency.
- Bottles:Traditional glass or rigid plastic containers, often requiring separate administration sets. Hospitals in developing regions still extensively use bottles due to established infrastructure and lower initial cost.
- Ampoules:Small, sealed glass containers for single-dose sterile solutions. They are primarily used for small volume drug reconstitution or flushing.
- Pouches:Similar to flexible bags but often smaller in volume, used for specific drug delivery or irrigation needs.
The shift towards Flexible Bags is pronounced. Bottles maintain a significant but declining role.
Application:
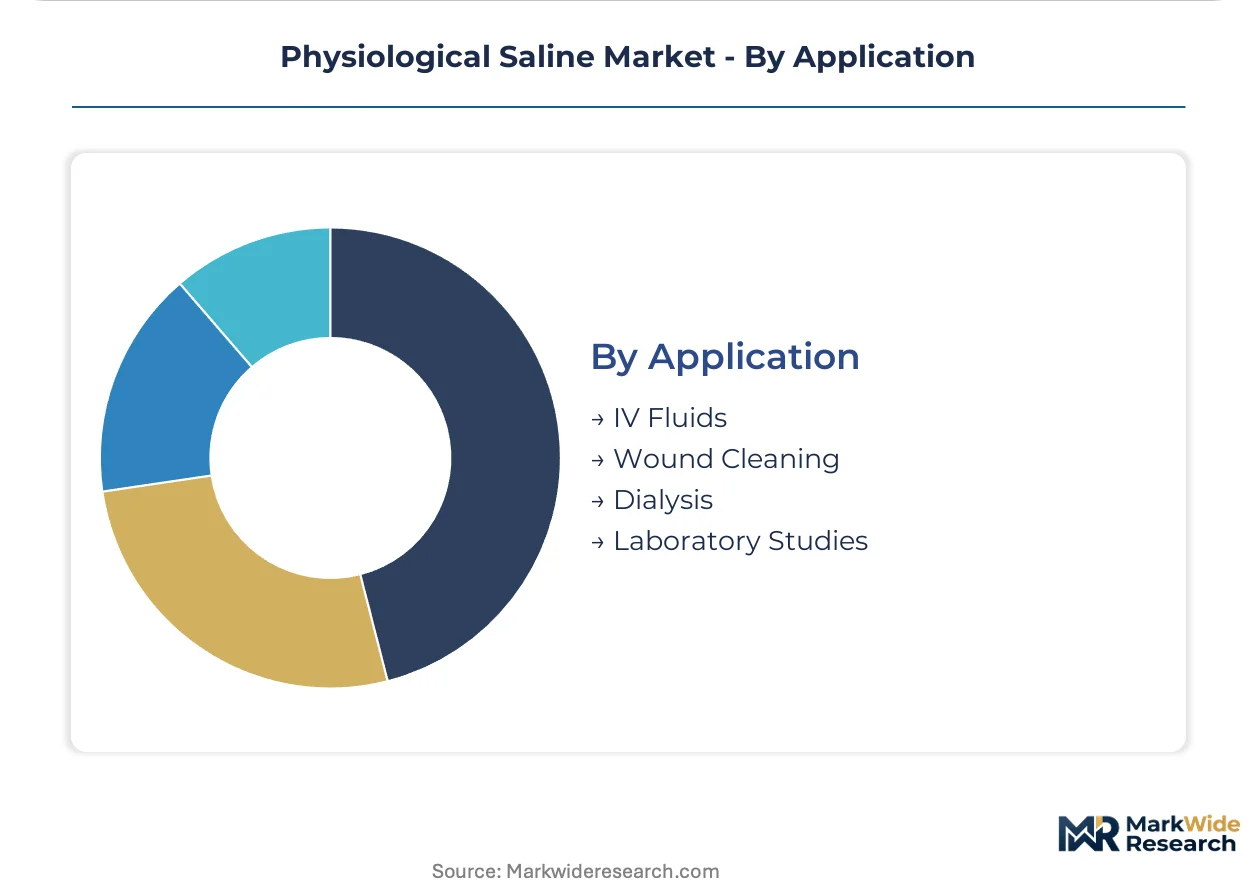
Application maturity determines the established protocols and emerging uses for physiological saline.
- IV Fluids:Intravenous administration of saline for rehydration, electrolyte balance, and as a carrier for medications. This application forms the foundational demand in all acute care settings globally.
- Dialysis:Use of saline for priming dialysis machines, flushing catheters, and managing fluid balance in patients with renal failure. Demand is consistent and driven by the rising prevalence of chronic kidney disease.
- Wound Cleaning:Application of sterile saline to irrigate and debride wounds, preventing infection and promoting healing.
- Laboratory Studies:Saline serves as a diluent, wash solution, or control in various biochemical and cell culture experiments.
IV Fluids dominate immediate demand. Dialysis provides a consistent, long-term requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global medical supply chain infrastructure underpins the distribution of physiological saline across diverse geographies. This critical network ensures essential intravenous solutions reach healthcare facilities worldwide. Strategic regional investments in public health significantly influence market dynamics and demand patterns.
China
Government-led initiatives to expand public hospital infrastructure significantly boost saline demand across China. The NMPA strictly governs product specifications and supply chain integrity for medical devices. Manufacturing capabilities in the Yangtze River Delta region are rapidly scaling to meet national requirements.
United States
Extensive hospital systems and chronic disease management programs maintain consistent demand for IV fluids in the United States. US FDA mandates rigorous quality standards for all parenteral drug manufacturing. Major pharmaceutical clusters in the Northeast Corridor drive innovation in sterile packaging.
Germany
Germany's advanced healthcare system and aging population generate substantial demand for physiological saline in hospitals. The European Medicines Agency (EMA) enforces stringent quality and manufacturing standards for all medical solutions. Key medical technology clusters in Bavaria are developing next-generation infusion therapies.
India
Expanding public healthcare access and a vast patient population fuel significant demand for basic medical consumables in India. The CDSCO regulates pharmaceutical manufacturing and distribution to ensure product safety. Gujarat's pharmaceutical hubs are increasing production capacity for essential IV solutions.
Japan
Japan's rapidly aging population and sophisticated healthcare infrastructure drive demand for high-quality physiological saline. The PMDA maintains strict regulatory oversight for all pharmaceutical and medical device imports. The Kanto region remains a hub for advanced medical research and development in sterile solutions.
Physiological Saline Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the physiological saline market. This market exhibits a tiered structure, with a few large-scale producers dominating high-volume contracts. Strategic archetypes include diversified pharmaceutical giants, specialized infusion therapy providers, and broad-portfolio medical device manufacturers. Dominant competitive moves involve securing large group purchasing organization contracts and expanding manufacturing capacity to meet demand spikes.
Among the established medical solution providers, Baxter International Inc. exemplifies a diversified global healthcare company leveraging extensive manufacturing scale and established hospital relationships. Fresenius Kabi AG represents a focused specialist in infusion therapies and clinical nutrition, emphasizing core medical segments with deep product expertise. B. Braun Melsungen AG occupies a position as a broad-portfolio medical device and pharmaceutical manufacturer, offering a wide range of essential hospital products including saline. These entities demonstrate the varying strategic approaches to capturing market share within this essential commodity segment, often relying on long-term supply agreements.
| Leading Market Players |
|---|
| Baxter International Inc |
| B. Braun Melsungen AG |
| Fresenius Kabi AG |
| ICU Medical Inc |
| Otsuka Pharmaceutical Co Ltd |
| Pfizer Inc |
| Grifols SA |
| Medline Industries LP |
| Terumo Corporation |
| Others |
Cost & Logistics Intelligence
Underutilized global manufacturing capacity outside of crisis periods drives supplier behavior, influencing competitive pricing and strategic inventory management. This dynamic shapes how suppliers approach long-term contracts and capital investments.
Pricing Analysis
Volume-discount tiering structures characterize pricing in the physiological saline market, favoring large purchasers. The dominant pricing model is contract-based long-term offtake, particularly through Group Purchasing Organizations for hospital systems. Price differentiation stems from stringent quality grade certifications, like those from the US FDA, and the significant volume scale of procurement. Cost compression intensifies due to raw material volatility for USP-grade sodium chloride and water for injection. Hospitals, leveraging GPOs, represent the most price-sensitive buyers, while specialized bioprocessing applications exhibit lower sensitivity.
Supply Chain Analysis
Strict regulatory mandates from bodies like the NMPA in China and the US FDA limit cross-border flows of physiological saline, necessitating adherence to diverse specifications. Supply concentration centers on key manufacturing hubs in China, the United States, and Germany. The industry sources critical raw materials such as USP-grade sodium chloride and specialized polymer films for flexible bags. Single-source vulnerability remains a structural risk, particularly for essential components like sterile ports. Downstream distribution primarily relies on established hospital procurement channels and emerging home healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The physiological saline market is undergoing a platform-economics inflection, driven by the shift towards integrated flexible bags with sterile connection ports. This evolution creates an ecosystem around safe and efficient intravenous fluid delivery systems.
For Market Incumbents: Entrench existing market positions by securing long-term Group Purchasing Organization contracts and expanding manufacturing capacity in key geographies like China. This defends against margin pressure from raw material volatility and emerging specialized entrants. Investing in robust regulatory certification, including US FDA and EMA standards, reinforces product quality and supply chain resilience. Deepening established hospital relationships provides critical channel control. For New Entrants and Emerging Players: Geographic underpenetration in basic healthcare systems across Africa and Southeast Asia represents a significant white-space opportunity. Targeting high-value bioprocessing applications in advanced biopharmaceutical production offers another niche. The most penetrable segment involves supplying regions where local sterile manufacturing capabilities are limited. A viable go-to-market angle is developing pre-packaged kits for home infusion therapy, bypassing GPO-dominated hospital channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among producers with established long-term supply agreements and diversified end-user segments. This market offers long-term viability given physiological saline's essential, non-discretionary nature and the rising prevalence of chronic diseases. Acquisition targets should include specialized infusion therapy providers or manufacturers possessing advanced aseptic processing capabilities. The signal to watch for market inflection is the accelerated adoption rates of non-PVC flexible bags in emerging markets.| Strategic Initiative | Industry Significance |
|---|---|
| Expand sterile manufacturing capacity in Asia | Increases supply resilience and market access in high-growth regions like China and India. |
| Develop non-PVC flexible bag solutions | Addresses clinical demand for reduced contamination risk and improved patient safety. |
| Forge partnerships with Group Purchasing Organizations | Secures large-volume contracts and stable demand from dominant hospital end-users. |
| Invest in advanced bioprocessing saline formulations | Captures high-value niche demand from cell and gene therapy manufacturing. |
| Strengthen supply chain for critical raw materials | Mitigates price volatility and ensures continuity of production for essential inputs. |
Research Approach
Operator-level perspectives from hospital procurement managers, GPO contract specialists, pharmaceutical R&D leads, and regulatory affairs professionals anchored the qualitative base. This primary research was triangulated with extensive secondary validation from sources including US FDA filings, EMA submissions, NMPA guidelines, and relevant industry association reports. A robust bottom-up and top-down approach ensured comprehensive data synthesis.
Scenario-bracketing informed the quantitative forecast framework, assessing market trajectories under various economic and regulatory conditions across the analysis window. The model integrated segmentation dimensions including product types, end-users, packaging formats, applications, and regional regulatory clusters. Compound annual growth rates were derived through statistical regression analysis. Key industry-specific forecast inputs included chronic disease prevalence rates and government public health investment trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified pharmaceutical giants or specialized infusion therapy providers would shift outcomes. This analysis reflects assumptions regarding regulatory stability and market access. Material shifts in public health emergencies or major manufacturing facility outages would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Disposable and Reusable Masks Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Medical Gas Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
US Ostomy Care and Accessories Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Global Unna Boot Market
Medical Supplies
Cryotubes Market
Medical Supplies
Swab Cups Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Global Urinary Drainage Bags Market