
 GCC Syringes and Needles Market | 2026-2036
GCC Syringes and Needles Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Syringes and Needles Market Foresight
Hospital end-user demand is shifting toward safety-engineered syringes and needles across the GCC. Becton, Dickinson and Company anchors its regional position through extensive distribution networks covering Saudi Arabia and the UAE. Terumo Corporation differentiates via advanced safety needle technology tailored to infection control protocols. Abu Dhabi Medical Devices Company leverages local manufacturing advantages to compete on cost and delivery speed for government tenders.
Syringes and needles are precision medical instruments typically manufactured from medical-grade stainless steel, polypropylene barrels, and latex-free elastomeric plungers, designed to deliver sterile fluid transfer or extraction with controlled dosing accuracy. Safety needles and hypodermic syringes command the strongest margin pools as healthcare facilities prioritize sharps injury prevention and single-use sterility standards. Blood collection and vaccination applications drive volume throughput, while diabetes care segments sustain recurring demand through chronic disease management protocols.
SFDA regulations in Saudi Arabia, UAE Ministry of Health and Prevention standards, and GCC-wide harmonization efforts on medical device registration collectively shape product compliance requirements and market access pathways. These frameworks mandate sterility assurance, material biocompatibility, and traceability systems that filter out uncertified suppliers. Stakeholders must monitor evolving prequalification criteria for national tender programs and alignment with anticipated Gulf Centralized Procedure developments.
Market Dynamics
Saudi Food and Drug Authority mandates on sharps injury prevention are compressing procurement timelines across GCC hospital networks. Government healthcare infrastructure spending in Saudi Arabia and the UAE is accelerating safety-engineered device replacement cycles.
Growth Catalysts
- Safety-Engineered Device Mandates:SFDA regulations in Saudi Arabia now require retractable needles and shielded syringes in all public healthcare facilities, creating immediate replacement demand across the Kingdom's hospital network.
- Diabetes Prevalence:Chronic disease management protocols in the UAE and Kuwait sustain recurring demand for insulin delivery devices, with patient registries expanding faster than population growth.
- Vaccination Program Scale-Up:National immunization drives in Qatar and Oman prioritize single-use sterility standards, driving volume throughput in disposable syringe procurement.
Market Restraints
- Medical-Grade Polypropylene Concentration:Raw material supply for barrel production concentrates among Asian petrochemical suppliers, exposing GCC converters to freight cost volatility and currency fluctuation risk.
- Safety Mechanism Patent Thickets:Retractable needle and shielded syringe IP portfolios held by established manufacturers create licensing friction for regional entrants seeking to localize production.
- Stainless Steel Hypodermic Tubing Import Dependency:Precision needle cannula manufacturing remains concentrated in European and East Asian specialist foundries, limiting GCC supply chain autonomy.
Strategic Opportunities
- Local Manufacturing Incentives:Saudi Arabia's medical device localization programs offer tender preference and customs duty relief for domestic production of safety-engineered syringes.
- Home Healthcare Expansion:Self-administration protocols for biologics and hormone therapies are creating demand for patient-friendly safety needles with reduced activation force.
- GCC Harmonized Registration:Anticipated Gulf Centralized Procedure developments would streamline multi-country market access, reducing redundant conformity assessment costs for manufacturers.
Industry Challenges
- Sterility Assurance Validation:Ethylene oxide sterilization facility qualification and residual testing compliance timelines extend product launch schedules by 12-18 months for new market entrants.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization studies face capacity constraints at notified body laboratories, delaying regulatory submissions for elastomeric plunger formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Syringes and Needles Market |
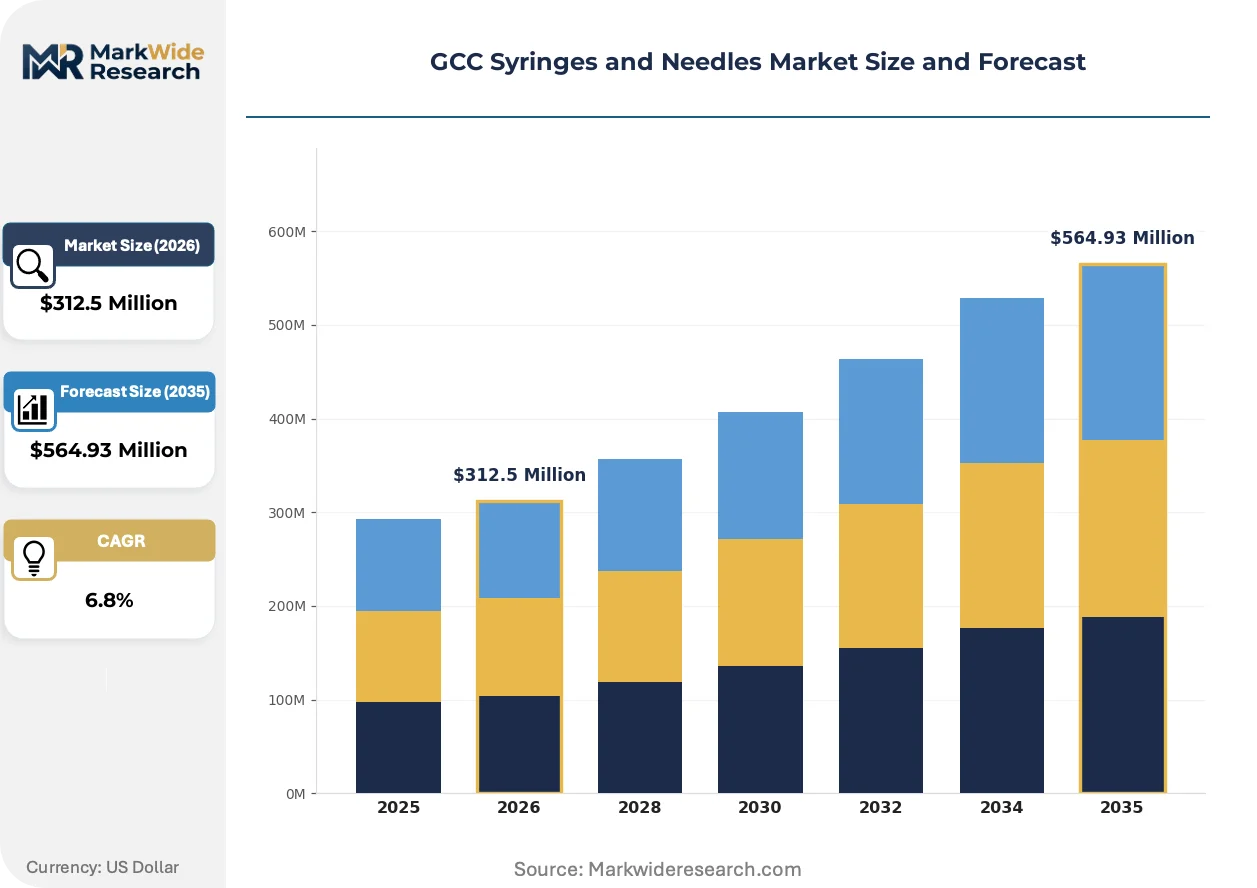
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypodermic Syringes, Insulin Syringes, Tuberculin Syringes, Safety Needles, Intravenous Cannulas Application: Vaccination, Blood Collection, Anesthesia Administration, Diabetes Care, Intramuscular Injection End User: Hospitals, Diagnostic Laboratories, Clinics, Ambulatory Surgical Centers, Blood Banks Packaging Type: Blister Packs, Single Unit Packs, Bulk Packaging, Sterile Sealed Packs |
| Companies Covered | Terumo Corporation, Medtronic plc, Becton, Dickinson and Company, Abu Dhabi Medical Devices Company, Smiths Medical, Nipro Corporation, Baxter International Inc., IBN Sina Medical Factory, B. Braun Melsungen AG, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Syringes and Needles Market Shifts & Advancements
Active needlestick prevention mechanisms and connected drug delivery platforms are reshaping product specifications across GCC procurement channels. Hospital pharmacy directors now prioritize devices with integrated safety features and digital traceability.
Passive safety needle technology is absorbing procurement preference in Saudi tertiary care centers. The mechanism deploys a protective shield upon needle withdrawal without requiring clinician activation. Ministry of Health hospitals in Riyadh and Jeddah have standardized on these devices for phlebotomy and injection procedures, compressing demand for conventional active-safety alternatives that rely on manual thumb activation.
UAE Ministry of Health and Prevention standards now mandate unique device identification traceability for all Class IIa and above syringes and needles entering the Emirates. The regulation requires GS1-compliant barcoding on individual unit packaging, with data submission to the national medical device registry. Dubai Health Authority facilities have accelerated compliance timelines, requiring full traceability implementation by Q1 2026 for all new tenders.
Consolidated purchasing through GCC central medical stores is displacing hospital-level procurement autonomy. Saudi Arabia's National Unified Procurement Company now manages safety-engineered syringe acquisition for all Ministry of Health facilities, aggregating demand into multi-year framework agreements. Kuwait's Central Medical Stores Department and Oman's Ministry of Health Supply Directorate are piloting similar centralization, compressing vendor negotiation leverage and standardizing product specifications across previously fragmented institutional buyers.
GCC Syringes and Needles Market Segmentation
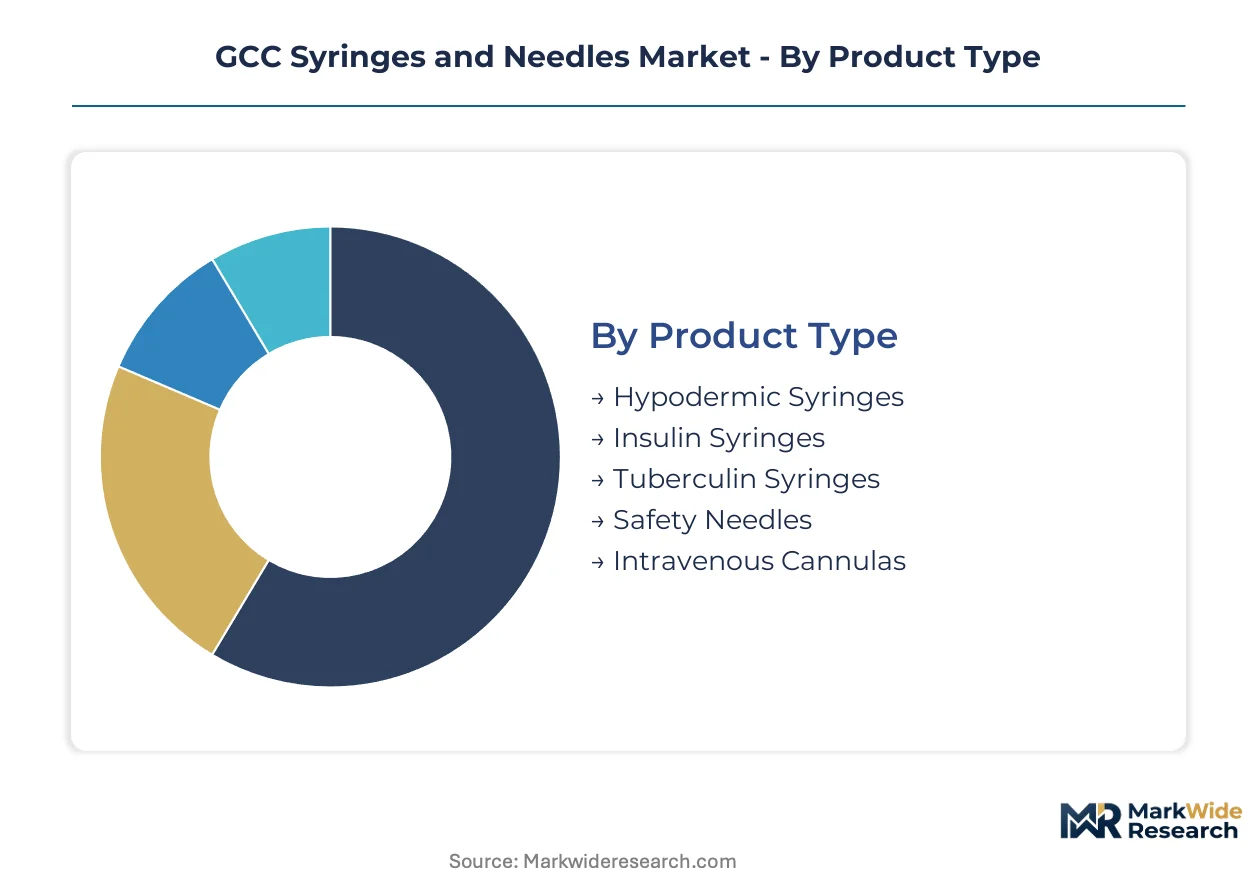
Segmentation in the GCC syringes and needles market reveals distinct procurement behaviors across product specifications, clinical applications, and institutional channels. Each dimension carries unique compliance burdens and margin structures that reshape competitive positioning for manufacturers and distributors.
Product Type:
Cost tier separates routine disposable procurement from premium safety-engineered specifications across GCC hospital networks.
- Hypodermic Syringes:Standard polypropylene barrel construction with latex-free elastomeric plungers dominates high-volume procurement through Saudi Arabia's National Unified Procurement Company. MOH facilities in Riyadh and Jeddah specify these for general injection protocols, though SFDA mandates are accelerating migration toward safety-engineered alternatives.
- Safety Needles:Retractable and shielded cannula designs incorporate passive or active injury prevention mechanisms. UAE Ministry of Health and Prevention standards now require these devices for all phlebotomy and injection procedures in Dubai Health Authority facilities, compressing demand timelines for conventional alternatives.
- Insulin Syringes:Ultra-fine gauge needles with unit-dose calibration serve chronic diabetes management protocols across Kuwait and UAE patient registries.
- Tuberculin Syringes:Low-volume graduated barrels with precision markings support Mantoux testing and allergy diagnostics in Qatar's primary care network.
- Intravenous Cannulas:Teflon or polyurethane catheter-over-needle designs anchor vascular access procedures in Oman's tertiary hospitals.
Hypodermic syringes lead volumes today; safety needles are gaining share fastest.
Application:
Volume throughput and sterility assurance requirements fragment procurement specifications across clinical use cases.
- Vaccination:Single-dose prefilled and disposable formats prioritize cold chain integrity and mass immunization throughput. Qatar's national immunization drives and Oman's expanded childhood vaccination schedules aggregate demand into multi-million unit tenders with stringent sterility documentation.
- Diabetes Care:Recurring daily injection protocols sustain insulin delivery device consumption across UAE and Kuwait chronic disease registries. Patient self-administration trends favor pen needles and safety-engineered syringes with reduced activation force.
- Blood Collection:Vacuum tube systems and safety-engineered winged sets support diagnostic laboratory throughput in Saudi Arabia's expanding hospital network.
- Anesthesia Administration:Luer-lock compatibility and high-pressure resistance specifications dominate operating theater procurement in Abu Dhabi's surgical centers.
- Intramuscular Injection:Standard hypodermic configurations serve antibiotic and vaccine delivery across GCC primary care clinics.
Vaccination applications anchor procurement scale; diabetes care is expanding most quickly.
End User:
Centralized purchasing authority versus institutional autonomy reshapes vendor negotiation dynamics across buyer categories.
- Hospitals:Consolidated procurement through Saudi NUPCO and similar centralized medical stores aggregates demand into framework agreements with standardized safety specifications. Tertiary care centers in Riyadh, Jeddah, and Dubai Health Authority facilities drive premium device adoption.
- Diagnostic Laboratories:High-throughput blood collection operations in UAE and Qatar prioritize vacuum tube compatibility and needlestick prevention compliance.
- Clinics:Fragmented primary care networks across Kuwait and Oman rely on distributor stock-and-deliver arrangements with shorter replenishment cycles.
- Ambulatory Surgical Centers:Procedure-specific kits and reduced inventory carrying costs favor pre-sterilized single-unit packaging in Saudi Arabia's growing day-surgery sector.
- Blood Banks:Donor safety protocols and traceability mandates specify large-bore collection sets with integrated sampling ports.
Hospitals concentrate procurement value today; diagnostic laboratories are climbing the fastest.
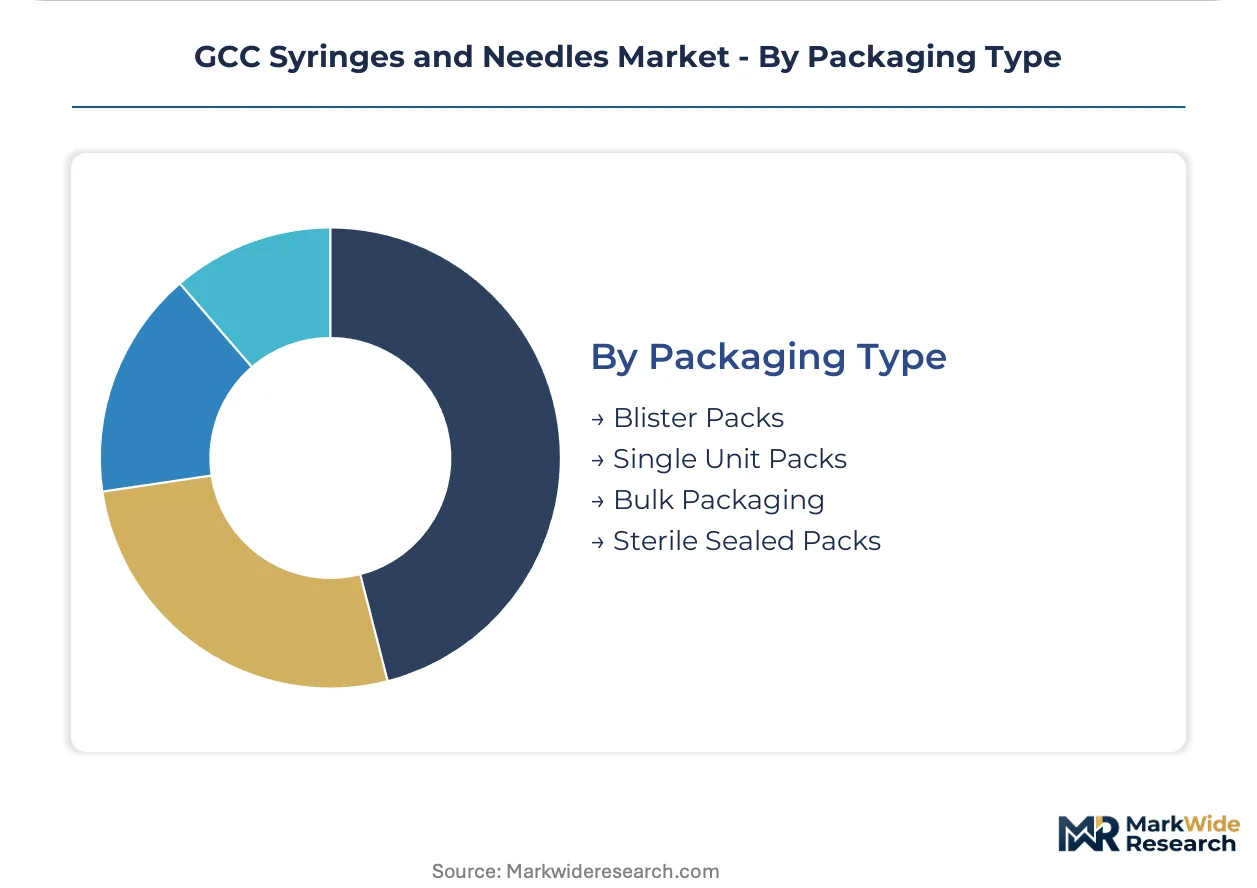
Packaging Type:
Supply chain configuration and sterility validation timelines differentiate procurement economics across packaging formats.
- Single Unit Packs:Individual sterile barrier systems with peel-open aseptic presentation dominate operating theater and emergency department protocols. Dubai Health Authority's Q1 2026 traceability mandates require GS1-compliant barcoding on these units.
- Sterile Sealed Packs:Multi-layer pouch construction with ethylene oxide sterilization certificates supports extended shelf life requirements for strategic stockpiling in Saudi Arabia's central medical stores.
- Blister Packs:Thermoformed tray formats with Tyvek lidding serve retail pharmacy and home healthcare distribution channels across UAE.
- Bulk Packaging:Unsterilized component shipments for in-house sterilization remain limited to industrial converters participating in Saudi localization programs.
Single unit packs dominate hospital procurement today; sterile sealed packs are gaining preference fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production localization incentives in Saudi Arabia are narrowing the cost-of-compliance gap that historically favored Asian imports. GCC states now compete for medical device manufacturing investment through tender preferences and customs relief. Hospital procurement centralization is redistributing demand concentration across the region's healthcare infrastructure.
Saudi Arabia
Safety-engineered device mandates from the Saudi Food and Drug Authority are accelerating replacement cycles across Ministry of Health facilities. The National Unified Procurement Company aggregates demand into multi-year framework agreements that favor domestic production. Riyadh and Jeddah tertiary care centers are standardizing on passive safety needle technology for phlebotomy protocols.
United Arab Emirates
Dubai Health Authority's Q1 2026 traceability deadlines are compressing supplier qualification timelines for GS1-compliant barcoding. The UAE Ministry of Health and Prevention mandates unique device identification for all Class IIa syringes and needles entering the Emirates. Abu Dhabi's medical device manufacturing zone anchors regional production ambitions with government-backed localization incentives.
Kuwait
Expanding diabetes patient registries sustain recurring demand for insulin delivery devices across chronic disease management protocols. The Central Medical Stores Department is piloting consolidated purchasing frameworks that mirror Saudi Arabia's centralization model. Kuwait City hospital networks prioritize pen needles and safety-engineered syringes with reduced activation force for self-administration.
Qatar
National immunization drives aggregate disposable syringe demand into multi-million unit tenders with stringent sterility documentation. The Ministry of Public Health prioritizes single-use sterility standards for expanded childhood vaccination schedules. Doha's diagnostic laboratory cluster drives vacuum tube system procurement for high-throughput blood collection operations.
Oman
The Ministry of Health Supply Directorate is piloting centralized procurement standardization across previously fragmented institutional buyers. Tertiary hospitals in Muscat specify Teflon and polyurethane intravenous cannulas for vascular access procedures. Government healthcare infrastructure spending is accelerating safety-engineered device adoption in the Sultanate's expanding hospital network.
GCC Syringes and Needles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational safety-technology leaders commanding premium positioning in Saudi and UAE hospital networks. Regional converters compete on cost and delivery speed for government tenders through local manufacturing advantages. Three archetypes dominate: integrated global suppliers with proprietary safety IP, regional fabricators leveraging proximity to central medical stores, and specialist needle-cannula producers dependent on imported stainless steel tubing. Consolidation pressure is intensifying through framework agreement aggregation, while licensing friction from retractable mechanism patent portfolios constrains new entrant expansion.
Among Japanese precision instrument manufacturers, Terumo Corporation and Nipro Corporation exemplify the safety-technology specialist archetype with advanced needlestick prevention portfolios. Becton, Dickinson and Company anchors the integrated multinational tier through extensive distribution networks spanning Saudi Arabia and the UAE. Abu Dhabi Medical Devices Company occupies a position within the regional converter segment, leveraging local production status for tender preference in Emirates government procurement.
| Leading Market Players |
|---|
| Terumo Corporation |
| Medtronic plc |
| Becton, Dickinson and Company |
| Abu Dhabi Medical Devices Company |
| Smiths Medical |
| Nipro Corporation |
| Baxter International Inc. |
| IBN Sina Medical Factory |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Captive sterilization infrastructure anchors pricing power for established manufacturers serving Saudi Arabia's National Unified Procurement Company tenders. In-house ethylene oxide facility qualification compresses launch timelines for domestic producers while imposing 12-18 month barriers on import-dependent competitors, allowing localized converters to command tender preference without margin erosion.
Pricing Analysis
Distributor margin stacking shapes final delivered costs across GCC hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates safety-engineered retractable needles from conventional hypodermic syringes from bulk non-sterile components. Certification tier drives price differentiation, with SFDA prequalified products commanding 15-25% premiums over MOHAP-registered equivalents. Cost compression in the economy tier intensifies because Asian converters flood spot markets with uncertified inventory. Government tenders exhibit lowest price sensitivity; retail pharmacy channels show highest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese precision stainless steel tubing foundries supplying needle cannula blanks. GCC converters draw from South Korean and Chinese petrochemical suppliers for medical-grade polypropylene barrels, with Thai and Malaysian latex-free elastomer sources feeding plunger production. Tariff exposure compounds freight cost volatility for European needle inputs. Distribution runs through centralized medical stores in Riyadh, Dubai, and Kuwait City, displacing hospital-level procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC syringes and needles market compounds steadily through chronic disease prevalence and regulatory ratcheting on sharps injury prevention. Government healthcare infrastructure spending across the Kingdom and Emirates locks in replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anticipate patent cliff pressure on retractable needle IP portfolios as first-generation safety mechanisms face compulsory licensing threats in Saudi localization programs. Deepen backward integration into polypropylene compounding at Jubail Industrial City to defend margin position against Asian import volatility. Secure multi-year framework agreements with NUPCO before Kuwait and Oman centralize procurement. For New Entrants and Emerging Players: Distributor partnerships with established hospital supply houses offer the fastest path to tender qualification without sterilization facility capital. Target Oman's Ministry of Health Supply Directorate pilot program, where centralization creates vendor churn and specification gaps. Position on patient-friendly safety needles with reduced activation force for Kuwait's expanding diabetes self-administration segment. For Investors and Strategic Acquirers: Roll-up economics work for regional converters with sterilization assets because GCC harmonization will consolidate fragmented national registration requirements into single-entry pathways. Five-to-ten year viability hinges on Gulf Centralized Procedure implementation pace. Watch SFDA enforcement intensity on non-safety devices as the signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Safety-Engineered Device Localization | Saudi tender preference and customs relief reward domestic ethylene oxide sterilization capacity. |
| GS1 Traceability Compliance | Dubai Health Authority mandates compress supplier qualification timelines for Emirates market access. |
| Passive Safety Needle R&D | Riyadh and Jeddah tertiary centers standardize on shielded cannula designs without clinician activation. |
| Central Medical Store Partnership | NUPCO aggregation displaces hospital-level negotiation leverage toward framework agreement capture. |
| Diabetes Self-Administration Focus | Kuwait and UAE patient registries expand faster than population growth for insulin delivery devices. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down medical device import tracking forms the analytical core of this study. Primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committees, and SFDA regulatory affairs specialists combined with secondary validation from SFDA filings, MOHAP medical device registries, GCC customs databases, and National Unified Procurement Company tender documentation. Triangulation between demand-side consumption patterns and supply-side manufacturing capacity ensures cross-verified volume estimates.
Input-output matrices map safety-engineered syringe adoption rates against diabetes prevalence registries and vaccination program scale-ups across the projection horizon. Segmentation dimensions include product type, clinical application, end-user institution tier, and packaging format. CAGRs derive from regression analysis of historical procurement volumes against regulatory mandate implementation curves. Sterilization facility qualification timelines and biocompatibility testing backlogs inform supply-side constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Gulf Centralized Procedure delays and polypropylene feedstock price volatility. Forecasts reflect documented assumptions on regulatory enforcement intensity and localization incentive durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Breast Shells Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Human Acellular Dermis Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Medical Nitrile Gloves Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Auto-Disable Syringes Market