
 Medical Plastics Market | 2026-2036
Medical Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Plastics Market Analysis
Multi-source procurement of medical-grade resins is hardening as device OEMs diversify away from concentrated petrochemical supply. Eastman Chemical Company leverages its copolyester technology leadership to sustain premium positioning in drug-delivery applications. Evonik Industries AG anchors its portfolio through high-performance polyamide specialization for surgical robotics housings. SABIC competes aggressively on polycarbonate scale for diagnostic equipment enclosures across Asian manufacturing hubs.
Medical plastics encompass polymer formulations engineered to meet ISO 10993 biocompatibility standards, with melt-flow indices typically ranging from 5 to 50 g/10 min to accommodate precision injection molding of complex geometries for patient-contact applications. These materials serve primarily to reduce infection risk through disposable instrument design while enabling lightweight, radiolucent alternatives to metal in implantable and diagnostic platforms. Thermoplastics dominate current volume consumption due to reprocessability and weldability advantages in automated assembly lines. Biodegradable plastics represent the fastest-expanding category as European Union Medical Device Regulation (MDR) compliance pressures mount against permanent implant polymers. Injection molding technology captures the largest margin pool given its centrality to high-cavity production of syringe barrels, luer connectors, and inhaler components.
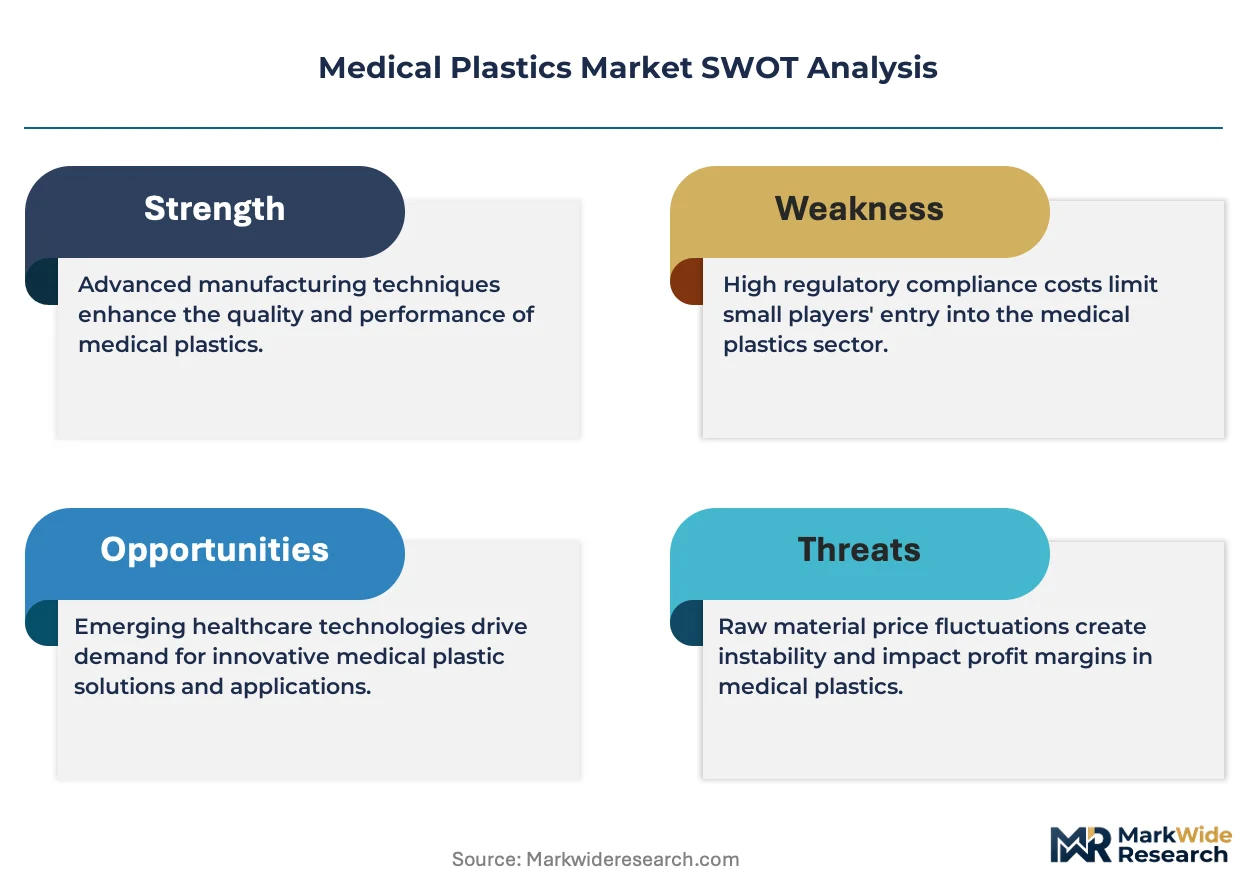
The FDA enforces biocompatibility and sterilization validation requirements under 21 CFR Part 820 quality system regulations, while the EU MDR mandates enhanced clinical evidence for polymer-containing implantable devices. REACH restrictions on phthalate plasticizers and ECHA scrutiny of halogenated flame retardants are reshaping compounder formulation strategies across European supply chains. Stakeholders must monitor evolving EPA per- and polyfluoroalkyl substance (PFAS) regulatory proposals, as fluoropolymer alternatives in catheter and stent coatings face potential phase-out timelines that would disrupt established processing protocols and supplier qualifications.
Market Dynamics
The FDA's updated biocompatibility testing frameworks are accelerating material substitution toward medical-grade thermoplastics while EU MDR compliance pressures intensify against permanent implant polymers. Device OEMs face hardening multi-source procurement requirements as concentrated petrochemical supply creates vulnerability in resin availability for sterile single-use instruments.
Growth Catalysts
- Minimally invasive surgical expansion:Hospitals prioritize single-use sterile instruments to reduce infection risk, driving thermoplastic demand for precision-molded components with melt-flow indices optimized for high-cavity production.
- REACH plasticizer restrictions:ECHA scrutiny of phthalate formulations is reshaping compounder strategies across European supply chains, opening substitution windows for copolyester and polyamide alternatives in drug-delivery platforms.
- Germany precision molding concentration:The Stuttgart cluster anchors specialized converter capacity for high-tolerance implantable components, attracting device OEM qualification programs and sustaining technical know-how density.
Market Restraints
- Petrochemical feedstock volatility:Medical-grade resin pricing tracks naphtha and propylene cost swings, compressing compounder margins during energy price spikes and limiting long-term contract flexibility.
- Fluoropolymer regulatory overhang:EPA PFAS phase-out proposals threaten established catheter and stent coating protocols, forcing premature supplier requalification timelines before alternatives achieve equivalent performance.
- Biodegradable polymer processing limitations:PLA and PHA formulations exhibit narrower thermal windows than conventional thermoplastics, constraining cycle speeds in automated syringe barrel production lines.
Strategic Opportunities
- Indian diagnostic equipment manufacturing:CDSCO streamlined medical device registration is attracting polycarbonate enclosure production for point-of-care platforms serving domestic and export demand.
- Biodegradable implant convergence:EU MDR enhanced clinical evidence requirements for permanent polymers create regulatory tailwinds for resorbable suture anchors and tissue scaffolds in orthopedic applications.
- Surgical robotics housing specialization:High-performance polyamide compounds with laser-direct structuring compatibility enable integrated antenna and sensor architectures in next-generation minimally invasive systems.
Industry Challenges
- ISO 10993-18 chemical characterization expertise:Device sponsors face acute shortages of toxicologists capable of interpreting extractables and leachables data for novel polymer formulations under FDA scrutiny.
- Steam sterilization validation timelines:Gamma and e-beam alternatives require extensive material aging studies, extending time-to-market for implantable devices by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Plastics Market |
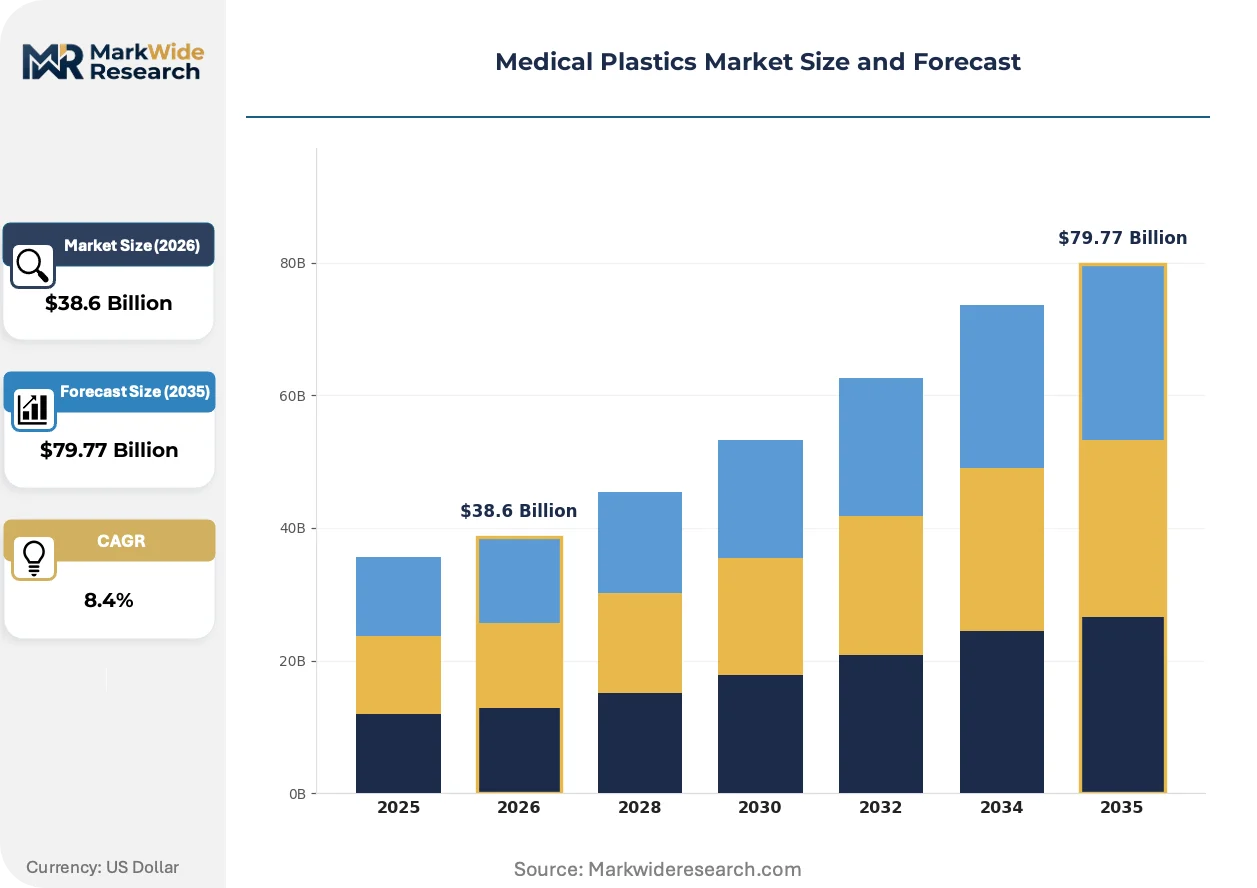
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosetting Plastics, Biodegradable Plastics, Polycarbonate Application: Medical Devices, Drug Delivery Systems, Packaging, Surgical Instruments End User: Hospitals, Clinics, Laboratories, Research Institutes Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | Eastman Chemical Company, Evonik Industries AG, SABIC, Nolato AB, Röchling SE & Co. KG, Celanese Corporation, Solvay S.A., Saint-Gobain Performance Plastics, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Plastics Market Emerging Trajectories
Additive manufacturing of patient-specific surgical guides and fixation plates is reshaping production economics for low-volume orthopedic applications. Polymer formulation houses now integrate 3D printing compatibility into medical-grade resin specifications.
Biodegradable polymer processing is decentralizing implantable device supply chains by enabling point-of-care manufacturing of resorbable scaffolds. Academic medical centers in the Netherlands and Switzerland are piloting hospital-based extrusion and printing of patient-matched craniofacial implants. This technology is compressing logistics costs and cold-chain requirements for temperature-sensitive biopolymer feedstocks.
REACH restrictions on halogenated flame retardants are forcing diagnostic equipment enclosure redesigns across European supply chains. Compounders pivot toward phosphorus-nitrogen intumescent systems in polycarbonate blends, though these formulations demand tighter processing windows. Asian manufacturing hubs serving EU export markets face accelerated reformulation timelines to maintain CE marking validity.
Hospital procurement consolidation is consolidating supplier relationships for standardized consumables. Integrated delivery networks in the United States now mandate single-source contracts for luer connectors and IV components, squeezing regional molders. German university hospitals have established cooperative purchasing pools for polymer-based surgical instruments, shifting volume toward qualified tier-one compounders with validated sterilization documentation.
Medical Plastics Market Segmentation
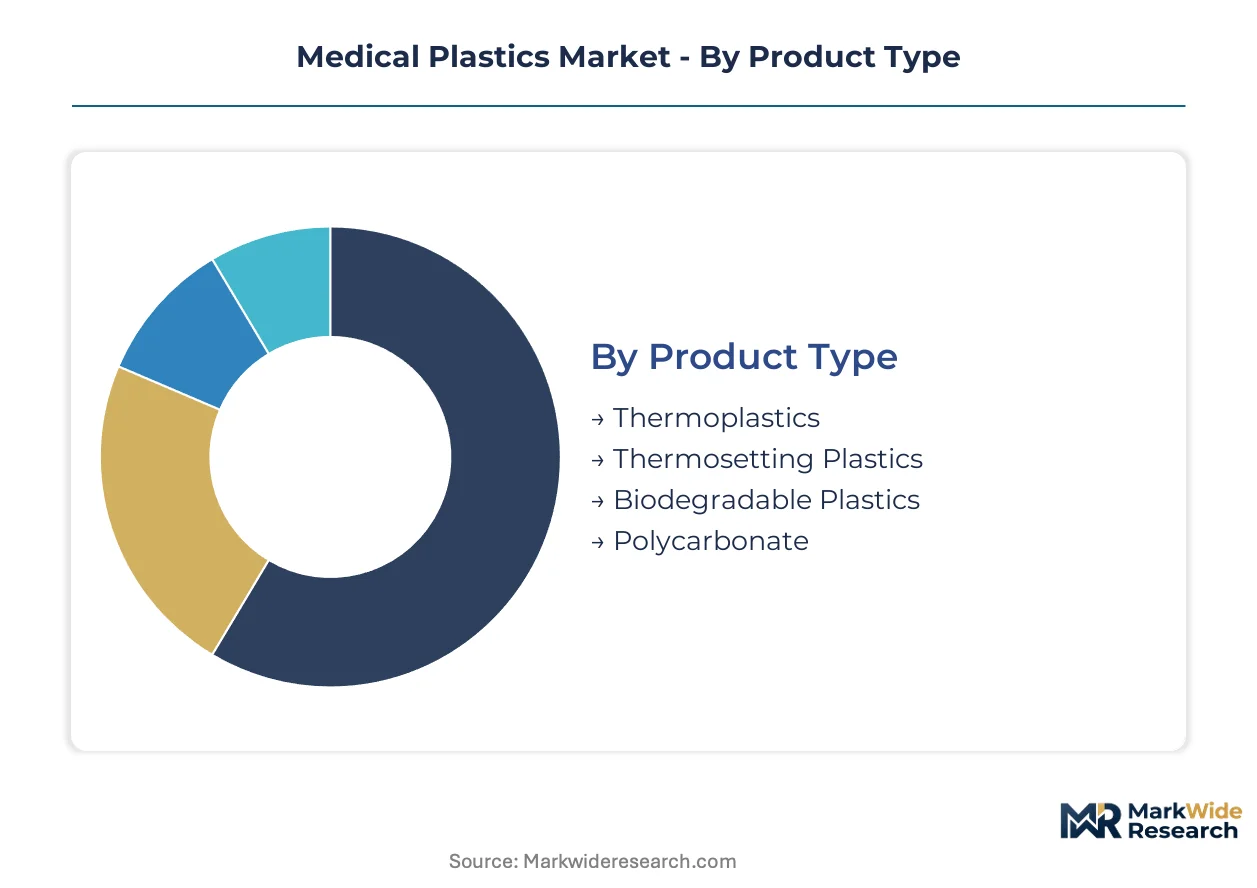
Medical plastics segmentation reflects divergent processing requirements between high-volume disposable consumables and precision-engineered implantable platforms. Material selection cascades through sterilization compatibility, regulatory pathway complexity, and end-use mechanical demands.
Product Type:
Thermoplastics dominate resin consumption by tonnage while biodegradable formulations command premium positioning in resorbable applications.
- Thermoplastics:Medical-grade polypropylene and polyethylene formulations deliver reprocessability and weldability advantages for automated syringe barrel and luer connector production. Hospitals across Germany and the United States prioritize these materials for single-use sterile instrument programs under FDA and EU MDR compliance frameworks.
- Biodegradable Plastics:PLA and PHA polymers enable resorbable suture anchors and tissue scaffolds that eliminate secondary removal surgeries. EU MDR enhanced clinical evidence requirements for permanent implants are accelerating qualification timelines for these formulations in orthopedic applications across Switzerland and the Netherlands.
- Thermosetting Plastics:Cross-linked silicone and epoxy systems provide dimensional stability for implantable pacemaker headers and diagnostic equipment structural components.
- Polycarbonate:Optical clarity and impact resistance position this material for diagnostic equipment enclosures and surgical lighting diffusers in point-of-care platforms.
Mature deployment sits with thermoplastics in standardized consumables. Newer deployment is concentrated in biodegradable plastics for patient-specific resorbable implants.
Application:
Application segmentation tracks the infection risk hierarchy from sterile single-use instruments to permanent implantable devices.
- Medical Devices:Catheters, stents, and implantable ports demand fluoropolymer and thermoplastic elastomer formulations with validated extractables profiles under ISO 10993-18 chemical characterization protocols. FDA biocompatibility testing framework updates are accelerating material substitution timelines for catheter coatings.
- Surgical Instruments:Single-use forceps, retractors, and trocars utilize glass-filled polypropylene for rigidity without metallic artifact generation in MRI environments. German university hospital cooperative purchasing pools are consolidating volume toward qualified tier-one compounders with validated sterilization documentation.
- Drug Delivery Systems:Copolyester and cyclic olefin polymer formulations provide moisture barrier properties for inhaler canisters and pre-filled syringe barrels.
- Packaging:Multilayer barrier films and rigid trays protect sterile device integrity through distribution cold chains.
Volume concentration aligns with medical devices. Steepest expansion trajectory is emerging in surgical instruments as procurement consolidation favors standardized disposable platforms.
End User:
End user segmentation captures divergent specification intensity between acute care facilities and research-oriented institutions.
- Hospitals:Integrated delivery networks in the United States mandate single-source contracts for IV components and luer connectors, consolidating supplier relationships toward compounders with validated sterilization documentation and batch traceability systems.
- Clinics:Ambulatory surgical centers prioritize cost-optimized polypropylene formulations for routine procedure kits with abbreviated regulatory pathways.
- Laboratories:Diagnostic consumables demand optical-grade polycarbonate and cyclic olefin copolymers for microplate and cuvette applications.
- Research Institutes:Academic medical centers in the Netherlands and Switzerland pilot hospital-based extrusion of patient-matched resorbable scaffolds, compressing logistics costs for temperature-sensitive biopolymer feedstocks.
Procurement scale concentrates with hospitals. Technology adoption leadership resides in research institutes pioneering point-of-care manufacturing models.
Technology:
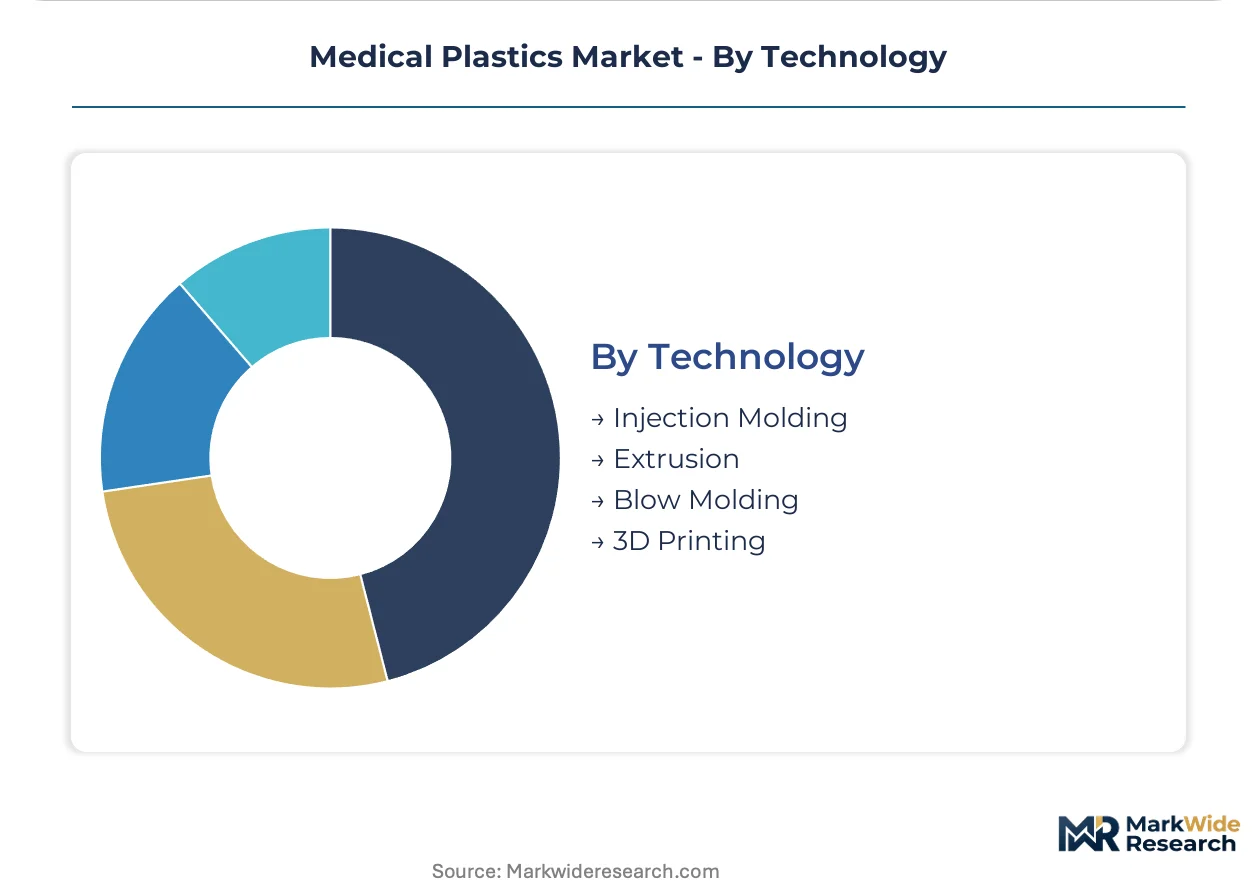
Technology segmentation reflects the margin hierarchy between high-cavity automated molding and emerging additive platforms.
- Injection Molding:High-cavity tooling for syringe barrels and inhaler components captures the largest margin pool in medical plastics processing, with Stuttgart-area precision molders anchoring specialized capacity for high-tolerance implantable components.
- 3D Printing:Patient-specific surgical guides and craniofacial fixation plates are decentralizing orthopedic supply chains through point-of-care manufacturing, with academic medical centers piloting hospital-based production to eliminate cold-chain logistics for biopolymer feedstocks.
- Extrusion:Continuous profile production serves catheter shaft and tubing applications with tight dimensional tolerances.
- Blow Molding:Pharmaceutical bottle and container production utilizes barrier-enhanced polyethylene terephthalate formulations.
Process maturity centers on injection molding. Capability expansion is concentrating in 3D printing as polymer formulation houses integrate additive compatibility into medical-grade resin specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast and polymer compounding expertise in Germany's industrial belt anchor regional supply capabilities for medical-grade resin production.
United States
Minimally invasive surgical device OEMs and diagnostic equipment manufacturers drive thermoplastic consumption across the Midwest and Southeast. FDA 21 CFR Part 820 quality system regulations enforce biocompatibility validation timelines that favor established compounders with sterilization documentation. The Gulf Coast petrochemical corridor supplies propylene and ethylene feedstocks to medical-grade polypropylene producers serving syringe barrel and IV component molders.
Germany
Precision implantable component demand from Swiss and Dutch device manufacturers concentrates converter activity in the Stuttgart region. EU MDR enhanced clinical evidence requirements accelerate material substitution toward medical-grade thermoplastics with established biocompatibility profiles. The Baden-Württemberg molding cluster sustains technical know-how density for high-tolerance surgical robotics housings and drug-delivery platforms.
China
Domestic diagnostic equipment production and export-oriented contract manufacturing expand polycarbonate consumption for point-of-care enclosures. NMPA medical device registration reforms streamline approval pathways for polymer-containing instruments. The Yangtze River Delta anchors injection molding capacity serving both domestic hospital procurement and Western OEM supply chains.
India
CDSCO streamlined medical device registration attracts polycarbonate enclosure production for diagnostic platforms targeting domestic and Middle Eastern export markets. Ambulatory surgical center expansion in Maharashtra and Karnataka drives polypropylene demand for routine procedure kits. Gujarat's petrochemical complexes supply medical-grade polyethylene formulations to regional converters.
Switzerland
Academic medical centers in Zurich and Basel pioneer hospital-based extrusion of patient-matched resorbable scaffolds from PLA and PHA biopolymers. Swissmedic oversight of implantable devices creates regulatory alignment with EU MDR standards. The Basel biotech corridor attracts biodegradable polymer formulation houses serving orthopedic applications across Alpine markets.
Medical Plastics Market Vendor Landscape
Global majors compete with regional champions across material technology specialization and sterilization validation capabilities. The vendor base stratifies between petrochemical-scale resin producers, specialized medical compounders, and precision conversion houses. Three archetypes dominate: integrated chemical conglomerates with medical-grade certification depth, independent compounders with ISO 10993 testing expertise, and regional molders with hospital procurement relationships. Capacity expansion in Asian manufacturing hubs and backward integration into resin production represent the dominant competitive moves.
Within the integrated chemical tier, Eastman Chemical Company and SABIC occupy positions anchored by copolyester and polycarbonate scale respectively. Evonik Industries AG exemplifies the specialized compounder archetype through its high-performance polyamide focus. These three entities represent divergent strategic postures: petrochemical breadth versus formulation depth versus polymer chemistry specialization.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Evonik Industries AG |
| SABIC |
| Nolato AB |
| Röchling SE & Co. KG |
| Celanese Corporation |
| Solvay S.A. |
| Saint-Gobain Performance Plastics |
| Dow |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in the United States and cooperative purchasing pools at German university hospitals command contract-based long-term offtake agreements that compress margins for regional molders lacking sterilization validation depth. Pricing power concentrates with compounders holding FDA master files and EU MDR technical documentation.
Pricing Analysis
Warranty and validation service bundling separates premium medical-grade resin pricing from unbundled commodity polymer quotes. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 10993 certification tier and batch traceability system sophistication. Price differentiation hinges on sterilization documentation completeness and geographic delivery cost to Stuttgart-area precision molders. Cost compression in standard-grade polypropylene intensifies because Gulf Coast petrochemical overcapacity feeds Asian export competition. Ambulatory surgical centers in India exhibit highest price sensitivity; Swiss orthopedic device OEMs show least.
Supply Chain Analysis
Reverse logistics for temperature-sensitive PLA and PHA biopolymer feedstocks requires cold-chain refurbishment networks from Netherlands academic medical centers back to Basel formulation houses. Medical-grade resin production concentrates in the United States, Germany, and China. Supply chains draw from naphtha and propylene feedstocks, precision molding tooling, and sterilization validation services. Single-source vulnerability in fluoropolymer coatings for catheters threatens established protocols under EPA scrutiny. Distribution runs through compounder-direct relationships with hospital procurement committees and GPO contracts managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical plastics markets are consolidating as EU MDR enhanced clinical evidence requirements force subscale compounders without toxicology expertise toward exit. Regulatory compliance burden favors integrated resin producers with captive sterilization validation capabilities.
For Market Incumbents: Deploy sterilization documentation leverage to secure multi-year sole-source contracts with integrated delivery networks. Anchor capacity expansion in the Stuttgart precision molding cluster to capture Swiss and Dutch orthopedic device OEM qualification programs. Biodegradable polymer substitution threatens conventional thermoplastic positions in resorbable implant applications. For New Entrants and Emerging Players: Laser-direct structuring compatibility in high-performance polyamide compounds offers a technology-first wedge into surgical robotics housing supply chains. Target Indian diagnostic equipment manufacturers seeking polycarbonate enclosure suppliers with CDSCO registration experience. Pursue hospital-based point-of-care manufacturing partnerships with Netherlands academic medical centers as go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors specialized compounders with ISO 10993-18 chemical characterization expertise and established FDA master files. Long-term viability centers on resorbable polymer formulation capabilities aligned with EU MDR permanent implant restrictions. Monitor EPA PFAS regulatory finalization timing as inflection indicator for fluoropolymer alternative demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive medical-grade polypropylene supply secures margin control for syringe barrel molders facing Gulf Coast feedstock volatility. |
| EU MDR Technical Documentation Investment | Enhanced clinical evidence capabilities accelerate qualification timelines for permanent implant polymer substitutes. |
| Hospital System Partnership | Direct relationships with German university hospital purchasing pools bypass distributor markups on standardized surgical instruments. |
| Biodegradable Polymer Formulation Expansion | PLA and PHA processing expertise captures regulatory tailwinds from EU restrictions on permanent orthopedic implants. |
| Precision Molding Capacity Addition | Stuttgart-region high-tolerance component production attracts Swiss device OEM qualification for implantable platforms. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation databases, and SEC 10-K resin producer disclosures, complemented by interviews with biomedical engineers, hospital GPO contracts managers, compounder technical directors, and sterilization validation specialists. Secondary sources included customs trade data for medical-grade polymer imports, ISO 10993 biocompatibility standard revision records, and REACH restriction impact assessments. Bottom-up demand modeling from syringe barrel and catheter consumption data triangulated against top-down petrochemical feedstock allocation estimates.
Cross-referencing historical price elasticity patterns against expert panel input on regulatory compliance cost trajectories shaped the analytical framework. Segmentation dimensions modeled include material technology tier, sterilization compatibility class, end-use application intensity, and regional regulatory cluster. CAGRs were derived from production capacity expansion announcements weighted against hospital procurement consolidation trends. Industry-specific forecast inputs incorporated EU MDR implementation pace and CDSCO registration reform uptake.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPA PFAS phase-out timelines or sustained propylene feedstock price spikes. Forecasts reflect assumptions about sterilization validation backlog durations and biodegradable polymer processing yield improvements. Practitioners should monitor ECHA restriction proposal advancement and NMPA medical device registration reform implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Combat Dressing Market
Medical Supplies
Global Cleanroom Disposable Gloves Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Trauma Products Market
Medical Supplies
Face Mask Market
Medical Supplies
Global Syringes and Needles Market
Medical Supplies
Transfusion Bottles Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Global Dental Sterilization Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Surgical Glue Market