
 Blood Flow Measurement Devices Market | 2026-2036
Blood Flow Measurement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Flow Measurement Devices Market Intelligence
The direct-to-hospital sales channel for specialized diagnostic equipment is fragmenting as group purchasing organizations gain more influence. This shift challenges established go-to-market strategies. Philips Healthcare leverages its broad portfolio and existing hospital relationships to maintain its position. Medtronic plc focuses on integrating its devices within its broader cardiovascular and surgical ecosystems, while Transonic Systems Inc. specializes in high-precision transit-time flow measurement solutions for research and clinical applications.
Blood flow measurement devices are medical instruments used to quantify the volume rate of blood flow in a vessel, organ, or tissue. These systems often utilize principles like the Doppler effect, with frequencies typically in the 2-10 MHz range for ultrasonic devices, to non-invasively assess hemodynamic status. Doppler Ultrasound systems remain the workhorse in hospitals for general diagnostics, particularly in cardiology. However, Laser Doppler technology is the fastest-growing product segment, finding strong application in specialized vascular surgery and critical care settings.
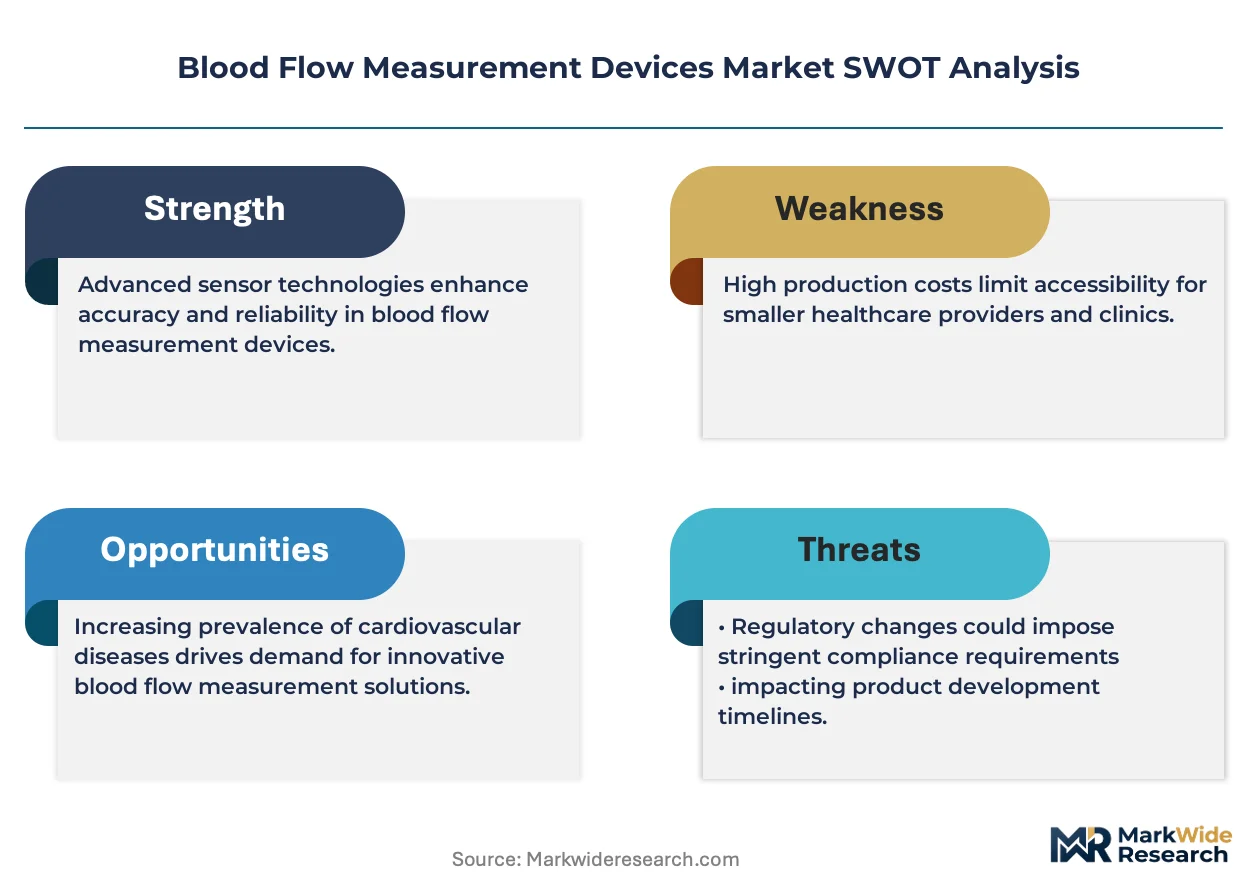
Market access hinges on clearance from bodies like the US FDA and adherence to the EU's Medical Device Regulation (MDR) overseen by notified bodies under the EMA. Compliance with ISO 13485 standards for medical device quality management systems is a prerequisite for most major markets. The key decision for manufacturers will be balancing investment in next-generation non-invasive technologies against the cost of navigating these stringent, multi-jurisdictional regulatory pathways.
Market Dynamics
The central force shaping the market is the technological transition from invasive measurement techniques to non-invasive diagnostic modalities. This shift, led by advancements in Laser Doppler and high-frequency ultrasonic systems, prioritizes patient safety and diagnostic accuracy, compelling a re-evaluation of clinical workflows.
Growth Catalysts
- Advanced Technology Adoption:The adoption of Laser Doppler flowmetry in specialized fields like vascular surgery and critical care enhances diagnostic precision for microcirculation assessment, driving segment-specific growth.
- Cardiovascular Disease Prevalence:A rising incidence of chronic cardiovascular and peripheral artery diseases, particularly within the aging populations of developed nations like Germany, sustains high demand for routine blood flow diagnostics in hospitals.
- Wearable Device Integration:The emergence of wearable, continuous monitoring devices for at-risk patients creates a new avenue for data collection outside of traditional clinical settings, supporting telehealth and remote patient management initiatives.
Market Restraints
- High Equipment Cost:The significant capital investment required for advanced transit-time ultrasonic and Laser Doppler systems can be a substantial barrier for smaller clinics, community hospitals, and healthcare systems in developing economies.
- Technical Limitations:Ultrasonic devices can face limitations in signal penetration and accuracy in obese patients or through calcified vessels, which can impede reliable diagnostic outcomes and limit their universal applicability.
- Stringent Regulatory Hurdles:The rigorous clinical evidence and documentation requirements mandated by regulatory bodies, notably the EU's Medical Device Regulation (MDR), create lengthy and expensive pathways to market approval.
Strategic Opportunities
- Expansion in Emerging Markets:Untapped opportunities exist in regions such as Latin America and Southeast Asia, where increasing healthcare expenditure and infrastructure development are creating new markets for diagnostic equipment.
- Neurological Monitoring Applications:There is significant potential for applying blood flow measurement technology to neurology, specifically for monitoring cerebral blood flow in stroke patients, traumatic brain injury cases, and during neurosurgery.
- AI and Predictive Analytics:Integrating blood flow data with artificial intelligence platforms offers an opportunity to develop predictive diagnostic tools that can identify patients at high risk of adverse cardiovascular events before symptoms manifest.
Industry Challenges
- Skilled Technician Shortage:A persistent shortage of sonographers and clinical technicians proficient in operating advanced Doppler and laser-based systems can limit the effective utilization of these technologies in healthcare facilities.
- Data Integration Complexity:Ensuring seamless integration of new measurement devices with legacy hospital information systems (HIS) and electronic health record (EHR) platforms presents a significant technical and logistical challenge for IT departments.
- Cybersecurity Compliance:Manufacturers face the ongoing challenge of updating device software and network protocols to protect against evolving cybersecurity threats and comply with stringent data privacy regulations like HIPAA in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Flow Measurement Devices Market |
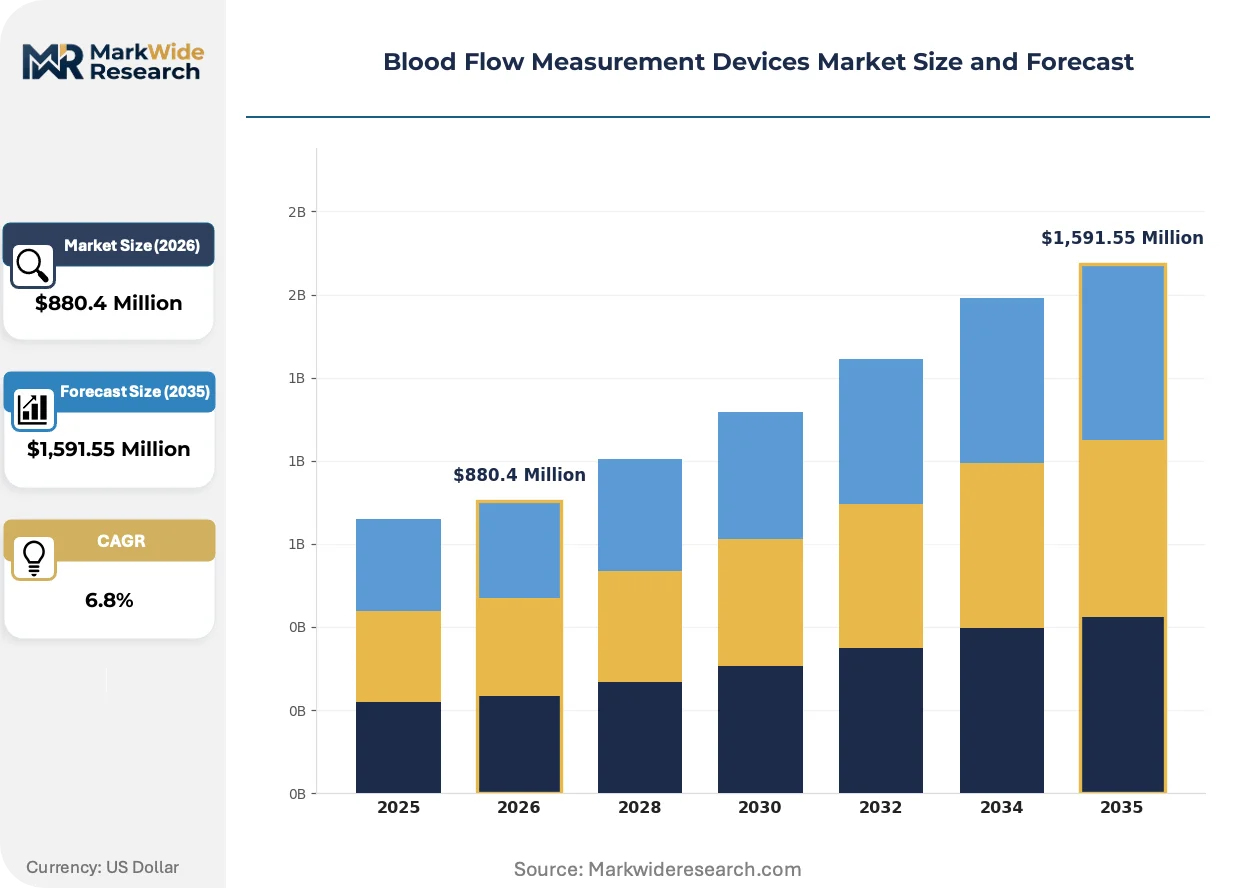
| Market Size in 2026 | $880.4 Million |
| Market Size in 2035 | $1,591.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Doppler Ultrasound, Electromagnetic Flowmeter, Thermal, Ultrasonic, Laser Doppler Application: Cardiology, Neurology, Vascular Surgery, Critical Care, Research Laboratories End User: Hospitals, Diagnostic Centers, Clinics, Academic Institutions, Rehabilitation Centers Technology: Transit-Time, Continuous Wave, Pulsed Wave, Spectral, Volume Flow Measurement |
| Companies Covered | Philips Healthcare, Edwards Lifesciences Corporation, Medtronic plc, Cook Medical Inc., Terumo Corporation, GE Healthcare, Canon Medical Systems Corporation, Transonic Systems Inc., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Flow Measurement Devices Market Strategic Shifts & Innovations
The evolution of blood flow measurement devices is defined by the convergence of miniaturization, wireless connectivity, and data analytics. This creates a push towards systems that offer not just measurement but also interpretation and integration into broader patient care ecosystems, influenced heavily by regulatory demands for performance and safety.
Wearable continuous blood flow monitors are gaining traction, often using principles like photoplethysmography. These devices are being adopted primarily for remote patient monitoring applications and within academic clinical research. This development is hybridizing clinical-grade diagnostics with consumer-facing wellness technology, creating a new market space for medical-grade wearables that provide longitudinal hemodynamic data.
The European Union's Medical Device Regulation (MDR) has fundamentally altered the compliance landscape by demanding more robust clinical evidence and post-market surveillance. This regulation forces manufacturers to generate and maintain extensive technical documentation and clinical data throughout the device lifecycle. Consequently, companies producing blood flow meters for the EU market are reinvesting heavily in clinical studies and quality management systems to retain their CE marking.
A notable demand-side shift involves the move away from single capital equipment purchases toward more flexible procurement models. This trend disrupts the traditional direct sales channel, as large hospital networks increasingly prefer managed equipment services or subscription-based agreements that bundle device access with maintenance and technology upgrades. This pattern is particularly evident in North America and Western Europe, where healthcare providers seek to optimize lifecycle cost management.
Blood Flow Measurement Devices Market Segmentation
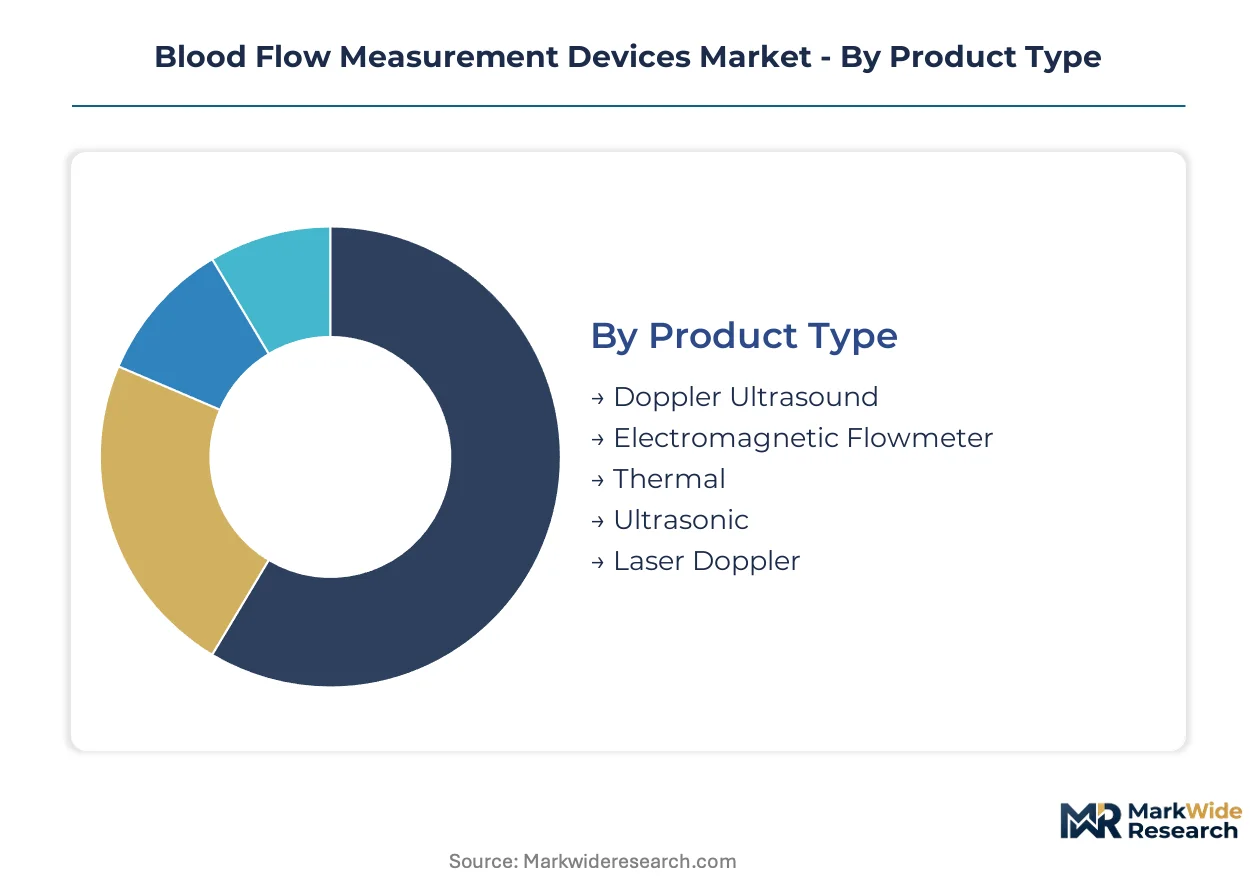
The Blood Flow Measurement Devices market structure reflects diverse technological approaches and specialized clinical applications. Understanding these distinct segments allows manufacturers to tailor product development, regulatory strategies, and market access initiatives effectively. Each segment addresses specific clinical needs and operational environments within healthcare systems.
Product Type:
The intensity of after-sales service requirements often correlates with the complexity and precision demands of each product type.
- Doppler Ultrasound:These devices utilize the Doppler effect, typically operating in the 2-10 MHz frequency range, to non-invasively assess hemodynamic status. Demand concentrates within cardiology departments for general diagnostics, driven by chronic cardiovascular disease prevalence.
- Laser Doppler:Microcirculation assessment in specialized fields like vascular surgery and critical care relies on Laser Doppler technology. This segment experiences rapid growth due to its enhanced diagnostic precision and non-invasive nature.
- Electromagnetic Flowmeter:Electromagnetic flowmeters measure blood flow by detecting voltage induced by blood moving through a magnetic field.
- Thermal:Thermal blood flow measurement devices quantify flow based on heat dissipation from a heated sensor.
- Ultrasonic:General ultrasonic devices provide non-invasive imaging and flow assessment, serving various diagnostic purposes.
By volume, Doppler Ultrasound leads. By growth pace, Laser Doppler is ahead.
Application:
Application focus dictates the specific technical specifications and clinical validation required for blood flow measurement devices.
- Cardiology:This application involves routine diagnostics and monitoring of hemodynamic status in patients with heart conditions. High demand stems from the rising incidence of chronic cardiovascular diseases, particularly in aging populations.
- Vascular Surgery:Specialized procedures in vascular surgery require precise microcirculation assessment, often using advanced Laser Doppler technology. This sector benefits from advanced technology adoption for enhanced diagnostic accuracy.
- Neurology:Neurological applications focus on monitoring cerebral blood flow in conditions like stroke and traumatic brain injury.
- Critical Care:Critical care settings use these devices for continuous patient monitoring and hemodynamic management.
- Research Laboratories:Academic and pharmaceutical research laboratories employ blood flow measurement devices for experimental studies.
Cardiology commands the largest share, while Vascular Surgery exhibits strong expansion.
End User:
The customer type significantly influences procurement models and device integration requirements across the healthcare landscape.
- Hospitals:Hospitals represent the primary end-users, integrating a broad range of blood flow measurement devices for general diagnostics and specialized procedures. Their extensive networks and patient volumes sustain consistent demand for both workhorse and advanced systems.
- Diagnostic Centers:These centers specialize in outpatient testing and advanced imaging, requiring efficient and accurate blood flow measurement solutions. Demand here is driven by the need for specialized services and rapid patient throughput.
- Clinics:Smaller clinics utilize more compact and cost-effective blood flow measurement devices for basic screening.
- Academic Institutions:Universities and research institutions employ these devices for teaching, training, and clinical studies.
- Rehabilitation Centers:Rehabilitation centers may use blood flow monitoring to assess recovery and therapeutic efficacy.
Demand from Hospitals remains foundational, with emerging opportunities in Diagnostic Centers.
Technology:
The maturity of measurement technology influences development costs, regulatory pathways, and market acceptance.
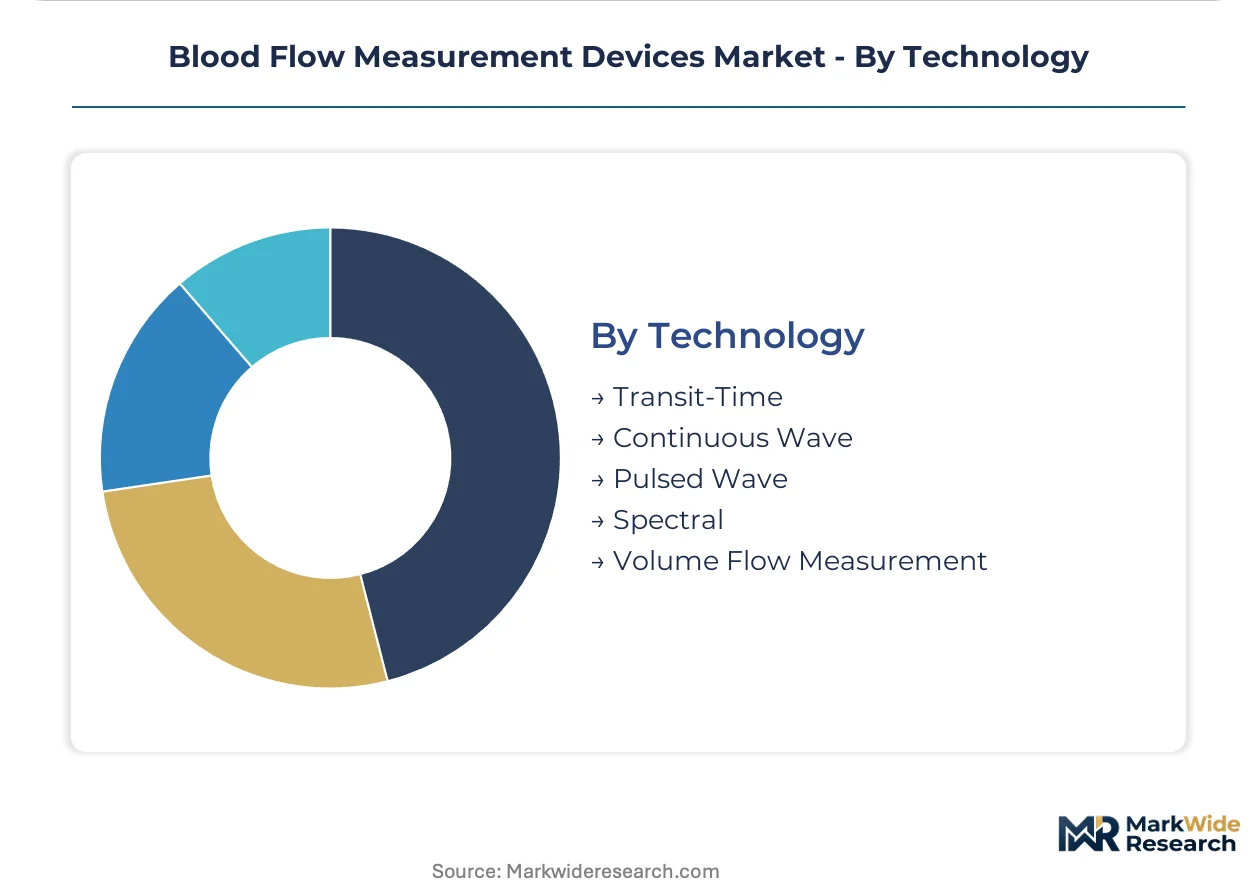
- Transit-Time:Transit-time flow measurement solutions offer high precision and are often used in research and specialized clinical applications requiring accurate volume flow data. These systems are valued for their accuracy in complex fluid dynamics.
- Continuous Wave:Continuous wave Doppler technology provides simpler, qualitative blood flow assessment, primarily used for routine screening and basic diagnostic evaluations. This technology offers cost-effectiveness for general diagnostic purposes.
- Pulsed Wave:Pulsed wave Doppler allows for depth-specific velocity measurements within a vessel.
- Spectral:Spectral Doppler provides detailed flow velocity information over time, aiding in the diagnosis of vascular conditions.
- Volume Flow Measurement:This category encompasses technologies focused on quantifying the total volume of blood flowing through a vessel.
Continuous Wave is a mature technology, whereas Transit-Time is gaining significant traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global blood flow measurement devices market leverages extensive healthcare infrastructure, including advanced hospital networks and research institutions, to facilitate diagnostic innovation and patient care. This infrastructure supports the integration of sophisticated technologies, driving market expansion in regions with high medical expenditure and technological adoption.
United States
High incidence of cardiovascular diseases and a strong emphasis on preventive care drive demand for blood flow measurement devices in the United States. US FDA clearance for medical devices ensures product safety and efficacy, shaping market access. The Greater Boston medical device cluster continues to foster innovation in non-invasive diagnostic technologies.
Germany
An aging population and an extensive network of specialized vascular surgery centers sustain demand for advanced blood flow diagnostics in Germany. Adherence to the EU's Medical Device Regulation (MDR) mandates rigorous clinical evidence for market entry. Bavaria's medical technology hub promotes research and development in precision instruments.
China
Expanding healthcare expenditure and increasing prevalence of chronic diseases contribute to significant market growth for blood flow measurement devices in China. NMPA approval processes regulate new product introductions and market access. The Yangtze River Delta region supports a robust ecosystem for medical device manufacturing and distribution.
Japan
Japan's rapidly aging population and strong emphasis on advanced medical technology drive demand for high-precision blood flow measurement solutions. PMDA oversight ensures device safety and efficacy, maintaining high-quality standards. Tokyo's medical technology firms focus on miniaturization and integrated diagnostic systems.
India
Growing patient populations and government initiatives aimed at improving healthcare access expand the market for blood flow measurement devices in India. The CDSCO regulates medical device imports and local manufacturing, influencing market dynamics. Bengaluru's burgeoning med-tech sector attracts investment in advanced diagnostic solutions.
Blood Flow Measurement Devices Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing specialized sensors and software. The competitive landscape for blood flow measurement devices exhibits a tiered structure, with large, diversified healthcare technology companies alongside focused innovators. Companies frequently engage in portfolio diversification and strategic partnerships to expand their market reach and technological capabilities.
Within the diversified healthcare technology sector, Philips Healthcare and Medtronic plc represent major conglomerates offering broad portfolios that integrate blood flow measurement devices into larger diagnostic and therapeutic ecosystems. Transonic Systems Inc., in contrast, exemplifies a specialized innovator, focusing on high-precision transit-time flow measurement solutions for niche research and clinical applications. These companies anchor different segments of the market, from comprehensive hospital solutions to highly technical laboratory instruments.
| Leading Market Players |
|---|
| Philips Healthcare |
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Cook Medical Inc. |
| Terumo Corporation |
| GE Healthcare |
| Canon Medical Systems Corporation |
| Transonic Systems Inc. |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Under-capacity in advanced sensor manufacturing for Laser Doppler systems drives both supplier behavior and pricing posture for high-precision blood flow measurement devices. This utilization level directly influences component availability and final product costs for manufacturers.
Pricing Analysis
Volume-based discount tiering characterizes pricing for blood flow measurement devices, particularly for large hospital networks and group purchasing organizations. Price differentiation stems from device precision and the inclusion of comprehensive after-sales service and software integration. Pricing softness affects general diagnostic ultrasonic devices due to increased competition and standardization. Hospitals, requiring extensive device portfolios, are generally less price-sensitive for critical care systems than smaller clinics acquiring basic screening tools.
Supply Chain Analysis
Single-source vulnerability for specialized microelectronics and optical components presents a significant supply chain risk for advanced blood flow measurement devices. Supply concentration for these critical inputs often resides in East Asian manufacturing hubs and specific European precision engineering centers. Device manufacturers rely on medical-grade plastics and advanced sensor arrays. Distribution runs through established direct-to-hospital channels and increasingly through managed equipment service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption driven by the technological inflection towards advanced non-invasive diagnostic modalities. The transition from invasive techniques to Laser Doppler and high-frequency ultrasonic systems redefines clinical workflows.
For Market Incumbents: Build ecosystem integration moats by embedding blood flow measurement devices within broader cardiovascular and surgical platforms. Incumbents like Medtronic plc should deepen software integration with hospital information systems to counter fragmentation from group purchasing organizations. Investment in next-generation non-invasive technologies provides a lever against emerging specialized competitors. Consolidating smaller innovators with niche expertise can further fortify market position.
For New Entrants and Emerging Players: Specialized vascular surgery applications in emerging markets like Southeast Asia represent a penetrable entry point for focused innovators. New players should target specific clinical needs where Laser Doppler technology offers superior diagnostic precision. A go-to-market angle focusing on cost-effective, high-precision devices with streamlined regulatory pathways can attract diagnostic centers. Developing AI-powered predictive analytics for microcirculation assessment offers a distinct value proposition.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized innovators with proprietary non-invasive technologies and strong regulatory compliance records. The market's long-term viability, spanning five to ten years, favors companies addressing chronic cardiovascular diseases and neurological monitoring. Acquisition targets should possess robust intellectual property in advanced sensor design or AI integration capabilities. The signal to watch is the accelerated adoption rate of wearable continuous monitoring devices in clinical settings.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Essential for US market access and establishing device safety and efficacy. |
| Hospital System Partnership | Secures long-term procurement agreements and broadens clinical reach. |
| Software Companion Development | Integrates device data with EHRs for enhanced diagnostic utility. |
| CE Marking Pathway | Ensures compliance with EU MDR for market entry across Europe. |
| Reimbursement Strategy | Critical for patient access and commercial viability in key markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis, combining primary interviews with extensive secondary validation. Clinicians, hospital purchasing committee members, R&D directors, and regulatory affairs specialists provided critical insights. Secondary data sources included regulatory body filings (US FDA, EU MDR), peer-reviewed medical literature, and national health statistics. This approach facilitated robust bottom-up and top-down triangulation of market dynamics.
The calibration approach involved iterative adjustments to an integrated analytical framework, modeling market volume and value across the analysis window. Segmentation dimensions included product type, application, end-user, technology, and regional healthcare infrastructure. Compound annual growth rates were derived from historical trends and projected adoption rates. Disease prevalence rates for cardiovascular conditions and healthcare expenditure trends served as key forecast inputs.
Practitioners should monitor shifts in regulatory landscapes and new technology breakthroughs for early signals of market revision. Forecasts inherently reflect assumptions regarding clinical practice evolution and healthcare policy. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Gram Staining System Market