
 Global Endoscopic Ultrasound Needles Market | 2026-2036
Global Endoscopic Ultrasound Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endoscopic Ultrasound Needles Market Foresight
Single-use sterility-grade needle specifications is collapsing the reusable instrument segment across premium hospital procurement channels. Boston Scientific Corporation leverages integrated endoscopy platforms to bundle needle sales with imaging systems. Medtronic anchors North American supply through direct sales teams embedded in IDN purchasing committees. Olympus Corporation dominates Asia-Pacific distribution via captive endoscope install bases that lock in needle compatibility.
Endoscopic ultrasound needles are hollow-core instruments manufactured from stainless steel or nitinol alloys, typically 19-25 gauge in diameter, designed for transmural tissue acquisition under real-time sonographic guidance during endoscopic procedures. Their primary purpose enables histological diagnosis of pancreatic, mediastinal, and submucosal lesions without surgical intervention. Fine needle aspiration occupies the largest volume share among product types due to established reimbursement codes for cytological sampling procedures. Fine needle biopsy segments grow fastest as pathology laboratories shift toward core tissue requirements for immunohistochemistry and molecular profiling panels. Hospitals capture the dominant end-user value pool given capital equipment ownership and bundled procedure economics.
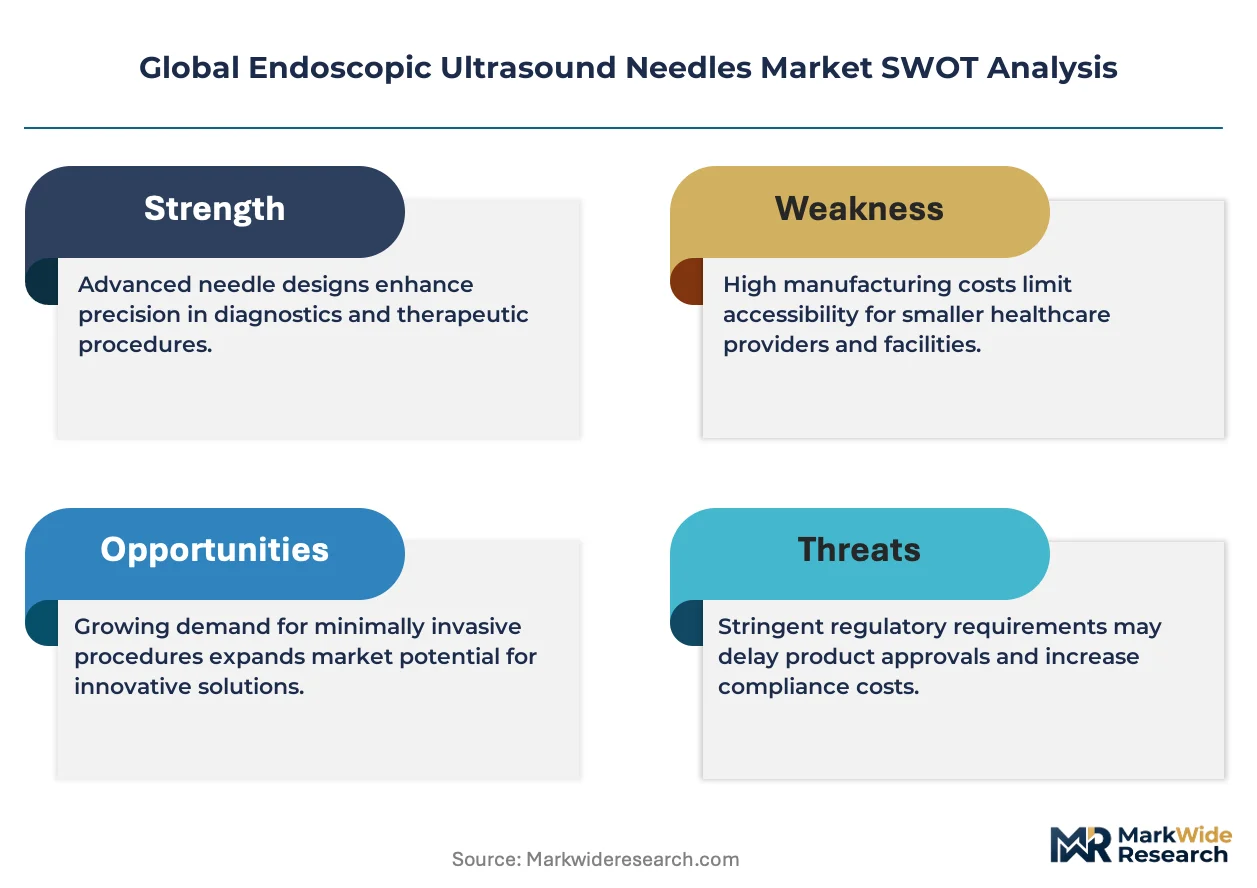
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards govern needle biocompatibility, sterility assurance, and traceability mandates that extend product development cycles. ISO 13485 quality management systems and Japan PMDA foreign manufacturer registration create layered compliance barriers for new market entrants. Stakeholders must monitor evolving NCCN guideline recommendations on sampling adequacy thresholds that directly influence hospital needle specification decisions and manufacturer R&D priorities.
Market Dynamics
Single-use sterility mandates are compressing reusable needle margins while accelerating capital rotation toward disposable platforms across tertiary hospital procurement channels.
Growth Catalysts
- Fine Needle Biopsy Transition:Pathology laboratories in the United States and Germany now require core tissue specimens for immunohistochemistry panels, pulling hospitals toward larger-gauge biopsy needles over traditional aspiration devices.
- EU MDR Streamlining:Harmonized technical documentation standards across European member states reduce redundant conformity assessments, accelerating product registration timelines for manufacturers with established ISO 13485 systems.
- Pancreatic Lesion Screening:Expanded NCCN guideline recommendations for early-stage pancreatic cyst surveillance drive procedural volume in gastroenterology departments across Japan and the United States.
Market Restraints
- Nitinol Alloy Cost Volatility:Superelastic nickel-titanium supply concentrates among a limited set of specialty metallurgy suppliers, exposing manufacturers to raw material price swings that compress gross margins on high-flexibility needle designs.
- Japan PMDA Foreign Manufacturer Registration:Extended audit timelines and mandatory in-country representation requirements create structural barriers for new entrants lacking established Japanese distribution partnerships.
- Reusable Instrument Residual Demand:Cost-constrained outpatient surgical centers in India and Brazil continue sterilizing and redeploying metal needle sets, delaying full conversion to single-use economics in price-sensitive segments.
Strategic Opportunities
- India Tertiary Hospital Expansion:Government-funded medical college hospital upgrades under the PLI scheme for medical devices create first-mover advantages for suppliers establishing direct sales infrastructure in Mumbai, Delhi, and Bangalore.
- Integrated EUS-ERCP Platforms:Convergence of diagnostic needle sampling with therapeutic biliary drainage procedures enables bundled procedure pricing that captures greater share of per-patient revenue in interventional gastroenterology suites.
- Medicaid Reimbursement Expansion:Proposed CMS coding updates for EUS-guided tissue acquisition would extend coverage to community hospital settings previously excluded from adequate procedural reimbursement.
Industry Challenges
- Interventional Endoscopist Training Pipeline:Fellowship programs in the United States and Germany graduate insufficient specialists to match procedural volume growth, creating scheduling bottlenecks that limit needle utilization per installed base.
- ISO 13485 Certification Timeline:Notified body backlogs extend quality management system audits to 14-18 months, delaying product launches for manufacturers awaiting updated certificates under EU MDR transition deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endoscopic Ultrasound Needles Market |
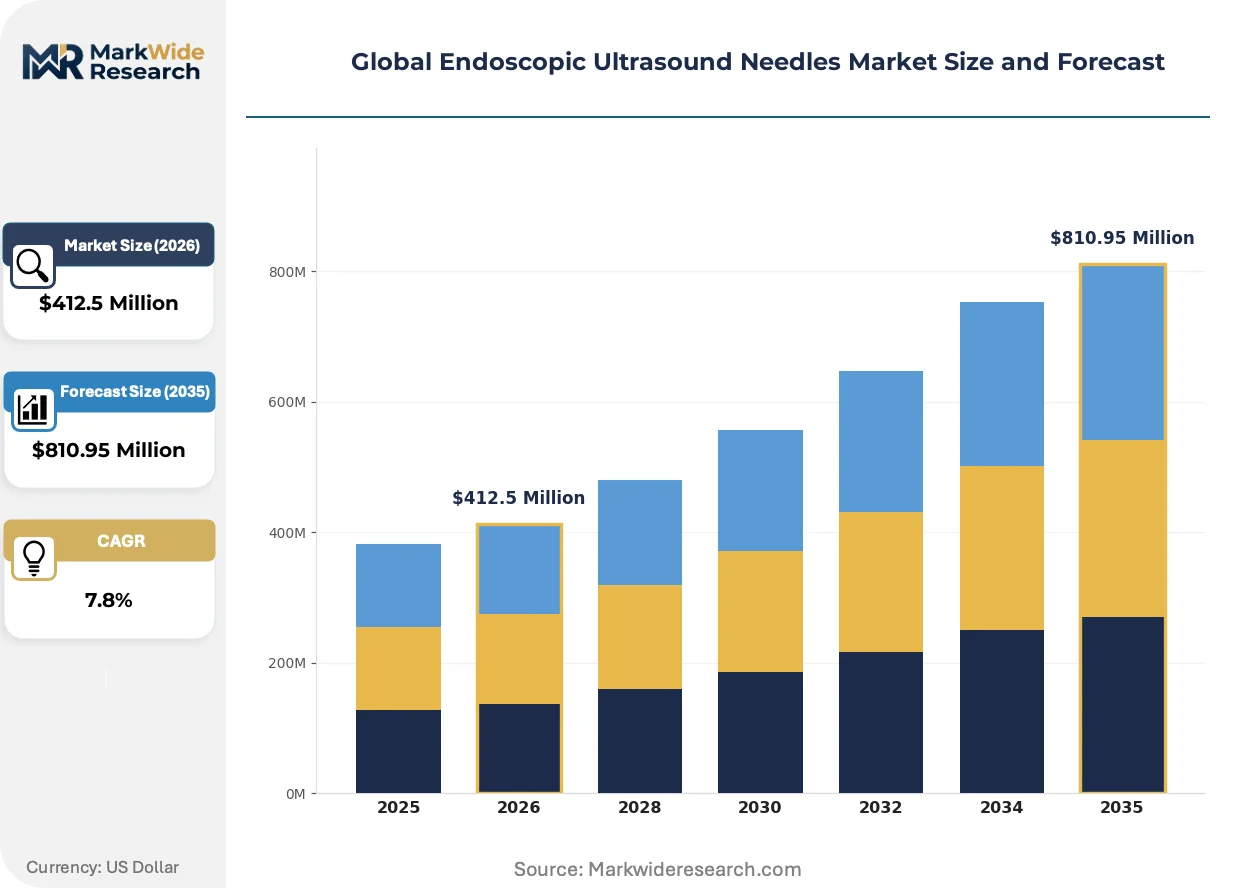
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Needle Aspiration, Fine Needle Biopsy, Core Biopsy Needle, Flexible Needles, Disposable Needles Application: Pancreatic Lesions, Submucosal Tumors, Lymph Node Sampling, Biliary Access, Abdominal Masses End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialty Clinics Distribution Channel: Direct Sales, Medical Distributors, Online Pharmacies, Wholesale Suppliers |
| Companies Covered | Boston Scientific Corporation, Medtronic, Olympus Corporation, CONMED Corporation, Cook Group Incorporated, Medi-Globe GmbH, ACE Medical Devices Pvt. Ltd, ENDO-FLEX GmbH, Micro-Tech Endoscopy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endoscopic Ultrasound Needles Market Shifts & Advancements
Needle design convergence with advanced imaging modalities and automated tissue handling systems is redefining procedural workflows and capital equipment purchasing criteria across hospital systems.
Coaxial needle systems with integrated suction control mechanisms are supplanting conventional manual aspiration devices in high-volume academic medical centers. Interventional gastroenterologists at tertiary hospitals in the United States and Japan adopt these platforms to reduce operator-dependent variability in tissue yield. The technology is compressing training curves for new practitioners while enabling standardized sampling protocols that satisfy molecular pathology laboratory requirements.
EU MDR technical documentation mandates now require enhanced biocompatibility testing and post-market surveillance systems for all Class IIa invasive devices. Manufacturers face extended development cycles as they establish clinical evidence packages and unique device identification traceability infrastructure. European notified bodies prioritize reviews for needle systems with demonstrated compatibility across multiple endoscope brands, disadvantaging captive accessory strategies.
Hospital value analysis committees now unbundle needle procurement from capital equipment contracts, forcing standalone pricing negotiations for disposable components. Group purchasing organizations in the United States consolidate demand across integrated delivery networks, extracting volume discounts that erode manufacturer list prices. This behavioral shift concentrates purchasing power among three dominant GPOs while marginalizing smaller regional distributors lacking national contract access.
Global Endoscopic Ultrasound Needles Market Segmentation
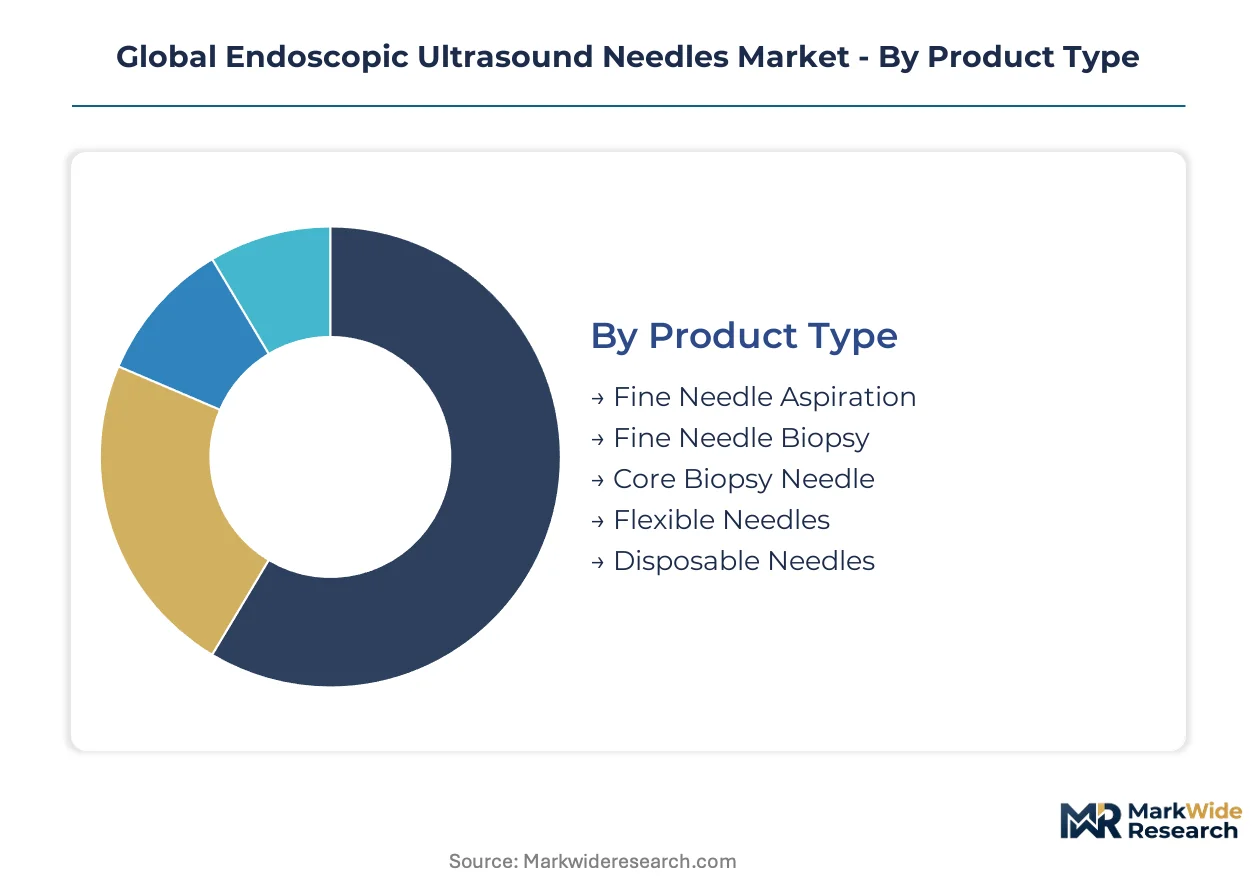
Segmentation in the Endoscopic Ultrasound Needles Market reveals distinct margin architectures across product technologies, clinical applications, and procurement channels. Understanding where value concentrates enables manufacturers to align R&D investments with highest-yield opportunities and optimize channel economics for each customer tier.
Product Type:
Fine needle aspiration and biopsy platforms command premium pricing in tertiary hospital procurement, while core biopsy and flexible designs serve specialized interventional workflows.
- Fine Needle Aspiration:Hollow 19-25 gauge stainless steel instruments designed for cytological sampling under EUS guidance. United States academic medical centers drive volume through established CPT reimbursement codes for pancreatic and mediastinal lesion evaluation.
- Fine Needle Biopsy:Core tissue acquisition devices with proprietary cutting mechanisms enabling histological specimens. German pathology laboratories now mandate these for immunohistochemistry panels, pulling conversion from aspiration devices.
- Core Biopsy Needle:Larger-gauge instruments for substantial tissue cores in submucosal tumor characterization.
- Flexible Needles:Nitinol-based designs navigating tortuous anatomical paths in biliary access procedures.
- Disposable Needles:Single-use platforms capturing procurement share as sterilization costs erode reusable economics.
The dominant share belongs to Fine Needle Aspiration, while Fine Needle Biopsy is closing the gap fastest.
Application:
Procedure volume distributes across anatomical targets based on disease incidence, screening protocol adoption, and interventionalist specialization density.
- Pancreatic Lesions:Dominant application segment driven by NCCN guideline expansion for cyst surveillance in high-risk populations. Japanese tertiary hospitals lead procedural density through mature endoscopy infrastructure and early screening protocols.
- Submucosal Tumors:Gastrointestinal stromal tumor evaluation and leiomyoma differentiation requiring core tissue for DOG1 and CD117 immunohistochemistry. United States community hospital adoption accelerates as EUS training expands beyond academic centers.
- Lymph Node Sampling:Mediastinal and celiac axis staging for lung and esophageal malignancies.
- Biliary Access:EUS-guided cholangiography and gallbladder drainage procedures.
- Abdominal Masses:Retroperitoneal and adrenal lesion characterization.
Pancreatic Lesions holds the largest procedure share, with Submucosal Tumors expanding most quickly as molecular pathology requirements proliferate.
End User:
Capital equipment ownership and bundled procedure economics determine purchasing authority and contract negotiation leverage across customer tiers.
- Hospitals:Integrated delivery networks in the United States and Germany concentrate procurement through value analysis committees unbundling disposable components from capital equipment. Ownership of EUS platforms creates captive demand for compatible needle systems.
- Ambulatory Surgery Centers:Cost-constrained settings in India and Brazil retaining reusable sterilization protocols due to capital limitations.
- Diagnostic Laboratories:Specimen quality requirements influencing hospital needle specification decisions.
- Specialty Clinics:Gastroenterology-focused practices with procedure volume insufficient for capital equipment investment.
Hospitals capture the dominant procurement value, while Diagnostic Laboratories are gaining influence fastest through tissue adequacy specifications.
Distribution Channel:
Channel selection reflects customer scale, geographic concentration, and regulatory complexity in target markets.
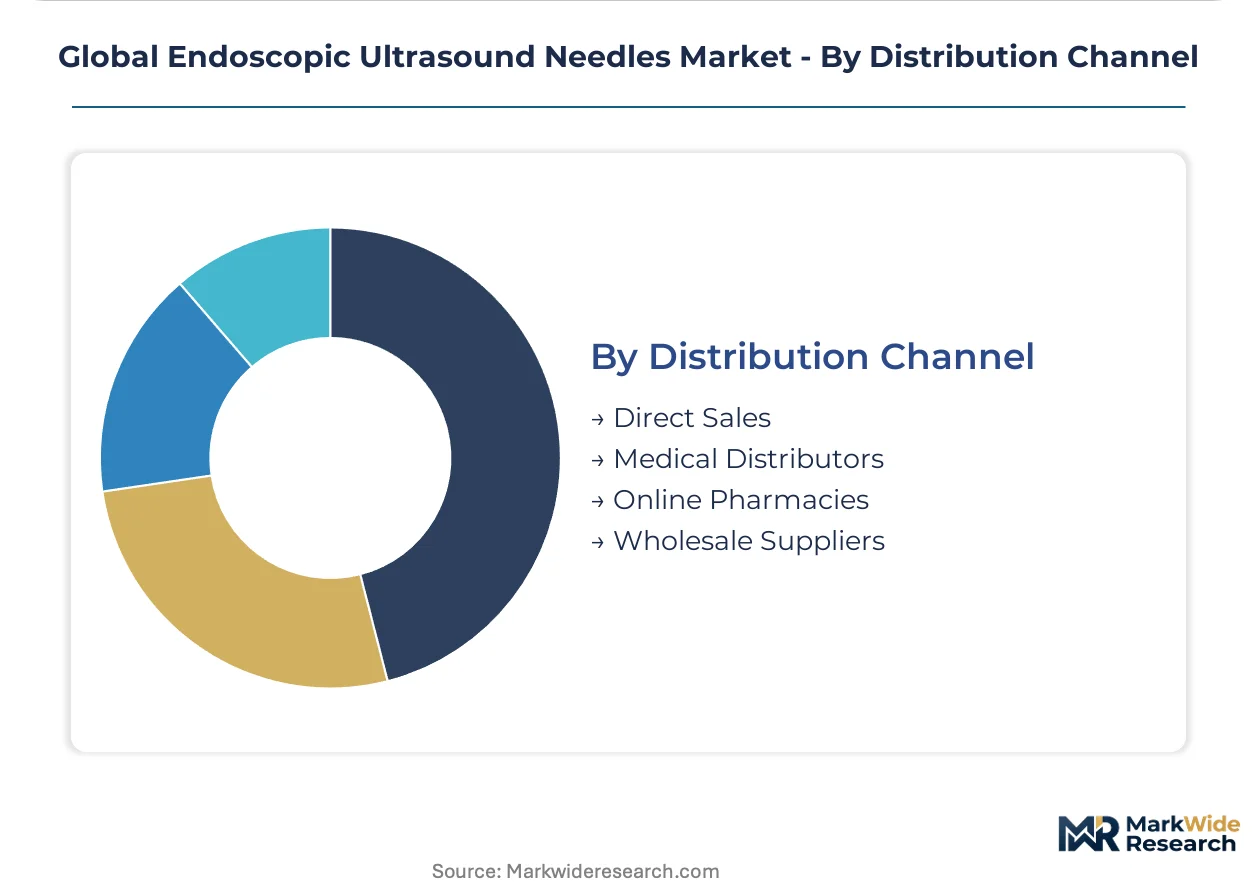
- Direct Sales:Embedded manufacturer representatives serving integrated delivery networks and academic medical centers in the United States. Medtronic and Boston Scientific deploy dedicated teams within IDN purchasing committees to secure sole-source contracts.
- Medical Distributors:Regional specialists navigating Japan PMDA foreign manufacturer registration requirements for market entrants lacking in-country infrastructure.
- Online Pharmacies:Emerging channel for standardized disposable components in price-sensitive segments.
- Wholesale Suppliers:Volume aggregation for smaller facilities lacking direct manufacturer relationships.
Direct Sales commands the highest margin channel share, with Medical Distributors expanding fastest in Asia-Pacific regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of endoscopic ultrasound needles concentrate among three manufacturing clusters serving distinct regulatory environments. Import demand patterns reveal procurement sophistication gaps between established healthcare infrastructure markets and emerging hospital upgrade cycles.
United States
Academic medical centers in Boston and Houston drive procedural volume through NCCN guideline adoption for pancreatic cyst surveillance. FDA 510(k) clearance pathways shape product development timelines for manufacturers targeting IDN purchasing committees. The Research Triangle Park corridor hosts sterilization validation facilities serving disposable needle platforms.
Germany
Pathology laboratories in Munich and Heidelberg mandate core tissue specimens for immunohistochemistry panels, accelerating fine needle biopsy conversion. EU MDR technical documentation standards compress registration timelines for ISO 13485-certified manufacturers. The Baden-Württemberg medical technology cluster concentrates needle coating and surface treatment capabilities.
Japan
Tertiary hospitals in Tokyo and Osaka maintain the highest EUS procedural density globally through mature endoscopy infrastructure. PMDA foreign manufacturer registration requirements extend audit timelines for new market entrants lacking in-country representation. The Kansai region anchors Asia-Pacific distribution networks for compatible needle systems.
India
Government-funded medical college hospital upgrades under the PLI scheme for medical devices create procurement windows in Mumbai, Delhi, and Bangalore. CDSCO medical device registration requirements layer compliance complexity for imported disposable platforms. Cost-constrained outpatient centers in secondary cities retain reusable sterilization protocols.
Switzerland
Specialty clinics in Zurich and Geneva source premium needle systems for complex interventional workflows. Swissmedic conformity assessment procedures align with EU MDR standards while maintaining distinct traceability mandates. The Basel pharmaceutical corridor influences adjacent diagnostic device specification requirements.
Global Endoscopic Ultrasound Needles Market Competitive Landscape
Listed leaders compete with private specialists across capital equipment bundling and standalone disposable procurement channels. The vendor base organizes into three tiers: integrated platform owners with captive install bases, independent needle specialists competing on compatibility breadth, and regional fabricators serving price-sensitive procurement segments. Consolidation pressure intensifies as hospital value analysis committees unbundle accessory purchasing from imaging system contracts. Dominant competitive moves include backward integration into nitinol alloy supply chains and strategic partnerships with pathology laboratory networks.
Among integrated platform owners, Boston Scientific Corporation and Olympus Corporation exemplify divergent geographic anchoring strategies. Boston Scientific Corporation occupies a position within North American IDN purchasing structures. Olympus Corporation anchors Asia-Pacific distribution through endoscope install base compatibility requirements. Medtronic sits within the scale-driven tier, representing direct sales deployment models embedded in hospital procurement committees.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Olympus Corporation |
| CONMED Corporation |
| Cook Group Incorporated |
| Medi-Globe GmbH |
| ACE Medical Devices Pvt. Ltd |
| ENDO-FLEX GmbH |
| Micro-Tech Endoscopy |
| Others |
Supply & Pricing Matrix
Capacity utilization at nitinol alloy foundries in Japan and Germany shapes both supply concentration and price floors for high-flexibility needle designs. Tertiary hospital procurement committees exploit this concentration through sole-source contract negotiations that compress manufacturer margins while locking in multi-year volume commitments.
Pricing Analysis
Integrated delivery network buyers anchor three-tier pricing structure across premium, standard, and economy levels in the United States. Price differentiation rests on FDA 510(k) clearance tier and sterilization validation depth, with academic medical centers least sensitive and Indian outpatient surgical centers most sensitive. Cost compression in economy tiers is intensifying because CDSCO registration requirements delay import substitution timelines.
Supply Chain Analysis
Just-in-time inventory strategies dominate disposable needle procurement at United States academic medical centers, while Japanese distributors maintain strategic stockpiles against PMDA audit disruptions. Manufacturing concentrates in Germany, Japan, and the United States. Raw material dependencies draw from nickel-titanium alloy suppliers, stainless steel mills, and ethylene oxide sterilization facilities. Single-source vulnerability concentrates in superelastic nitinol feedstock. Distribution runs through captive endoscope manufacturer networks and independent medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized interventional endoscopist training programs graduate insufficient practitioners to match procedural volume growth, creating persistent capability scarcity that constrains market expansion regardless of manufacturing capacity additions.
For Market Incumbents: Secure backward integration into nitinol alloy supply chains to defend against raw material price volatility from Japanese and German metallurgy suppliers. Expand ISO 13485-certified production capacity in Baden-Württemberg to exploit EU MDR streamlined registration timelines for Class IIa devices. For New Entrants and Emerging Players: FDA 510(k) premarket notification fast-tracks offer the most penetrable regulatory pathway for compatible needle designs targeting United States community hospitals outside integrated delivery network contracts. Focus initial go-to-market efforts on pathology laboratory specification influence rather than capital equipment bundling. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent needle specialists with demonstrated compatibility across multiple endoscope brands rather than captive platform owners. Long-term viability hinges on molecular pathology laboratory relationships that drive fine needle biopsy conversion. Watch NCCN guideline sampling adequacy threshold revisions as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates conformity assessment timelines for ISO 13485-certified manufacturers targeting German pathology laboratories. |
| Nitinol Alloy Supply Agreement | Locks in superelastic nickel-titanium pricing to stabilize gross margins on flexible needle platforms. |
| Pathology Laboratory Partnership | Secures core tissue specification influence that pulls hospital procurement toward fine needle biopsy devices. |
| India Direct Sales Infrastructure | Captures PLI scheme-funded medical college hospital upgrade windows in Mumbai, Delhi, and Bangalore. |
| Coaxial Needle System Launch | Reduces operator-dependent variability to satisfy molecular pathology laboratory yield requirements. |
Research Methodology
Cross-validation between hospital procurement database analysis and GPO contract documentation anchors the qualitative findings. Primary interviews with interventional gastroenterologists, biomedical engineers, GPO contracts managers, and pathology laboratory directors combined with secondary validation from FDA 510(k) filings, EU MDR notified body registers, CMS Medicare reimbursement data, and hospital capital equipment purchasing records. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis enable triangulation across modeling approaches.
Sensitivity analysis across the projection horizon tests forecast robustness against regulatory timeline slippage and reimbursement coding changes. Segmentation dimensions include product type, application target, end-user tier, and regional regulatory cluster. CAGRs derive from installed base expansion rates and procedure volume intensity per EUS platform. Industry-specific inputs incorporate NCCN guideline adoption curves and pathology laboratory tissue adequacy specification shifts.
Decision-makers should treat outputs as directional under stable reimbursement and regulatory approval base assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR notified body backlog conditions and nitinol alloy supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
North America Disposable Endoscopes Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Endoscope Washer Disinfector Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Endoscopy Market
Endoscopy
Global Flexible Endoscopes Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Endoscopic Probe Disinfection Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Gastroscopes Market
Endoscopy
Industrial Endoscope Market
Endoscopy
ENT Endoscopy Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Veterinary Endoscopy Devices Market