
 Pachymeter Market | 2026-2036
Pachymeter Market Size, Share, and Industry Trends Forecast 2026-2036
Pachymeter Market Outlook
Ophthalmology clinics are broadening their pachymeter procurement beyond traditional hospital settings. Carl Zeiss Meditec AG leverages its OCT platform integration to dominate premium optical pachymetry. NIDEK Co., Ltd. sustains strong positioning across Asia-Pacific through localized manufacturing and service networks. Reichert Inc. specializes in handheld ultrasound devices for mobile screening programs.
A pachymeter measures corneal thickness with precision typically within plus or minus five micrometers, employing either ultrasonic transducers or optical interferometry to generate cross-sectional maps essential for glaucoma risk assessment and refractive surgical planning. Optical pachymeters command margin pools in premium eye care chains where non-contact measurement reduces infection control burden, while ultrasound pachymeters retain volume leadership in developing markets due to lower capital requirements and durable probe architecture. Ultrasound imaging technology anchors the installed base, though optical coherence tomography systems capture fastest growth by bundling pachymetry with anterior segment analysis.
The FDA enforces 510(k) premarket notification for pachymeter devices, while the EU Medical Device Regulation imposes stricter clinical evidence requirements under CE marking pathways. Japan's PMDA maintains distinct pharmaceutical and medical device agency review timelines that shape product launch sequencing for multinational manufacturers. Stakeholders must monitor reimbursement code consolidation for corneal diagnostics as payers scrutinize overlap between standalone pachymetry and comprehensive anterior segment imaging.
Market Dynamics
Optical coherence tomography systems are displacing standalone ultrasound units in premium diagnostic workflows, compressing equipment replacement cycles and forcing manufacturers to bundle anterior segment analysis capabilities to defend installed base positions.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements under CE marking pathways are accelerating hospital consolidation toward validated, multi-function platforms that combine pachymetry with broader anterior imaging.
- Corneal cross-linking protocols:Rising surgical volumes for keratoconus treatment in Germany and Japan are driving instrument procurement beyond traditional glaucoma screening applications.
- Mobile screening programs:Government-funded rural eye health initiatives in India and Brazil are expanding demand for portable ultrasound devices with durable probe architecture.
Market Restraints
- Input cost volatility:Precision optical components and piezoelectric crystals face supply concentration from Japanese and German specialty material suppliers, squeezing margin pools on mid-range systems.
- Technical limitation:Ultrasound pachymetry requires corneal contact and coupling gel, creating infection control burdens that optical methods avoid in premium eye care chains.
- Regulatory friction:Japan's PMDA maintains distinct pharmaceutical and medical device agency review timelines that delay product launch sequencing for multinational manufacturers.
Strategic Opportunities
- Underpenetrated geography:Indonesia and Vietnam present white space for optical pachymetry adoption as private ophthalmology chains expand in Southeast Asian metropolitan clusters.
- Technology convergence:Integration of artificial intelligence-assisted thickness mapping with swept-source OCT is creating premium pricing tiers for early keratoconus detection.
- Distribution innovation:Direct-to-clinic leasing models are displacing traditional capital equipment sales in India's tier-two cities, lowering barrier to entry for independent practitioners.
Industry Challenges
- Certification timeline compression:FDA 510(k) premarket notification pathways for software-enabled diagnostic features are extending validation periods for OCT-integrated systems.
- Talent scarcity:Shortage of trained biomedical engineers capable of servicing hybrid optical-ultrasound platforms is constraining after-sales network expansion in Latin America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pachymeter Market |
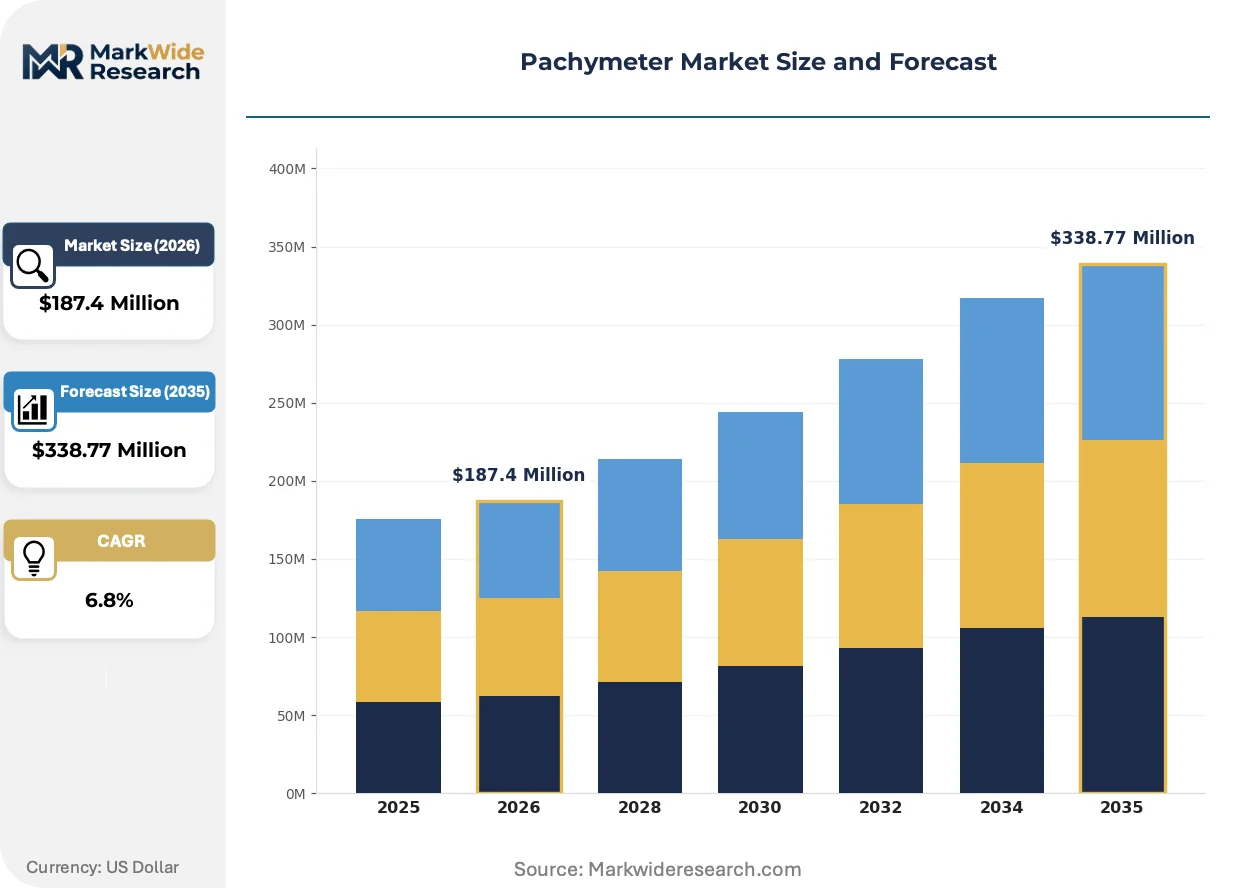
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Pachymeters, Optical Pachymeters, Advanced In Vivo Pachymeters, Contact Pachymeters End User: Ophthalmology Clinics, Hospitals, Research Institutes, Optical Centers Technology: Optical Coherence Tomography, Ultrasound Imaging, Laser-Based Measurement, Digital Imaging Application: Corneal Thickness Measurement, Refractive Surgery, Eye Health Monitoring, Disease Diagnosis |
| Companies Covered | Carl Zeiss Meditec AG, NIDEK Co., Ltd., Reichert Inc., Sonomed Escalon, Topcon Corporation, DGH Technology, Inc., Quantel Medical, Optovue, Inc., TOMEY Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pachymeter Market Strategic Shifts
Swept-source optical coherence tomography is compressing measurement acquisition times while expanding diagnostic parameter capture beyond central corneal thickness, reshaping competitive differentiation around software analytics rather than hardware precision alone.
Spectral-domain OCT technology generates cross-sectional corneal maps at speeds exceeding traditional time-domain systems by orders of magnitude. Refractive surgery centers in South Korea and Spain are adopting these platforms for pre-operative screening workflows. The technology is expanding into cataract planning suites as manufacturers bundle pachymetry with biometry and tomography in single-device configurations.
The FDA's Quality System Regulation for ophthalmic devices mandates design controls and process validation that extend development timelines for software-as-medical-device features. Manufacturers must document clinical performance across intended use populations before 510(k) clearance. Early-stage companies are responding by partnering with established OEMs to leverage existing quality management infrastructure rather than building compliant systems independently.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchases, pressuring vendors to compete on transparent maintenance pricing. Academic medical centers in the United States and university eye hospitals in Germany are piloting performance-based service agreements tied to device uptime guarantees. This shift is most visible in North American health systems where capital budget scrutiny has intensified under value-based care reimbursement frameworks.
Pachymeter Market Segmentation
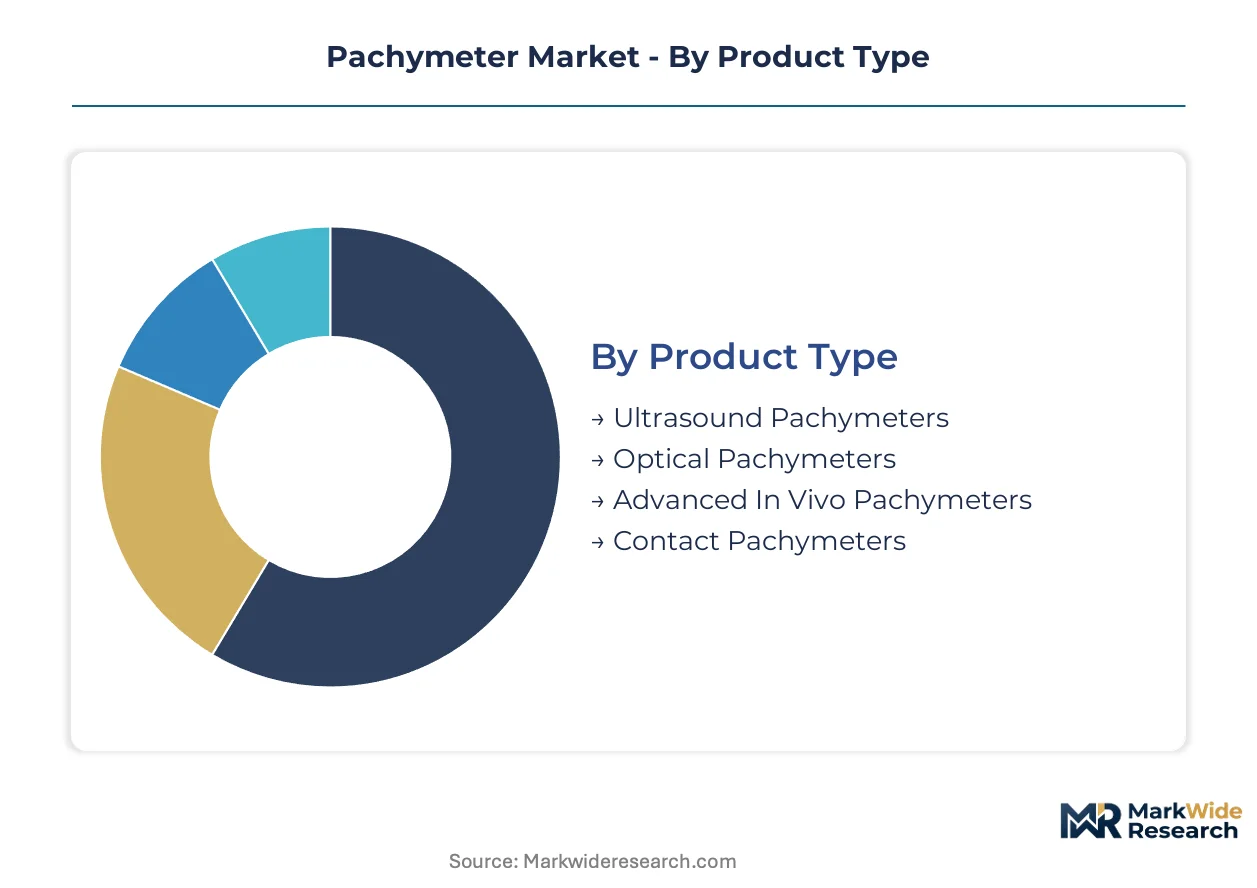
Pachymeter procurement decisions hinge on workflow integration requirements and capital constraints. Segmentation reveals how technology choices diverge between high-volume screening programs and precision surgical planning environments.
Product Type:
Buyers prioritize measurement modality based on infection control protocols and throughput demands.
- Ultrasound Pachymeters:Piezoelectric transducers generate thickness readings through direct corneal contact with coupling gel. Demand concentrates in India's government-funded rural screening initiatives where probe durability and low capital requirements outweigh infection control burdens.
- Optical Pachymeters:Non-contact interferometry eliminates gel application and reduces cross-contamination risk. Premium eye care chains in Germany and South Korea favor these systems for high-patient-volume workflows where throughput and sterility protocols drive equipment selection.
- Advanced In Vivo Pachymeters:Integrated anterior segment analysis platforms bundle tomography with thickness mapping.
- Contact Pachymeters:Direct applanation methods persist in legacy installations and budget-constrained settings.
Volume sits with ultrasound systems; growth tilts toward optical platforms.
End User:
Procurement authority is shifting from hospital materials management to clinic-level decision-makers.
- Ophthalmology Clinics:Independent practices and chain-affiliated centers drive replacement demand for compact, multi-function devices. Brazil's expanding private ophthalmology networks prioritize portable systems that support mobile screening alongside fixed-base operations.
- Hospitals:Academic medical centers and tertiary facilities anchor demand for research-grade precision and comprehensive anterior segment imaging. University eye hospitals in Germany specify optical coherence tomography-integrated platforms for keratoconus research protocols.
- Research Institutes:Clinical trial sites and university laboratories require calibrated, traceable measurement systems.
- Optical Centers:Retail vision care settings adopt basic screening models for pre-referral triage.
Clinics capture volume leadership; hospital procurement is climbing the fastest.
Technology:
Platform selection determines software upgrade pathways and service contract structures.
- Optical Coherence Tomography:Spectral-domain and swept-source architectures deliver sub-micron precision with cross-sectional mapping capabilities. Spain's refractive surgery centers deploy these systems for pre-operative screening bundles that combine pachymetry with biometry.
- Ultrasound Imaging:Time-domain acoustic measurement retains installed base dominance through probe longevity and field serviceability. Indonesia's emerging metropolitan clusters favor these systems for their tolerance of variable power supply and limited biomedical engineering support.
- Laser-Based Measurement:Confocal and Scheimpflug principles enable non-contact thickness profiling.
- Digital Imaging:Software-enhanced photographic analysis offers entry-level screening functionality.
Ultrasound imaging holds installed base dominance; optical coherence tomography gains share fastest.
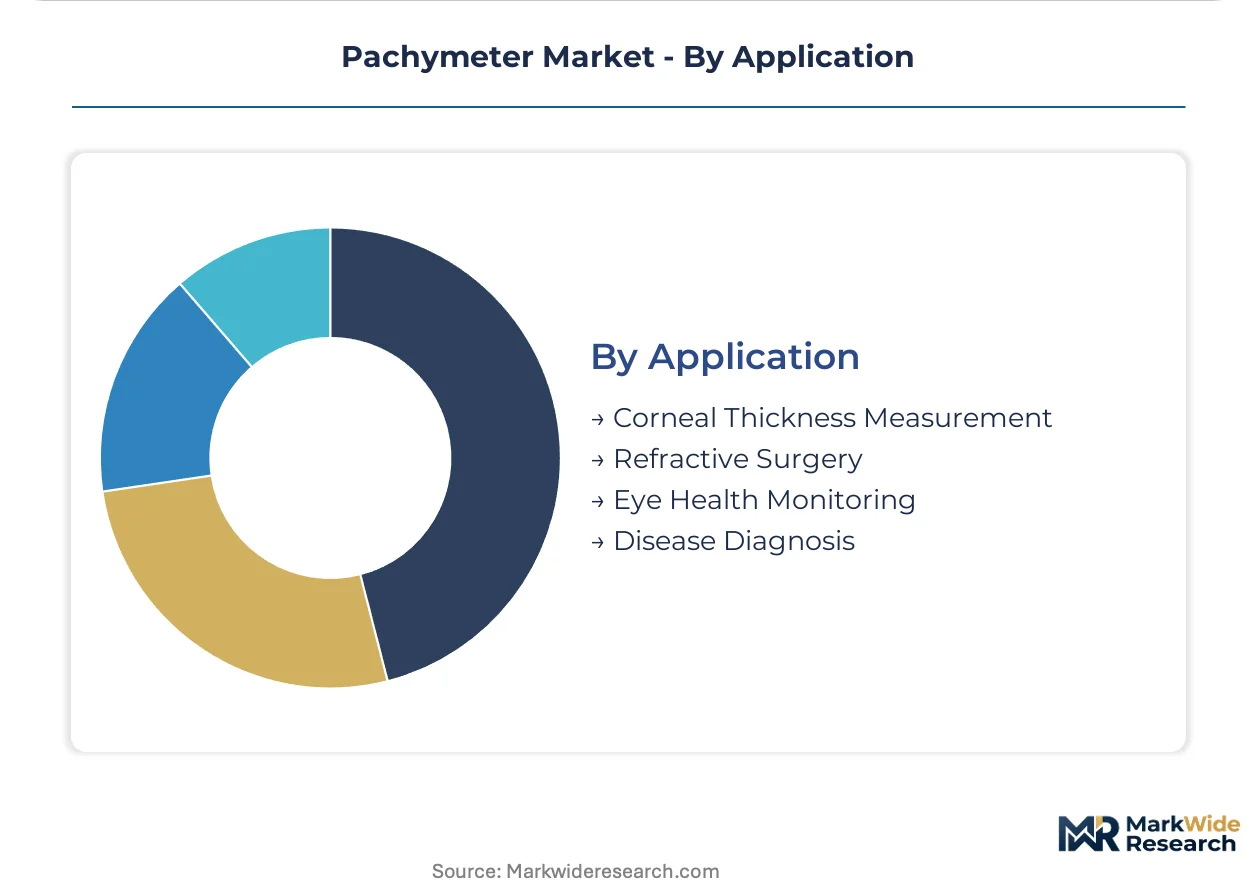
Application:
Clinical use case dictates required precision thresholds and regulatory documentation burdens.
- Corneal Thickness Measurement:Central and peripheral thickness mapping for glaucoma risk stratification represents the foundational application. Japan's PMDA review timelines shape validation requirements for devices targeting this indication.
- Refractive Surgery:Pre-operative screening for LASIK and PRK candidacy demands plus-or-minus five micrometer accuracy. South Korea's high-volume surgical centers drive adoption of swept-source platforms that compress acquisition times.
- Eye Health Monitoring:Longitudinal tracking for progressive conditions requires reproducible measurement protocols.
- Disease Diagnosis:Keratoconus detection and ectasia screening leverage artificial intelligence-assisted thickness pattern recognition.
Thickness measurement commands volume; refractive surgery applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate optical component manufacturing, while India's special economic zones near Hyderabad attract assembly operations for handheld ultrasound devices.
United States
Academic medical centers in Boston and Baltimore drive procurement of research-grade OCT platforms for keratoconus protocols. The FDA's 510(k) premarket notification requirements extend validation timelines for software-enabled diagnostic features. Refractive surgery chains in California and Texas prioritize non-contact optical systems to reduce infection control burdens in high-volume settings.
Germany
University eye hospitals in Heidelberg and Tübingen specify swept-source OCT systems for anterior segment research. The EU Medical Device Regulation imposes stricter clinical evidence requirements under CE marking pathways. Precision optics manufacturers in the Stuttgart region supply spectral-domain components to domestic device assemblers.
Japan
Corneal cross-linking volume growth in Tokyo and Osaka surgical centers drives instrument procurement beyond traditional glaucoma applications. The PMDA maintains distinct pharmaceutical and medical device agency review timelines that shape product launch sequencing. Yokohama-based distributors service the installed base of hybrid optical-ultrasound platforms across Kanto prefecture.
India
Government-funded rural screening initiatives in Maharashtra and Tamil Nadu expand demand for portable ultrasound devices with durable probe architecture. The CDSCO regulates ophthalmic device imports through mandatory registration and quality certification. Private ophthalmology chains in Bangalore and Hyderabad adopt direct-to-clinic leasing models to lower capital barriers for independent practitioners.
Brazil
Expanding private ophthalmology networks in São Paulo and Rio de Janeiro prioritize compact systems supporting mobile screening alongside fixed-base operations. ANVISA enforces Good Manufacturing Practice inspections for imported diagnostic equipment. Metropolitan clusters in Minas Gerais and Paraná states favor ultrasound systems for tolerance of variable power supply conditions.
Pachymeter Market Competitive Environment
Top-tier vendors anchor premium optical coherence tomography integration, while mid-tier specialists concentrate on handheld ultrasound durability and service network density. The vendor base stratifies across three tiers: integrated platform developers, portable device specialists, and regional assembly operations. Two strategic archetypes dominate: precision optics conglomerates leveraging captive component supply, and focused instrument manufacturers building dense after-sales networks. Competitive moves center on bundling anterior segment analysis capabilities and compressing equipment replacement cycles through software upgrade pathways.
Within the precision optics tier, Carl Zeiss Meditec AG exemplifies platform integration strategy, while NIDEK Co., Ltd. occupies a position emphasizing localized manufacturing footprints. Reichert Inc. represents the handheld specialization archetype, anchoring the portable ultrasound segment where durable probe architecture determines procurement decisions. These three entities collectively illustrate the geographic and technological bifurcation shaping vendor positioning.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| NIDEK Co., Ltd. |
| Reichert Inc. |
| Sonomed Escalon |
| Topcon Corporation |
| DGH Technology, Inc. |
| Quantel Medical |
| Optovue, Inc. |
| TOMEY Corporation |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees unbundling after-sales service contracts from equipment purchases are forcing manufacturers to absorb validation cost burdens upfront, compressing margin pools on mid-range systems and tilting supply commitments toward premium optical platforms with longer replacement cycles.
Pricing Analysis
Expedited delivery premiums dominate contract negotiations as German university eye hospitals and South Korean refractive surgery centers demand compressed lead times for OCT-integrated platforms. Pricing stratifies across premium, standard, and economy tiers based on measurement precision certification and bundled software analytics. Cost compression in ultrasound segments is intensifying because Indian government tenders prioritize probe durability over optical sophistication. Mobile screening programs in Brazil and Indonesia exhibit highest price sensitivity, while academic medical centers in the United States and Germany demonstrate lowest sensitivity due to research grant funding.
Supply Chain Analysis
Direct-to-clinic channels handle independent practitioner demand in India's tier-two cities, while distributor networks service hospital procurement committees across Germany and Japan. Precision optical component manufacturing concentrates in Germany and Japan, with piezoelectric crystal supply anchored in Japanese specialty material foundries. Raw material dependencies include spectral-domain sensors, swept-source lasers, and ultrasonic transducer ceramics. Single-source vulnerability in Japanese piezoelectric supply creates bottleneck risk for ultrasound platform assemblers. Distribution runs through authorized service partners with biomedical engineering certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pachymeter market functions as a cost-of-compliance arena where the FDA's 510(k) premarket notification and the EU Medical Device Regulation's clinical evidence requirements erect formidable barriers that favor incumbent platform developers with established quality management infrastructure.
For Market Incumbents: Hedge against optical coherence tomography convergence by deepening software analytics capabilities that extend equipment replacement cycles. Acquire regional service networks in Latin America to address talent scarcity constraining hybrid platform maintenance. Carl Zeiss Meditec AG's platform integration strategy and NIDEK's localized manufacturing footprints illustrate defensive positioning against mid-tier specialists. For New Entrants and Emerging Players: Artificial intelligence-assisted thickness mapping for early keratoconus detection offers a technology-first wedge into premium pricing tiers. Target Indonesia and Vietnam's metropolitan ophthalmology clusters where private chain expansion outpaces incumbent service coverage. Pursue direct-to-clinic leasing models in India's tier-two cities to bypass capital barrier constraints facing independent practitioners. For Investors and Strategic Acquirers: The window for entry favors vertically integrated precision optics specialists with captive component supply and existing regulatory dossiers. Long-term viability hinges on software-as-medical-device revenue streams displacing transactional equipment sales. Watch for FDA 510(k) clearance timeline compression as the signal indicating regulatory capacity constraints that will accelerate consolidation toward compliant platform developers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation clinical evidence requirements accelerate hospital consolidation toward validated multi-function platforms. |
| Hospital System Partnership | Performance-based service agreements with German university eye hospitals and US academic medical centers secure installed base positions. |
| Software Companion Development | AI-assisted thickness mapping bundled with swept-source OCT creates premium pricing tiers for early keratoconus detection. |
| Reimbursement Strategy | Navigation of CMS and private payer code consolidation for corneal diagnostics protects revenue streams against comprehensive imaging overlap. |
| Geographic Expansion | Direct-to-clinic leasing models in India's tier-two cities and Southeast Asian metropolitan clusters lower barrier to entry for independent practitioners. |
Study Parameters
Document review covered FDA 510(k) filings, EU Medical Device Regulation technical documentation, and PMDA submission records, complemented by interviews with ophthalmology clinic directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, and optical component trade flow data. Bottom-up demand modeling across end-user segments was triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Cross-referencing historical replacement cycle data with expert panel input on technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology platform, and application use case, with regional regulatory cluster as an additional industry-specific dimension. CAGRs were derived from equipment shipment volumes and average selling price trajectories, incorporating corneal cross-linking procedural growth and refractive surgery volume trends as forecast inputs.
Several conditions sit outside the modeled scope, including macroeconomic disruptions to healthcare capital budgets, abrupt regulatory pathway modifications, and breakthrough non-contact measurement technologies. Forecasts reflect assumptions regarding continued reimbursement code stability and procedural volume growth trajectories. Periodic stress-testing of base assumptions against PMDA review timeline shifts and input cost volatility in precision optical supply chains is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market