
 Pathological Examination Market | 2026-2036
Pathological Examination Market Size, Share, and Industry Trends Forecast 2026-2036
Pathological Examination Market Outlook
The transition from single-source hospital pathology departments to multi-source outsourced networks is shifting procurement patterns across health systems. F. Hoffmann-La Roche Ltd anchors its position through integrated instrument and reagent platforms that lock in laboratory workflows. Thermo Fisher Scientific leverages its distribution scale to supply consumables and imaging systems across fragmented clinical markets. Quest Diagnostics Incorporated sustains volume leadership through its national laboratory footprint and direct payer contracts.
Pathological examination encompasses the macroscopic and microscopic analysis of tissue, cell, and fluid specimens to diagnose disease, characterize lesions, and guide therapeutic decisions, typically involving formalin-fixed paraffin-embedded processing, thin-section microtomy, and hematoxylin-eosin staining with optional immunohistochemical or molecular adjuncts. Histology remains the foundational revenue pool given its ubiquity in cancer diagnosis, while AI-Driven Solutions represent the fastest-expanding technology segment as laboratories seek computational assistance for pattern recognition and quantification. Digital Pathology infrastructure spending is concentrating among early-adopter health systems that can amortize scanner capital across high specimen volumes.
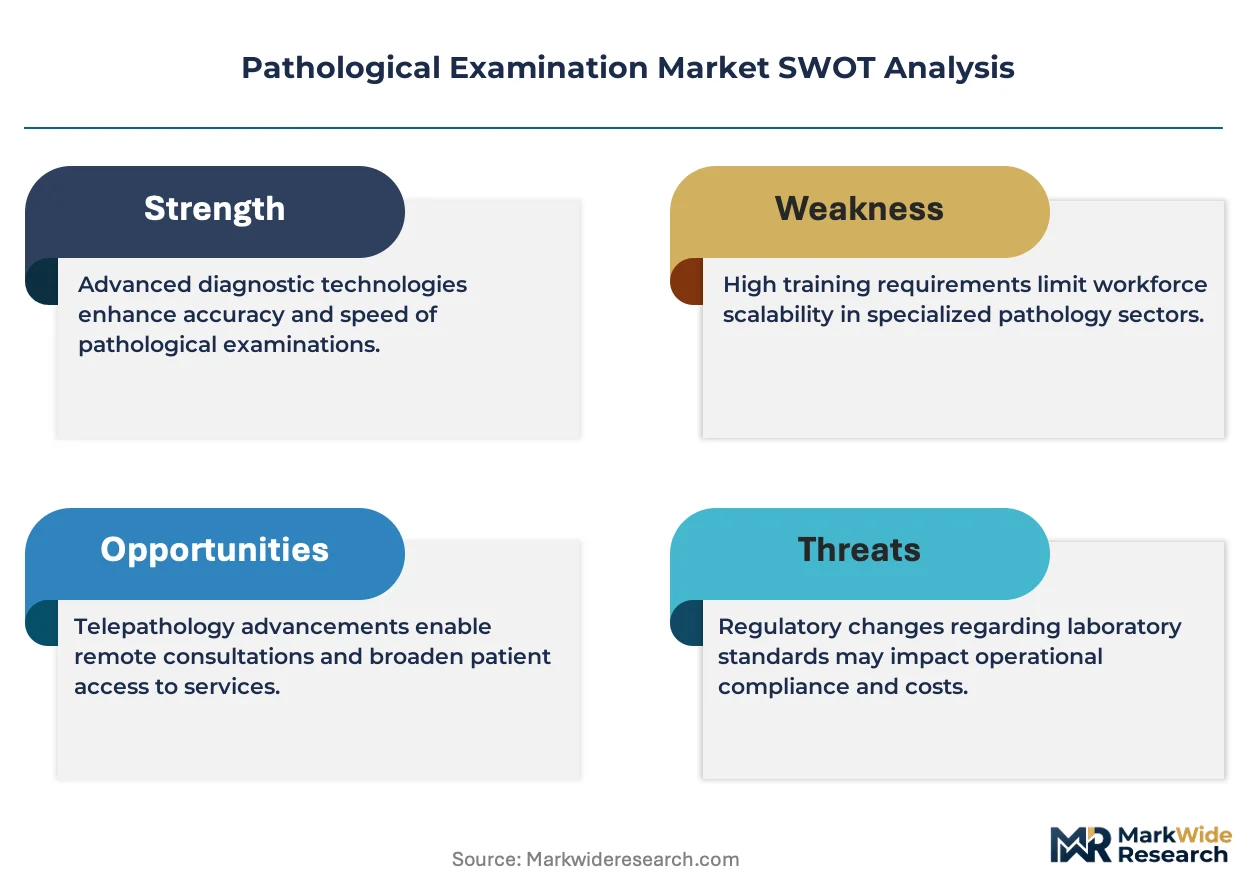
FDA premarket review pathways for digital pathology devices and the EU MDR's stricter diagnostic device classifications are elevating compliance costs and consolidating vendor access for smaller manufacturers. The EPA and OSHA maintain parallel jurisdiction over chemical hazards in histology laboratories, shaping reagent substitution trends and ventilation infrastructure investments. Stakeholders must monitor how reimbursement parity between digital and glass-slide interpretations evolves, as this will determine adoption velocity and capital allocation priorities across health system pathology departments.
Market Dynamics
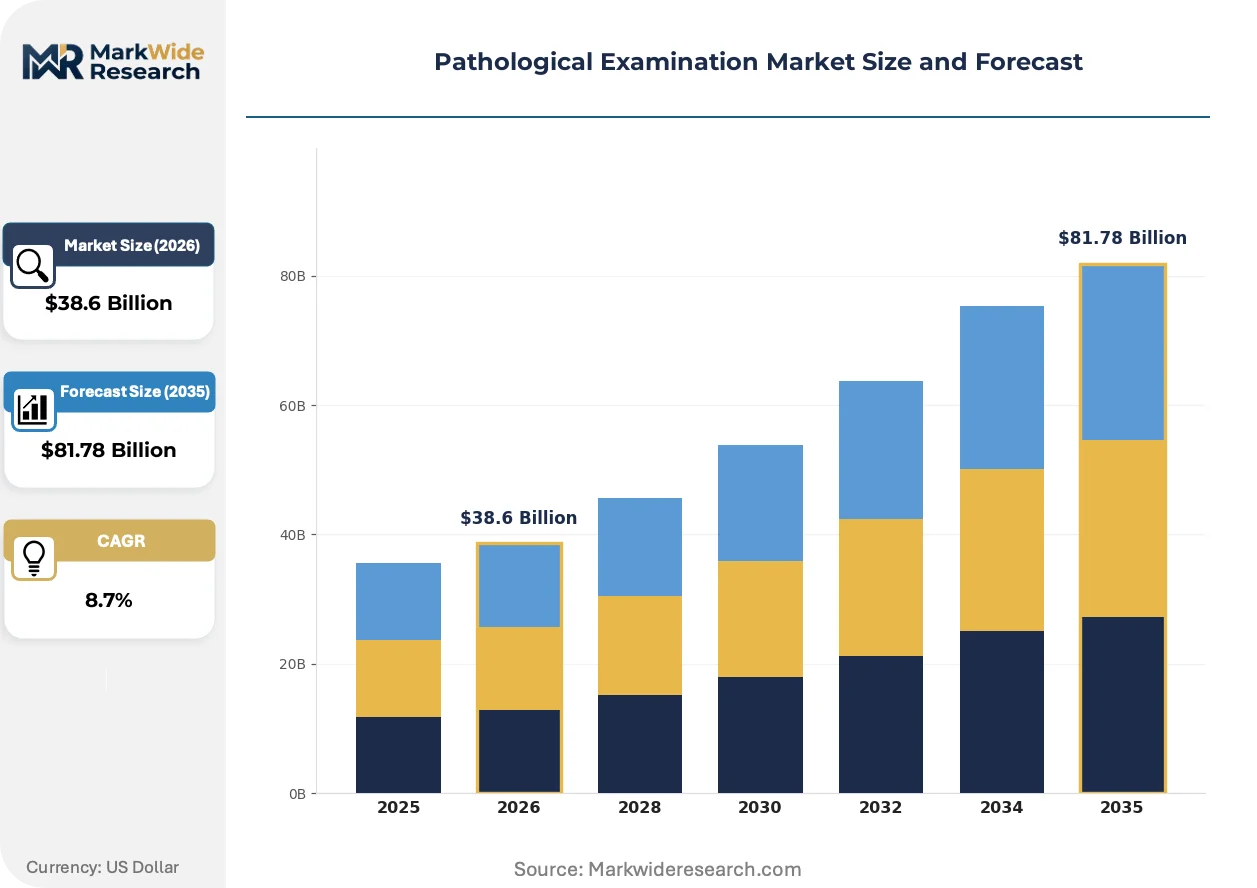
Whole-slide imaging infrastructure is compressing turnaround times for oncology diagnostics while forcing capital reallocation from microscopes to scanners and cloud storage architectures across hospital laboratories.
Growth Catalysts
- FDA Digital Pathway Reforms:Streamlined premarket review for AI-assisted diagnostic devices accelerates deployment of computational pathology tools in clinical workflows.
- Oncology Caseload Concentration:Hospital laboratories in the United States and Germany are outsourcing high-volume histopathology to manage rising cancer screening backlogs.
- Cloud-Native Platforms:Remote slide access enables pathologist workforce pooling across health systems, reducing specialist shortage constraints in rural markets.
Market Restraints
- Scanner Capital Intensity:High-throughput whole-slide imaging systems require substantial upfront investment that strains mid-sized laboratory budgets.
- Reagent Supply Concentration:Specialized histology chemicals face sourcing vulnerabilities from limited qualified suppliers in Europe and Asia.
- EU MDR Classification Burden:Stricter diagnostic device categories elevate compliance documentation requirements for digital pathology vendors seeking CE marking.
Strategic Opportunities
- China Centralized Networks:National pathology infrastructure investments create procurement windows for imaging and informatics vendors in tier-one hospital clusters.
- AI-Assisted Quantification:Machine learning integration with immunohistochemistry scoring opens service revenue streams in biomarker interpretation.
- Telepathology Distribution:Direct-to-laboratory digital platforms bypass traditional distributor markups in fragmented outpatient clinic segments.
Industry Challenges
- Computational Pathology Talent Gap:Shortage of dual-trained professionals capable of validating algorithm outputs against histologic ground truth slows AI deployment.
- Legacy LIS Integration Friction:Laboratory information system interoperability gaps complicate digital workflow implementation in established hospital environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pathological Examination Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Histology, Cytopathology, Immunohistochemistry, Frozen Section Technology: Digital Pathology, Slide Scanning, AI-Driven Solutions, Traditional Microscopy End User: Hospitals, Clinical Laboratories, Research Institutes, Specialty Clinics Application: Oncology, Infectious Diseases, Genetic Disorders, Autoimmune Conditions |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Quest Diagnostics Incorporated, Sonic Healthcare, 3DHISTECH Ltd, Agilent Technologies Inc, Leica Biosystems, NeoGenomics Laboratories Inc, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pathological Examination Market Strategic Shifts
Computational assistance is migrating from research adjunct to clinical necessity as specimen volumes outpace pathologist supply, while regulatory frameworks crystallize around algorithmic diagnostic accountability.
Multiplex immunofluorescence is consolidating discrete biomarker tests into single-slide assays, reducing tissue consumption and reagent costs. Academic medical centers in Germany and the United States are adopting these platforms for companion diagnostic workflows. The technology is consolidating previously separate staining protocols into unified analytical pipelines that compress turnaround times for precision oncology decisions.
EMA's In Vitro Diagnostic Regulation transition is recasting conformity assessment requirements for digital pathology devices marketed in Europe. Manufacturers face notified body bottlenecks and expanded clinical evidence demands for software-based diagnostic tools. High-complexity laboratories in the Netherlands and Switzerland are front-loading validation studies to maintain uninterrupted market access during the regulatory transition window.
Pathology service procurement is gravitating toward capitated per-specimen contracts that bundle histology, special stains, and molecular adjuncts into single price points. Integrated delivery networks in the United States are consolidating vendor relationships to secure volume discounts and standardized reporting formats. This purchasing model is most visible in oncology-focused health systems where diagnostic spend represents a measurable cost center within episode-based reimbursement frameworks.
Pathological Examination Market Segmentation
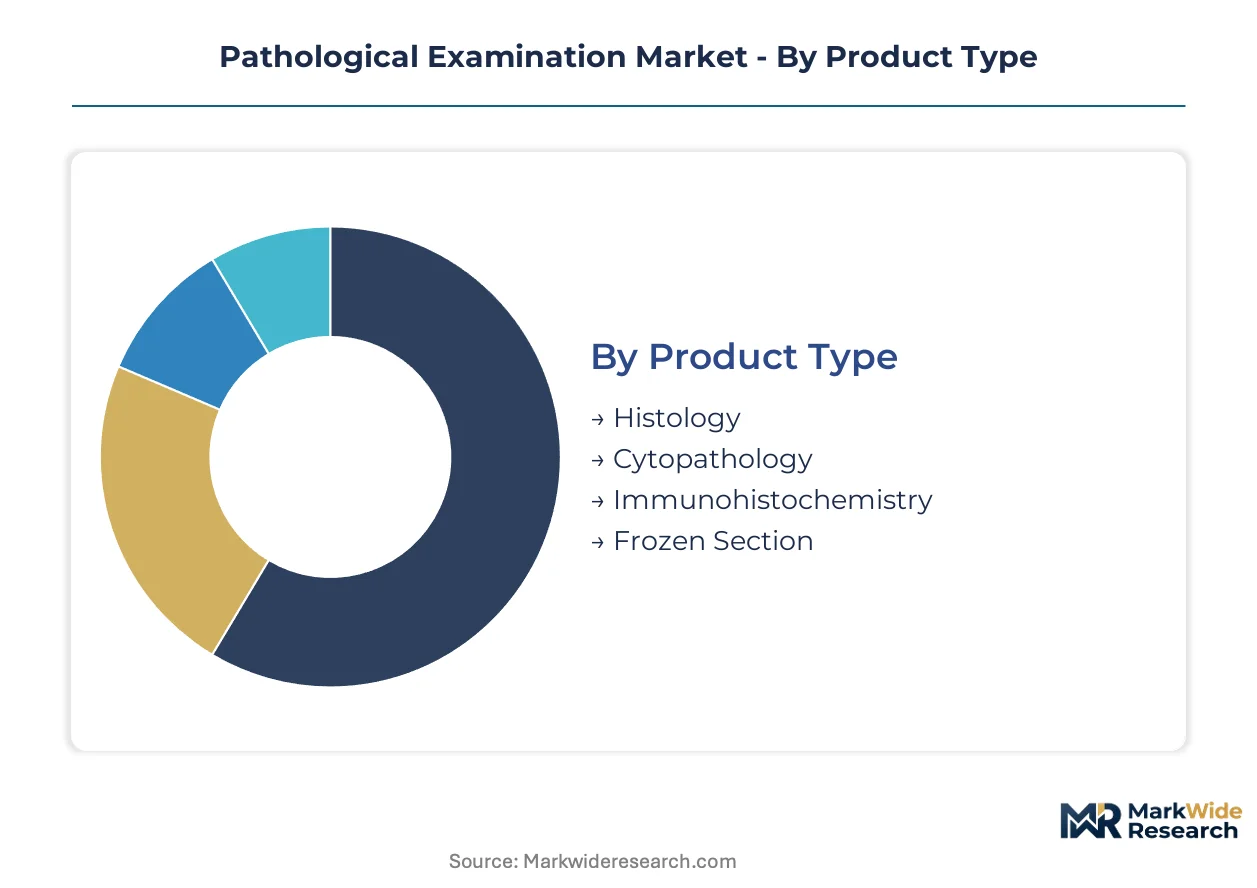
Segmentation in pathological examination reveals where capital flows concentrate and where technology transitions create procurement inflection points. Laboratories allocate budgets differently across product tiers, with high-throughput platforms commanding premium pricing while commoditized consumables compete on contract scale.
Product Type:
Histology anchors volume procurement through its ubiquity in cancer diagnosis, while immunohistochemistry captures premium margins through biomarker complexity and companion diagnostic linkages.
- Histology:Formalin-fixed paraffin-embedded tissue processing with hematoxylin-eosin staining constitutes the procedural foundation for solid tumor diagnosis. Demand concentrates in hospital laboratories across the United States and Germany as oncology caseloads strain traditional workflow capacity.
- Immunohistochemistry:Antibody-based protein detection enables precise tumor subtyping and therapeutic target identification. Academic medical centers in Switzerland and the Netherlands are expanding IHC panels for precision oncology protocols, driving reagent consumption and specialized technician demand.
- Cytopathology:Cell-based specimen analysis supports cervical cancer screening and fluid diagnostics in high-volume reference laboratories.
- Frozen Section:Rapid intraoperative consultation guides surgical margin decisions in tertiary care hospitals with embedded pathology services.
Today's leader: Histology. Tomorrow's challenger: Immunohistochemistry.
Technology:
Capital intensity separates digital infrastructure from legacy equipment, with AI-assisted platforms requiring specialized validation protocols that traditional microscopy avoids.
- Digital Pathology:Whole-slide imaging and cloud-native storage architectures enable remote diagnostic access and computational analysis. Early-adopter health systems in Germany and the United States are amortizing scanner investments across centralized laboratory networks to justify capital outlays.
- AI-Driven Solutions:Machine learning algorithms assist pattern recognition, quantification, and biomarker scoring with regulatory-validated outputs. FDA premarket review pathway streamlining is accelerating clinical deployment in high-complexity laboratories seeking productivity gains.
- Slide Scanning:High-throughput digitization hardware bridges analog specimen archives with digital workflow integration.
- Traditional Microscopy:Conventional light microscopy persists in resource-constrained settings and specialized consultative practice.
Installed base dominance: Traditional Microscopy. Steepest expansion trajectory: AI-Driven Solutions.
End User:
Specimen volume scale and reimbursement complexity differentiate procurement priorities across facility types, with integrated delivery networks consolidating vendor relationships.
- Hospitals:Inpatient and surgical pathology services drive high-throughput histology demand with embedded laboratory infrastructure. United States health systems are outsourcing non-core pathology to manage fixed costs while retaining intraoperative and complex case capabilities.
- Clinical Laboratories:Reference and commercial laboratories aggregate specimens across multiple health systems to achieve economies of scale. Quest Diagnostics and similar operators leverage national footprints for direct payer contracting and standardized reporting.
- Research Institutes:Academic and translational research facilities prioritize experimental platforms and multiplex technologies for discovery workflows.
- Specialty Clinics:Dermatology and gastroenterology practices require rapid turnaround for biopsy services with limited on-site technical capacity.
Volume concentration: Hospitals. Margin expansion: Clinical Laboratories.
Application:
Disease prevalence and diagnostic complexity determine reagent consumption patterns, with oncology commanding specialized staining protocols that infectious disease testing rarely requires.
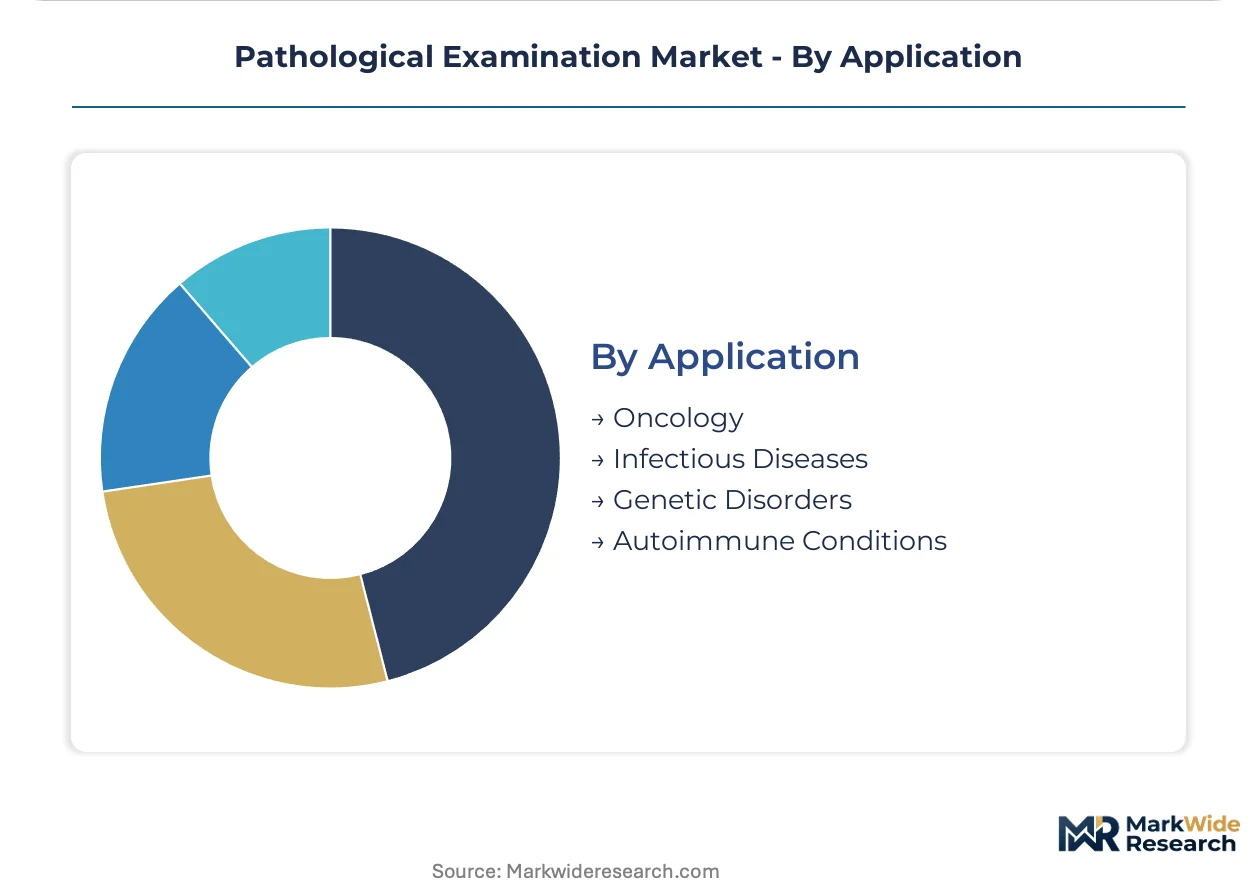
- Oncology:Cancer diagnosis and subtyping represent the dominant application through histology, IHC, and emerging molecular adjuncts. China's tier-one hospital clusters are building centralized pathology networks to manage rising cancer screening volumes.
- Infectious Diseases:Microbiological and histopathological diagnosis of bacterial, viral, and fungal pathogens supports antimicrobial stewardship programs. Public health laboratories in Germany maintain specialized capabilities for outbreak investigation and resistance surveillance.
- Genetic Disorders:Constitutional and somatic genetic testing integrates with histopathological correlation for hereditary cancer syndromes.
- Autoimmune Conditions:Tissue-based autoantibody detection and inflammatory pattern analysis supports rheumatology and dermatology diagnostics.
Revenue anchor: Oncology. Emerging volume: Genetic Disorders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors pathological examination infrastructure through concentrated hospital laboratory networks and early digital pathology adoption. Germany and China follow as distinct investment poles with divergent regulatory frameworks and procurement models.
United States
Oncology caseload concentration and integrated delivery network consolidation drive scanner procurement across hospital systems. FDA streamlined premarket review pathways accelerate AI-assisted diagnostic device deployment. The Greater Boston and San Francisco Bay Area clusters host validation partnerships between academic medical centers and computational pathology developers.
Germany
Centralized pathology networks in North Rhine-Westphalia and Bavaria aggregate specimens to achieve scanner capital efficiency. EMA's In Vitro Diagnostic Regulation transition elevates clinical evidence demands for software-based diagnostic tools. The Heidelberg and Munich metropolitan regions concentrate whole-slide imaging validation studies ahead of notified body bottlenecks.
China
Tier-one hospital clusters in Beijing, Shanghai, and Guangzhou build national pathology infrastructure to manage rising cancer screening volumes. NMPA regulatory pathways for digital medical devices shape vendor market entry timelines. The Yangtze River Delta region concentrates procurement windows for imaging and informatics platforms.
Switzerland
Academic medical centers in Basel and Zurich expand immunohistochemistry panels for precision oncology protocols. Swissmedic diagnostic device classifications align with EU MDR standards while maintaining distinct conformity assessment timelines. The Basel metropolitan area anchors biomarker interpretation service development.
Netherlands
High-complexity laboratories front-load validation studies to maintain uninterrupted market access during regulatory transition windows. The Dutch national health system's centralized procurement influences reagent contract structures across Benelux. The Amsterdam-Rotterdam corridor concentrates digital workflow implementation among early-adopter health systems.
Pathological Examination Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-assisted quantification and cloud-native platform development. The vendor base stratifies across integrated instrument-reagent platforms, distribution-scale consumables suppliers, and national laboratory footprint operators. Three archetypes dominate: workflow-locked integrated systems vendors, volume-leveraged reference laboratory networks, and computational assistance specialists. Competitive moves concentrate on strategic partnerships for algorithm validation and geographic expansion through outsourced pathology service contracts.
Among Swiss and German integrated healthcare conglomerates, F. Hoffmann-La Roche Ltd and Merck KGaA occupy positions anchoring instrument-reagent platform ecosystems. Thermo Fisher Scientific exemplifies the distribution-scale archetype with consumables and imaging systems reach. Quest Diagnostics Incorporated represents the national laboratory footprint model with direct payer contracting capabilities. These three company structures illustrate how vendor positioning aligns with procurement consolidation trends across health system pathology departments.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Quest Diagnostics Incorporated |
| Sonic Healthcare |
| 3DHISTECH Ltd |
| Agilent Technologies Inc |
| Leica Biosystems |
| NeoGenomics Laboratories Inc |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
REACH chemical safety mandates gate both qualified reagent supply and premium-tier pricing access for histology consumables, as laboratories must source compliant solvents and stains from certified European manufacturers or absorb validation costs for alternative formulations. This regulatory filter concentrates procurement leverage among incumbent chemical suppliers while mid-sized laboratories face cost compression from mandatory ventilation infrastructure upgrades.
Pricing Analysis
Input-cost pass-through from specialty chemical feedstocks drives contract renegotiations across formalin, xylene, and hematoxylin supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified reagents from laboratory-grade alternatives and bulk unvalidated imports. Pricing pressure stems from EPA and OSHA compliance investments that laboratories cannot defer. Reference laboratories exhibit lowest price sensitivity due to volume-scale amortization, while specialty clinics in fragmented outpatient segments negotiate aggressively on per-specimen rates.
Supply Chain Analysis
Warehouse-distribution layers in the United States, Germany, and China maintain regional distribution centers for temperature-sensitive reagents and just-in-time scanner component fulfillment. Supply chains draw from concentrated specialty chemical production in Germany and Switzerland for histology stains, plus precision optics manufacturing in Japan and Germany for whole-slide imaging hardware. Single-source vulnerability persists for high-resolution camera sensors and specialized objective lenses. Distribution runs through distributor-led hub-and-spoke patterns in North America and direct hospital contracts in European centralized networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Pathology departments are shifting procurement toward FDA-validated digital platforms and AI-assisted diagnostic tools that command premium pricing through reimbursement parity and liability risk reduction.
For Market Incumbents: Hedge scanner hardware commoditization by deepening software and algorithm service revenue streams. Lock in laboratory workflows through integrated reagent-instrument platforms that raise switching costs. Counter emerging cloud-native competitors by embedding AI validation partnerships with academic medical centers in the United States and Germany.
For New Entrants and Emerging Players: Computational pathology algorithms offer a technology-first wedge into biomarker quantification services where pathologist shortage creates immediate productivity demand. Target mid-sized hospital systems in the Netherlands and Switzerland lacking capital for full scanner deployment. Pursue telepathology distribution models that bypass traditional distributor markups in fragmented European markets.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional reference laboratory networks with underutilized specimen aggregation potential. Long-term viability centers on scale economies in digital workflow transition rather than legacy histology commoditization. Watch FDA reimbursement parity determinations between digital and glass-slide interpretations as the decisive inflection signal for capital allocation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Pathway Submission | Streamlined premarket review accelerates AI-assisted diagnostic deployment in high-complexity laboratories. |
| Cloud-Native Platform Integration | Remote slide access enables pathologist workforce pooling across rural and metropolitan health systems. |
| Hospital System Partnership | Integrated delivery networks consolidate vendor relationships to secure standardized reporting formats. |
| AI Algorithm Validation Study | Academic medical center partnerships establish clinical evidence for regulatory submissions and market access. |
| Reimbursement Strategy Development | CMS and commercial payer parity determinations shape digital pathology adoption velocity across hospital laboratories. |
Study Parameters
Direct dialogue with hospital laboratory directors, pathology department chairs, GPO contracts managers, and digital pathology platform engineers grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up specimen volume modeling and top-down health system expenditure analysis triangulated market size estimates.
Bottom-up segmentation by product type, technology tier, end-user facility scale, and application area anchored volume projections across the analysis window. CAGRs derived from historical adoption curve analysis for digital pathology infrastructure and pathologist workforce supply-demand modeling. Forecast inputs incorporated NMPA regulatory timeline assumptions for China market entry and EU MDR notified body capacity constraints.
The model holds under stable regulatory transition timelines and reimbursement parity evolution; deviation in FDA premarket review throughput or CMS coverage determinations would shift adoption velocity materially. Forecasts reflect documented assumptions regarding scanner capital cost trajectories and cloud storage economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Eye Testing Equipment Market