
 Pathology Instruments Market | 2026-2036
Pathology Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Pathology Instruments Market Analytics
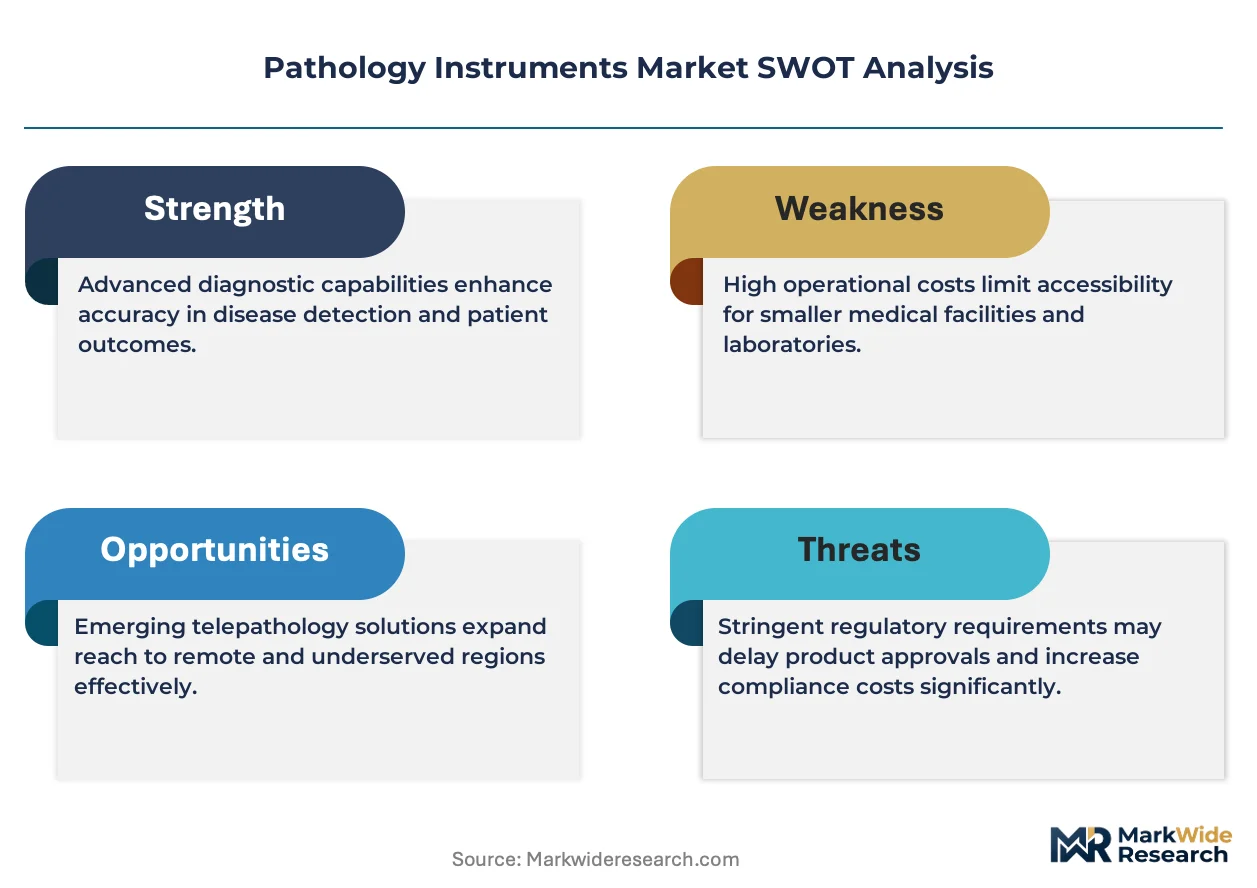
Certified histotechnologist shortages across major healthcare systems is bifurcating the Pathology Instruments Market into automation-intensive and labor-dependent service tiers. Danaher Corporation leverages its life sciences instrumentation portfolio to anchor premium workflow solutions in high-throughput laboratories. Thermo Fisher Scientific competes through integrated reagent-instrument platforms that reduce manual handling steps. Bio-Rad Laboratories specializes in fluorescence-based imaging systems for research-intensive settings.
Pathology instruments encompass devices for tissue preparation, staining, microscopic examination, and digital image capture of biological specimens, typically operating at resolutions from 0.2 micrometers in light microscopy to sub-nanometer scales in electron microscopy variants, with slide scanners now achieving whole-slide imaging at 20x to 40x magnification for remote diagnostic consultation. These instruments serve primarily to enable morphological disease diagnosis, biomarker localization, and quantitative cellular analysis in clinical and research workflows. Digital imaging technology leads installed base expansion as laboratories retrofit legacy brightfield systems for telepathology compliance and AI-assisted screening. Automation in tissue processing represents the fastest-growing technology segment, driven by throughput demands in cancer diagnosis applications where standardized staining protocols reduce inter-operator variability.
The FDA enforces quality system regulation under 21 CFR Part 820 for in vitro diagnostic devices, while the Clinical Laboratory Improvement Amendments mandate proficiency testing that shapes instrument validation requirements across US reference laboratories. In Europe, the In Vitro Diagnostic Regulation transitions notified body oversight toward stricter performance documentation, compressing timelines for new instrument approvals. ISO 15189 accreditation requirements for medical laboratories increasingly specify traceability in automated staining workflows. Stakeholders must monitor how regulatory divergence between FDA and IVDR frameworks influences instrument platform standardization decisions in multinational laboratory networks.
Market Dynamics
Automation in tissue processing is compressing laboratory staffing models while digital imaging retrofits force capital allocation tradeoffs between legacy brightfield systems and whole-slide infrastructure.
Growth Catalysts
- IVDR Transition:The European In Vitro Diagnostic Regulation mandates stricter performance documentation, accelerating instrument platform consolidation in multinational laboratory networks seeking standardized compliance.
- Telepathology Mandates:Remote diagnostic consultation requirements in hospital networks are driving slide scanner installations for AI-assisted screening workflows.
- Cancer Diagnosis Throughput:Standardized automated staining protocols reduce inter-operator variability in high-volume clinical laboratories processing biopsy specimens.
Market Restraints
- Histotechnologist Scarcity:Certified technician shortages constrain laboratory expansion regardless of instrument availability, creating operational bottlenecks in automated workflow deployment.
- Input Cost Volatility:Specialized optical components and precision motion systems face supply concentration risks from German and Japanese component suppliers.
- Regulatory Divergence:Misalignment between FDA quality system regulation and IVDR notified body oversight extends validation timelines for instruments targeting both markets.
Strategic Opportunities
- Research-Intensive Imaging:Fluorescence-based microscopy systems for biomarker localization remain underpenetrated in academic medical centers transitioning to quantitative cellular analysis.
- Reagent-Instrument Integration:Bundled consumable platforms reduce manual handling steps and capture recurring revenue streams in reference laboratory procurement.
- ISO 15189 Accreditation:Medical laboratory certification requirements specifying traceability in automated staining workflows create specification advantages for compliant instrument vendors.
Industry Challenges
- Legacy System Integration:Retrofitting existing brightfield infrastructure for digital capture requires proprietary interface development and disrupts established diagnostic workflows.
- Certification Timeline Compression:IVDR implementation deadlines compress notified body capacity, delaying new instrument approvals and freezing product roadmaps.
- Workflow Standardization:Inter-operator variability in tissue preparation persists despite automation, requiring continuous proficiency testing under CLIA mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pathology Instruments Market |
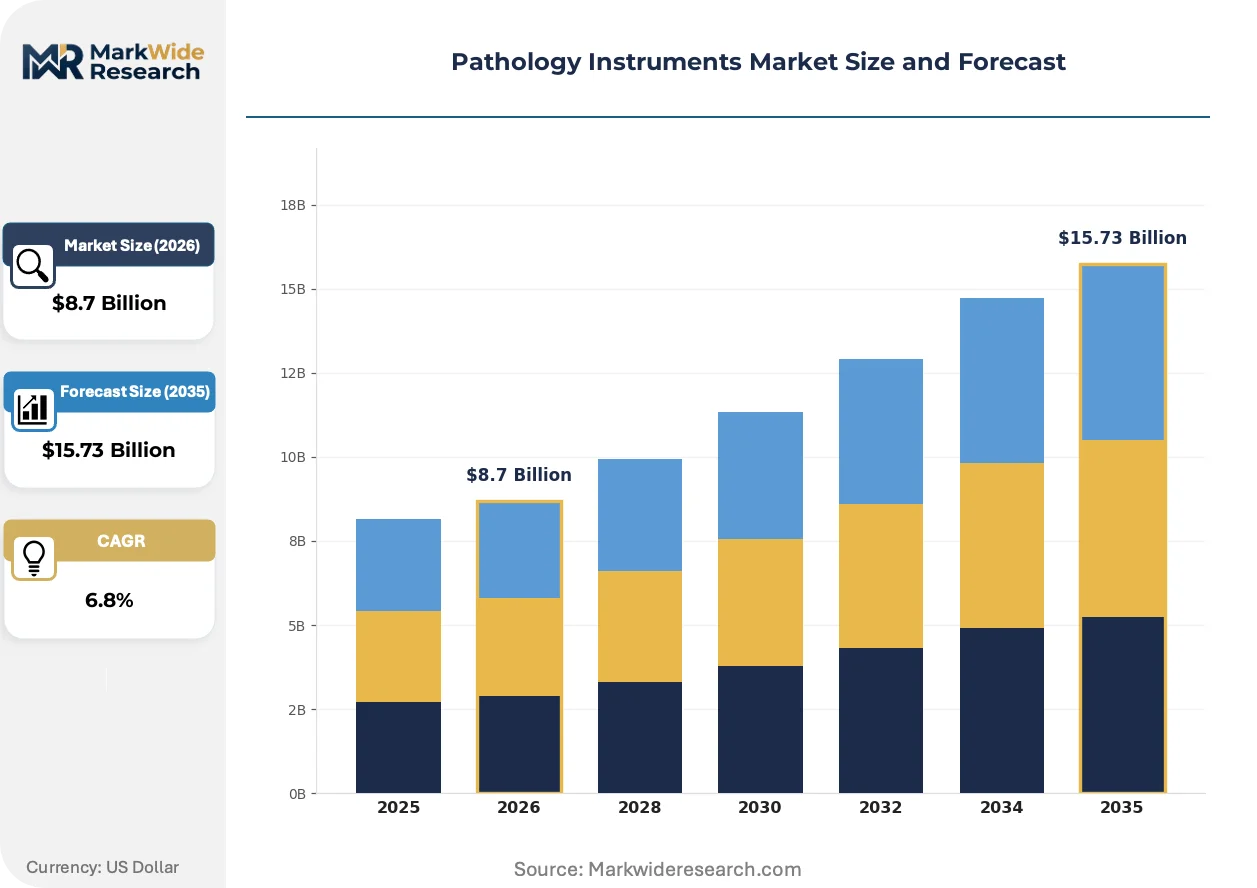
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Stainers, Slide Scanners, Cryostats Technology: Digital Imaging, Fluorescence, Immunohistochemistry, Automation End User: Hospitals, Laboratories, Research Institutions, Clinics Application: Cancer Diagnosis, Infectious Disease Testing, Genetic Testing, Tissue Analysis |
| Companies Covered | Danaher Corporation, Abbott Laboratories, Becton, Dickinson and Company, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific, Bio-Rad Laboratories, Hamamatsu Photonics, Agilent Technologies Inc., PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pathology Instruments Market Evolving Landscape
Digital pathology infrastructure is reshaping competitive positioning around data architecture rather than optical performance alone, with AI-assisted screening capabilities becoming primary selection criteria.
Whole-slide imaging systems operating at 20x to 40x magnification are bifurcating the installed base between laboratories capable of remote diagnostic consultation and those locked into localized brightfield workflows. Academic medical centers and consolidated hospital networks are adopting these platforms aggressively. The technology is bifurcating service tier structures into automation-intensive hubs and labor-dependent satellite laboratories.
REACH substance restrictions and RoHS compliance requirements in Europe are constraining optical component supply chains for mercury-based illumination systems. Manufacturers are accelerating LED and solid-state light source transitions to maintain market access. Fluorescence microscopy segments face the steepest reformulation timelines given spectral precision requirements.
Buying committees in consolidated US hospital networks now weight total cost of ownership over instrument acquisition price, unbundling after-sales service contracts for competitive bidding. Independent service organizations are capturing maintenance revenue previously held by original equipment manufacturers. This pattern is most visible in multi-site health systems centralizing pathology services under regional laboratory hubs.
Pathology Instruments Market Segmentation
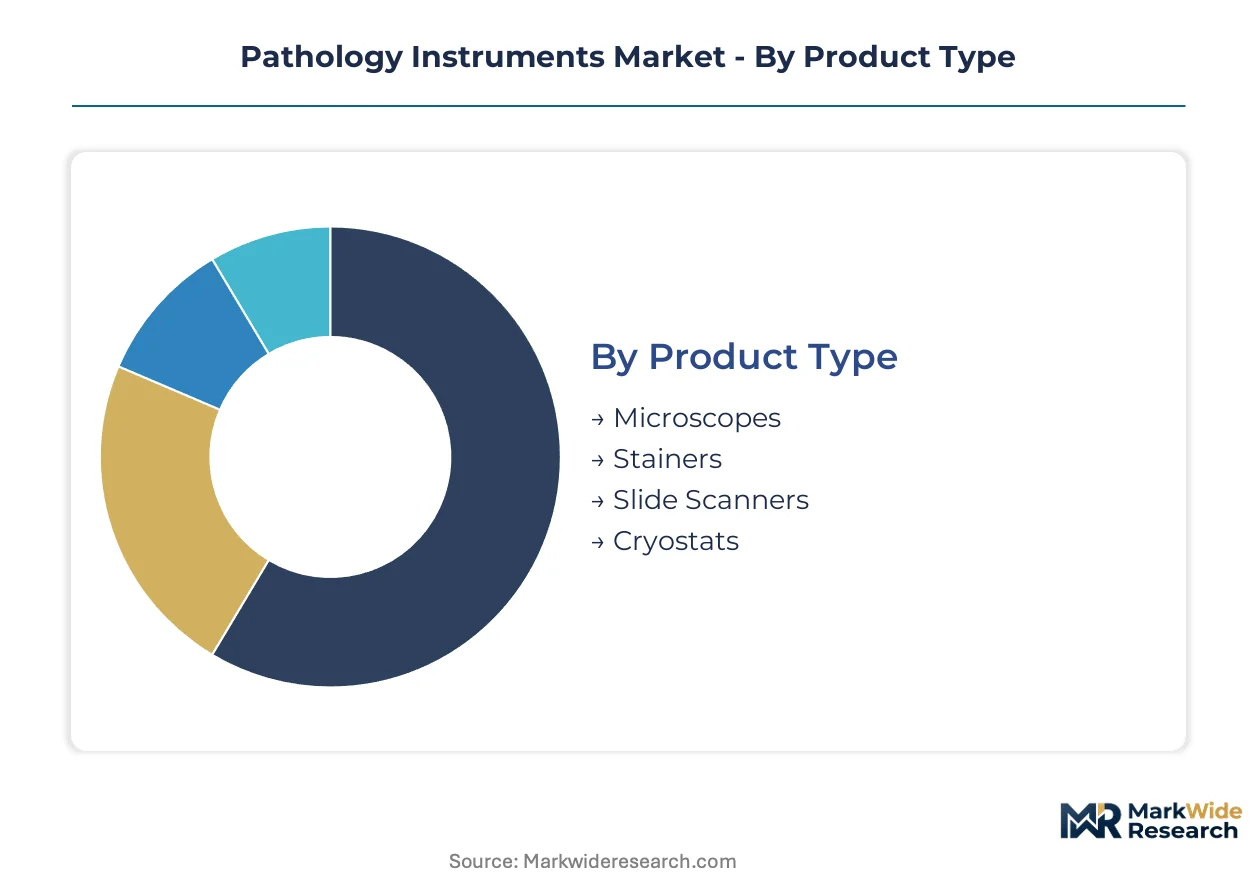
Segmentation in pathology instruments determines procurement pathways and margin structures. Product type governs capital allocation cycles while technology choice locks laboratories into specific consumable ecosystems. End user concentration shapes service contract pricing and geographic deployment priorities.
Product Type:
Microscopes flow through specialized microscopy distributors with technical service capabilities. Stainers and slide scanners deploy through laboratory supply consortia. Cryostats concentrate in direct manufacturer relationships due to installation complexity.
- Microscopes:Brightfield and fluorescence configurations remain the foundational diagnostic platform. Demand concentrates in German hospital networks consolidating pathology services under centralized hubs, driven by IVDR-mandated performance documentation requirements.
- Stainers:Automated tissue processing systems standardize staining protocols across high-throughput laboratories. US clinical laboratories expand capacity as FDA tightens quality controls, compressing staffing models while reducing inter-operator variability.
- Slide Scanners:Whole-slide imaging at 20x to 40x magnification enables telepathology compliance.
- Cryostats:Frozen section preparation systems serve intraoperative consultation workflows.
Microscopes dominate installed base. Slide scanners are where expansion concentrates.
Technology:
Technology selection determines consumable lock-in and service revenue streams. Digital imaging retrofits force capital allocation tradeoffs. Fluorescence systems command premium positioning in research-intensive settings.
- Digital Imaging:Whole-slide capture and remote consultation infrastructure reshape competitive positioning around data architecture. Academic medical centers in the United States adopt these platforms aggressively for AI-assisted screening workflows.
- Automation:Robotic tissue processing and staining workflows compress laboratory staffing models. German hospital networks drive demand as centralized laboratory hubs consolidate pathology services under standardized protocols.
- Fluorescence:Spectral imaging systems for biomarker localization face REACH substance restrictions on mercury-based illumination.
- Immunohistochemistry:Antigen detection protocols require validated reagent-instrument integration.
Digital imaging commands highest capital intensity. Automation is climbing the fastest.
End User:
End user type dictates purchasing committee composition and contract structure. Hospitals weight total cost of ownership over acquisition price. Research institutions prioritize optical performance specifications.
- Hospitals:Consolidated US hospital networks centralize pathology services under regional laboratory hubs. Buying committees unbundle after-sales service contracts for competitive bidding as independent service organizations capture maintenance revenue.
- Laboratories:Reference laboratories process high biopsy volumes requiring standardized automated staining. CLIA-mandated proficiency testing shapes instrument validation requirements across US facilities.
- Research Institutions:Academic medical centers transition to quantitative cellular analysis.
- Clinics:Smaller diagnostic facilities rely on labor-dependent workflows.
Laboratories anchor volume procurement. Hospitals are where platform consolidation accelerates.
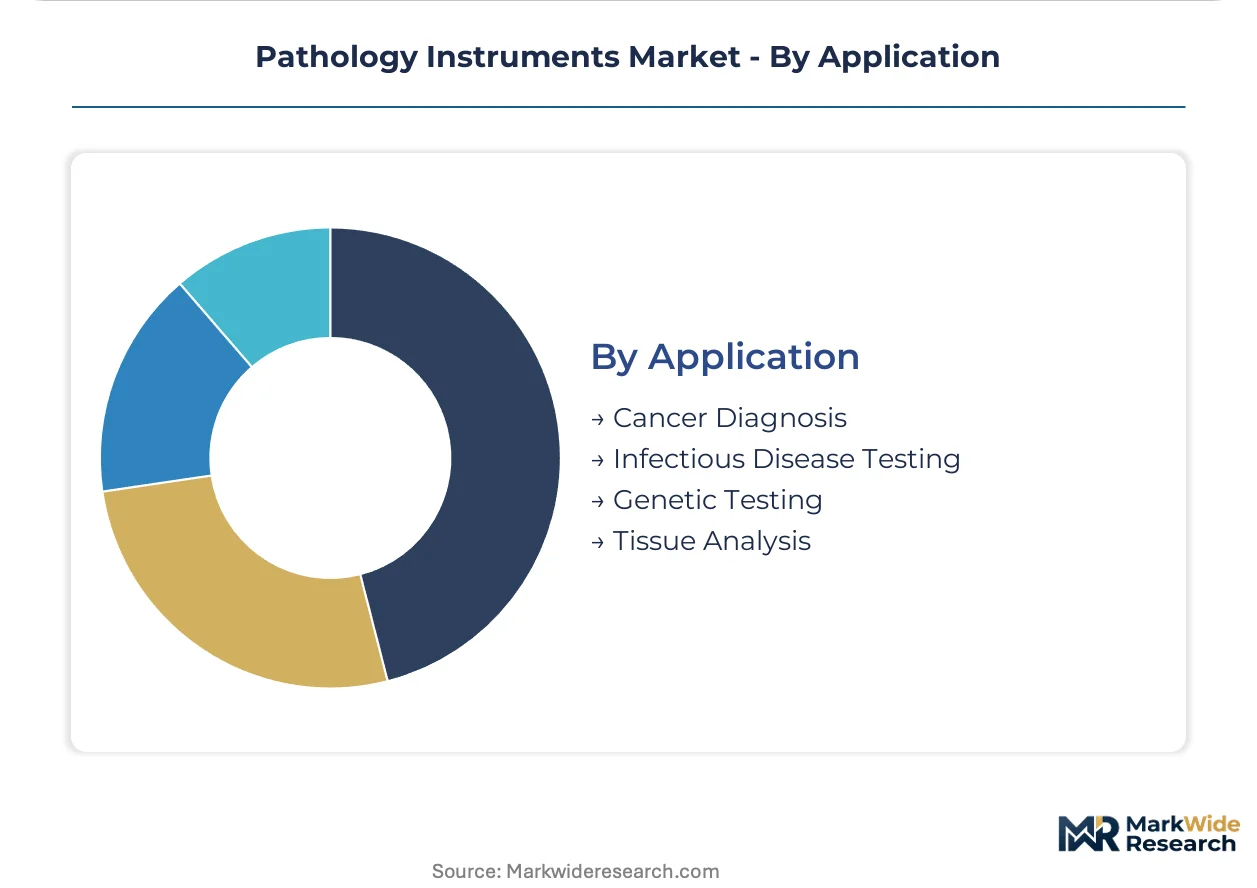
Application:
Application focus determines throughput requirements and regulatory scrutiny intensity. Cancer diagnosis demands highest automation levels. Genetic testing drives fluorescence imaging adoption.
- Cancer Diagnosis:Biopsy specimen processing at scale requires automated staining protocols. US clinical laboratories expand capacity under FDA quality system regulation enforcement, reducing manual handling variability.
- Tissue Analysis:Morphological assessment workflows span brightfield microscopy through whole-slide imaging. German hospital networks consolidate services under ISO 15189 accreditation requirements specifying traceability.
- Infectious Disease Testing:Rapid pathogen identification protocols prioritize turnaround time.
- Genetic Testing:Biomarker localization and molecular pathology applications.
Cancer diagnosis anchors capital deployment. Tissue analysis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys pathology instruments for centralized hub consolidation while the United States prioritizes FDA-mandated quality system upgrades. Japan emphasizes precision optical manufacturing for export markets. China scales domestic production to reduce import dependency. India expands reference laboratory networks to serve diagnostic demand growth.
Germany
Hospital networks consolidate pathology services under centralized laboratory hubs in North Rhine-Westphalia and Bavaria. The In Vitro Diagnostic Regulation mandates stricter performance documentation, accelerating platform standardization. Munich and Heidelberg host precision optics clusters supplying specialized illumination components.
United States
Clinical laboratories expand automated tissue processing capacity as biopsy volumes rise. FDA enforces quality system regulation under 21 CFR Part 820, tightening validation requirements. Greater Boston and Research Triangle Park anchor digital pathology development for AI-assisted screening workflows.
Japan
Academic medical centers adopt fluorescence microscopy for quantitative cellular analysis. METI supports precision manufacturing standards for optical component exports. Hamamatsu and Tokyo metropolitan areas concentrate solid-state light source development replacing mercury-based systems.
China
Domestic manufacturers scale slide scanner production to capture telepathology infrastructure demand. NMPA strengthens diagnostic device registration requirements under revised medical device regulations. Shanghai and Suzhou clusters develop automated staining platforms for cancer diagnosis throughput.
India
Reference laboratories process rising biopsy specimen volumes in metropolitan centers. CDSCO implements medical device rules requiring traceability in automated workflows. Maharashtra and Karnataka states concentrate diagnostic hub expansion serving tier-two city networks.
Pathology Instruments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Pathology Instruments Market. Danaher Corporation and Thermo Fisher Scientific anchor premium workflow solutions through life sciences instrumentation portfolios. Specialists occupy fluorescence imaging and reagent-instrument integration niches. Competitive moves concentrate on reagent-instrument bundling and digital platform consolidation for telepathology compliance.
Within the integrated instrumentation tier, Danaher Corporation and Thermo Fisher Scientific exemplify scale-driven platform strategies. Danaher leverages workflow automation across high-throughput laboratory networks. Thermo Fisher competes through consumable-instrument integration reducing manual handling steps. Bio-Rad Laboratories occupies the research-intensive imaging segment specializing in fluorescence-based systems for biomarker localization.
| Leading Market Players |
|---|
| Danaher Corporation |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Hamamatsu Photonics |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| Others |
Value Network & Pricing Analysis
High-throughput laboratory consolidation in Germany and the United States generates scale economies that compress unit costs for automated staining platforms while simultaneously elevating price floors for specialized optical components sourced from precision manufacturing clusters. This dynamic concentrates margin capture among integrated instrumentation vendors capable of bundling consumable streams with capital equipment deployment.
Pricing Analysis
Long-term service contracts dominate procurement in consolidated US hospital networks, unbundling after-sales agreements for competitive bidding while independent service organizations capture maintenance revenue previously held by original equipment manufacturers. Price differentiation stems from ISO 15189 accreditation tier and after-sales service bundling intensity. Cost compression in mid-tier stainers intensifies as domestic manufacturers in China scale automated platform production. Reference laboratories exhibit highest price sensitivity due to volume procurement leverage, while academic medical centers prioritize optical performance specifications over acquisition cost.
Supply Chain Analysis
Germany and Japan anchor precision optical component manufacturing for specialized illumination systems and precision motion assemblies used in fluorescence microscopy and whole-slide imaging platforms. Supply chains draw from mercury-based light sources facing REACH substance restrictions, solid-state LED alternatives, and high-grade optical glass feedstock. Single-source vulnerability concentrates in German precision optics clusters supplying spectral illumination components. Distribution runs through laboratory supply consortia for stainers and slide scanners, with cryostats deploying through direct manufacturer relationships due to installation complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital pathology platform economics are shifting value capture from optical hardware specifications toward data architecture and AI-assisted screening interoperability, with telepathology compliance mandates accelerating ecosystem consolidation around integrated workflow vendors.
For Market Incumbents: Shield installed base positions by deepening reagent-instrument integration that locks reference laboratories into recurring consumable revenue streams. Accelerate ISO 15189 accreditation alignment for automated staining traceability to preempt specification advantages from emerging competitors. Prioritize backward integration into solid-state light source manufacturing to mitigate REACH-driven supply disruption risks in fluorescence imaging segments. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for slide scanner platforms offer regulatory arbitrage opportunities against IVDR-constrained European competitors. White-space concentration exists in research-intensive fluorescence imaging for academic medical centers transitioning to quantitative cellular analysis, where incumbent bundling strategies penetrate weakly. Direct-to-laboratory digital pathology subscription models bypass consolidated hospital network procurement committees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reagent-instrument integration specialists with captive consumable streams over pure-play hardware vendors facing digital retrofit margin compression. Long-term viability rests on AI-assisted screening algorithm development capabilities and telepathology infrastructure deployment scale. The signal to watch is IVDR notified body capacity constraints easing, which would unlock frozen European product roadmaps and accelerate platform consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Integration | Bundled consumable platforms capture recurring revenue in CLIA-mandated proficiency testing environments. |
| ISO 15189 Accreditation Alignment | Medical laboratory certification requirements create specification barriers for non-compliant instrument vendors. |
| Digital Pathology Platform Launch | Whole-slide imaging at 20x to 40x magnification enables AI-assisted screening workflow adoption in academic centers. |
| REACH Compliance Transition | LED and solid-state light source development maintains European market access for fluorescence microscopy segments. |
| Regional Laboratory Hub Partnership | Consolidated German hospital networks centralize pathology services under standardized automated workflow protocols. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with histotechnologists, laboratory directors, biomedical engineers, and GPO contracts managers across US and European healthcare systems. Secondary validation drew from FDA 510(k) filings, IVDR notified body documentation, hospital procurement databases, and CLIA proficiency testing records. Bottom-up instrument shipment estimates triangulated against top-down healthcare capital expenditure projections across the analysis window.
Across the modeling period, segmentation dimensions included product type, technology platform, end-user concentration, and application intensity with cancer diagnosis throughput as a specific weighting factor. CAGRs were derived from installed base expansion rates and replacement cycle compression in digital imaging retrofits. Forecast inputs incorporated biopsy volume growth trajectories and regulatory timeline shifts between FDA quality system regulation and IVDR implementation deadlines.
Underlying assumptions cover telepathology mandate adoption curves and histotechnologist labor availability, with deviation risk concentrated in IVDR notified body capacity constraints and REACH substance restriction enforcement timelines. Recalibration cycles align with material shifts in regulatory divergence patterns and digital pathology platform consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Nasometry Devices Market