
 Immunoassay Instruments Market | 2026-2036
Immunoassay Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoassay Instruments Market Outlook
IVDR implementation in Europe is pivoting the cost-of-entry calculus for instrument manufacturers seeking CE-marked placement. Abbott leverages its vertically integrated reagent-instrument ecosystem to sustain compliance economies that smaller rivals cannot match. Siemens Healthineers anchors its position through automated workstation architectures that dominate high-throughput hospital laboratory workflows.
Immunoassay instruments are analytical systems that detect and quantify target analytes through antigen-antibody binding reactions, typically achieving sensitivity thresholds in the picogram-per-milliliter range via chemiluminescent or fluorescent signal amplification. These systems serve primarily as diagnostic infrastructure for clinical decision-making, therapeutic monitoring, and epidemiological surveillance. Automated workstation configurations within the technology dimension concentrate margin pools through reagent-locked consumable streams and service contracts. Chemiluminescent immunoassay platforms within product type classifications lead volume placement due to superior dynamic range and multiplexing capacity, while radioimmunoassay segments retain niche utility in reference laboratories handling specialized endocrinology panels.
FDA oversight through CLIA complexity categorization shapes instrument design requirements for moderate-to-high complexity testing environments, while EMA's IVDR framework mandates post-market surveillance infrastructure that reshapes distributor obligations across European member states. ISO 13485 quality management certification functions as a baseline predicate for market access in both jurisdictions. Stakeholders must weigh regulatory compliance burn rates against the defensive moat that certified manufacturing creates for incumbent positions.
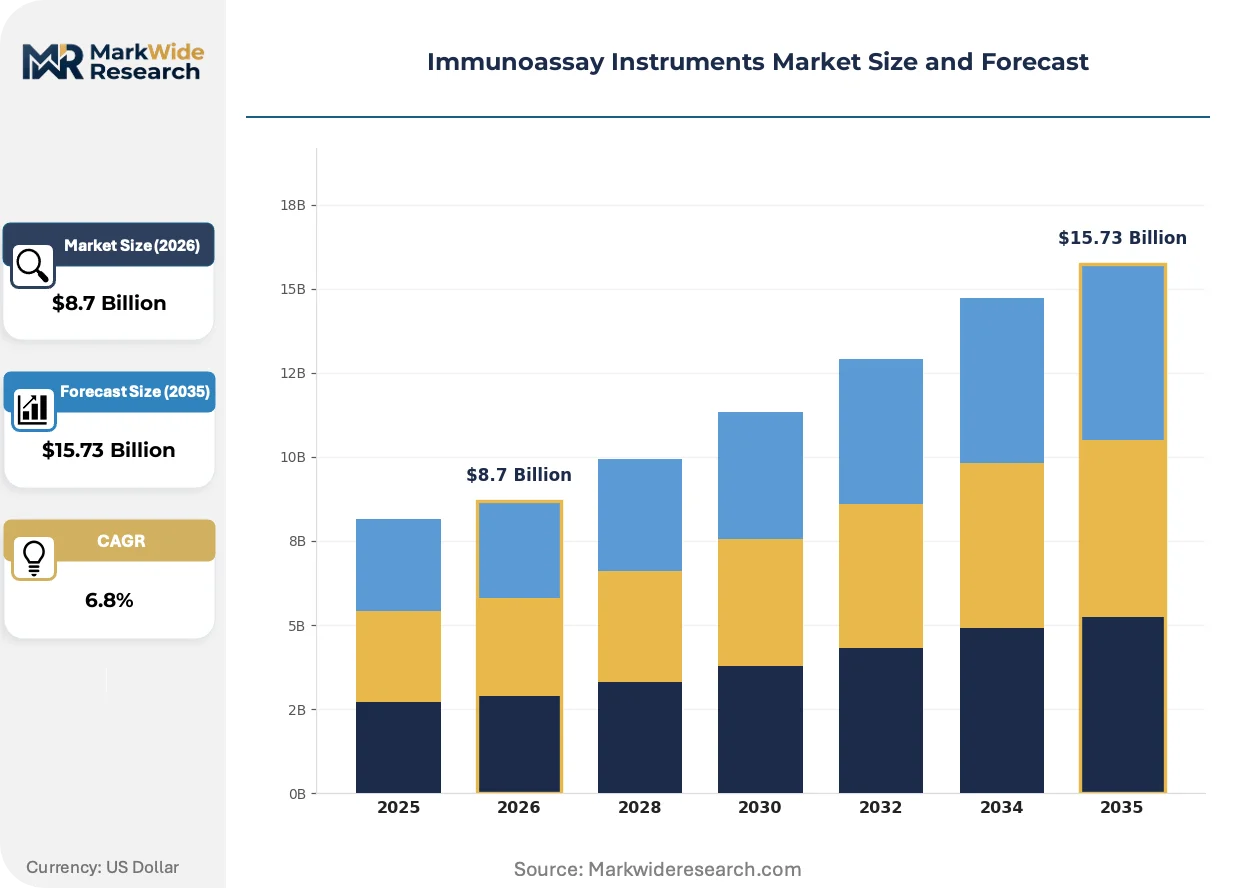
Market Dynamics
IVDR compliance timelines are compressing vendor decision windows across Europe, forcing instrument manufacturers to absorb post-market surveillance infrastructure costs or surrender CE-marked positions to vertically integrated competitors with captive regulatory affairs teams.
Growth Catalysts
- CLIA complexity escalation:FDA reclassification of moderate-complexity tests is driving hospital laboratories toward fully automated chemiluminescent platforms that internalize quality control protocols.
- Centralized laboratory consolidation:Germany's hospital network restructuring is concentrating procurement authority at regional hub laboratories with standardized instrument specifications.
- Multiplexing throughput demands:Infectious disease surveillance programs require simultaneous analyte detection capabilities that single-analyte enzyme immunoassay systems cannot deliver.
Market Restraints
- Reagent lock-in economics:Closed-system architectures tether hospitals to proprietary consumable streams with limited third-party alternatives, inflating lifetime cost-of-ownership calculations.
- Radioisotope supply fragility:Iodine-125 and tritium sourcing constraints from limited production facilities create batch-to-batch variability risks for radioimmunoassay reference laboratories.
- IVDR technical documentation burdens:European notified body capacity bottlenecks are extending conformity assessment timelines beyond eighteen months for novel instrument submissions.
Strategic Opportunities
- Point-of-care decentralization:India's district hospital network expansion under the Ayushman Bharat scheme creates placement opportunities for compact chemiluminescent analyzers with simplified maintenance protocols.
- AI-assisted result interpretation:Machine learning algorithms integrated into instrument software are reducing manual validation burdens for high-volume thyroid and fertility panels.
- Biomarker menu expansion:Emerging protein-based sepsis signatures and Alzheimer's blood tests are opening new assay development partnerships between platform vendors and biopharmaceutical sponsors.
Industry Challenges
- Field service engineer scarcity:Specialized training requirements for electrochemiluminescence optics and fluidic systems outpace vocational program output in secondary metropolitan markets.
- Legacy LIS integration friction:Hospital information system heterogeneity forces costly middleware development for bidirectional data exchange with existing laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoassay Instruments Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme-Linked Immunosorbent Assay, Radioimmunoassay, Fluorescent Immunoassay, Chemiluminescent Immunoassay Technology: Microplate Readers, Automated Workstations, Liquid Handling Systems, Detection Systems Application: Clinical Diagnostics, Food Safety Testing, Environmental Monitoring, Pharmaceutical Research End User: Hospitals, Research Laboratories, Diagnostic Centers, Pharmaceutical Companies |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Thermo Fisher Scientific Inc., Danaher, Beckman Coulter, Inc., bioMérieux, DiaSorin S.p.A., QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoassay Instruments Market Strategic Shifts
Instrument architectures are converging toward modular, software-defined platforms that separate detection hardware from assay-specific reagent cartridges, enabling vendors to refresh test menus without full-system replacement cycles.
Magnetic microparticle chemiluminescence is unifying previously separate immunoassay and molecular diagnostics workflows onto single-track automation. Academic medical centers in the United States are piloting these consolidated workstations for STAT infectious disease and oncology panels. The technology is unifying capital allocation decisions by collapsing two instrument categories into one procurement negotiation.
EMA's IVDR Article 10 post-market surveillance mandates now require proactive vigilance reporting for instrument-analyte combinations with elevated failure rates. Manufacturers must maintain dedicated pharmacovigilance infrastructure or delegate to authorized representatives with documented competency. High-throughput hospital laboratories in France and the Netherlands are prioritizing vendors with established European regulatory affairs presence over entrants dependent on distributor-led compliance.
Consolidated procurement consortia are displacing individual hospital purchasing autonomy across Nordic health systems. Regional procurement bodies in Sweden and Denmark now negotiate multi-year instrument leases with guaranteed reagent minimums, compressing vendor margins while locking in placement security. This concentration is most visible in oncology and endocrinology testing lines where standardization across hospital networks reduces inter-laboratory variability concerns.
Immunoassay Instruments Market Segmentation
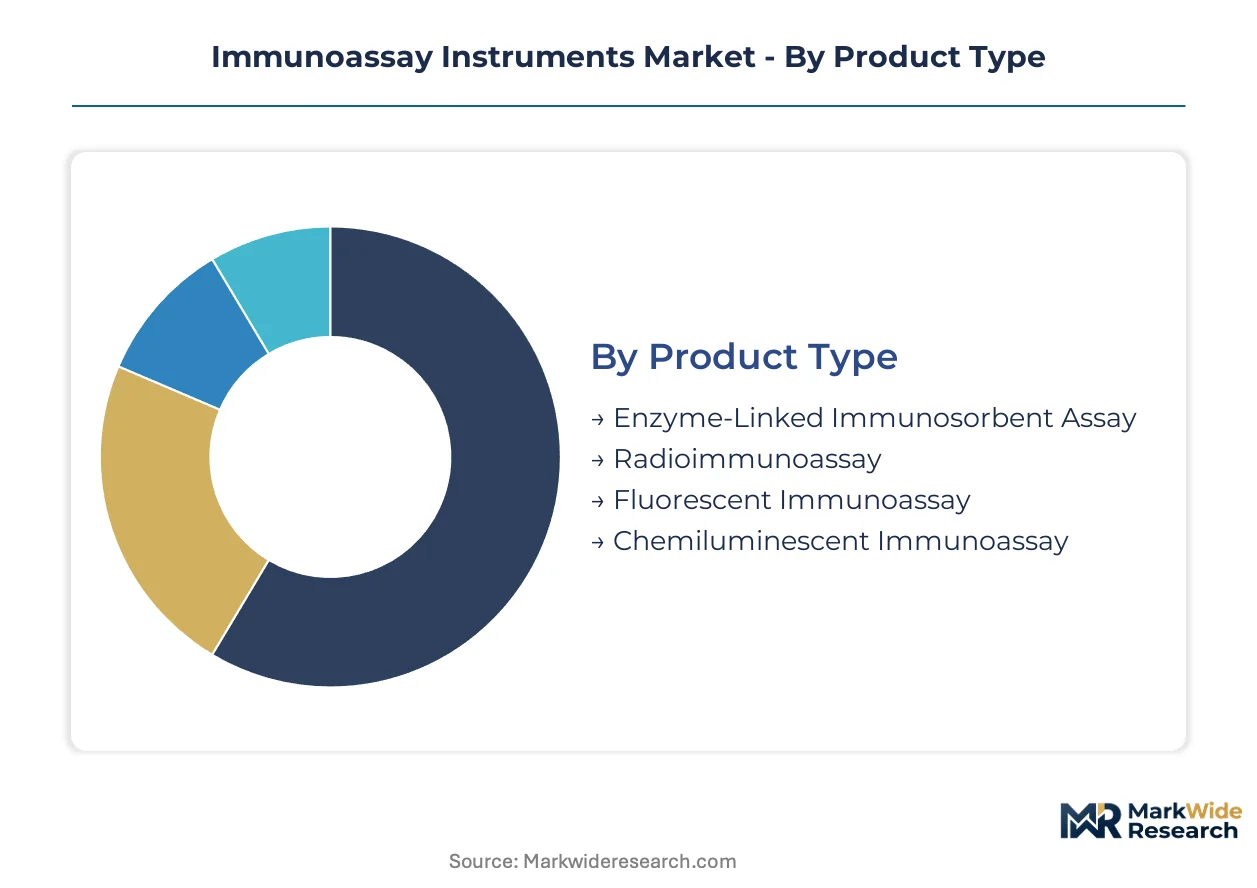
Immunoassay instrument architectures fragment across detection chemistry, automation level, and end-use environment, with each dimension imposing distinct engineering constraints and margin structures. Procurement patterns diverge sharply between centralized hospital laboratories demanding throughput and research settings prioritizing assay flexibility.
Product Type:
Supply concentration in chemiluminescent platforms reflects manufacturing scale economies in optical detection modules and magnetic microparticle handling systems.
- Chemiluminescent Immunoassay:Signal amplification through acridinium ester or alkaline phosphatase substrates achieves femtomolar sensitivity thresholds. Hospital laboratories in Germany and the United States concentrate procurement of these platforms under IVDR and CLIA frameworks that prioritize reproducible high-throughput workflows.
- Enzyme-Linked Immunosorbent Assay:Colorimetric detection via horseradish peroxidase conjugates dominates research and food safety applications where capital constraints outweigh speed requirements. Academic laboratories in India and Brazil retain substantial installed bases of manual plate-wash configurations.
- Radioimmunoassay:Iodine-125 labeled tracers retain niche utility in reference endocrinology panels requiring absolute quantification without matrix interference.
- Fluorescent Immunoassay:Europium chelate time-resolved detection serves point-of-care infectious disease screening where compact footprint overrides multiplexing capacity.
Today's leader: Chemiluminescent Immunoassay. Tomorrow's challenger: Fluorescent Immunoassay.
Technology:
Margin structures concentrate in automated workstation configurations that internalize reagent handling, incubation, and detection within closed architectures.
- Automated Workstations:Integrated sample-to-result systems with random-access scheduling dominate hospital laboratory procurement in France and the Netherlands. Siemens Healthineers anchors this tier through standardized regional hub contracts that specify guaranteed uptime clauses.
- Detection Systems:Modular photomultiplier tube and CCD camera units enable assay menu refreshes without full instrument replacement. Research laboratories in the United States prefer this flexibility for biomarker development partnerships.
- Liquid Handling Systems:Precision pipetting robotics reduce technician exposure to biohazardous samples in high-volume diagnostic centers.
- Microplate Readers:Entry-tier absorbance and fluorescence endpoints serve resource-constrained environmental monitoring stations in secondary Indian cities.
Reagent lock-in economics favor Automated Workstations. Open architecture modularity sustains Detection Systems.
Application:
Volume concentration in clinical diagnostics reflects therapeutic decision dependency and reimbursement code density across OECD health systems.
- Clinical Diagnostics:Thyroid, fertility, and infectious disease panels generate recurring revenue through standardized assay protocols. Centralized laboratory networks in Sweden and Denmark negotiate multi-year reagent minimums that compress vendor margins while securing placement.
- Pharmaceutical Research:Pharmacokinetic and immunogenicity studies demand custom assay development with biopharmaceutical sponsors. Contract research organizations in Massachusetts and Basel concentrate specialized chemiluminescent platform installations.
- Food Safety Testing:Mycotoxin and allergen detection protocols align with EU Regulation 1881/2006 maximum residue limits for import compliance.
- Environmental Monitoring:Endocrine disruptor surveillance in watersheds employs competitive ELISA formats where field portability outweighs laboratory precision.
Clinical Diagnostics commands current revenue concentration. Pharmaceutical Research offers the steepest expansion trajectory through biomarker co-development partnerships.
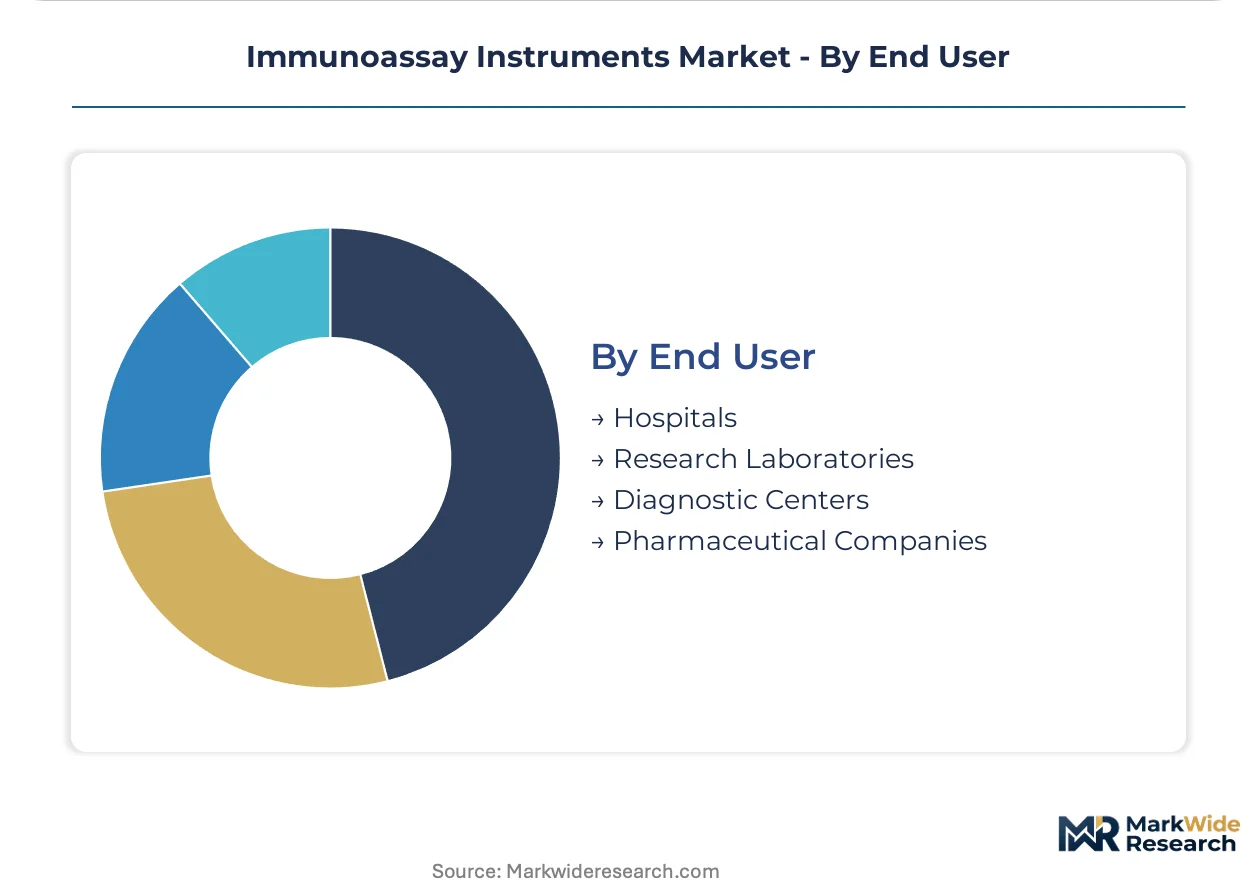
End User:
Procurement authority concentration in hospital networks reflects diagnostic service centralization under Germany's hospital restructuring and India's Ayushman Bharat district hospital expansion.
- Hospitals:Regional hub laboratories in North Rhine-Westphalia and Tamil Nadu consolidate instrument specifications to reduce inter-laboratory variability. FDA CLIA complexity categorization shapes their preference for fully automated platforms with internalized quality control.
- Diagnostic Centers:Independent reference laboratories in Texas and São Paulo compete on turnaround time for STAT infectious disease panels.
- Research Laboratories:Academic medical centers pilot magnetic microparticle chemiluminescence for consolidated infectious disease and oncology workflows.
- Pharmaceutical Companies:In-house bioanalytical groups at large-cap sponsors maintain captive instrument fleets for clinical trial sample analysis.
Hospitals dominate current placement volume. Diagnostic Centers are gaining share fastest through decentralized testing network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The immunoassay instruments industry traces its commercial origins to mid-20th century radioimmunoassay development in the United States, with subsequent chemiluminescent platform scaling concentrated in German and Swiss precision engineering clusters through the 1980s and 1990s.
United States
Hospital laboratory consolidation and CLIA complexity reclassification drive automated platform procurement. FDA oversight through 510(k) and CLIA frameworks mandates quality control internalization for moderate-to-high complexity testing. Academic medical centers in Massachusetts and California pilot magnetic microparticle chemiluminescence for consolidated infectious disease workflows.
Germany
Regional hub laboratory restructuring under hospital network centralization concentrates procurement authority at scale. EMA IVDR implementation tightens post-market surveillance obligations for CE-marked instrument placement. North Rhine-Westphalia's laboratory networks specify standardized chemiluminescent platform specifications across multiple hospital sites.
India
District hospital network expansion under Ayushman Bharat generates demand for compact analyzers with simplified maintenance protocols. CDSCO medical device regulations align with risk-based classification for diagnostic instrument import and manufacture. Tamil Nadu's diagnostic infrastructure buildout concentrates placement opportunities in secondary metropolitan markets.
Japan
Aging demographics and chronic disease monitoring sustain high-throughput endocrinology and thyroid panel demand. PMDA pharmaceutical and medical device agency oversees instrument approval through harmonized international standards. Kanto region hospital networks prioritize vendors with established domestic service engineering capabilities.
Switzerland
Reference laboratory precision requirements and biopharmaceutical contract research sustain specialized platform demand. Swissmedic medical device regulations enforce conformity assessment for active diagnostic equipment. Basel's concentration of pharmaceutical sponsors drives captive instrument fleets for clinical trial bioanalysis.
Immunoassay Instruments Market Competitive Environment
The competitive structure tilts toward vertically integrated multinational conglomerates with captive reagent-instrument ecosystems. Three archetypes dominate: diversified diagnostics conglomerates with full workflow automation portfolios, specialized chemiluminescent platform vendors with regional service density, and research-oriented suppliers with modular open architectures. Competitive moves concentrate on strategic partnerships for biomarker assay co-development and geographic expansion through distributor consolidation in emerging markets.
Among diversified diagnostics conglomerates, Abbott and Siemens Healthineers occupy positions exemplifying the reagent-locked consumable stream model, while F. Hoffmann-La Roche Ltd anchors the premium-tier precision diagnostics archetype through integrated instrument-reagent-service bundling. These entities represent the compliance economies and post-market surveillance infrastructure scale that IVDR and CLIA frameworks increasingly favor over fragmented competitors.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Thermo Fisher Scientific Inc. |
| Danaher |
| Beckman Coulter, Inc. |
| bioMérieux |
| DiaSorin S.p.A. |
| QuidelOrtho Corporation |
| Others |
Value Chain & Pricing Dynamics
Instrument-reagent bundling splits the market into locked-ecosystem premium tiers and modular open-architecture alternatives, with Abbott and Siemens Healthineers commanding pricing power through captive consumable streams while smaller vendors compete on capital equipment flexibility. This bifurcation concentrates margin extraction in automated workstation configurations where service contracts and reagent minimums extend revenue recognition over multi-year placement cycles.
Pricing Analysis
Bundled service contracts versus unbundled equipment-only procurement defines pricing architecture across hospital laboratory networks. Three-tier pricing structure across premium, standard, and economy levels reflects IVDR certification grade, CLIA complexity tier, and geographic service density. Cost compression in economy-tier manual platforms intensifies because Indian and Brazilian procurement authorities prioritize capital expenditure minimization over lifetime cost-of-ownership. Diagnostic centers in São Paulo and Texas exhibit highest price sensitivity due to competitive turnaround-time pressures, while German regional hub laboratories demonstrate lowest sensitivity given standardized reagent-locked specifications.
Supply Chain Analysis
Photomultiplier tube and CCD sensor supply rests on Japanese and German precision optics manufacturers with limited alternative sourcing. Magnetic microparticle chemiluminescence substrates draw from Swiss and US specialty chemical producers, while precision fluidic components source from German micromachining clusters. Single-source vulnerability concentrates in iodine-125 radioisotope production facilities located in Canada and South Africa. Distribution runs through authorized representative networks in Europe and direct field service organizations in North America, with emerging markets relying on distributor-led technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunoassay instruments market functions as a stable compounder where chronic disease monitoring volumes and regulatory compliance mandates generate recurring replacement demand across decade-long instrument lifecycles.
For Market Incumbents: Deploy reagent-locked ecosystem extensions to neutralize modular open-architecture challengers. Siemens Healthineers anchors regional hub contracts through guaranteed uptime clauses that embed switching costs. Abbott sustains compliance economies of scale through vertically integrated regulatory affairs teams that absorb IVDR documentation burdens smaller rivals cannot match. Capacity addition in Tamil Nadu and North Rhine-Westphalia secures placement density ahead of distributor consolidation.
For New Entrants and Emerging Players: Independent reference laboratories represent the most penetrable channel partner type for compact chemiluminescent platforms with simplified maintenance protocols. India's Ayushman Bharat district hospital expansion offers white-space placement opportunity where established vendors lack service engineering density. AI-assisted result interpretation modules provide differentiation angle for thyroid and fertility panel automation without full workstation capital requirements.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized chemiluminescent platform vendors possessing regional service density and biomarker co-development partnerships. Five-to-ten year viability hinges on IVDR compliance infrastructure and post-market surveillance capabilities rather than hardware innovation alone. Acquisition target archetype: mid-cap European vendors with established notified body relationships and captive reagent manufacturing. Signal to watch: EMA pharmacovigilance enforcement actions that disqualify distributor-dependent compliance models.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR technical documentation investment defends European placement against notified body capacity bottlenecks. |
| Hospital System Partnership | Multi-year reagent minimum contracts in Sweden and Denmark lock out modular competitors through standardization. |
| Software Companion Development | AI-assisted result interpretation reduces manual validation burdens for high-volume thyroid panels. |
| Reimbursement Strategy | CLIA complexity reclassification alignment secures favorable CMS coding for automated platforms. |
| Biomarker Assay Co-development | Sepsis signature and Alzheimer's blood test partnerships open new revenue streams beyond established panels. |
Study Parameters
Direct dialogue with hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists informed qualitative grounding across North American and European procurement networks. Secondary validation drew from FDA 510(k) filings, EMA IVDR technical documentation summaries, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up instrument placement estimates triangulated against top-down market size assessments derived from reagent stream revenue disclosures.
Bottom-up modeling segmented volume and value across product type, automation level, application, and end-user archetype throughout the forecast period. Detection chemistry, throughput capacity, and geographic regulatory cluster dimensions captured technology substitution dynamics. CAGRs emerged from weighted average growth across segment-level demand drivers including CLIA complexity escalation, IVDR compliance timelines, and district hospital network expansion patterns.
Revisions become necessary when IVDR notified body capacity constraints extend beyond current assessment timelines, radioisotope supply disruptions alter reference laboratory economics, or AI-assisted diagnostic algorithms trigger FDA software-as-medical-device reclassification. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Electroporation Instruments Market