
 Global Wavefront Aberrometers Market | 2026-2036
Global Wavefront Aberrometers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wavefront Aberrometers Market Foresight
Software-defined wavefront analysis modules bundled with annual calibration subscriptions is repositioning how ophthalmic equipment vendors monetize hardware deployments. Carl Zeiss Meditec AG leverages its integrated surgical workflow software to lock in recurring revenue across refractive laser suites. Johnson & Johnson Vision anchors its competitive stance through proprietary wavefront-to-treatment planning algorithms that tighten clinician switching costs. Nidek Co. Ltd. specializes in compact tabletop systems that dominate high-volume screening environments across Asia-Pacific eye hospitals.
Wavefront aberrometers are precision diagnostic instruments that measure optical aberrations across the entire eye using wavefront sensing technology, typically resolving aberrations up to the sixth order or higher with micron-level accuracy at the pupil plane. These systems generate detailed ocular maps that guide excimer laser ablation profiles, orthokeratology lens designs, and corneal pathology assessments. Shack-Hartmann systems occupy the mature core of installed bases where replacement cycles now drive the majority of revenue. Adaptive optics technology represents the fastest-expanding segment as research institutes deploy high-resolution retinal imaging configurations that extend diagnostic capabilities beyond standard clinical practice. Hartmann-Shack sensing remains the dominant technology layer across commercial preoperative assessment applications where proven reimbursement pathways sustain margin pools.
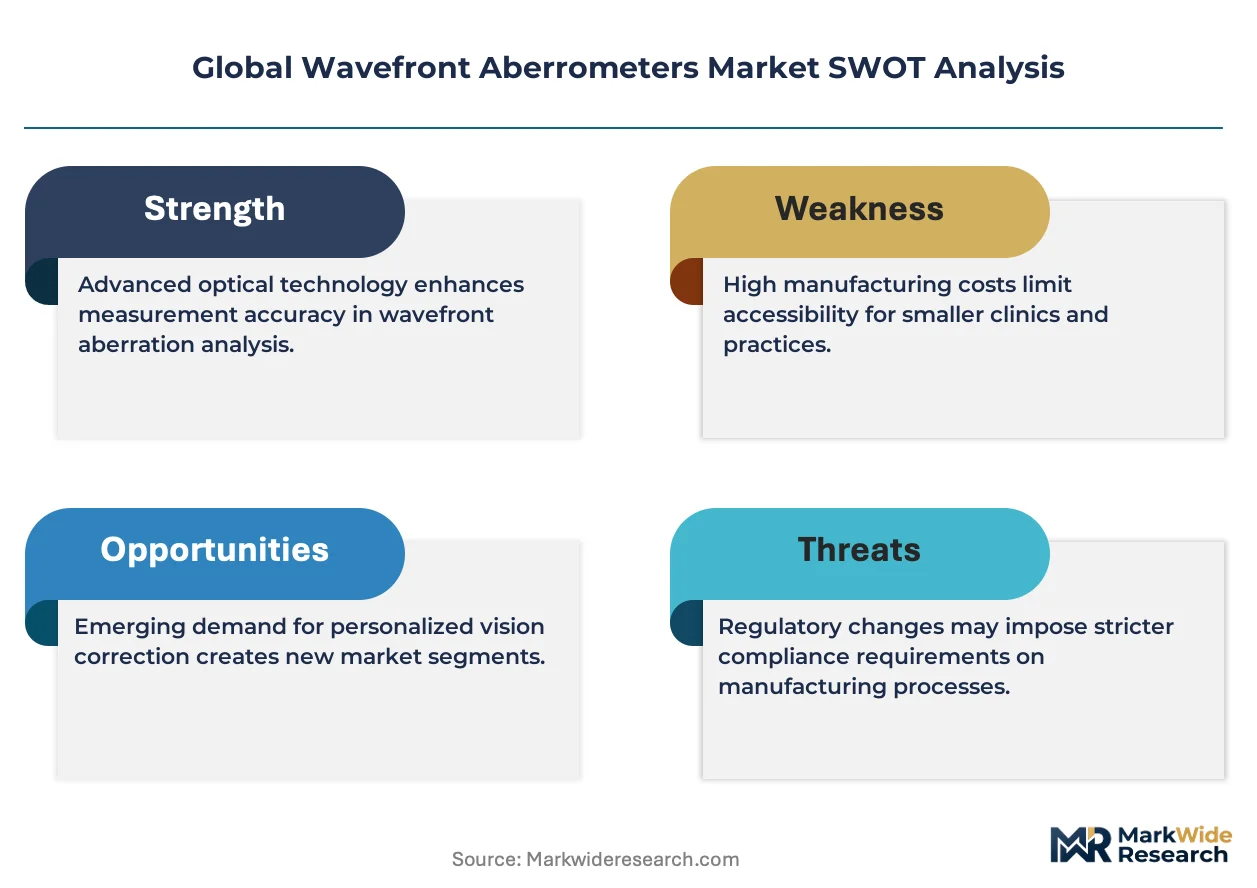
FDA 510(k) clearance requirements for ophthalmic diagnostic devices and the EU MDR's tightened clinical evidence standards for Class IIa medical devices are extending product development timelines and raising barriers for new aberrometer entrants. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards further constrain hardware design choices for manufacturers targeting dual US-European market access. Stakeholders must monitor how adaptive optics research demand migrates from academic centers into commercial diagnostic workflows, as this transition will determine which technology configurations justify premium positioning in the next equipment replacement cycle.
Market Dynamics
Software-defined wavefront analysis modules bundled with annual calibration subscriptions are repositioning how ophthalmic equipment vendors monetize hardware deployments, locking clinicians into recurring revenue ecosystems rather than transactional equipment sales.
Growth Catalysts
- EU MDR tightened clinical evidence standards:Class IIa medical device requirements for aberrometer-integrated surgical suites are extending product development timelines and raising barriers for new entrants, protecting incumbent margin pools.
- Refractive surgery clinic expansion:Germany and Japan are accelerating procurement of wavefront-guided diagnostic platforms as premium vision correction chains consolidate diagnostic capabilities.
- Shack-Hartmann replacement cycles:Mature installed bases across North American and European eye hospitals now drive the majority of commercial revenue as aging systems require hardware refresh.
Market Restraints
- ISO 10993 biocompatibility testing:Electrical safety and biocompatibility validation for dual US-European market access constrains hardware design choices and extends engineering cycles.
- Adaptive optics cost structure:High-resolution retinal imaging configurations remain prohibitively expensive for standard clinical practice, limiting addressable market expansion.
- Supply concentration in precision optics:Shack-Hartmann sensor arrays and deformable mirror components rely on concentrated specialty manufacturing clusters in Germany and Japan.
Strategic Opportunities
- South Korea premium vision correction chains:Underpenetrated demand concentrates in high-volume screening environments seeking compact tabletop diagnostic systems.
- India refractive surgery network expansion:Emerging middle-class access to LASIK and SMILE procedures is creating new diagnostic equipment procurement cycles.
- Adaptive optics research-to-clinic migration:Academic center deployments of high-resolution retinal imaging are creating pathways for commercial diagnostic workflow integration.
Industry Challenges
- FDA 510(k) clearance pathway complexity:Ophthalmic diagnostic device premarket validation requirements demand extensive clinical evidence packages that compress development timelines.
- Wavefront-to-treatment algorithm integration:Proprietary treatment planning software creates clinician switching costs that complicate competitive positioning for hardware-only vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wavefront Aberrometers Market |
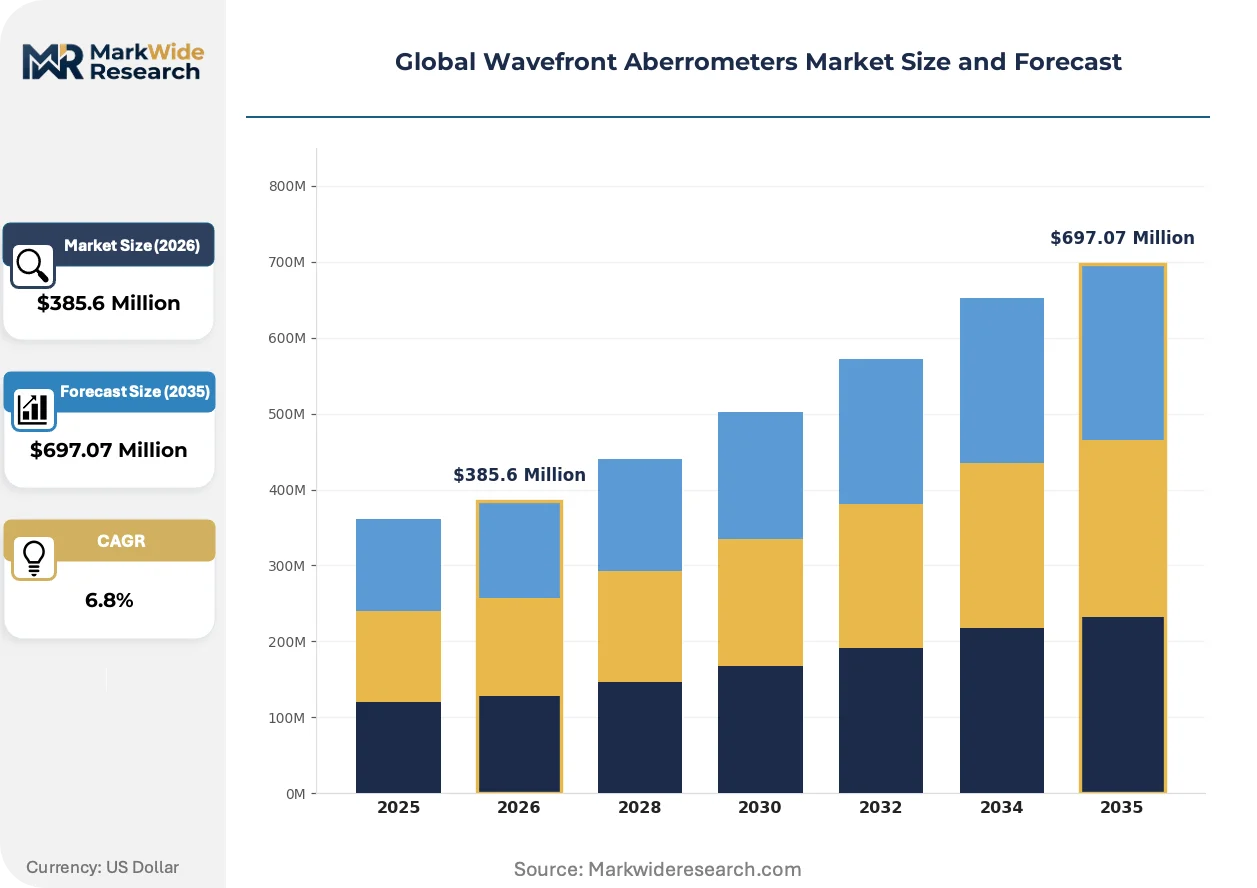
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shack-Hartmann, Tscherning, Curvature, Pyramid Technology: Optical Coherence Tomography, Laser Ray Tracing, Hartmann-Shack Sensing, Adaptive Optics Application: Preoperative Assessment, Custom Laser Surgery, Contact Lens Fitting, Corneal Diagnostics End User: Ophthalmic Clinics, Research Institutes, Diagnostic Centers, Vision Care Centers |
| Companies Covered | Alcon Vision LLC, Carl Zeiss Meditec AG, Johnson & Johnson Vision, Nidek Co. Ltd., Essilor Instruments, Topcon Corporation, Luneau Technology Group, Haag-Streit Group, SCHWIND eye-tech-solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wavefront Aberrometers Market Shifts & Advancements
Three intersecting forces are reshaping wavefront aberrometer commercialization: adaptive optics hardware migration from research to clinical settings, regulatory frameworks tightening premarket validation requirements, and procurement models shifting toward subscription-based software ecosystems.
Adaptive optics technology is overtaking Shack-Hartmann configurations in next-generation retinal imaging platforms. Research institutes across Japan and Germany are deploying high-resolution diagnostic configurations that extend capabilities beyond standard clinical practice. This hardware transition is compressing the performance gap between academic research tools and commercial preoperative assessment systems.
EU MDR clinical evidence standards are extending product development timelines for Class IIa ophthalmic diagnostic devices. Manufacturers targeting dual US-European market access must now satisfy both FDA 510(k) clearance pathways and tightened European premarket validation requirements. Aberrometer-integrated surgical suites face the steepest compliance burden as regulators demand robust clinical performance data.
Annual calibration subscriptions are displacing transactional hardware sales across refractive laser suite deployments. Ophthalmic equipment vendors now bundle software-defined wavefront analysis modules with recurring service contracts that lock in clinician relationships. This procurement evolution is most visible in South Korea's premium vision correction chains and India's expanding refractive surgery center networks.
Global Wavefront Aberrometers Market Segmentation
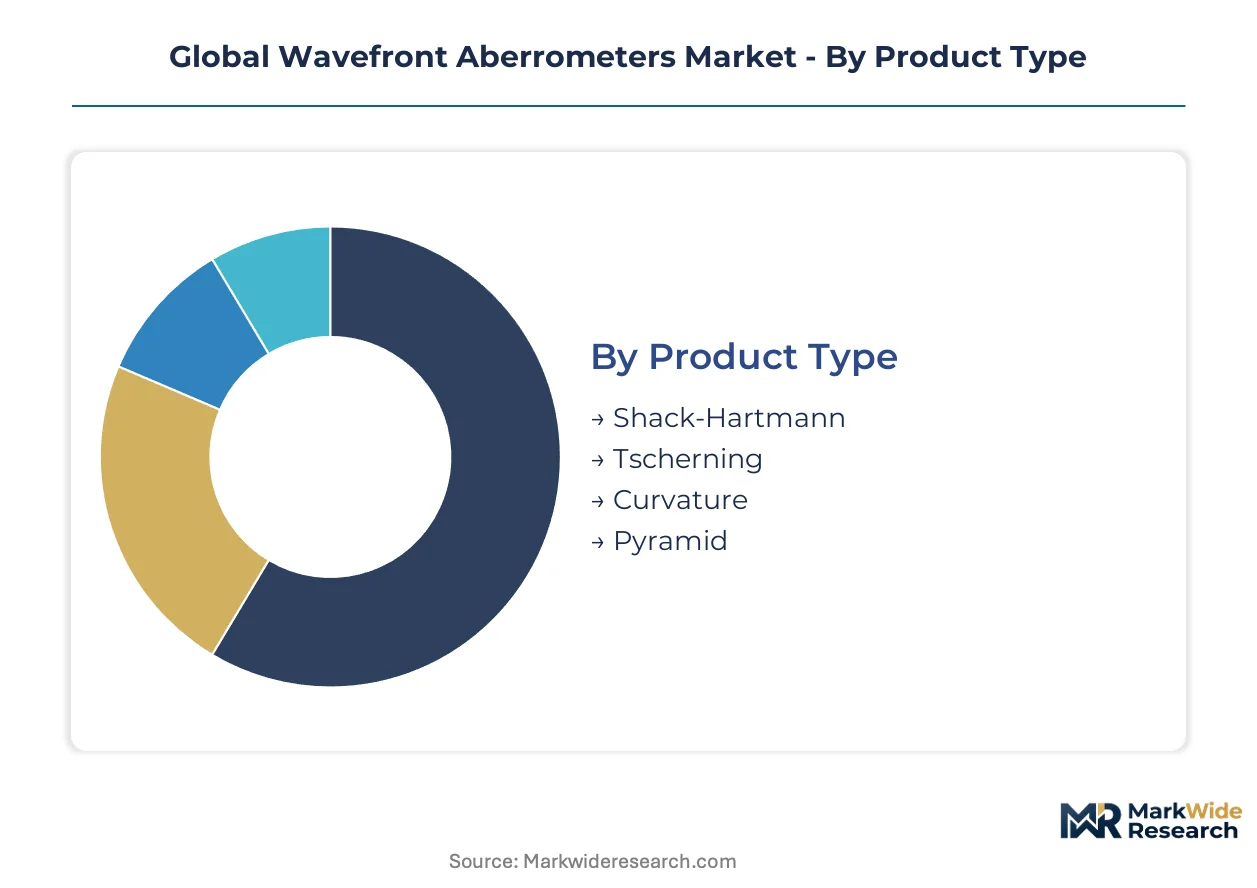
Wavefront aberrometer segmentation reveals how diagnostic hardware integrates across standalone screening stations versus embedded surgical workflows. Understanding these configuration patterns clarifies where procurement budgets concentrate and which technology layers command premium positioning.
Product Type:
Standalone diagnostic stations dominate high-volume screening environments, while embedded configurations lock into excimer laser suites through surgical workflow integration.
- Shack-Hartmann:Shack-Hartmann wavefront sensors deploy lenslet arrays to measure local wavefront tilts across the pupil aperture, resolving aberrations through centroid displacement analysis. Mature installed bases across German and Japanese refractive surgery clinics now drive replacement procurement cycles as aging systems require hardware refresh.
- Tscherning:Tscherning aberrometers use retinal spot pattern analysis to reconstruct wavefront errors from reflected light distribution. Research institutes in South Korea deploy these configurations for high-resolution retinal imaging studies that extend beyond standard clinical protocols.
- Curvature:Curvature-based systems measure corneal shape through Placido disk reflection patterns, offering cost-effective topography integration for Indian vision correction chains expanding screening capacity.
- Pyramid:Pyramid wavefront sensors achieve high dynamic range through quadriwave lateral shearing interferometry, enabling measurement of highly aberrated eyes in specialized diagnostic centers.
Volume placements concentrate in Shack-Hartmann configurations; the faster expansion belongs to pyramid sensors in research-to-clinic migration pathways.
Technology:
Cost tier stratification separates premium adaptive optics research platforms from reimbursement-sustained clinical sensing technologies.
- Optical Coherence Tomography:OCT-integrated wavefront systems combine interferometric depth imaging with aberration measurement, enabling layered corneal and retinal analysis. Diagnostic centers in Germany leverage these configurations for comprehensive preoperative screening bundles that justify elevated procedure pricing.
- Laser Ray Tracing:Laser ray tracing aberrometers project sequential beams through the pupil to map optical path differences directly. Japanese ophthalmic equipment vendors embed these sensors into compact tabletop systems for high-throughput vision care centers.
- Hartmann-Shack Sensing:Hartmann-Shack technology dominates commercial preoperative assessment through proven FDA 510(k) clearance pathways and established reimbursement codes across US refractive surgery networks.
- Adaptive Optics:Adaptive optics systems deploy deformable mirrors and closed-loop wavefront correction to achieve diffraction-limited retinal imaging resolution. Academic medical centers in Japan and Germany represent the primary demand concentration as clinical translation remains cost-prohibitive for standard practice.
Procurement volumes cluster in Hartmann-Shack sensing; adaptive optics claims the steepest expansion trajectory as hardware costs compress toward clinical accessibility thresholds.
Application:
Application segmentation tracks how wavefront data converts into revenue—through surgical procedure fees, custom lens manufacturing, or diagnostic service billing.
- Preoperative Assessment:Preoperative wavefront measurement generates ablation profiles for excimer laser systems, with South Korean premium vision correction chains bundling these diagnostics into all-inclusive procedure packages.
- Custom Laser Surgery:Wavefront-guided LASIK and SMILE procedures command elevated reimbursement where FDA-cleared treatment planning algorithms demonstrate superior visual outcomes over conventional approaches.
- Contact Lens Fitting:Orthokeratology and specialty contact lens designs leverage wavefront data for customized back-surface geometry, particularly in India's expanding myopia management clinics.
- Corneal Diagnostics:Corneal pathology assessment applications concentrate in German university hospitals integrating wavefront tomography with endothelial cell analysis for graft evaluation protocols.
Revenue concentration sits with preoperative assessment; custom laser surgery applications are gaining share fastest as wavefront-guided procedure penetration deepens.
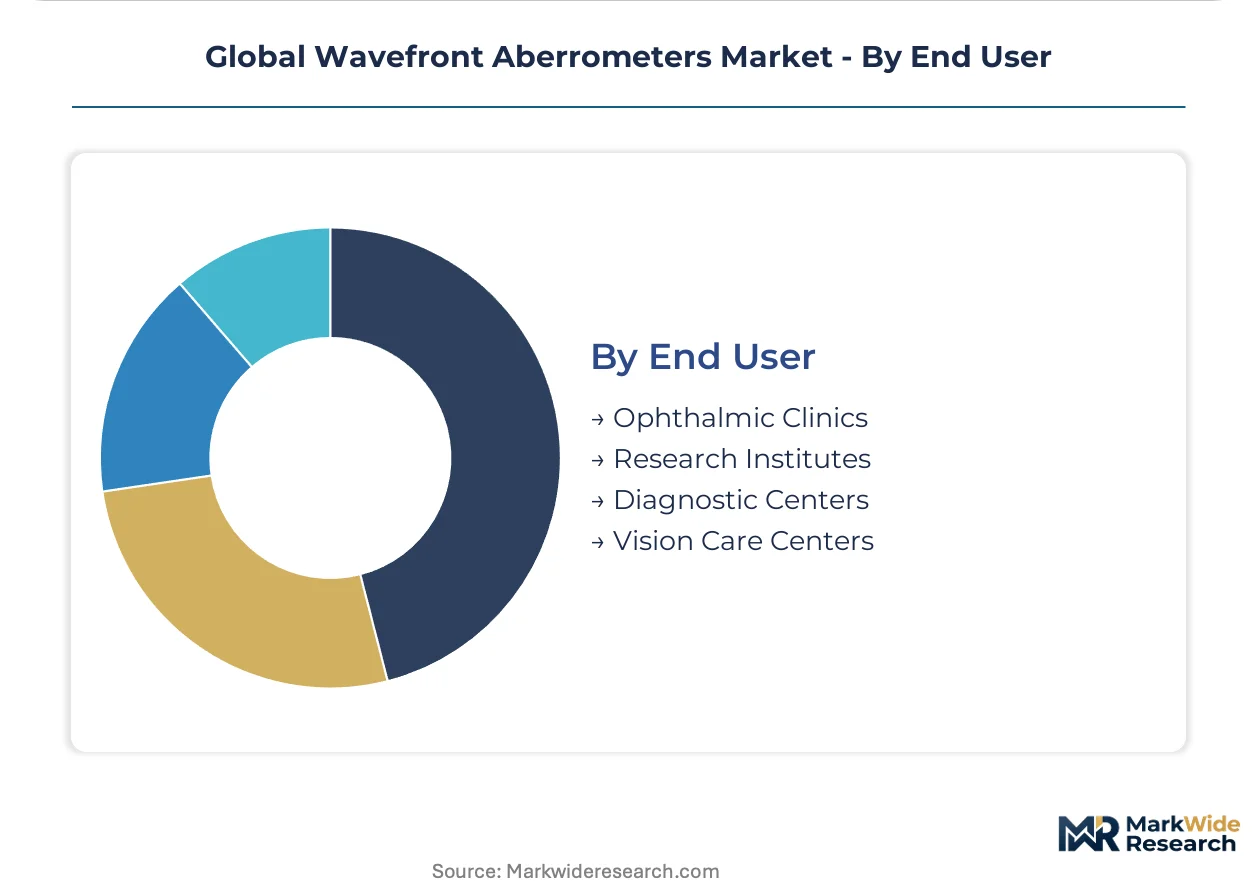
End User:
Customer type segmentation distinguishes capital-intensive hospital procurement from high-volume clinic refresh cycles and research grant-funded acquisitions.
- Ophthalmic Clinics:Private refractive surgery clinics in India and South Korea drive compact tabletop system demand, prioritizing throughput metrics and annual calibration subscription bundles over absolute measurement precision.
- Research Institutes:Academic centers across Japan and Germany deploy adaptive optics configurations for retinal imaging research, with funding cycles tied to national vision science grant programs.
- Diagnostic Centers:Independent diagnostic chains in Germany consolidate preoperative screening services for multiple surgical providers, creating centralized wavefront analysis hubs.
- Vision Care Centers:High-volume vision correction chains standardize on unified hardware platforms to simplify staff training and maintenance logistics across multi-site networks.
Equipment placements concentrate in ophthalmic clinics; research institutes are expanding fastest as adaptive optics hardware migrates toward clinical translation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan concentrate precision optics manufacturing for wavefront sensing components, while the United States and South Korea absorb the majority of clinical system deployments. Consumption patterns diverge between mature replacement markets and emerging expansion corridors.
United States
FDA 510(k) clearance pathways for ophthalmic diagnostic devices sustain Hartmann-Shack sensing procurement across refractive surgery networks. The FDA's tightened premarket validation requirements for Class IIa devices compress development timelines for new entrants. Metropolitan surgical hubs in California and Texas drive replacement cycles for aging Shack-Hartmann installed bases.
Germany
EU MDR clinical evidence standards for aberrometer-integrated surgical suites protect incumbent margin pools through extended compliance timelines. Bavarian precision optics clusters supply Shack-Hartmann sensor arrays and deformable mirror components to global equipment manufacturers. University hospitals in Baden-Württemberg integrate wavefront tomography with endothelial cell analysis for corneal graft evaluation protocols.
Japan
METI-funded vision science grant programs sustain adaptive optics research deployments at academic medical centers in Tokyo and Osaka. PMDA regulatory harmonization with FDA standards accelerates dual-market clearance for domestic equipment vendors. Nagoya-area manufacturers specialize in compact tabletop systems for high-throughput screening environments across Asia-Pacific.
South Korea
MFDS medical device registration requirements for ophthalmic diagnostics align with international standards to facilitate export-oriented production. Seoul Capital Area premium vision correction chains standardize on unified hardware platforms across multi-site networks. Busan-Ulsan diagnostic hubs consolidate preoperative screening services for refractive surgery providers.
India
CDSCO medical device rules for Class B and C ophthalmic equipment establish quality benchmarks for imported diagnostic systems. Maharashtra and Karnataka refractive surgery centers expand procurement of wavefront-guided platforms as middle-class LASIK access deepens. Delhi-NCR vision correction chains prioritize compact tabletop systems with annual calibration subscription bundles.
Global Wavefront Aberrometers Market Competitive Landscape
Top-tier vendors anchor integrated surgical workflow ecosystems, while mid-tier specialists compete on compact hardware configurations for high-volume screening. The vendor base stratifies across three layers: multinational ophthalmic conglomerates with proprietary software stacks, regional equipment fabricators with cost-optimized designs, and precision optics component suppliers. Dominant competitive moves include strategic partnerships between diagnostic hardware and excimer laser manufacturers, plus technology licensing agreements that embed wavefront-to-treatment algorithms into surgical planning software.
Among Germany-based precision optics conglomerates, Carl Zeiss Meditec AG exemplifies the integrated-solution archetype through its surgical workflow software ecosystems. Johnson & Johnson Vision occupies a position within the proprietary-algorithm tier, anchoring competitive stance through treatment planning software that elevates clinician switching costs. Nidek Co. Ltd. represents the compact-specialist archetype, with its Japanese corporate structure signaling concentration in high-volume tabletop configurations for Asia-Pacific eye hospitals.
| Leading Market Players |
|---|
| Alcon Vision LLC |
| Carl Zeiss Meditec AG |
| Johnson & Johnson Vision |
| Nidek Co. Ltd. |
| Essilor Instruments |
| Topcon Corporation |
| Luneau Technology Group |
| Haag-Streit Group |
| SCHWIND eye-tech-solutions |
| Others |
Supply & Pricing Matrix
Captive production of Shack-Hartmann lenslet arrays and deformable mirror components by German and Japanese precision optics clusters anchors both supply security and premium pricing power for integrated surgical suite vendors. This vertical control over wavefront sensing hardware enables tiered service bundling that locks clinic networks into recurring calibration revenue streams rather than transactional equipment sales.
Pricing Analysis
Margin tightening in compact tabletop configurations reflects MFDS registration cost absorption and ISO 10993 biocompatibility validation burdens passed through to Indian and South Korean clinic buyers. Three-tier pricing structure across premium adaptive optics research platforms, standard Hartmann-Shack clinical systems, and economy curvature-based screening devices separates measurement precision grades. Pricing pressure intensifies in high-volume ophthalmic clinic segments as Nidek and domestic Asian fabricators compete on annual subscription bundling. Research institutes demonstrate lowest price sensitivity due to METI and EU grant funding insulation.
Supply Chain Analysis
Direct-to-OEM channels handle precision optics component demand from Carl Zeiss Meditec and Johnson & Johnson Vision surgical suite integrators. Manufacturing concentrates in Bavarian optics clusters, Nagoya-area precision mechanics, and South Korean electro-optics fabrication zones. Shack-Hartmann sensor arrays, deformable mirrors, and closed-loop wavefront correction electronics constitute critical input dependencies. Single-source vulnerability in specialty lenslet array production creates procurement risk for vendors lacking backward integration into German supply bases. Distribution runs through excimer laser manufacturer partnerships and GPO contracts with hospital purchasing committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR compliance costs and FDA 510(k) clinical evidence burdens force capital-constrained regional fabricators toward exit or acquisition.
For Market Incumbents: Deepen proprietary wavefront-to-treatment algorithm development to elevate clinician switching costs against emerging software-defined competitors. Lock in refractive surgery clinic networks through multi-year calibration subscription contracts that embed hardware refresh cycles. Prioritize certification investment for dual FDA-EU MDR clearance to exploit extended compliance timelines burdening new entrants.
For New Entrants and Emerging Players: Compact tabletop system demand from India's expanding refractive surgery networks offers the most penetrable entry vector for cost-optimized hardware configurations. South Korean premium vision correction chains seeking unified multi-site platforms present secondary white-space opportunity. Pursue go-to-market alignment with regional excimer laser distributors lacking captive diagnostic capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier precision optics specialists with captive Shack-Hartmann component production and established PMDA-MFDS regulatory dossiers. Long-term viability favors targets demonstrating clinical translation pathways for adaptive optics research platforms toward reimbursable diagnostic workflows. Monitor adaptive optics hardware cost compression curves as the critical inflection signal for research-to-clinic migration timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence standards protect incumbent margin pools through extended compliance barriers. |
| Hospital System Partnership | German university hospitals integrate wavefront tomography with endothelial analysis for graft protocols. |
| Software Companion Development | Annual calibration subscriptions displace transactional sales across South Korean clinic networks. |
| Reimbursement Strategy | FDA-cleared treatment planning algorithms sustain premium positioning in US refractive surgery networks. |
| Geographic Expansion | Indian refractive surgery center procurement creates equipment refresh demand for compact configurations. |
Research Methodology
FDA 510(k) clearance databases, EU MDR technical documentation filings, and Japanese PMDA medical device registration records formed the secondary backbone for regulatory pathway analysis. Primary interviews with refractive surgery clinic procurement directors, biomedical engineers at German university hospitals, ophthalmic equipment sales executives, and GPO contracts managers validated hardware deployment patterns and pricing model evolution. Bottom-up and top-down triangulation across installed base estimates and procedure volume projections anchored market sizing.
Bottom-up modeling of Shack-Hartmann replacement cycles, adaptive optics research grant funding flows, and subscription revenue conversion rates across the analysis window combined with top-down macroeconomic sensitivity testing. Segmentation dimensions included product type configuration, technology layer, application revenue conversion pathway, and end-user procurement archetype. CAGRs derived from equipment placement velocity curves and service contract renewal rate assumptions calibrated against historical refractive surgery procedure penetration patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to adaptive optics cost compression trajectories and regulatory harmonization shifts between FDA and PMDA standards. Forecasts reflect documented assumptions regarding grant funding continuity for academic center deployments and middle-class LASIK access expansion in emerging markets. Practitioners should monitor deformable mirror manufacturing scale-up indicators and EU MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Hair Mineral Analyzer Market