
 Immunoassay Analyzers Market | 2026-2036
Immunoassay Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoassay Analyzers Market Outlook
China is rewriting competitive dynamics in immunoassay manufacturing as domestic producers scale automated platform output for regional export. Siemens Healthineers AG leverages its installed base of chemiluminescence systems to sustain service revenue across European hospital networks. Abbott anchors its position through vertically integrated reagent-analyzer bundling, while F. Hoffmann-La Roche Ltd differentiates via high-throughput cobas architectures that dominate reference laboratory workflows.
Immunoassay analyzers are automated or semi-automated instruments that detect and quantify target analytes—antigens, antibodies, hormones, or drugs—through antigen-antibody binding reactions, typically achieving sensitivity thresholds in the picogram-per-milliliter range depending on detection chemistry. These systems serve core diagnostic functions in clinical settings, enabling quantitative results for patient management decisions across infectious disease, endocrinology, oncology, and toxicology panels. Automated technology segments command premium placement in high-volume hospital laboratories where throughput requirements exceed several hundred tests per hour, while chemiluminescence detection methods are displacing older ELISA workflows in mid-tier diagnostic centers due to superior precision and reduced manual handling. Manual and semi-automated configurations retain durable positions in research institutes and pharmaceutical companies where assay flexibility and lower capital burden outweigh speed requirements.
FDA premarket notification pathways under 21 CFR Part 866 shape analyzer commercialization timelines for US market entry, while EU IVDR compliance obligations are forcing substantial technical documentation upgrades across existing CE-marked portfolios. China's NMPA has tightened registration requirements for imported in vitro diagnostic instruments, creating localized production incentives that alter supply configurations. Stakeholders must weigh regulatory capital intensity against reagent lock-in economics when evaluating platform commitments across jurisdictions.
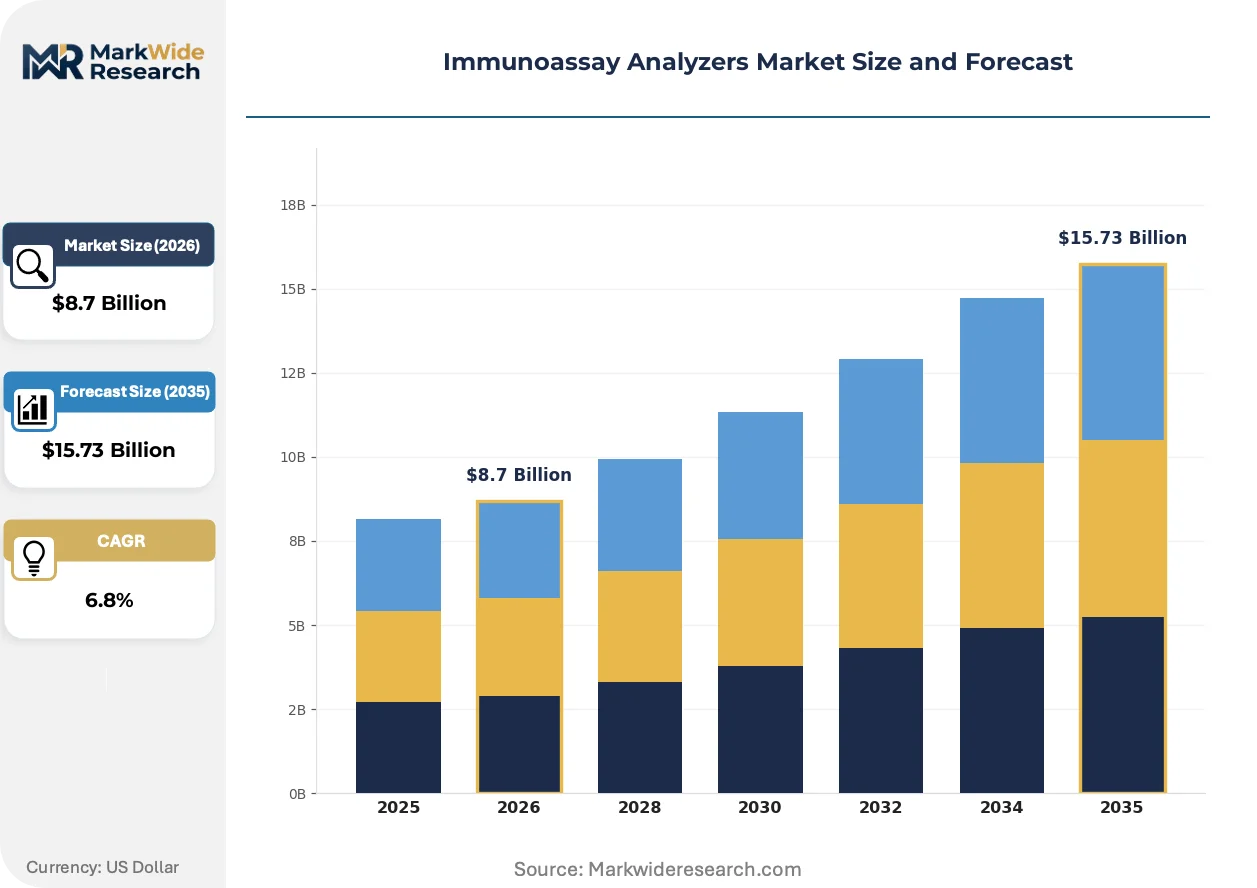
Market Dynamics
Chemiluminescence detection chemistry is compressing legacy ELISA workflows across mid-tier diagnostic centers, while EU IVDR compliance deadlines force accelerated replacement of pre-2022 analyzer installations.
Growth Catalysts
- FDA 510(k) premarket notification:Streamlined clearance pathways under 21 CFR Part 866 accelerate US commercialization timelines for automated platforms.
- Hospital laboratory consolidation:Centralized procurement of high-throughput systems by integrated delivery networks concentrates demand for chemiluminescence architectures.
- Point-of-care infectious disease panels:Emergency department triage protocols for sepsis and respiratory pathogens pull compact immunoassay units into decentralized settings.
Market Restraints
- Reagent lock-in economics:Closed-system consumable contracts create switching costs that entrench incumbent vendors and depress price competition.
- EU IVDR technical documentation:Substantial upgrades to existing CE-marked portfolios strain mid-tier manufacturer compliance budgets.
- Monoclonal antibody supply concentration:Dependence on Chinese biologics manufacturers exposes reagent production to geopolitical friction.
Strategic Opportunities
- Veterinary diagnostics expansion:Companion animal oncology and endocrinology testing opens greenfield demand for species-specific assay menus.
- Digital pathology convergence:Integration of immunoassay quantification with whole-slide imaging creates workflow synergies in academic medical centers.
- India's PLI scheme for medical devices:Domestic production incentives attract component assembly operations serving South Asian export markets.
Industry Challenges
- Multiplex assay development expertise:Scarcity of bioengineers capable of optimizing antibody-fluorophore pairings for simultaneous analyte detection.
- Legacy LIS integration complexity:HL7 FHIR interoperability gaps between new analyzers and entrenched hospital information systems delay deployment.
- ISO 15189 accreditation timelines:Extended audit cycles for clinical laboratory quality management compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoassay Analyzers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Chemiluminescence, Radioimmunoassay, Fluorescent End User: Hospital Laboratories, Diagnostic Centers, Research Institutes, Pharmaceutical Companies Technology: Manual, Automated, Semi-Automated, Microplate Application: Infectious Diseases, Hormone Testing, Drug Testing, Cancer Detection |
| Companies Covered | Siemens Healthineers AG, Abbott, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Danaher, bioMérieux, Beckman Coulter, Inc., QuidelOrtho Corporation, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoassay Analyzers Market Strategic Shifts
Detection chemistry architectures are fragmenting into application-optimized configurations, while regulatory documentation requirements reshape vendor competitive positioning across jurisdictions.
Multiplexed bead-based immunoassay platforms are hybridizing flow cytometry detection with traditional ELISA workflows. Reference laboratories in Germany and the United States are adopting these systems for cytokine profiling and autoantibody panels. The technology is hybridizing previously separate instrument categories, compressing capital equipment footprints while expanding test menus per square meter of bench space.
EU IVDR Article 10 technical documentation obligations are forcing substantial quality management system upgrades across legacy CE-marked portfolios. Manufacturers must now submit clinical performance data for Class C and D in vitro diagnostic devices that previously relied on self-certification. High-throughput analyzer vendors serving European hospital networks are responding by consolidating notified body relationships and pre-emptively retiring marginal product lines.
Centralized procurement consortia are consolidating analyzer purchasing decisions at integrated delivery network headquarters rather than individual hospital laboratories. Device vendors face compressed sales cycles and standardized specification requirements that favor multi-year reagent supply agreements over capital-only transactions. This pattern is most visible in United States health systems exceeding ten hospital campuses, where procurement committees now mandate interoperability with enterprise laboratory information systems as a threshold qualification.
Immunoassay Analyzers Market Segmentation
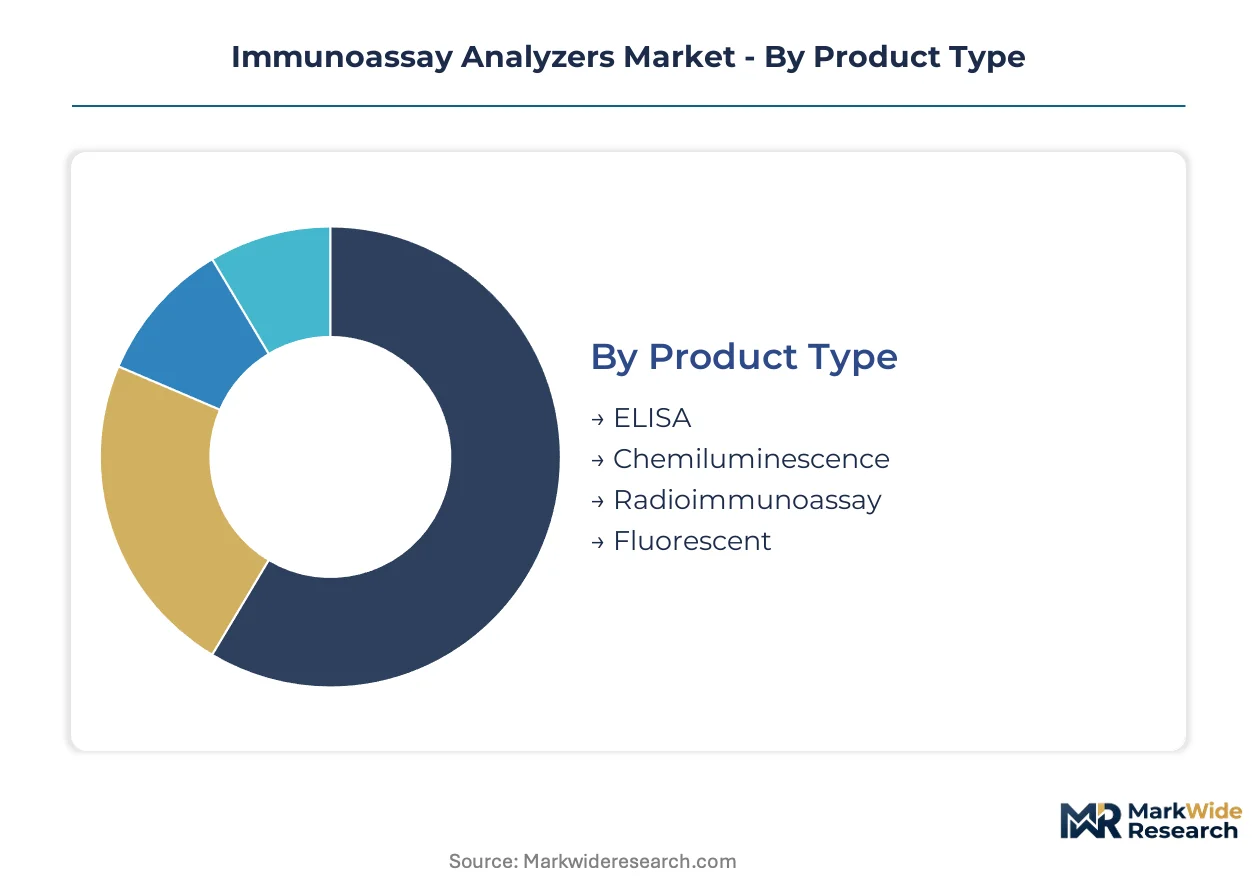
Segmentation in immunoassay analyzers reveals how detection chemistry, automation level, and clinical setting interact to determine procurement decisions. Hospital laboratories prioritize throughput and reagent bundling, while research settings trade speed for assay flexibility.
Product Type:
Cost tier differentiation across detection chemistries separates premium chemiluminescence platforms from legacy ELISA infrastructure and specialized radioactive or fluorescent methods.
- Chemiluminescence:Enzyme-triggered light emission detection achieves picogram-per-milliliter sensitivity thresholds with minimal background interference. United States hospital networks are consolidating procurement around these architectures as integrated delivery networks negotiate multi-year reagent supply agreements.
- ELISA:Colorimetric enzyme-linked detection remains entrenched in resource-constrained settings and research protocols requiring open-system flexibility. Diagnostic centers in Germany retain substantial installed bases despite gradual displacement by chemiluminescence workflows.
- Radioimmunoassay:Isotope-labeled antibody detection persists in endocrinology reference laboratories requiring absolute quantification of low-abundance hormones.
- Fluorescent:Fluorophore-conjugated detection supports multiplexed bead-based platforms for cytokine profiling in academic medical centers.
Chemiluminescence holds installed capacity. Fluorescent is rotating up the share rankings.
End User:
Customer type determines automation requirements, with throughput demands and capital budgets diverging sharply across hospital consolidation, decentralized diagnostics, and exploratory research.
- Hospital Laboratories:High-volume centralized facilities processing several hundred tests per hour demand fully automated chemiluminescence platforms with random-access capabilities. China's tertiary hospital expansion is accelerating replacement of legacy manual systems in provincial capitals.
- Diagnostic Centers:Mid-tier independent laboratories balance test menu breadth against capital constraints, favoring semi-automated configurations with expandable throughput. These facilities in the United States face compressed margins from reimbursement pressure.
- Research Institutes:Academic and government laboratories prioritize assay customization over speed, sustaining demand for open-architecture manual and microplate systems.
- Pharmaceutical Companies:Drug development pipelines require validated biomarker quantification for clinical trial endpoints, driving procurement of FDA 510(k)-cleared platforms with documented precision.
Hospital laboratories hold installed capacity. Diagnostic centers are rotating up the share rankings.
Technology:
Automation maturity creates a spectrum from labor-intensive manual processing to lights-out laboratory robotics, with capital intensity and labor substitution as core trade-offs.
- Automated:Robotic sample handling, reagent dispensing, and result reporting minimize technician intervention for high-throughput operations. Germany's reference laboratory networks have nearly completed migration to these architectures ahead of EU IVDR compliance deadlines.
- Semi-Automated:Partial mechanization of washing and detection steps reduces hands-on time while preserving protocol flexibility for lower-volume settings. Diagnostic centers in China's tier-2 cities are adopting these systems as stepping stones to full automation.
- Manual:Technician-performed pipetting and incubation retains relevance where assay customization outweighs throughput requirements.
- Microplate:96-well and 384-well format readers serve high-density screening applications in pharmaceutical discovery and research protocols.
Automated systems hold installed capacity. Semi-automated configurations are rotating up the share rankings.
Application:
Clinical indication drives test menu design, with infectious disease panels commanding the highest volume and oncology biomarkers attracting premium pricing.
- Infectious Diseases:Pathogen antigen and antibody detection dominates routine diagnostic volume, with respiratory and sepsis panels pulling compact analyzers into emergency department settings. United States health systems are standardizing these protocols across integrated delivery networks.
- Cancer Detection:Tumor marker quantification for prostate-specific antigen, CA-125, and AFP supports screening and monitoring workflows with higher reimbursement per test. China's expanding oncology infrastructure is accelerating adoption in provincial cancer centers.
- Hormone Testing:Endocrinology panels for thyroid function, fertility, and cortisol assessment sustain steady demand in hospital outpatient settings.
- Drug Testing:Therapeutic drug monitoring and toxicology screening serve specialized reference laboratories and forensic applications with regulated chain-of-custody requirements.
Infectious diseases holds installed capacity. Cancer detection is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific diagnostic equipment throughput, handling containerized analyzer components for regional assembly networks. European distribution relies on Rotterdam's multimodal connectivity to synchronize just-in-time reagent supply chains. These infrastructure nodes determine competitive access patterns across major procurement markets.
United States
Integrated delivery networks in Texas and Florida are consolidating laboratory procurement under centralized capital committees. FDA 510(k) premarket notification pathways under 21 CFR Part 866 streamline clearance timelines for automated platforms. Boston's medical technology cluster houses reference laboratories migrating to chemiluminescence architectures ahead of reimbursement shifts.
Germany
Reference laboratory networks in Bavaria and North Rhine-Westphalia have nearly completed migration to fully automated systems. EU IVDR Article 10 technical documentation obligations are forcing quality management upgrades across legacy CE-marked portfolios. The Rhine-Main metropolitan region concentrates notified body relationships and regulatory consulting capacity for compliance transitions.
China
NMPA registration requirements for imported in vitro diagnostic instruments have tightened, creating localized production incentives. Tertiary hospital expansion in provincial capitals accelerates replacement of legacy manual systems. The Yangtze River Delta manufacturing corridor scales automated platform output for regional export markets.
Japan
PMDA regulatory pathways maintain rigorous clinical performance documentation standards for analyzer commercialization. METI industrial policy supports domestic production of high-precision optical detection components. The Kansai region around Osaka retains concentration of reagent manufacturing and precision engineering suppliers.
India
Domestic production incentives under the PLI scheme for medical devices attract component assembly operations. Diagnostic centers in Maharashtra and Karnataka balance capital constraints against expanding test menu requirements. The Delhi-NCR corridor concentrates import distribution channels for refurbished analyzer platforms.
Immunoassay Analyzers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying optical detection modules and precision fluidics. The vendor base stratifies across three tiers: multinational conglomerates with vertically integrated reagent-analyzer bundling, mid-scale regional manufacturers with localized regulatory approvals, and niche component suppliers focused on specific detection chemistries. Strategic archetypes include throughput-maximizing hospital network suppliers, flexibility-oriented research platform vendors, and cost-optimized emerging market entrants. Dominant competitive moves involve multi-year reagent supply agreements that create switching costs, and preemptive product line retirements to streamline compliance documentation.
Among diversified health technology conglomerates, Siemens Healthineers AG and Abbott exemplify platform integrators with extensive installed base leverage. Danaher occupies a position representing precision instrumentation scale. F. Hoffmann-La Roche Ltd anchors the high-throughput reference laboratory tier. These entities represent archetypal competitive positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Danaher |
| bioMérieux |
| Beckman Coulter, Inc. |
| QuidelOrtho Corporation |
| BD |
| Others |
Value Chain & Pricing Dynamics
Monoclonal antibody supply concentration in Chinese biologics manufacturers determines both the spread between premium chemiluminescence systems and economy-tier ELISA platforms and the geographic configuration of reagent sourcing networks. NMPA registration barriers for imported instruments compress margins on foreign-made analyzers while amplifying localization incentives that reshape tier boundaries.
Pricing Analysis
Volume-discount tiering structures separate multi-year reagent bundling contracts for integrated delivery networks from capital-only transactions for independent diagnostic centers. Pricing stratifies across premium, standard, and economy tiers based on throughput certification and after-sales service attachment. Cost compression in mid-tier configurations is intensifying because hospital procurement committees now mandate enterprise LIS interoperability as a threshold qualification. Research institutes exhibit the highest price sensitivity due to discretionary capital budgets, while reference laboratories in Germany and the United States show the lowest sensitivity given reimbursement stability.
Supply Chain Analysis
Export-control regimes restricting precision optical detection components limit flows from Japanese and German suppliers to Chinese assembly operations. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta scaling automated platform output and Bavaria retaining precision fluidics engineering. Supply chains draw from monoclonal antibody bioreactors, photomultiplier tubes, and precision syringe pumps. Single-source vulnerability in Chinese biologics manufacturing exposes reagent production to geopolitical friction. Distribution runs through Rotterdam's multimodal hub for European just-in-time reagent synchronization and Shanghai's containerized component throughput for Asia-Pacific assembly networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics dominate hardware margins as multi-year reagent supply agreements expand faster than analyzer unit placements, with consumable lock-in generating recurring revenue streams that subsidize capital equipment pricing.
For Market Incumbents: Entrench installed base leverage through preemptive EU IVDR compliance upgrades that strain mid-tier competitor documentation budgets. Consolidate notified body relationships to accelerate Class C and D device recertification timelines. Deepen backward integration into precision optical detection module production to reduce Japanese component dependency exposure. Prioritize capacity addition in China's Yangtze River Delta manufacturing corridor to satisfy NMPA localization requirements for regional hospital procurement. For New Entrants and Emerging Players: Build out species-specific assay menus for veterinary oncology and endocrinology testing where incumbent reagent libraries remain underdeveloped. Target India's diagnostic center expansion under PLI scheme production incentives as the most penetrable geography for cost-optimized semi-automated configurations. Pursue GPO contract penetration through software companion development that addresses HL7 FHIR interoperability gaps in legacy hospital information systems. For Investors and Strategic Acquirers: The market sits at a compliance-transition phase that favors vertically integrated reagent-analyzer bundlers with notified body relationship density. Long-term viability hinges on reagent lock-in economics rather than hardware innovation cycles, positioning consumable-dependent business models favorably across the five-to-ten year window. Acquisition target archetypes include mid-scale regional manufacturers with localized NMPA approvals and niche multiplex assay development capabilities. The signal to watch is EU IVDR technical documentation submission backlogs at marginal product lines, which would indicate accelerated consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Bundling Contracts | Multi-year consumable agreements with integrated delivery networks in Texas and Florida lock in switching costs. |
| EU IVDR Compliance Pathway | Article 10 technical documentation upgrades for Class C and D devices force quality management system consolidation. |
| Hospital System Partnership | Enterprise LIS interoperability mandates from procurement committees exceeding ten campuses standardize analyzer specifications. |
| Software Companion Development | HL7 FHIR middleware integration addresses legacy system compatibility barriers delaying deployment in academic medical centers. |
| CE Marking Pathway | Notified body relationship consolidation streamlines legacy portfolio recertification ahead of compliance deadlines. |
Study Parameters
Initial hypotheses were tested against primary input from hospital laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at IVD manufacturers and refined through secondary validation against FDA 510(k) premarket notification filings, EU IVDR technical documentation databases, NMPA registration records, and hospital procurement contract disclosures. Bottom-up analyzer shipment data triangulated with top-down reagent consumption estimates across the projection horizon.
Demand-supply-balance framing anchored the analytical framework across detection chemistry, automation level, and end-user segmentation dimensions with regional regulatory cluster overlays. CAGRs were derived from installed base replacement cycles, compliance-driven upgrade timelines, and reagent attach rate assumptions. Forecast inputs incorporated EU IVDR Article 10 transition deadlines, NMPA import registration tightening trajectories, and integrated delivery network consolidation patterns in United States health systems.
Practitioners should monitor monoclonal antibody supply chain disruptions, EU IVDR notified body capacity constraints, and NMPA localization enforcement intensity for early signals of forecast deviation. Forecasts reflect assumptions regarding compliance timeline adherence and reimbursement stability in core markets. Material shifts in Chinese biologics export restrictions or EU IVDR audit backlog accumulation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Global Radioimmunoassay Market